
 Global Electronic Materials Market | 2026-2036
Global Electronic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Materials Market Analysis
Market Overview
East Asian substrate capacity expansion is fragmenting traditional supply relationships as new fabrication lines in Taiwan and South Korea compete for limited precursor chemicals. Shin-Etsu Chemical Co., Ltd. leverages its polysilicon monopoly to sustain pricing power across wafer markets. Applied Materials, Inc. anchors equipment-materials bundling strategies that extend its influence into process chemistry selection. JSR Corporation specializes in photoresist formulations that occupy critical positions at sub-7nm nodes where alternatives remain scarce.
Technical Scope and Segment Dynamics
Electronic materials encompass chemically engineered substances—silicon wafers, photoresists, CMP slurries, and dielectric films—processed to exacting purity specifications measured in parts per billion, enabling the fabrication of integrated circuits and printed circuit assemblies. These materials determine transistor density, signal integrity, and thermal performance in devices ranging from smartphones to satellite systems. Semiconductor-grade silicon and advanced photoresists lead product type revenue pools, while printed electronics technology commands the fastest expansion as flexible hybrid electronics displace conventional rigid substrates in automotive and medical applications. Power electronics applications within the application dimension concentrate margin capture, driven by silicon carbide and gallium nitride substrate demand from electric vehicle inverters.
Regulatory Environment and Strategic Outlook
REACH in Europe restricts perfluorinated compound use in etching chemistries, forcing reformulation investments that reshape competitive cost structures. The EPA in the United States enforces emissions controls on semiconductor fabrication facilities that elevate abatement capital requirements. China's GB standards and dual carbon goals impose energy intensity ceilings on polysilicon purification operations. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which material classes face accelerated substitution mandates versus grandfathered compliance windows.
Market Dynamics
Substrate capacity expansion in Taiwan and South Korea is fragmenting traditional supply relationships as new fabrication lines compete for limited precursor chemicals, forcing buyers to requalify alternative sourcing channels.
Growth Catalysts
- AI Chip Demand Surge:Hyperscale data centers in the United States and China are consuming advanced packaging substrates at volumes that justify dedicated chemical supply lines.
- REACH Reformulation Mandates:The European Chemicals Agency is accelerating perfluorinated compound phase-outs, creating first-mover advantages for suppliers with compliant etching chemistries.
- Silicon Carbide Substrate Scaling:Electric vehicle inverter manufacturers are qualifying 200mm SiC wafers, pulling demand for high-purity polysilicon precursors.
Market Restraints
- Polysilicon Supply Concentration:Five producers control over 80% of semiconductor-grade polysilicon purification, with Chinese energy intensity ceilings constraining expansion timelines.
- Photoresist Technical Limitations:EUV resists below 3nm node requirements exhibit stochastic defect rates that yield management systems cannot yet compensate.
- Abatement Capital Burden:EPA emissions controls on perfluorinated gas destruction require $50-100 million per fabrication facility for thermal scrubber installations.
Strategic Opportunities
- India Packaging Hub Emergence:The country's PLI scheme for semiconductor assembly is attracting substrate manufacturers seeking alternative sourcing to East Asian concentration.
- Flexible Hybrid Electronics Convergence:Printed electronics technology is penetrating automotive interior sensing and medical wearable applications previously served by rigid PCBs.
- Japan METI Critical Materials Security:Subsidies for domestic photoresist and CMP slurry production are opening captive supply arrangements for non-Japanese device makers.
Industry Challenges
- Process Engineer Scarcity:Sub-7nm node qualification requires expertise in stochastic modeling and contamination control that existing training pipelines cannot supply at scale.
- Dual-Use Export Control Compliance:US Bureau of Industry and Security licensing timelines for advanced deposition equipment extend 12-18 months, freezing capacity planning.
- Legacy 200mm Equipment Obsolescence:Power semiconductor foundries face 40-week lead times for refurbished ion implanters as original manufacturers discontinue support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Materials Market |
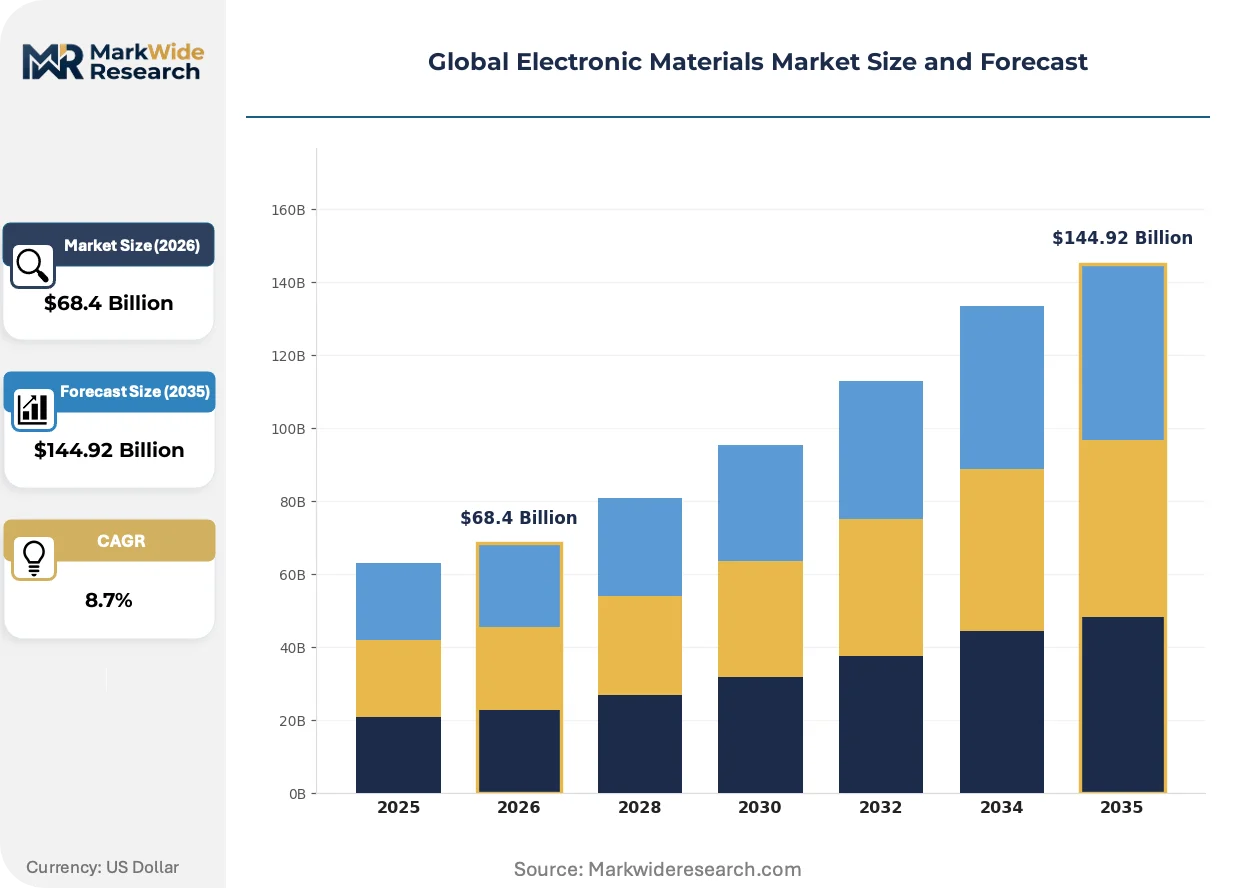
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductors, Insulators, Dielectrics, Semiconductors Technology: Printed Electronics, MEMS, Nanotechnology, Photovoltaics End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Application: Power Electronics, Optoelectronics, Sensing Devices, Circuit Boards |
| Companies Covered | Applied Materials, Inc., Kyocera Corporation, Shin-Etsu Chemical Co., Ltd., JSR Corporation, Tokyo Electron Limited, Sumco Corporation, Dow Inc., DuPont de Nemours, Inc., Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Materials Market Emerging Trajectories
Computational lithography and materials informatics are compressing development cycles for next-node chemistries, while regulatory divergence between jurisdictions forces parallel qualification tracks.
Digital twin platforms for chemical vapor deposition processes are virtualizing equipment optimization, allowing TSMC and Samsung Foundry to reduce chamber matching time by 60% without physical wafer consumption. This virtualization compresses the barrier to entry for new material suppliers who can demonstrate process equivalence through simulation rather than full fab trials.
The European F-Gas Regulation is banning hydrofluorocarbon etching gases with global warming potentials above 150, compelling Lam Research and Tokyo Electron to qualify fluorine-free alternatives by 2027. Dry etching chemistries using NF3 alternatives face 30% throughput penalties that memory manufacturers in South Korea are absorbing through extended chamber residence times.
Consolidated procurement consortia among Apple, NVIDIA, and AMD are displacing individual foundry chemical purchasing, leveraging combined volume to secure priority allocation during supply shortages. This buyer concentration is most visible in Arizona and Texas, where TSMC and Samsung greenfield sites negotiate precursor supply before construction completion.
Global Electronic Materials Market Segmentation
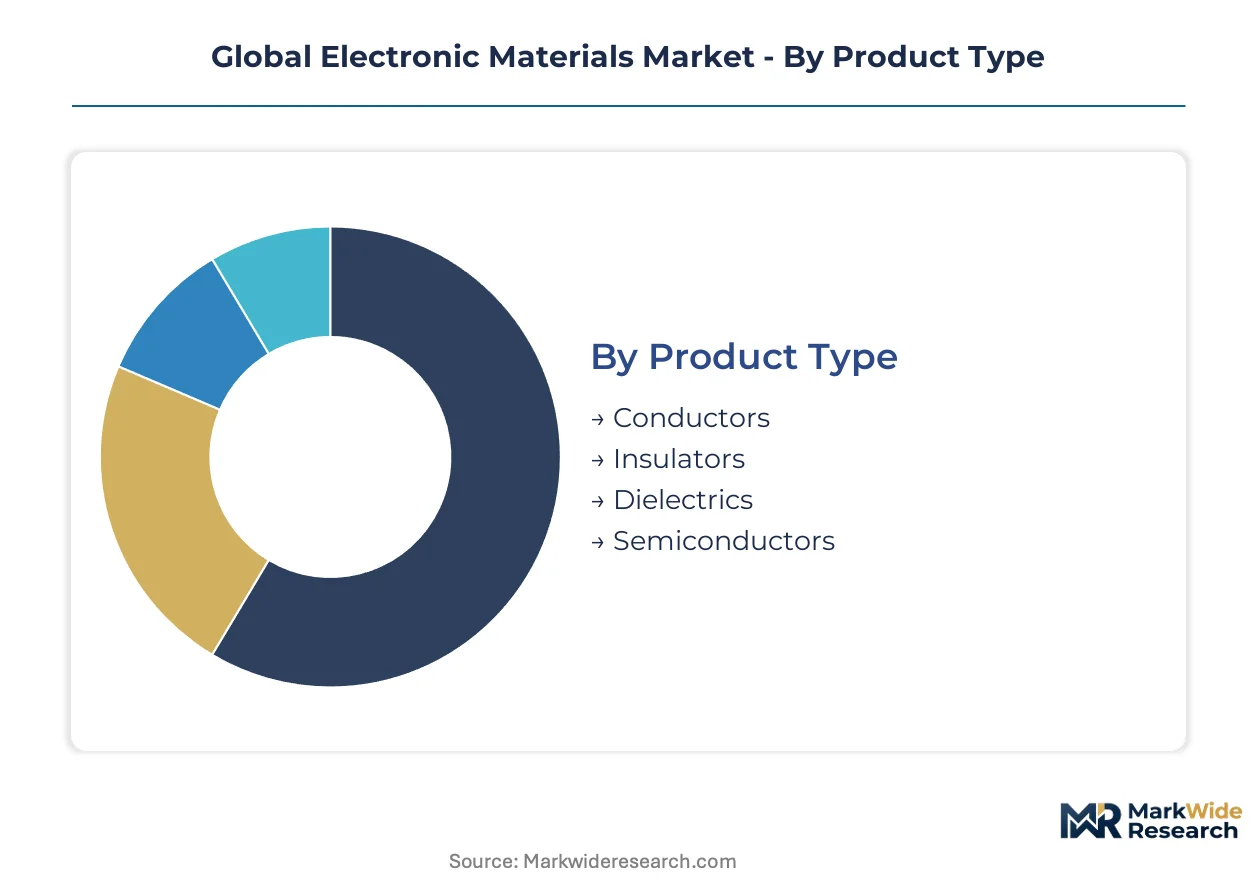
Electronic materials segment along four intersecting dimensions that determine qualification cycles, pricing power, and supplier switching costs. Foundry procurement teams weight product purity specifications against technology roadmaps when allocating long-term supply agreements.
Product Type:
Cycle times vary dramatically across material classes, with polysilicon purification requiring 18-24 month capacity ramps while specialty dielectrics requalify in 6-9 months.
- Semiconductors:Silicon wafers and compound semiconductor substrates processed to 11N purity standards form the physical foundation of transistor fabrication. Taiwan Semiconductor Manufacturing Company and Samsung Foundry in South Korea consume the majority of 300mm prime-grade silicon, with AI accelerator chip demand stretching ingot supply timelines. Polysilicon supply concentration in China and Germany constrains rapid expansion.
- Conductors:Copper interconnects, aluminum metallization, and emerging cobalt liners enable signal routing at sub-7nm nodes. Copper damascene processes dominate logic device fabrication in Taiwan and South Korea, though cobalt liner adoption for gap fill at 3nm nodes is accelerating chemical vapor deposition equipment demand.
- Dielectrics:Low-k and ultra-low-k films reduce capacitive coupling between metal lines in advanced interconnect stacks. Air-gap dielectrics and porous organosilicate glasses face integration challenges at leading-edge nodes.
- Insulators:Silicon dioxide, silicon nitride, and high-k gate dielectrics provide electrical isolation and gate capacitance control. Thermal oxide growth remains cost-effective for mature node production in Chinese fabs.
Semiconductors anchors the volume base while dielectrics gains share at the steepest rate.
Technology:
Capital intensity separates these platforms, with photovoltaics requiring gigascale manufacturing investments while printed electronics deploys at pilot-line scale.
- Printed Electronics:Conductive inks, dielectric pastes, and semiconductor formulations deposited through inkjet, screen, and gravure processes onto flexible substrates. Automotive interior sensing modules in Germany and medical wearable electrodes in the United States are displacing rigid PCB alternatives. Silver nanoparticle ink costs remain the primary adoption barrier.
- MEMS:Microelectromechanical systems combining mechanical structures with integrated circuit processing for sensors and actuators. Bosch in Germany and STMicroelectronics in France dominate automotive pressure and inertial sensor supply.
- Nanotechnology:Carbon nanotubes, graphene, and quantum dots enabling novel electronic properties. Thermal interface materials incorporating carbon nanotubes are penetrating data center cooling applications.
- Photovoltaics:Silicon-based and thin-film solar cell materials including polysilicon feedstock, silver pastes, and ethylene vinyl acetate encapsulants. PERC cell architecture transitions in China are pulling demand for high-purity polysilicon.
Photovoltaics commands the largest installed capacity while printed electronics climbs fastest.
End User:
Margin structures diverge sharply across these demand pools, with aerospace qualification cycles spanning 5-7 years against 18-24 months for consumer devices.
- Automotive:Power electronics materials for electric vehicle inverters, battery management systems, and autonomous driving sensors. Silicon carbide substrate demand from Tesla in the United States and BYD in China is straining 150mm and 200mm wafer supply. Functional safety standards under ISO 26262 extend material qualification timelines.
- Consumer Electronics:Smartphone, tablet, and wearable device components requiring miniaturization and thermal management. Apple and Samsung Electronics drive specifications for advanced packaging substrates.
- Telecommunications:5G base station amplifiers, optical transceivers, and network infrastructure semiconductors. Gallium nitride-on-silicon RF devices are displacing LDMOS in macro base stations.
- Aerospace:Radiation-hardened components, high-reliability interconnects, and thermal protection materials for satellites and avionics. European Space Agency qualification requirements limit qualified supplier pools.
Automotive anchors the volume base while aerospace gains share at the steepest rate.
Application:
Process complexity and material purity requirements scale with device performance demands, separating commodity circuit board laminates from specialized power semiconductor substrates.
- Power Electronics:Wide bandgap semiconductors, thermal interface materials, and packaging substrates for energy conversion. Wolfspeed in the United States and Infineon in Germany are qualifying 200mm silicon carbide wafers for next-generation electric vehicle inverters. Epoxy mold compounds with enhanced thermal conductivity face supply constraints.
- Optoelectronics:Light-emitting diodes, laser diodes, photodetectors, and optical modulators. Gallium arsenide and indium phosphide substrates for datacenter optical interconnects are concentrating demand in Taiwan and the United States.
- Sensing Devices:Image sensors, environmental sensors, and biometric detection components. Sony in Japan dominates CMOS image sensor supply for smartphone cameras.
- Circuit Boards:Printed circuit board laminates, prepregs, and conductive finishes for electronic system interconnection. High-frequency low-loss laminates for 5G infrastructure are substituting traditional FR-4 in China and the United States.
Circuit boards anchors the volume base while power electronics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions controls and Bureau of Industry and Security licensing timelines in the United States are reshaping where fabrication capacity materializes. Taiwan Semiconductor Manufacturing Company and Samsung Foundry expansion plans in Arizona and Texas are forcing precursor chemical suppliers to requalify domestic sourcing channels against established East Asian supply lines.
United States
Hyperscale data center construction in Virginia and Oregon is pulling advanced packaging substrate demand. The CHIPS and Science Act is directing subsidy flows toward domestic polysilicon purification and photoresist formulation capabilities. Phoenix and Austin fabrication clusters are negotiating chemical supply agreements before facility completion, compressing traditional procurement timelines.
Taiwan
TSMC's 3nm and 2nm node ramps are consuming EUV photoresist volumes that strain JSR Corporation and Tokyo Electron supply allocations. The island's environmental regulator enforces perfluorinated compound emissions ceilings that elevate abatement capital requirements. Hsinchu Science Park concentration is forcing specialty gas suppliers to co-locate purification facilities within industrial park boundaries.
South Korea
Samsung Foundry and SK Hynix memory expansion is absorbing CMP slurry and specialty dielectric volumes at rates that outstrip domestic chemical production. The Ministry of Trade, Industry and Energy is subsidizing etching chemistry localization to reduce Japanese import dependence. Pyeongtaek and Yongin semiconductor clusters are attracting German and US material suppliers seeking captive supply arrangements.
Japan
Photoresist and silicon wafer incumbents are leveraging METI critical materials security subsidies to defend domestic production scale against Korean and Chinese competition. The Ministry of Economy, Trade and Industry is directing funding toward 300mm silicon ingot capacity preservation. Kyushu and Tohoku manufacturing concentrations are maintaining process expertise in contamination control that new entrants cannot replicate.
Germany
Automotive power electronics demand from Infineon and Bosch is qualifying 200mm silicon carbide substrates for electric vehicle inverter applications. REACH compliance requirements are forcing reformulation investments in etching chemistries that reshape supplier cost structures. Saxony and Bavaria semiconductor clusters are integrating with Czech and Polish packaging facilities to build regional supply resilience.
Global Electronic Materials Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Polysilicon purification and EUV photoresist formulation remain consolidated around five to seven producers whose process expertise creates decade-long qualification barriers. Equipment-materials bundling specialists and captive chemical divisions of integrated device manufacturers represent distinct competitive archetypes. Capacity expansion and strategic partnerships dominate competitive moves, with foundry procurement consortia forcing supply priority negotiations before facility construction.
Within the materials formulation tier, Shin-Etsu Chemical Co., Ltd. and JSR Corporation exemplify Japanese specialization in purity-critical inputs where alternative sourcing remains scarce. Applied Materials, Inc. anchors equipment-chemistry bundling strategies that extend influence into process material selection. These three occupy positions where technical qualification requirements and capital intensity create defensive moats against new market entry.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Kyocera Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| JSR Corporation |
| Tokyo Electron Limited |
| Sumco Corporation |
| Dow Inc. |
| DuPont de Nemours, Inc. |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors impose cost volatility that amplifies East Asian supply concentration effects, forcing European buyers to absorb premium differentials against domestic contract pricing while polysilicon purity grades stratify procurement tiers.
Pricing Analysis
Geographic price spreads between German and Taiwanese polysilicon contracts exceed 15% after freight and duty layering, with contract-based long-term offtake dominating semiconductor-grade silicon while spot transactions govern commodity-grade feedstock. Price differentiation rests on certification grade—SEMI standard versus solar-grade specifications—and volume scale commitments that lock in foundry allocation priority. Cost compression in photoresist formulations is intensifying because JSR Corporation and Tokyo Electron are absorbing REACH reformulation expenses without full pass-through. Memory manufacturers exhibit highest price sensitivity due to cyclical margin pressure, while aerospace-qualified material buyers accept premiums for traceability documentation.
Supply Chain Analysis
Polysilicon purification feeds from metallurgical-grade silicon sourced primarily from China, Norway, and the United States, with semiconductor-grade refinement concentrating in Germany, Japan, and select Chinese facilities. High-purity hydrogen fluoride, trichlorosilane, and electronic-grade nitric acid constitute critical chemical dependencies that draw from Japanese and Korean specialty gas networks. Single-source vulnerability pervades EUV photoresist supply where JSR Corporation maintains formulation exclusivity at sub-3nm nodes. Distribution runs through consolidated procurement consortia—Apple, NVIDIA, and AMD negotiating directly with precursor suppliers—bypassing traditional foundry chemical purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face substitution defense imperatives as dry etching chemistries using NF3 alternatives penetrate South Korean memory fabs, threatening incumbent fluorinated gas positions.
For Market Incumbents: Insulate formulation portfolios by securing captive polysilicon purification capacity in Arizona and Texas before TSMC and Samsung Foundry complete construction, while accelerating REACH-compliant etching chemistry registration to capture first-mover advantage during European F-Gas phase-out. Threat vectors include Chinese polysilicon producers achieving SEMI certification and Lam Research qualifying fluorine-free process modules. For New Entrants and Emerging Players: Build out pilot-scale printed electronics capabilities targeting automotive interior sensing modules in Germany and medical wearable electrodes in the United States, where silver nanoparticle ink cost barriers are easing. The most penetrable white-space sits in India packaging hub emergence under PLI scheme subsidies, with substrate manufacturers seeking non-East Asian sourcing. Go-to-market leverage rests on demonstrating process equivalence through computational lithography simulation rather than full fab qualification trials. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated device manufacturer captive chemical divisions where parent companies seek to monetize non-core assets—particularly legacy dielectric formulation operations at mature-node fabs. Long-term viability favors suppliers with demonstrated sub-7nm node qualification expertise and established contamination control protocols that new entrants cannot replicate within a decade. Watch for inflection when Bureau of Industry and Security licensing timelines compress below six months, signaling capacity planning unfreezing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Purification | Secures feedstock autonomy against Chinese energy intensity ceilings constraining expansion timelines. |
| REACH-Compliant Etching Chemistry Registration | Captures European market share as ECHA accelerates perfluorinated compound phase-outs. |
| Computational Lithography Platform Deployment | Reduces chamber matching time by 60% for TSMC and Samsung Foundry qualification cycles. |
| India Packaging Hub Joint Venture | Establishes alternative sourcing footprint under PLI scheme subsidies reducing East Asian concentration. |
| Long-term Supply Agreement with Hyperscaler Consortia | Locks priority allocation through Apple, NVIDIA, and AMD consolidated procurement negotiations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and semiconductor equipment manufacturer disclosures, combining interviews with foundry procurement directors, specialty chemical plant managers, and downstream OEM technical qualification leads. Bottom-up triangulation across wafer consumption metrics and top-down validation against fabrication capacity announcements ensures cross-verification of material demand estimates.
Forecast inputs span technology node migration rates, regulatory compliance cost absorption, and regional capacity buildout announcements across the analysis window. Segmentation dimensions modeled include product purity grade, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections calibrated against historical polysilicon price-volume relationships and photoresist consumption per wafer layer at advanced nodes.
Stress conditions across Chinese energy policy enforcement, EPA emissions control stringency, and Bureau of Industry and Security licensing duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding node transition timelines and substitution elasticity for wide bandgap substrates. Material shifts in REACH perfluorinated compound phase-out schedules or dual-use export control scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Semiconductor Grade Neon Gas Market