
 OLED Panel Market | 2026-2036
OLED Panel Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Panel Market Intelligence
The modularization of display engine components is decoupling panel procurement from integrated touch and driver IC solutions for device manufacturers. Samsung Display leverages its vast manufacturing scale and R&D in the smartphone display segment to maintain a dominant position. LG Display specializes in large-format White OLED (WOLED) panels, primarily targeting the premium television market. Concurrently, BOE Technology Group from China competes on volume and cost across both rigid and flexible OLED formats.
An OLED panel is a self-emissive solid-state device utilizing organic compounds that illuminate when current is applied. This technology eliminates the need for a backlight, allowing for superior contrast, true black levels, and thinner device profiles. Flexible OLEDs for high-end smartphones represent the fastest-growing product type by revenue. The television application segment commands higher margins, while wearable devices drive significant volume.
Display manufacturers must adhere to material restrictions outlined in the EU's RoHS directive and meet energy efficiency targets from agencies like the US EPA. In Asia, compliance with China's GB standards and South Korea's environmental regulations is mandatory for market access. Stakeholders must now monitor the development of 'right to repair' legislation, which could influence panel design and aftermarket supply chains.
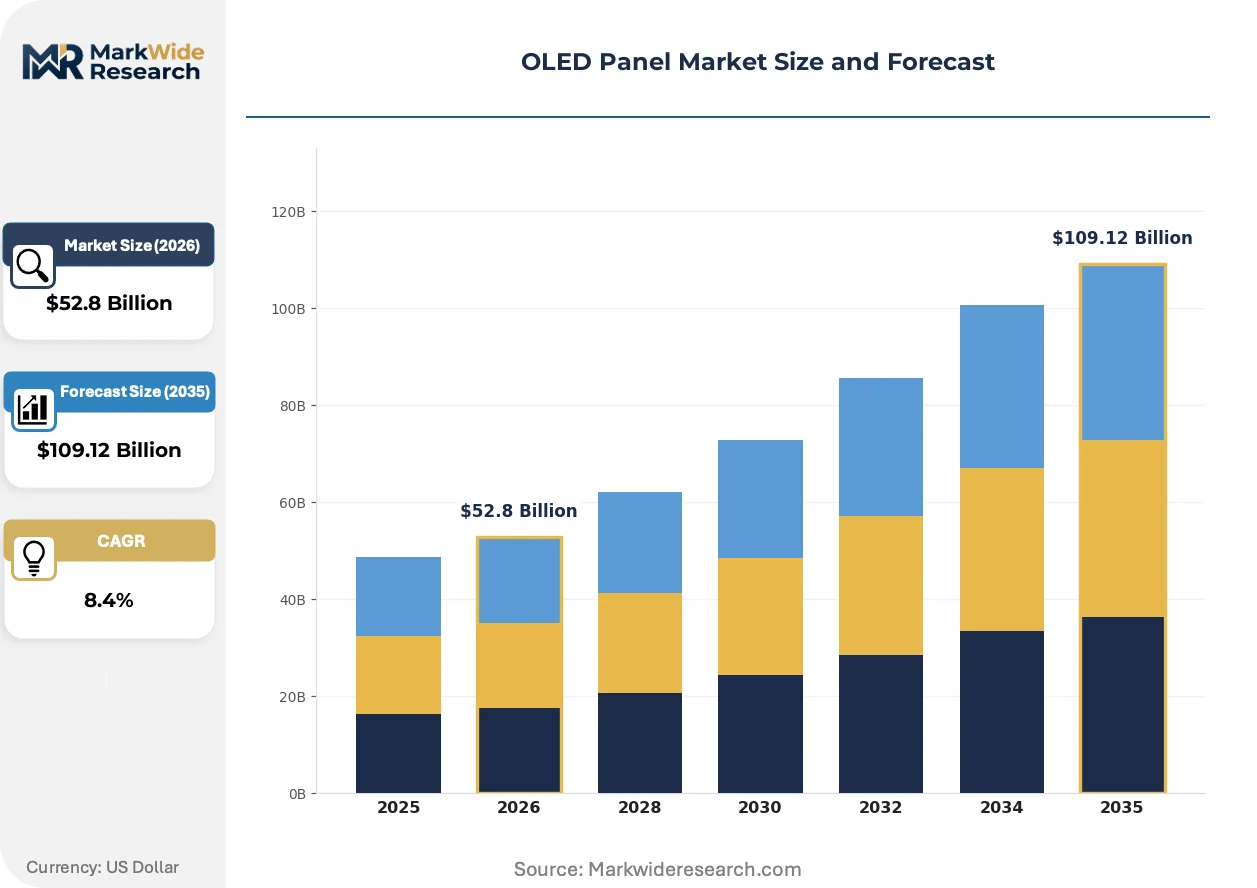
Market Dynamics
The market's central dynamic is the tension between massive capital investment in next-generation fabrication plants and intense price pressure from major device manufacturers. This is amplified by the heavy concentration of manufacturing capacity within specific consumer electronics clusters in China, which dictates cost structures and supply availability.
Growth Catalysts
- Phosphorescent Blue Emitters:Material science advancements in phosphorescent blue emitters are improving panel efficiency and operational lifetime, unlocking new applications in professional monitors and automotive displays.
- Premium Smartphone Demand:Strong demand from the premium smartphone sector for flexible and foldable OLED displays with higher refresh rates and resolutions acts as a primary growth engine.
- Automotive Integration:The automotive industry's shift toward digital cockpits and larger in-cabin screens creates a significant new demand vector for durable, free-form OLED panels.
Market Restraints
- High Capex Requirements:The immense capital expenditure needed to build and upgrade OLED fabrication facilities creates high barriers to entry, concentrating production among a few large players and limiting competitive diversity.
- Blue Emitter Lifespan:The limited operational lifespan and efficiency of blue organic materials compared to red and green counterparts remains a key technical constraint for certain long-life applications.
- Key Material Dependency:The supply chain is highly dependent on a few specialized suppliers for critical components like fine metal masks (FMM), creating potential bottlenecks and price volatility.
Strategic Opportunities
- Transparent OLEDs:The development of transparent OLED technology opens commercial opportunities in retail advertising, architectural glass, and smart windows, moving beyond traditional consumer electronics.
- Indian Market Penetration:India's expanding middle class and increasing smartphone adoption present a large, underpenetrated market for mid-range devices equipped with rigid OLED panels.
- 'Right to Repair' Legislation:Emerging 'right to repair' laws in Europe and the US could create an aftermarket for modular display panels, fostering a new service-oriented revenue stream.
Industry Challenges
- Yield Rate Optimization:Achieving and maintaining high manufacturing yield rates, especially for large-format and flexible panels, is a persistent operational challenge that directly impacts profitability.
- Evolving Environmental Standards:Navigating a complex web of environmental regulations, including the EU's RoHS directive and China's GB standards, requires constant process adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Panel Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $109.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible OLED, Rigid OLED, Transparent OLED, UHD OLED Application: Smartphones, Televisions, Wearable Devices, Digital Signage Technology: RGB OLED, White OLED, Top-emitting OLED, Bottom-emitting OLED End User: Consumers, Retailers, Manufacturers, Designers |
| Companies Covered | Samsung Display, LG Display, BOE Technology Group, AU Optronics, Universal Display Corporation, Sony Corporation, Visionox, Innolux Corporation, Tianma Microelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Panel Market Strategic Shifts & Innovations
Material science breakthroughs and advanced manufacturing techniques are pushing OLED technology beyond conventional form factors. These innovations focus on enhancing energy efficiency, expanding application suitability, and aligning with circular economy principles.
Tandem OLED architecture, which stacks multiple emissive layers, boosts panel brightness and extends operational lifespan. The automotive and high-end IT sectors are rapidly adopting this technology for its durability. This shift toward multi-stack designs is consolidating the market's focus on premium, long-life applications over purely cost-driven segments.
The European Union's updated RoHS directive places stricter limits on hazardous substances in electronic components, including materials in OLED panels. This forces manufacturers to invest in R&D for compliant alternatives and re-certify supply chains for market access. Panel makers targeting the television segment are most affected, accelerating the search for greener emitter materials.
Device manufacturers are increasingly unbundling panel sourcing, moving from integrated modules toward procuring discrete components. This modularization decouples the OLED panel from the touch and driver IC, giving OEMs greater supply chain control. This pattern is most visible among smartphone brands in China and Southeast Asia seeking differentiation without single-source dependency.
OLED Panel Market Segmentation
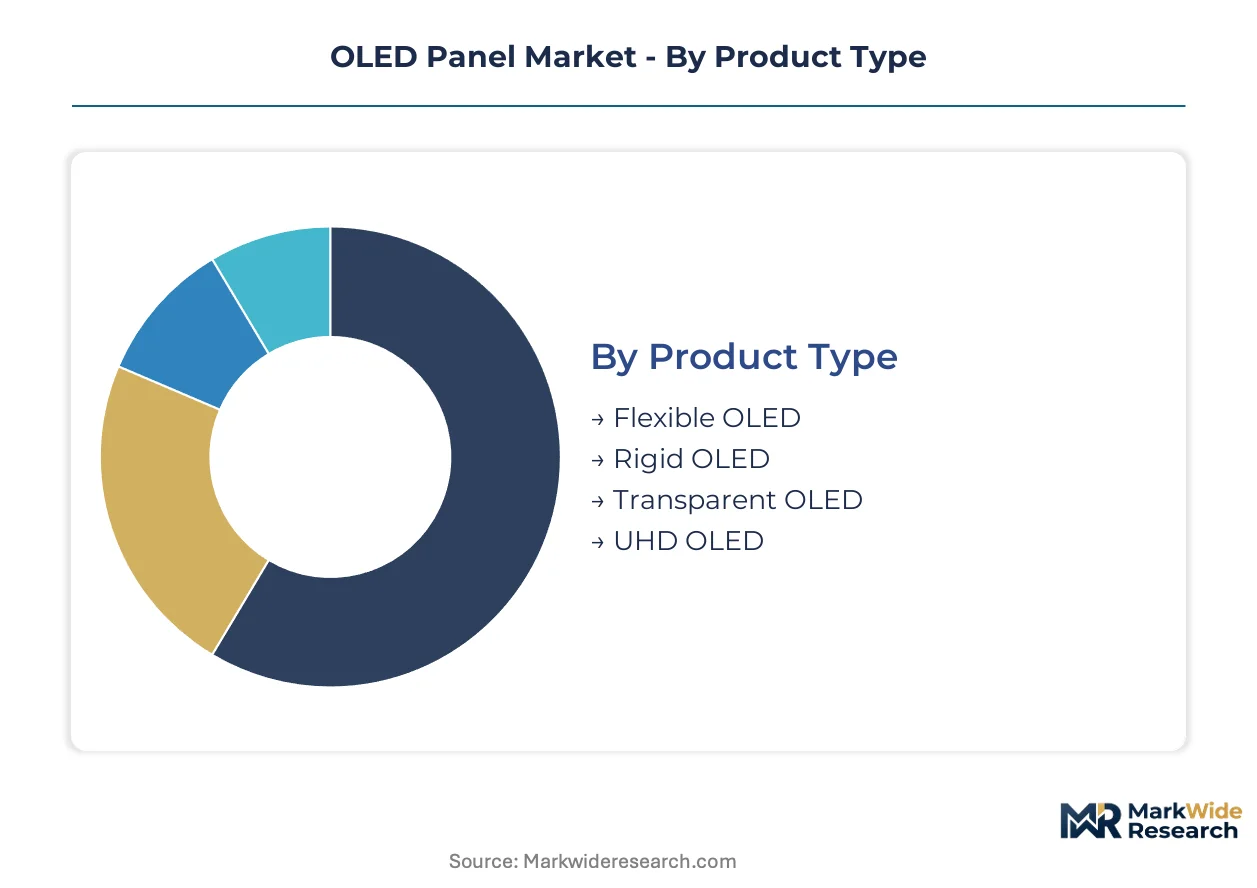
The OLED Panel Market segmentation provides a granular view of the diverse product offerings and their strategic deployment across various end-use applications.
Understanding these distinct segments is critical for assessing technological advancements, market penetration, and competitive dynamics within the industry.
Product Type:
The product type segmentation for OLED panels spans a spectrum from highly standardized, mass-produced components to cutting-edge, customized solutions. This differentiation impacts manufacturing complexity, pricing models, and target market applications.
- Flexible OLED:These panels are built on plastic substrates, allowing them to be bent, folded, or rolled into various form factors. Demand from premium smartphone manufacturers drives significant revenue, particularly for devices requiring curved or foldable displays.
- Rigid OLED:These displays utilize glass substrates, offering a cost-effective and robust solution for a wide range of mid-range smartphones and other consumer electronics.
- Transparent OLED:This innovative technology allows light to pass through the panel when pixels are off, creating see-through display surfaces. Commercial opportunities in retail advertising and architectural design are rapidly expanding.
- UHD OLED:Offering ultra-high definition resolutions, these panels provide exceptional visual clarity for high-end televisions and professional monitors.
Most installed capacity flows through Rigid OLED. Expansion is steepest in Flexible OLED.
Application:
The application segment illustrates the diverse deployment of OLED technology, from mature consumer electronics to emerging commercial installations. Each segment presents distinct performance requirements and market entry barriers.
- Smartphones:These devices are a primary driver for OLED panel demand, particularly for flexible and high-resolution displays. The premium smartphone sector consistently seeks improved refresh rates and color accuracy.
- Televisions:This segment leverages large-format OLED panels, especially White OLED, to deliver superior contrast and true black levels. High-margin opportunities exist within the premium television market.
- Wearable Devices:Small-format OLED panels provide vibrant, energy-efficient displays for smartwatches and fitness trackers, driving significant unit volume.
- Digital Signage:Large-scale OLED displays offer high visibility and dynamic content for commercial advertising and public information systems.
Smartphones contribute the largest volume, while Televisions command the highest per-unit value.
Technology:
The technology segmentation delineates OLED panels by their fundamental emission mechanisms and light extraction methods. These distinctions influence panel performance characteristics, manufacturing complexity, and suitability for specific applications.
- RGB OLED:This technology utilizes individual red, green, and blue subpixels to directly emit colored light, offering precise color control. It is commonly found in smaller displays like smartphones and virtual reality headsets.
- White OLED:These panels employ a stack of emissive layers to produce white light, which then passes through color filters to create RGB subpixels. LG Display primarily uses this for large-format television panels.
- Top-emitting OLED:Light is extracted from the top surface of the OLED stack, allowing for higher aperture ratios and brightness. This configuration is favored in high-resolution displays.
- Bottom-emitting OLED:Light is emitted through the transparent substrate, a simpler structure often used in early OLED designs and some rigid panel applications.
White OLED dominates large-format television panels, while RGB OLED is prevalent in mobile displays.
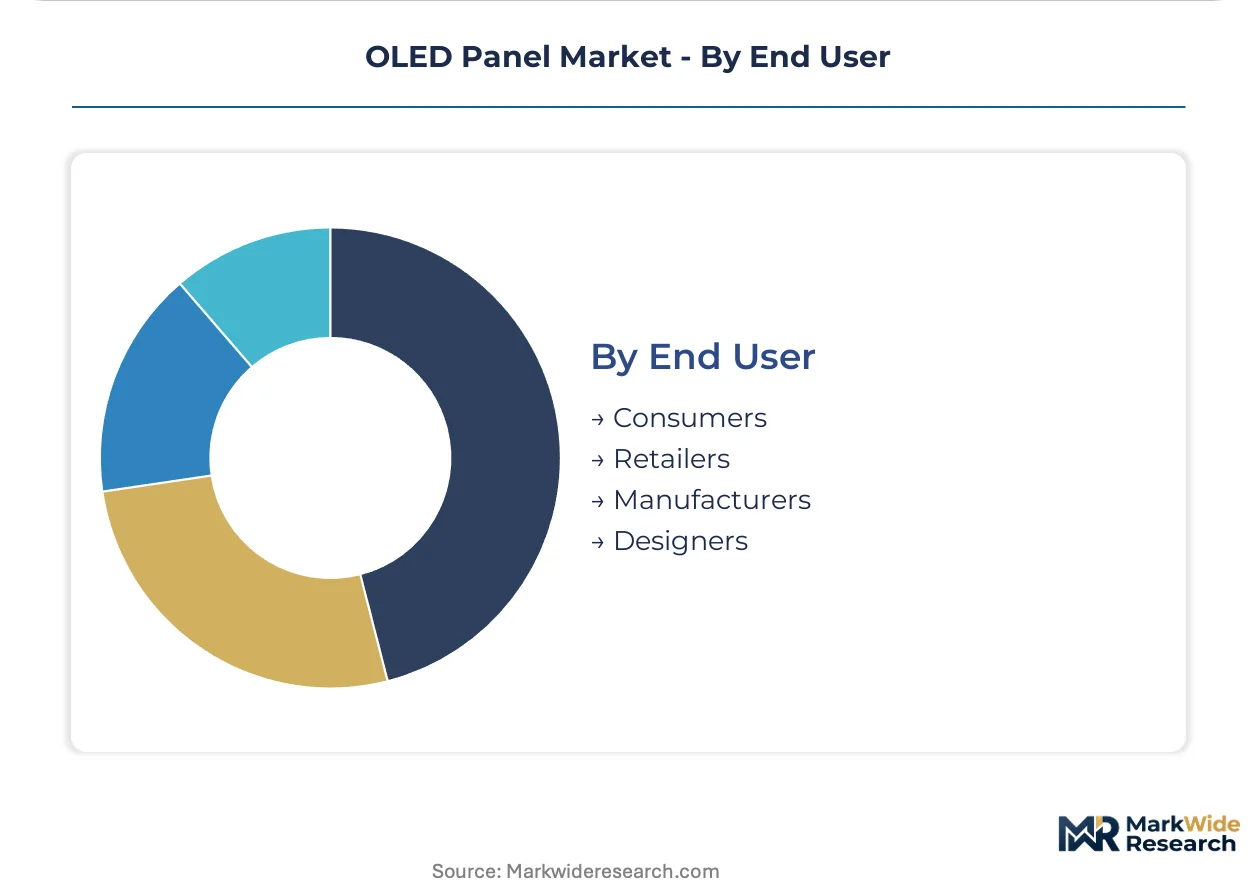
End User:
The end-user segmentation categorizes the primary purchasers of OLED panels based on their specific needs and purchasing power. Each group seeks distinct attributes, from cost-effectiveness to advanced customization.
- Consumers:These end-users indirectly drive demand through their purchase of OLED-equipped devices like smartphones, televisions, and wearables. Their preferences dictate trends in display quality and features.
- Manufacturers:Device manufacturers procure OLED panels for integration into their final products, influencing specifications and supply chain dynamics. Companies like Samsung and Apple are major buyers.
- Retailers:These entities purchase OLED panels for digital signage and in-store displays, focusing on visual impact and durability.
- Designers:Professional designers utilize OLED panels for specialized applications such as architectural installations or bespoke product prototypes, valuing aesthetic flexibility.
Manufacturers directly influence panel procurement, while Consumers drive overall market demand for finished products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The OLED industry scaled significantly in East Asia, particularly in South Korea and Japan, through pioneering display technologies. Early investments established foundational research and manufacturing capabilities for these advanced panels. China later emerged as a major production hub, leveraging vast industrial capacity.
China
China drives demand for flexible and rigid OLEDs, particularly for its massive smartphone market and burgeoning digital signage applications. The national GB standards mandate strict environmental compliance for manufacturing processes. The Yangtze River Delta region, including cities like Shenzhen, concentrates high-volume OLED panel production.
South Korea
South Korea maintains strong demand for premium smartphone displays and large-format White OLED televisions. The country's environmental regulations guide material usage and waste management in display fabrication. Paju and Asan are major manufacturing centers for advanced OLED panels, hosting key industry players.
Japan
Japan seeks high-resolution OLED panels for professional monitors and integrates durable displays into automotive applications. JIS standards provide comprehensive guidelines for material quality and product performance. The Tokyo region maintains strong research and development in emitter materials and advanced manufacturing equipment.
United States
The United States generates significant demand for high-end smartphone integration and sophisticated automotive digital cockpits. EPA energy efficiency targets influence panel design, while 'right to repair' legislation could reshape aftermarket supply chains. Silicon Valley drives advanced display integration into consumer electronics.
Germany
Germany integrates OLED panels into high-end automotive in-cabin systems and specialized professional IT monitors. The EU's RoHS directive places stringent limits on hazardous substances in display components. Bavaria focuses on automotive display innovation and integration within its robust manufacturing sector.
OLED Panel Market Key Industry Players
The competitive structure tilts toward vertically integrated display giants that command significant capital and technological resources. A few large players dominate the market due to immense capital expenditure requirements for fabrication facilities. These companies represent distinct archetypes: integrated display manufacturers, specialized material suppliers, and emerging cost-competitive producers. Capacity expansion in flexible OLEDs and continuous R&D in emitter materials are dominant competitive moves.
At the scale-driven end, Samsung Display and LG Display represent established South Korean powerhouses, leveraging extensive R&D and manufacturing prowess. Samsung Display anchors the premium smartphone segment, while LG Display occupies a position as a leader in large-format television panels. BOE Technology Group, a Chinese entity, exemplifies the aggressive expansion of production capacity and cost-competitive strategies across both rigid and flexible OLED formats. These entities collectively influence market dynamics through their specialized focus and broad product portfolios, shaping the global supply landscape.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology Group |
| AU Optronics |
| Universal Display Corporation |
| Sony Corporation |
| Visionox |
| Innolux Corporation |
| Tianma Microelectronics |
| Others |
Cost & Logistics Intelligence
Vertical integration by major display manufacturers anchors both the supply position and the pricing power within the OLED panel market. This strategic control over production capabilities and key component sourcing significantly influences market dynamics and cost structures.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for large-volume OLED panel procurement. Price differentiation stems from panel quality grade, such as UHD resolution, and the level of customization required for specific device form factors. Pricing pressure from major device manufacturers is intense, particularly for high-volume rigid OLED panels used in mid-range smartphones. Mid-range device manufacturers exhibit the highest price sensitivity, while premium smartphone brands prioritize performance and advanced features.
Supply Chain Analysis
Dual-sourcing requirements often mandated by device manufacturers aim to mitigate risks in the highly concentrated OLED supply chain. Geographic supply concentration primarily rests in South Korea, China, and Japan. The supply chain draws from specialized inputs like phosphorescent blue emitters and fine metal masks (FMM), creating potential single-source vulnerability. Direct sales to original equipment manufacturers (OEMs) define the dominant distribution model, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OLED panel market operates as a regulatory compounder, with the EU's updated RoHS directive driving significant investment in compliant material alternatives and greener manufacturing processes.
For Market Incumbents:Cement leadership by investing heavily in next-generation phosphorescent blue emitter R&D, extending panel lifespan and efficiency. Expand flexible OLED manufacturing capacity in strategic regions to address growing premium smartphone demand, mitigating intense price pressure from emerging cost-competitive producers. Prioritize compliance with evolving environmental standards like China's GB standards to maintain market access and differentiate through sustainable practices.
For New Entrants and Emerging Players:Niche technology development in transparent OLEDs presents a distinct technology-first wedge into commercial applications like retail and architecture. Target the underpenetrated Indian market with cost-effective rigid OLED panels for mid-range smartphones, leveraging volume-driven strategies. Focus on modular display components to offer greater supply chain flexibility to OEMs, challenging integrated solutions from established players.
For Investors and Strategic Acquirers:Consolidation pressure builds where high capital expenditure requirements limit competitive diversity, favoring established players. Long-term viability hinges on sustained demand for premium and specialized display applications over the next decade. Acquisition targets should include specialized material science firms focusing on emitter technology or companies with proprietary transparent OLED intellectual property. The signal to watch is the accelerated adoption rate of tandem OLED architecture in high-end IT and automotive displays.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Flexible OLEDs | Increases supply for premium smartphones and foldable devices, addressing a primary growth engine. |
| R&D in Phosphorescent Blue Emitters | Extends operational lifespan and efficiency of OLED panels, unlocking new long-life applications. |
| Strategic Partnerships with Automotive OEMs | Secures demand for durable, free-form OLEDs in the rapidly evolving digital cockpit market. |
| Supply Chain Diversification for FMM | Reduces reliance on single-source suppliers, mitigating potential bottlenecks and price volatility. |
| Investment in EU RoHS Compliant Materials | Ensures market access in Europe and enhances environmental sustainability credentials for panel manufacturers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive understanding of the OLED Panel Market. Primary research involved discussions with display engineers, procurement managers at device manufacturers, material scientists, and supply chain executives. This was triangulated with secondary data from corporate financial filings, patent databases, national trade statistics, and environmental agency reports.
The segment-weighting approach formed the foundation of the forecast framework, modeling market dynamics across product type, application, technology, end user, and regional demand. Compound annual growth rates were derived from historical data analysis and projected market trends over the projection horizon. Key industry-specific forecast inputs included display panel average selling prices (ASPs) and global device shipment forecasts across various application segments.
The model holds under current macroeconomic conditions and anticipated technological advancements; deviation in geopolitical trade policies, material supply disruptions, or rapid technological shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Touch Screen Display Market
Display Technologies
3LCD Projector Market
Display Technologies
United States Microdisplay Market
Display Technologies
Plasma Display Module Market
Display Technologies
Laptop Panels Market
Display Technologies
3D Display Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Global Display Controllers Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Touch Screen Film Market
Display Technologies
Backlit Displays Market
Display Technologies
Volumetric Display Market
Display Technologies
Asia Pacific Computer Monitor Market
Display Technologies
Automotive LCD Display Market