
 ITO Nanoparticles Market | 2026-2036
ITO Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
ITO Nanoparticles Market Foresight
Aftermarket ITO coating refurbishment is narrowing as a margin pool as manufacturers shift toward in-house thin-film deposition capabilities. American Elements leverages its vertical integration across indium refining to nanoparticle synthesis to sustain pricing power in North America. MITSUI MINING and SMELTING CO. LTD. anchors supply security through captive indium smelting operations in Japan. Nanoshel LLC specializes in custom nanorod geometries for niche sensor applications, occupying a defensible technology tier.
Indium tin oxide nanoparticles consist of a tin-doped indium oxide composition, typically formulated as In₂O₃:Sn with 5–10 weight percent tin oxide, synthesized via sol-gel or hydrothermal methods to achieve particle sizes below 100 nanometers for optimized optical transparency and electrical conductivity in thin-film applications. Transparent conductors represent the dominant application segment where nanopowder formulations command premium positioning due to superior sputtering efficiency in display manufacturing. Solar cell applications are accelerating fastest as nanocrystal architectures improve charge transport in perovskite and heterojunction cell designs, while sensor deployments in automotive LiDAR systems remain an emerging volume channel.
EPA hazardous substance reporting requirements and REACH substance authorization protocols in Europe constrain indium sourcing transparency and compel suppliers to maintain comprehensive chemical safety documentation. Japan's METI enforces JIS standards for electronic-grade nanopowders that directly gate market access for non-compliant imports. South Korea's MFDS and KATS frameworks extend quality verification into downstream consumer electronics supply chains. Stakeholders must monitor evolving rare earth export licensing regimes and indium stockpile policies across producing jurisdictions to anticipate supply discontinuities.
Market Dynamics
Touchscreen manufacturers are consolidating thin-film deposition capabilities in-house, collapsing the aftermarket refurbishment channel and compressing margin pools for independent coating suppliers across East Asian electronics clusters.
Growth Catalysts
- Perovskite Solar Expansion:Heterojunction cell architectures incorporating nanocrystal ITO formulations are accelerating photovoltaic efficiency gains in Japanese and South Korean manufacturing lines.
- REACH Substance Authorization:European material purity mandates are filtering non-compliant suppliers from the value chain, concentrating volume with certified nanopowder producers.
- Automotive LiDAR Integration:Tier-1 sensor suppliers in Germany and Japan are specifying custom nanorod geometries for transparent conductor layers in next-generation autonomous vehicle systems.
Market Restraints
- Indium Concentration Risk:Primary indium smelting capacity clusters in Chinese and Korean refining operations, exposing downstream nanoparticle synthesis to export licensing volatility.
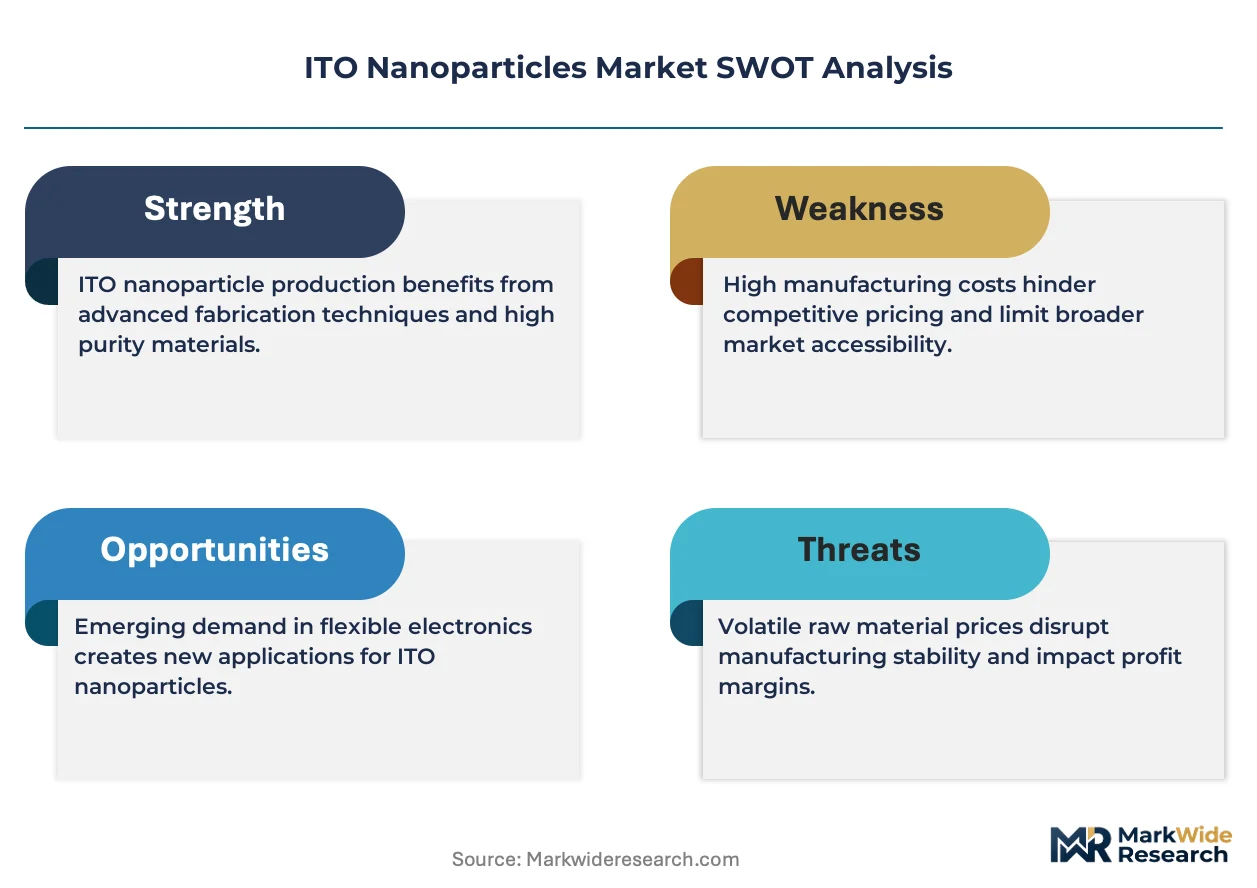
- Silver Nanowire Substitution:Flexible display manufacturers are piloting silver nanowire meshes for foldable applications, threatening ITO's dominance in emerging form factors.
- JIS Certification Barriers:Japan's METI-enforced electronic-grade standards gate market access for imported nanopowders lacking documented traceability protocols.
Strategic Opportunities
- US IRA Clean Energy Credits:Domestic solar cell manufacturing incentives are creating localized demand for sputtering-target-grade ITO nanoparticles in American thin-film deposition facilities.
- Printed Electronics Convergence:Inkjet deposition of ITO nanoparticle suspensions is enabling roll-to-roll transparent conductor manufacturing for flexible sensor substrates.
- Saudi Giga-Project Demand:NEOM and Red Sea tourism developments are specifying smart glass installations with integrated transparent conductor layers for climate-responsive building envelopes.
Industry Challenges
- Sol-Gel Process Scale-Up:Translating laboratory hydrothermal synthesis to continuous production lines requires capital-intensive reactor engineering and particle-size distribution control systems.
- Dual-Use Export Classification:Indium's presence on strategic materials watchlists complicates cross-border shipments of high-purity nanopowders to aerospace and defense contractors.
- Perovskite Interface Engineering:Charge transport layer integration demands precise work-function matching between ITO nanocrystal architectures and emerging organic-inorganic hybrid cell chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ITO Nanoparticles Market |
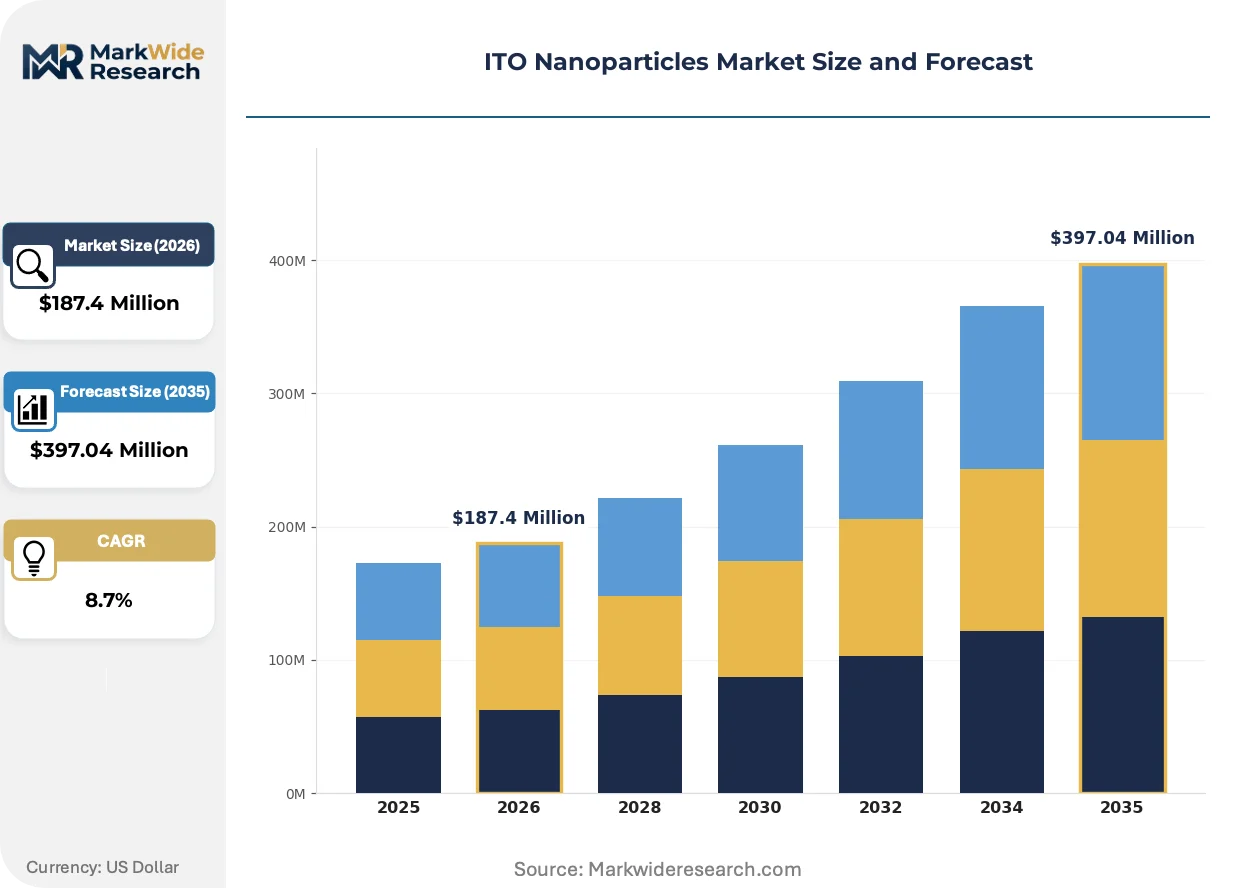
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanopowder, Nanocrystal, Nanorods, Nanodisks Application: Transparent Conductors, Electronics, Solar Cells, Sensors End User: Consumer Electronics, Solar Energy, Automotive, Aerospace Form: Powder, Film, Coating, Composite |
| Companies Covered | American Elements, Nanoshel LLC, NANOGRAFI Co. Inc., NYACOL Nano Technologies Inc., Indium Corporation, Merck KGaA, Umicore, MITSUI MINING and SMELTING CO. LTD., Nitto Denko Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ITO Nanoparticles Market Shifts & Advancements
Sputtering efficiency improvements and alternative deposition methods are restructuring how transparent conductor layers integrate into display and photovoltaic manufacturing workflows across East Asian production hubs.
Solution-processed ITO nanoparticle inks are migrating from laboratory prototyping to pilot-scale roll-to-roll coating lines. Korean display panel manufacturers are qualifying aqueous suspension formulations for flexible OLED substrate manufacturing. This migration from vacuum sputtering to wet-chemical deposition is compressing capital requirements for entry-level transparent conductor production.
EPA hazardous substance reporting thresholds for indium compounds are tightening documentation burdens on US-based nanoparticle importers. The agency's expanded chemical data reporting rules now capture downstream processing volumes previously exempt from disclosure. Solar cell manufacturers in California and Texas are consolidating supplier relationships to reduce compliance fragmentation across their raw material portfolios.
Buyer consolidation among tier-1 touchscreen module suppliers is compressing vendor qualification cycles and favoring integrated material-formulation-deposition partnerships. Japanese electronics assemblers are specifying nanopowder specifications directly with indium refiners, bypassing traditional chemical distributor intermediaries. This channel restructuring is most visible in South Korean smartphone supply chains, where Samsung Display and LG Innotek have established captive nanoparticle specification teams.
ITO Nanoparticles Market Segmentation
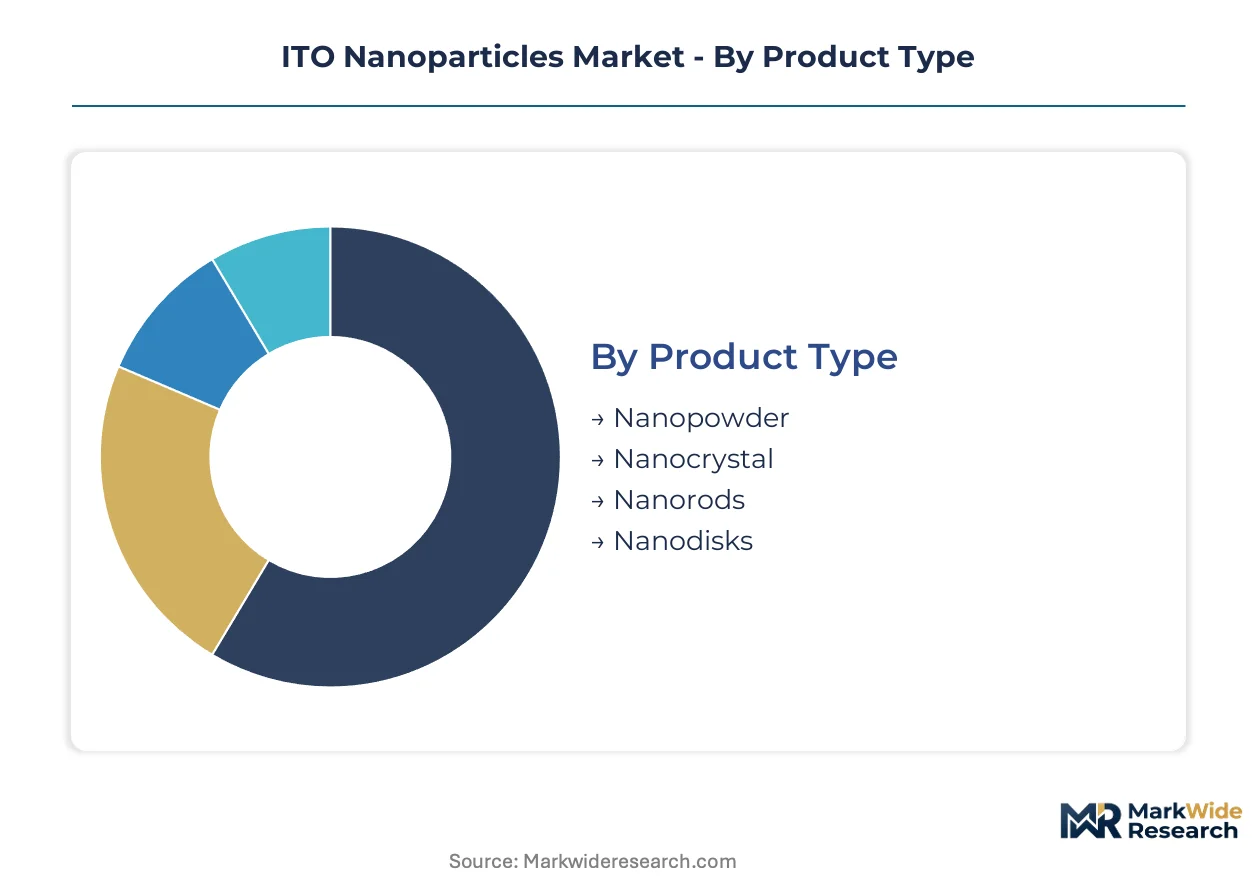
ITO nanoparticle specifications diverge sharply across deposition methods and end-use performance thresholds. Product geometry, application layer, and form factor each command distinct supply chain configurations and pricing bands.
Product Type:
Cost tier differentiation separates commodity nanopowders from engineered nanorod architectures.
- Nanopowder:Spherical particulate formulations below 100 nanometers dominate sputtering target production. Display manufacturers in South Korea and Japan consume volume for thin-film transistor backplanes.
- Nanocrystal:Crystalline domain structures with controlled grain boundaries optimize charge transport in photovoltaic applications. Perovskite cell producers specify nanocrystal ITO for heterojunction interfaces.
- Nanorods:Aspect-ratio-tuned geometries enable anisotropic conductivity in sensor applications. Automotive LiDAR suppliers specify custom rod lengths for transparent conductor grids.
- Nanodisks:Platelet morphologies with tunable surface plasmon resonance occupy niche optical coating segments.
Nanopowder holds installed capacity. Nanocrystal is rotating up the share rankings.
Application:
Application layer determines purity grade and documentation burden.
- Transparent Conductors:Sputtering-target-grade formulations require 99.99% purity with documented traceability. Touchscreen module suppliers in East Asia specify direct refiner relationships to bypass distributor markups.
- Solar Cells:Perovskite and heterojunction architectures demand work-function-matched nanocrystal layers. Japanese and South Korean photovoltaic lines are qualifying aqueous ink formulations.
- Electronics:Printed circuit and flexible substrate applications utilize lower-purity nanopowder dispersions.
- Sensors:Automotive and industrial detection systems specify geometrically precise nanorod depositions.
Transparent conductors anchor current volume. Solar cells are climbing the fastest.
End User:
Customer type dictates procurement scale and technical service intensity.
- Consumer Electronics:Smartphone and tablet manufacturers consolidate specifications through captive nanoparticle teams. Samsung Display and LG Innotek negotiate directly with indium refiners.
- Solar Energy:Domestic manufacturing incentives under the US IRA are creating localized demand for sputtering-grade material.
- Automotive:Tier-1 sensor suppliers specify custom geometries for autonomous vehicle LiDAR systems.
- Aerospace:Defense contractors face dual-use export classification complexity for high-purity shipments.
Consumer electronics holds installed capacity. Solar energy is rotating up the share rankings.
Form:
Form factor shapes capital requirements and deposition workflow integration.
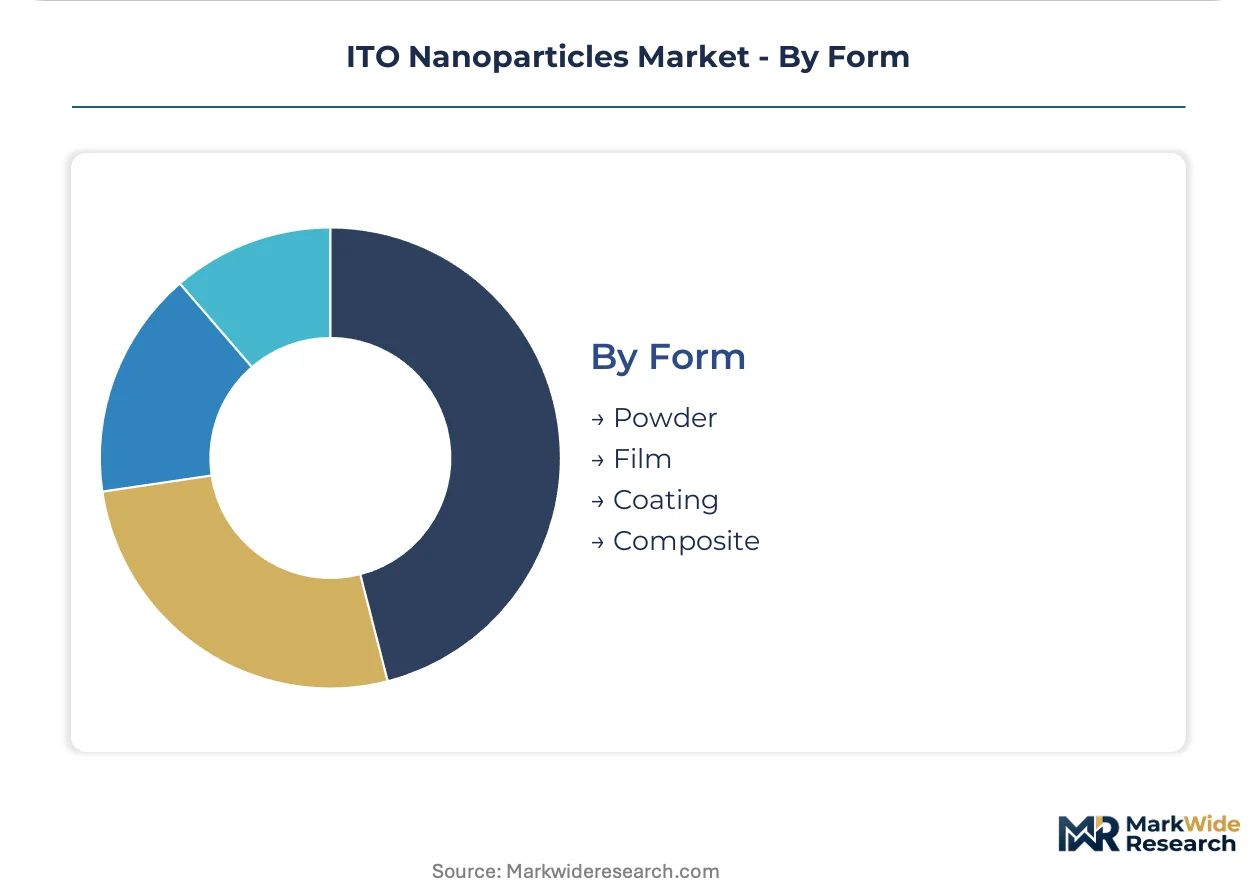
- Powder:Dry nanopowder remains the baseline feedstock for vacuum sputtering operations. Established display lines in Japan and South Korea maintain powder-based workflows.
- Film:Pre-cast transparent conductor layers compress processing steps for entry-level manufacturers.
- Coating:Solution-processed suspensions enable roll-to-roll wet deposition. Korean panel makers are qualifying aqueous ITO inks for flexible OLED substrates.
- Composite:Polymer-matrix formulations target emerging printed electronics applications.
Powder holds installed capacity. Coating is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan demonstrate the least price elasticity, absorbing premium nanopowder grades for display manufacturing, while Chinese and Southeast Asian procurement teams negotiate aggressively on standard formulations. European buyers split between certified premium tiers for automotive applications and cost-optimized grades for industrial coatings. North American demand clusters around solar energy incentives that prioritize domestic sourcing over unit cost minimization.
United States
Domestic solar cell manufacturing incentives under the IRA are creating localized demand for sputtering-target-grade ITO nanoparticles in Texas and California thin-film facilities. EPA hazardous substance reporting requirements now capture downstream processing volumes, compelling importers to consolidate supplier relationships. Austin and Dallas-Fort Worth clusters host emerging deposition equipment vendors qualifying aqueous ink formulations.
Japan
Perovskite and heterojunction photovoltaic lines in Osaka and Nagoya are qualifying nanocrystal ITO architectures for next-generation cell efficiencies. METI enforces JIS standards for electronic-grade nanopowders that gate market access for non-compliant imports. The Kansai industrial corridor maintains captive indium refining relationships with downstream nanoparticle specification teams at major display assemblers.
South Korea
Samsung Display and LG Innotek negotiate directly with indium refiners, bypassing traditional chemical distributor intermediaries for touchscreen module feedstock. MFDS and KATS frameworks extend quality verification into consumer electronics supply chains. The Seoul Capital Area concentration of panel manufacturers is piloting aqueous suspension formulations for flexible OLED substrate production.
Germany
Tier-1 automotive sensor suppliers in Munich and Stuttgart specify custom nanorod geometries for LiDAR transparent conductor layers in autonomous vehicle systems. REACH substance authorization protocols filter non-compliant suppliers from the European value chain. The Bavarian automotive electronics cluster is consolidating vendor qualification cycles around integrated material-formulation-deposition partnerships.
China
Primary indium smelting capacity clusters in Chinese refining operations expose downstream nanoparticle synthesis to export licensing volatility under evolving rare earth policies. The country's national materials regulator monitors strategic indium stockpile levels that anticipate supply discontinuities. Yangtze River Delta electronics manufacturing hubs are shifting thin-film deposition capabilities in-house, collapsing aftermarket refurbishment channels.
ITO Nanoparticles Market Competitive Landscape
Capability concentration sits with integrated indium refiners who control upstream material purity; scale advantage sits with diversified chemical conglomerates who cross-subsidize nanoparticle R&D across multiple specialty lines. The vendor base separates into three tiers: captive smelter-affiliated producers, independent nanoparticle specialists, and diversified materials distributors. Consolidation pressures favor backward integration into indium refining and strategic partnerships with display equipment OEMs.
Among integrated materials producers, American Elements leverages its vertical integration across indium refining to nanoparticle synthesis, while MITSUI MINING and SMELTING CO. LTD. anchors supply security through captive smelting operations in Japan. Nanoshel LLC occupies a defensible technology tier specializing in custom nanorod geometries for niche sensor applications.
| Leading Market Players |
|---|
| American Elements |
| Nanoshel LLC |
| NANOGRAFI Co. Inc. |
| NYACOL Nano Technologies Inc. |
| Indium Corporation |
| Merck KGaA |
| Umicore |
| MITSUI MINING and SMELTING CO. LTD. |
| Nitto Denko Corp. |
| Others |
Supply & Pricing Matrix
Indium concentration risk in Chinese and Korean primary smelting operations determines both three-tier pricing spreads across sputtering-grade, electronic-grade, and industrial-grade tiers and the elongated supply chain shape that chains downstream nanoparticle synthesis to export licensing volatility. Buyers in South Korea and Japan absorb premium spreads for documented traceability, while Southeast Asian procurement teams negotiate aggressively on standard formulations.
Pricing Analysis
Aftermarket coating refurbishment revenue is collapsing as touchscreen manufacturers consolidate thin-film deposition in-house, compressing lifetime value capture toward parts and raw material supply contracts. Pricing stratifies across premium sputtering-target grades with 99.99% purity and documented REACH compliance, standard electronic-grade nanopowders, and economy-tier industrial dispersions. Cost compression in standard grades is intensifying because Samsung Display and LG Innotek negotiate directly with indium refiners, bypassing distributor markups. Consumer electronics buyers demonstrate the least price elasticity, while industrial coating purchasers remain most sensitive.
Supply Chain Analysis
Tariff exposure between China and the United States complicates cross-border shipments of high-purity nanopowders flagged under dual-use export classifications. Primary indium smelting capacity clusters in China, South Korea, and Japan, with downstream nanoparticle synthesis drawing from captive refining operations, indium ingot feedstock, and specialty chemical precursors. Single-source vulnerability runs through Chinese rare earth export licensing regimes that anticipate supply discontinuities. Distribution runs through direct refiner relationships with major display assemblers, collapsing traditional chemical distributor channels across East Asian electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite solar cell commercialization represents a high-growth disruption as heterojunction architectures incorporating nanocrystal ITO formulations accelerate photovoltaic efficiency gains beyond incumbent silicon baselines.
For Market Incumbents: Insulate margin position by deepening backward integration into indium refining and securing captive smelting relationships in Japan or South Korea. Silver nanowire substitution in foldable displays threatens ITO dominance; preemptive investment in aqueous ink formulation capabilities for roll-to-roll deposition preserves relevance in emerging flexible substrate workflows. For New Entrants and Emerging Players: Build out aqueous suspension formulation capabilities targeting US solar cell manufacturing facilities qualifying for IRA clean energy credits. The domestic sputtering-target-grade segment remains penetrable because incumbent supply chains optimize for East Asian display volumes rather than localized American photovoltaic demand. A direct technical service model supporting Texas and California thin-film deposition clusters bypasses established distributor relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors materials specialists with nanocrystal architecture expertise over commodity nanopowder producers. Long-term viability over the next decade hinges on interface engineering capabilities for perovskite charge transport layers. Watch qualification timelines for aqueous ink formulations at Korean flexible OLED lines as the inflection signal for wet-chemical deposition displacement of vacuum sputtering.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Refining | MITSUI MINING and SMELTING CO. LTD. anchors supply security through captive Japanese smelting operations. |
| Aqueous Ink Formulation Development | Korean panel manufacturers pilot roll-to-roll deposition for flexible OLED substrate production. |
| REACH Certification Investment | European substance authorization protocols filter non-compliant suppliers from automotive value chains. |
| Direct Refiner Relationship Establishment | Samsung Display and LG Innotek negotiate nanopowder specifications bypassing chemical distributors. |
| Custom Nanorod Geometry Specialization | Nanoshel LLC occupies defensible positioning for automotive LiDAR transparent conductor specifications. |
Research Methodology
A spread of perspectives from thin-film deposition equipment engineers, indium refinery procurement managers, display panel R&D directors, and solar cell manufacturing executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings from listed materials producers, JIS and REACH regulatory documentation, and photovoltaic project development databases. Bottom-up volume estimates from nanoparticle consumption at individual manufacturing lines triangulated against top-down market sizing from indium refining output statistics.
Demand-supply balance modeling across the projection horizon segmented volume by product geometry, application layer purity requirements, end-user procurement scale, and deposition method form factor. CAGRs derived from fitted growth curves incorporating perovskite solar expansion trajectories, automotive LiDAR adoption curves, and touchscreen manufacturing capacity forecasts. Industry-specific inputs included sputtering target utilization rates, aqueous ink qualification timelines at Korean panel makers, and IRA domestic content credit thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified chemical conglomerates or sudden indium stockpile policy shifts by Chinese regulators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Thermoelectric Materials Market