
 AI Inference Hardware Performance Benchmarking Test Systems Market | 2026-2036
AI Inference Hardware Performance Benchmarking Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
AI Inference Hardware Performance Benchmarking Test Systems Market Insights
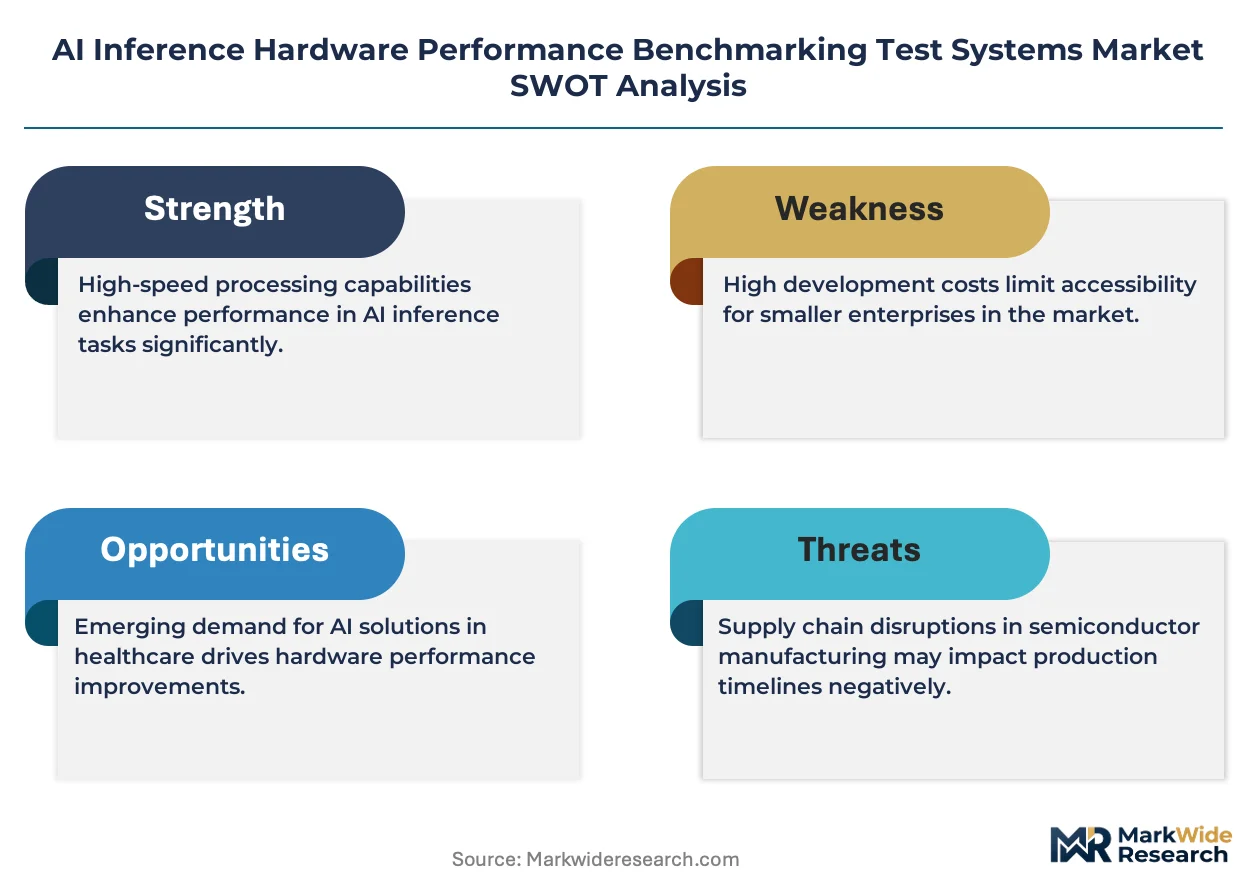
Taiwanese foundry capacity for advanced packaging is rebalancing how benchmarking test systems get provisioned across the supply chain. NVIDIA leverages its CUDA ecosystem dominance to shape inference benchmark standards that downstream equipment makers must follow. AMD sustains competitive pressure through open-source ROCm tooling that challenges proprietary benchmarking silos. Intel anchors its position with x86-compatible validation frameworks that appeal to enterprise datacenter operators seeking hardware-agnostic testing protocols.
AI Inference Hardware Performance Benchmarking Test Systems comprise instrumented measurement platforms that quantify throughput, latency, power efficiency, and accuracy degradation across neural network workloads on specialized accelerators, typically operating at nanosecond-level precision with thermal and electrical boundary condition control. These systems enable procurement decisions, certification workflows, and competitive product positioning in commercial and regulatory contexts. GPU-Based Systems occupy the largest installed base given NVIDIA's market presence, though ASIC-Based Systems represent the fastest-expanding category as custom silicon from cloud providers demands specialized validation rigs. Cloud-Based deployment mode is gaining share as hyperscalers distribute benchmark workloads across geographically dispersed infrastructure rather than maintaining captive on-premises labs.
FDA scrutiny of AI-enabled medical devices is elevating the importance of reproducible inference performance documentation for hardware submissions. The EU AI Act's conformity assessment requirements are pushing European technology vendors toward certified benchmarking protocols that demonstrate systemic risk mitigation. China's GB standards for AI product testing, administered by SAMR, create parallel compliance obligations for hardware sold into that market. Stakeholders must monitor how divergent regulatory benchmarking requirements fragment test system architectures or drive consolidation around interoperable standards.
Market Dynamics
Hyperscale cloud operators are internalizing validation workflows to compress deployment timelines for custom AI accelerators, forcing test system vendors to co-locate engineering teams with foundry ecosystems rather than shipping finished equipment.
Growth Catalysts
- EU AI Act conformity assessments:High-risk AI system classifications mandate documented inference performance validation, creating procurement pull for certified test rigs among European technology vendors.
- Advanced packaging node proliferation:Taiwan's Hsinchu Science Park foundry-tester collaboration tightens validation cycles for 3nm-class AI accelerators, reducing time-to-certification.
- FDA medical device submissions:Reproducible inference performance documentation requirements elevate hardware benchmarking from optional to mandatory for AI-enabled diagnostic equipment approvals.
Market Restraints
- Probe card and socket cost volatility:Advanced-node contactor assemblies for sub-7nm testing consume 40-60% of system bill-of-materials, with lead times extending when semiconductor capital equipment demand surges.
- Taiwanese foundry concentration:Single-geography dependency for CoWoS and InFO packaging validation creates supply vulnerability during seismic or geopolitical disruptions.
- GB standards fragmentation:China's SAMR-administered AI product testing protocols diverge from ISO/IEC frameworks, forcing redundant test system configurations for market access.
Strategic Opportunities
- Cloud-based benchmark distribution:Hyperscalers are migrating validation workloads from captive labs to geographically dispersed infrastructure, opening subscription revenue models for test system vendors.
- ASIC validation specialization:Custom silicon from cloud providers demands thermal-electrical boundary condition rigs that GPU-centric equipment cannot address, creating white space for purpose-built architectures.
- India PLI scheme leverage:Domestic semiconductor manufacturing incentives are attracting packaging and test equipment investments, enabling early-mover positioning for benchmark system deployment.
Industry Challenges
- Picosecond-precision signal integrity engineering:Advanced-node AI accelerators operate at clock frequencies where nanosecond-level measurement tolerance becomes inadequate, requiring scarce RF/mixed-signal hardware talent.
- Multi-jurisdiction certification parallelism:Simultaneous FDA, EU AI Act, and NMPA submission timelines force test system operators to maintain divergent documentation protocols and audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Inference Hardware Performance Benchmarking Test Systems Market |
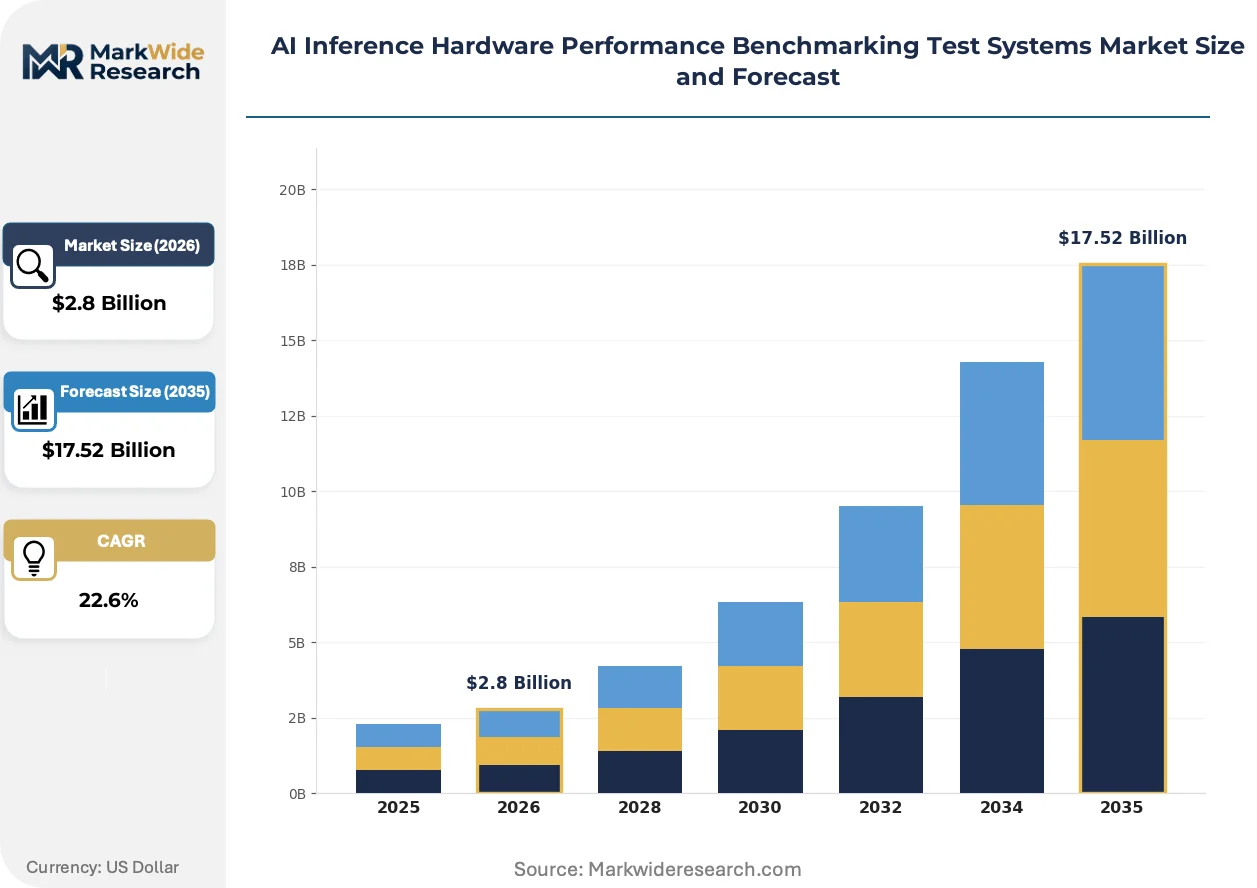
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.52 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPU-Based Systems, FPGA-Based Systems, ASIC-Based Systems, CPU-Based Systems, TPU-Based Systems Application: Natural Language Processing, Image Recognition, Autonomous Systems, Fraud Detection, Predictive Analytics End User Industry: Telecommunication Providers, Financial Institutions, Technology Vendors, Energy Operators, Automotive Suppliers Deployment Mode: On-Premises, Cloud-Based, Hybrid Deployment, Edge Deployment, Colocation Services |
| Companies Covered | NVIDIA, AMD, Intel, Qualcomm, Arm, Keysight Technologies, Amazon Web Services, Google Cloud, Microsoft Azure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Inference Hardware Performance Benchmarking Test Systems Market Trends and Innovations
Instrumentation architectures are bifurcating between general-purpose GPU validation platforms and highly specialized rigs for custom ASICs, with software-defined measurement layers enabling rapid reconfiguration across both categories.
Optical I/O characterization is expanding into inference benchmark suites as silicon photonics interconnects displace copper for intra-rack accelerator communication. Cloud providers deploying CPO-enabled clusters require test systems that validate optical link bit-error rates alongside traditional compute metrics. This convergence is compressing the validation timeline for next-generation training and inference fabrics.
The EU AI Act's risk-classification framework is mandating standardized performance disclosure protocols for high-stakes AI systems deployed in European markets. Hardware vendors must now submit reproducible inference latency and accuracy degradation documentation as part of conformity assessments. Test system providers are responding by embedding automated audit trail generation into their software stacks.
Buyer concentration among hyperscale operators is consolidating procurement authority into centralized technical sourcing teams with direct foundry relationships. Traditional distributor channels for test equipment are being disintermediated as cloud providers negotiate validation rig specifications directly with Taiwanese packaging houses. This pattern is most visible in the Hsinchu-Taichung corridor where co-development agreements now precede purchase orders.
AI Inference Hardware Performance Benchmarking Test Systems Market Segmentation
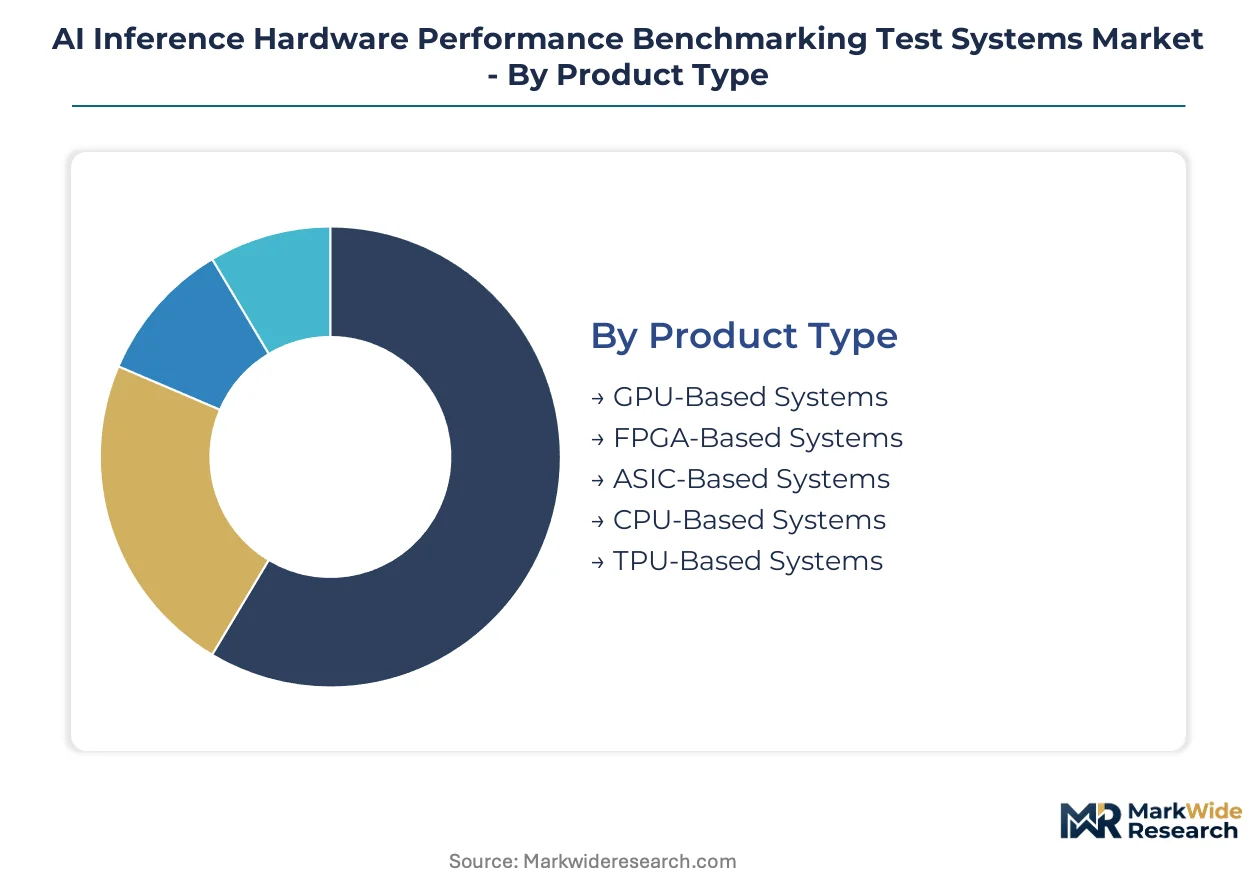
Segmentation in AI inference benchmarking reveals how validation requirements diverge across hardware architectures, workload types, and operational environments. Procurement patterns cluster around deployment constraints rather than raw performance metrics alone.
Product Type:
GPU-based systems anchor the installed base with mature software stacks, while ASIC-based rigs demand embedded thermal-electrical boundary control for custom silicon validation.
- GPU-Based Systems:These platforms leverage CUDA-compatible instrumentation to measure throughput and latency across NVIDIA's accelerator ecosystem. Demand concentrates in hyperscale cloud operator labs in Taiwan's Hsinchu Science Park, where foundry-tester collaboration compresses validation cycles for datacenter deployment. Thermal chamber integration and nanosecond-precision timing modules dominate system architecture.
- ASIC-Based Systems:Purpose-built rigs address custom silicon from cloud providers with specialized probe cards for sub-7nm nodes. Procurement is accelerating among hyperscalers internalizing validation workflows to bypass third-party bottlenecks. Power envelope characterization and signal integrity at picosecond precision distinguish these configurations from general-purpose alternatives.
- FPGA-Based Systems:Reconfigurable logic enables rapid benchmark adaptation for emerging neural network operators without hardware swaps.
- CPU-Based Systems:x86-compatible frameworks serve enterprise datacenter operators seeking hardware-agnostic validation protocols.
- TPU-Based Systems:Google-centric instrumentation supports tensor processing unit characterization for specific cloud provider ecosystems.
GPU-based systems lead volumes today; ASIC-based systems are gaining share fastest.
Application:
Natural language processing workloads drive peak memory bandwidth validation, whereas autonomous systems demand deterministic latency certification for safety-critical deployment.
- Natural Language Processing:Large language model inference requires sustained throughput measurement across trillion-parameter contexts with attention mechanism profiling. Financial institutions in Frankfurt and Singapore deploy these benchmarks for trading floor AI compliance under EU AI Act and MAS guidelines.
- Autonomous Systems:Real-time perception pipelines mandate worst-case latency bounding with thermal derating curves for automotive qualification. German KBA and US NHTSA submission timelines concentrate demand among Tier 1 automotive suppliers seeking pre-certified hardware documentation.
- Image Recognition:Convolutional neural network validation emphasizes accuracy degradation under quantized precision.
- Fraud Detection:Low-latency inference benchmarking supports real-time transaction scoring in payment networks.
- Predictive Analytics:Batch inference throughput measurement dominates enterprise software vendor procurement.
Natural language processing leads volumes today; autonomous systems are climbing the fastest.
End User Industry:
Technology vendors internalize validation to compress product cycles, while financial institutions outsource to certified third-party labs for regulatory documentation.
- Technology Vendors:Silicon designers and cloud operators maintain captive benchmarking infrastructure for competitive positioning and foundry qualification. Taiwan's Hsinchu-Taichung corridor concentrates procurement where co-development agreements with packaging houses precede purchase orders.
- Financial Institutions:Banks and payment processors demand reproducible audit trails for algorithmic trading and fraud detection hardware under SEC and ECB scrutiny. Subscription-based cloud benchmark services are displacing captive lab investments among mid-tier institutions.
- Telecommunication Providers:Edge AI deployment drives latency validation for radio access network optimization.
- Energy Operators:Grid management AI requires ruggedized thermal testing for substation deployment environments.
- Automotive Suppliers:Functional safety certification under ISO 26262 mandates deterministic inference benchmarking.
Technology vendors lead volumes today; financial institutions are expanding most quickly.
Deployment Mode:
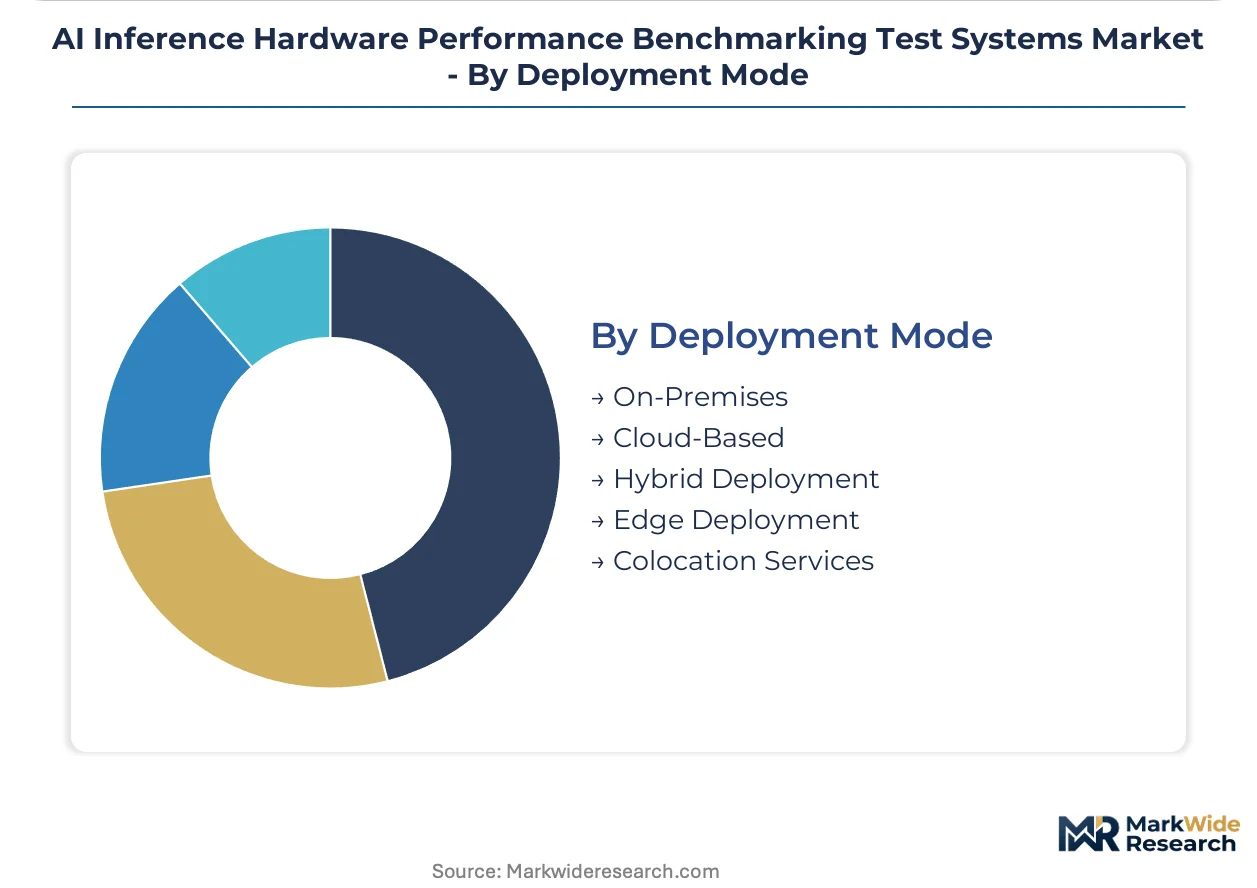
On-premises labs retain dominance for intellectual property protection, though cloud-based distribution is capturing share among geographically distributed engineering teams.
- Cloud-Based:Hyperscalers distribute benchmark workloads across geographically dispersed infrastructure rather than maintaining captive labs. AWS, Azure, and GCP internal teams negotiate validation specifications directly with Taiwanese foundries, disintermediating traditional equipment distributors.
- On-Premises:Captive facilities protect proprietary accelerator designs and enable picosecond-precision signal integrity engineering. Semiconductor designers in Israel, South Korea, and the US maintain these configurations for pre-tapeout verification.
- Hybrid Deployment:Split configurations reserve sensitive IP validation on-premises while outsourcing standardized workloads.
- Edge Deployment:Field-hardened rigs validate inference performance under environmental stress for remote installations.
- Colocation Services:Third-party datacenter hosting reduces capital burden for mid-size technology vendors.
On-premises deployment leads volumes today; cloud-based distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Validation infrastructure investment diverges sharply between the United States and Taiwan, with American hyperscalers internalizing benchmarking workflows while Taiwanese foundries concentrate advanced packaging validation in Hsinchu Science Park.
United States
FDA scrutiny of AI-enabled medical devices and NHTSA autonomous vehicle submissions drive demand for reproducible inference documentation. SEC disclosure requirements for algorithmic trading systems mandate certified hardware audit trails. Silicon Valley and Austin engineering clusters house captive validation labs where cloud providers pre-qualify accelerators before foundry tape-out.
Taiwan
CoWoS and InFO packaging concentration at TSMC creates unmatched validation rig demand for sub-7nm AI accelerators. The National Science and Technology Council coordinates foundry-tester collaboration protocols. Hsinchu Science Park facilities operate on compressed cycles where packaging houses and test system vendors share real-time thermal-electrical data.
China
SAMR-administered GB standards for AI product testing create parallel compliance obligations distinct from ISO/IEC frameworks. MIIT domestic semiconductor initiatives accelerate captive benchmarking infrastructure buildout. Shanghai and Beijing engineering centers maintain validation facilities serving both local cloud operators and NMPA medical device submissions.
Germany
KBA automotive certification timelines and EU AI Act conformity assessments concentrate demand among Tier 1 suppliers. The Federal Ministry for Economic Affairs funds semiconductor test equipment investments under European Chips Act implementation. Stuttgart and Munich automotive engineering clusters require deterministic latency validation for autonomous perception hardware.
South Korea
MFDS medical device AI regulations and Samsung's advanced packaging expansion drive specialized test rig procurement. The Ministry of Trade, Industry and Energy coordinates domestic foundry-benchmarking equipment partnerships. Seoul and Suwon engineering corridors house validation facilities serving both memory-integrated AI accelerators and automotive qualification workflows.
AI Inference Hardware Performance Benchmarking Test Systems Market Competitive Landscape
Taiwanese and American producers anchor distinct tiers in test system supply; European and Japanese specialists hold positions in precision instrumentation sub-segments. Market structure bifurcates between hyperscale-captive validation operations and merchant equipment vendors serving mid-tier technology firms. Three archetypes dominate: semiconductor foundry-integrated operations, cloud provider internal benchmarking divisions, and independent precision measurement specialists. Competitive dynamics center on co-development agreements with packaging houses and geographic co-location with foundry ecosystems.
Among American semiconductor and cloud operators, NVIDIA, AMD, and Intel occupy positions that exemplify divergent strategic approaches to benchmark standard-setting. NVIDIA represents the proprietary ecosystem archetype through CUDA-compatible instrumentation dominance. AMD exemplifies the open-source challenger position with ROCm tooling that resists vendor lock-in. Intel anchors the hardware-agnostic tier with x86-compatible frameworks appealing to enterprise datacenter operators. These three collectively shape downstream equipment specifications that Taiwanese and Japanese test system vendors must accommodate.
| Leading Market Players |
|---|
| NVIDIA |
| AMD |
| Intel |
| Qualcomm |
| Arm |
| Keysight Technologies |
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| Others |
Pricing and Supply Chain Analysis
Foundry-integrated test system vendors, many backed by Taiwanese family-owned industrial conglomerates, exercise pricing discipline through captive relationships with TSMC and ASE packaging houses. This ownership pattern concentrates supply-side bargaining power while insulating premium-tier pricing from commodity pressure.
Pricing Analysis
Capacity additions in South Korea and India are reshaping price floors for mid-tier GPU validation platforms. Three-tier pricing structure across premium, standard, and economy levels separates picosecond-precision ASIC rigs from general-purpose GPU systems from refurbished legacy equipment. Cost compression in standard-tier GPU benches is intensifying because hyperscalers are internalizing validation workflows. Cloud providers exhibit lowest price sensitivity; mid-tier semiconductor design houses face acute budget constraints.
Supply Chain Analysis
Freight costs for probe card assemblies and thermal chamber subsystems have amplified geographic sourcing decisions. Taiwan, Japan, and Germany anchor production for high-precision timing modules, ceramic substrates, and RF instrumentation respectively. Raw material dependencies span specialized ceramics, high-purity copper alloys, and photonic components. Single-source vulnerability concentrates in sub-7nm probe card manufacturing. Distribution runs through direct foundry partnerships rather than traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory certification requirements deepen hardware validation intensity across AI deployment contexts.
For Market Incumbents: Lock in co-development agreements with Hsinchu-Taichung packaging houses before competitor engineering teams establish beachheads. Deepen backward integration into probe card manufacturing to offset socket cost volatility. The threat of hyperscaler internal benchmarking divisions disintermediating merchant vendors demands preemptive channel control through direct foundry relationships. For New Entrants and Emerging Players: Capture white space in ASIC thermal-electrical boundary condition rigs where GPU-centric incumbents lack customization depth. India PLI scheme incentives offer the most penetrable geographic entry point for packaging-adjacent test equipment. Lead with subscription-based cloud benchmark services targeting mid-tier financial institutions seeking regulatory documentation without captive lab investment. For Investors and Strategic Acquirers: Valuations sit cheapest among precision instrumentation specialists with automotive qualification expertise but limited AI accelerator exposure. The five-to-ten year viability window favors acquisition targets with FDA and EU AI Act certification track records. Monitor NMPA submission timelines as an inflection indicator for China market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Co-Development Agreement | Tightens validation cycles for 3nm-class AI accelerators at TSMC Hsinchu facilities. |
| Cloud Benchmark Platform Launch | Enables subscription revenue from geographically dispersed hyperscaler engineering teams. |
| ASIC Validation Specialization | Addresses thermal-electrical boundary gaps that GPU-centric equipment cannot resolve. |
| Regulatory Certification Investment | Automates EU AI Act audit trail generation for conformity assessment workflows. |
| Optical I/O Characterization Suite | Validates silicon photonics bit-error rates for CPO-enabled training clusters. |
Research Methodology
Direct dialogue with test system engineering directors, hyperscaler infrastructure procurement leads, foundry packaging executives, and FDA regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from SEC hyperscaler capex disclosures, ETSI standardization documents, SAMR GB standard publications, and foundry earnings call transcripts. Bottom-up equipment shipment analysis triangulated against top-down AI accelerator wafer start projections.
Segmented outputs across hardware architecture type, deployment mode, and end-user industry classification structured the analytical framework throughout the projection horizon. CAGRs were derived from equipment procurement elasticity models calibrated to AI accelerator tape-out schedules. Forecast inputs incorporated EU AI Act implementation timelines and FDA medical device submission velocity.
Geopolitical disruption in Taiwan Strait shipping lanes, divergence between NMPA and FDA certification timelines, and hyperscaler vertical integration acceleration are the dominant revision risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Comparators Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Force Gauge Market
Test and Measurement
Rohs Tester Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Hour Meter Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market