
 Global Fluorescence Spectrophotometer Market | 2026-2036
Global Fluorescence Spectrophotometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorescence Spectrophotometer Market Foresight
Software-defined spectral analysis is shifting how fluorescence spectrophotometer vendors monetize hardware, with recurring revenue from cloud-connected calibration and remote diagnostics now bundled into instrument contracts. Thermo Fisher Scientific leverages its installed base of bench-top systems to lock in multi-year service agreements across North American pharmaceutical clients. Horiba Ltd. anchors its position in time-resolved fluorescence through proprietary picosecond detector technology that sustains premium pricing in academic consortia. PerkinElmer Inc. competes by extending its microplate reader software ecosystem into automated high-throughput screening workflows.
A fluorescence spectrophotometer measures emitted light intensity following sample excitation at specific wavelengths, typically operating across ultraviolet to near-infrared ranges with detection limits reaching picomolar concentrations for quantitative molecular analysis. Pharmaceutical testing commands the largest installed base among application segments, though environmental monitoring is gaining share as regulatory agencies mandate tighter pollutant detection thresholds. Bench-top systems dominate unit shipments but modular configurations are expanding fastest as laboratories prioritize reconfigurable optical paths for multi-modal experiments. Steady-state technology occupies the mature core of the market while time-resolved methods capture margin pools from advanced materials and life science research.
FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping features in instruments sold to US pharmaceutical end users, while EMA's analytical method validation guidelines under ICH Q2(R1) drive software qualification protocols across European installations. China's NMPA implementation of GB standards for analytical instrument performance is raising technical barriers for imported systems in domestic biotech laboratories. Stakeholders must monitor how evolving data integrity enforcement from multiple regulators simultaneously affects R&D prioritization and regional product configuration strategies.
Market Dynamics
Software-defined spectral analysis is compressing hardware margins while locking laboratories into recurring calibration and diagnostics subscriptions, fundamentally restructuring vendor revenue models across pharmaceutical and environmental testing segments.
Growth Catalysts
- EU MDR and IVDR frameworks:Tightened analytical instrument validation requirements across European member states are forcing testing laboratories to upgrade fluorescence systems with enhanced electronic record-keeping capabilities.
- China's biotech corridor expansion:Domestic contract research organizations around Shanghai are scaling analytical capabilities, driving concentrated demand for modular spectrophotometer configurations.
- Picomolar detection thresholds:Advances in detector sensitivity are opening quantitative molecular analysis applications in environmental pollutant monitoring where regulatory agencies mandate ever-tighter detection limits.
Market Restraints
- Optical component supply concentration:Specialized gratings and photomultiplier tubes rely on a limited supplier base concentrated in Germany and Japan, creating vulnerability to export control disruptions.
- High-purity solvent cost volatility:Reagent-grade solvents required for sample preparation experience price swings tied to petrochemical feedstock markets, squeezing operational budgets in high-throughput laboratories.
- Mass spectrometry substitution:LC-MS systems are capturing share in pharmaceutical impurity profiling where structural identification outweighs quantitative sensitivity requirements.
Strategic Opportunities
- India's pharmaceutical testing expansion:CDSCO's tightening quality control mandates for domestic drug manufacturers are creating instrument demand in Mumbai and Hyderabad manufacturing clusters.
- Cloud-connected calibration services:Remote diagnostics bundled with hardware contracts represent unmonetized recurring revenue streams that vendors can capture through subscription pricing models.
- Time-resolved fluorescence convergence:Integration with automated liquid handling platforms is opening high-throughput screening workflows in academic drug discovery consortia.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in picosecond detector design and optical path optimization remains concentrated among a narrow cohort of academic programs in the US and Germany.
- FDA 21 CFR Part 11 compliance timelines:Electronic record validation protocols extend sales cycles by six to twelve months for US pharmaceutical end users, compressing vendor cash conversion.
- Legacy system integration friction:Modular spectrophotometer configurations face compatibility barriers with established LIMS architectures in mature testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorescence Spectrophotometer Market |
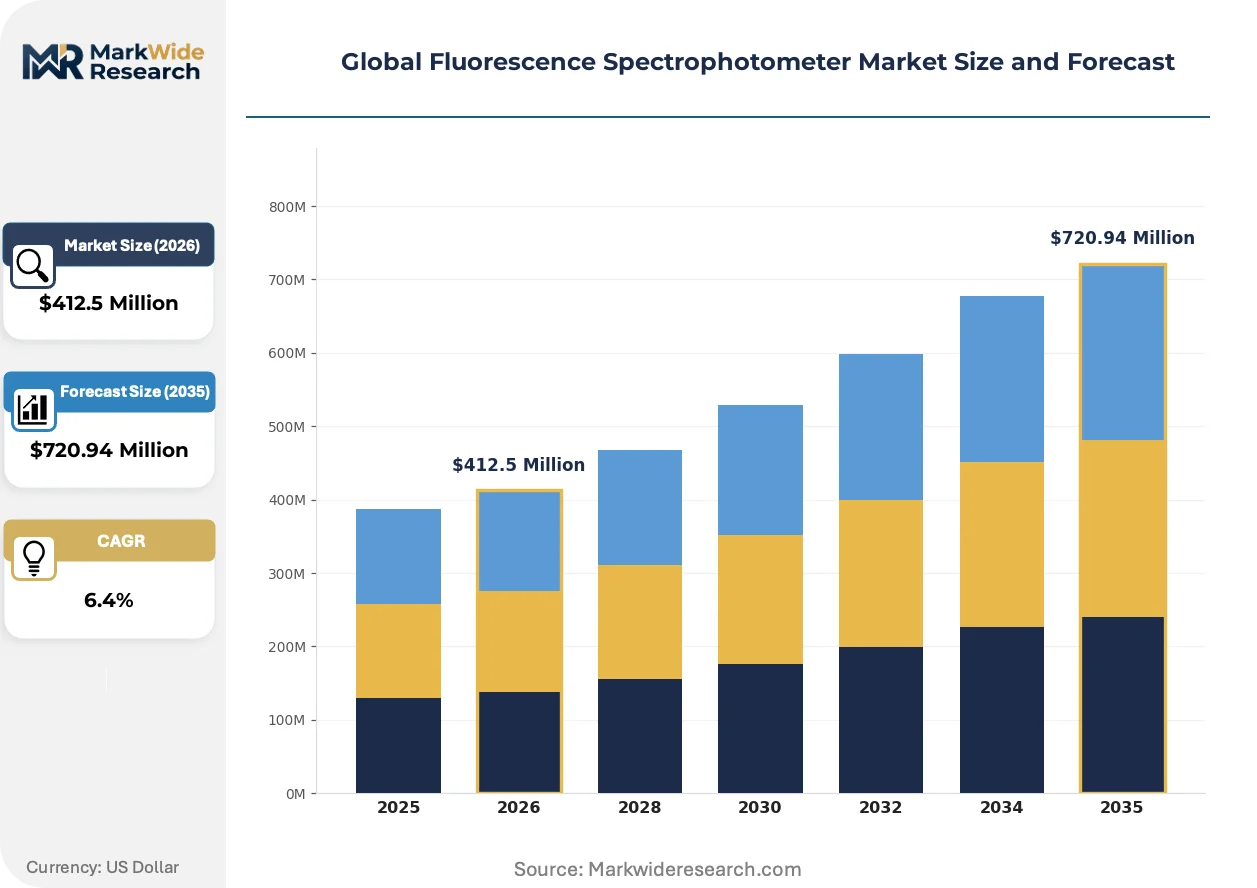
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-Top, Portable, Modular, Handheld, Microplate Reader Technology: Steady-State, Time-Resolved, Laser-Induced, Fluorescence Lifetime, Phase Modulation Application: Pharmaceutical Testing, Environmental Monitoring, Food Safety Analysis, Biochemical Research, Forensic Analysis End User: Research Institutes, Academic Laboratories, Biotechnology Firms, Chemical Companies, Forensic Labs |
| Companies Covered | Thermo Fisher Scientific Inc., Horiba Ltd., PerkinElmer Inc., Agilent Technologies Inc., Bruker Corporation, Shimadzu Corporation, Danaher Corporation, Edinburgh Instruments Ltd., JASCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorescence Spectrophotometer Market Shifts & Advancements
Fluorescence spectrophotometry is undergoing rapid instrumentation evolution as vendors compete to embed intelligence into optical systems and capture service revenue beyond hardware sales.
Time-resolved fluorescence detection is absorbing investment from steady-state instrument architectures as materials science and life science research demand picosecond-scale kinetic resolution. Academic consortia in Germany and Japan are adopting these systems fastest, with procurement concentrated in multi-instrument core facilities. The technology is absorbing margin pools that previously supported premium steady-state configurations, compressing pricing power in the mature instrument tier.
EMA's analytical method validation guidelines under ICH Q2(R1) are mandating enhanced software qualification protocols for European installations. Pharmaceutical testing laboratories must now demonstrate traceable calibration histories and automated audit trails, forcing vendors to re-engineer firmware architectures. European member states are responding with accelerated replacement cycles as legacy systems fail compliance audits.
Service unbundling is fragmenting traditional instrument sales into discrete hardware, calibration, and remote diagnostics contracts. North American pharmaceutical buyers are negotiating multi-year service agreements separately from capital purchases, shifting vendor relationships from transactional to recurring revenue models. This pattern is most visible in Boston and San Diego biotech clusters where procurement functions centralize spend across instrument fleets.
Global Fluorescence Spectrophotometer Market Segmentation
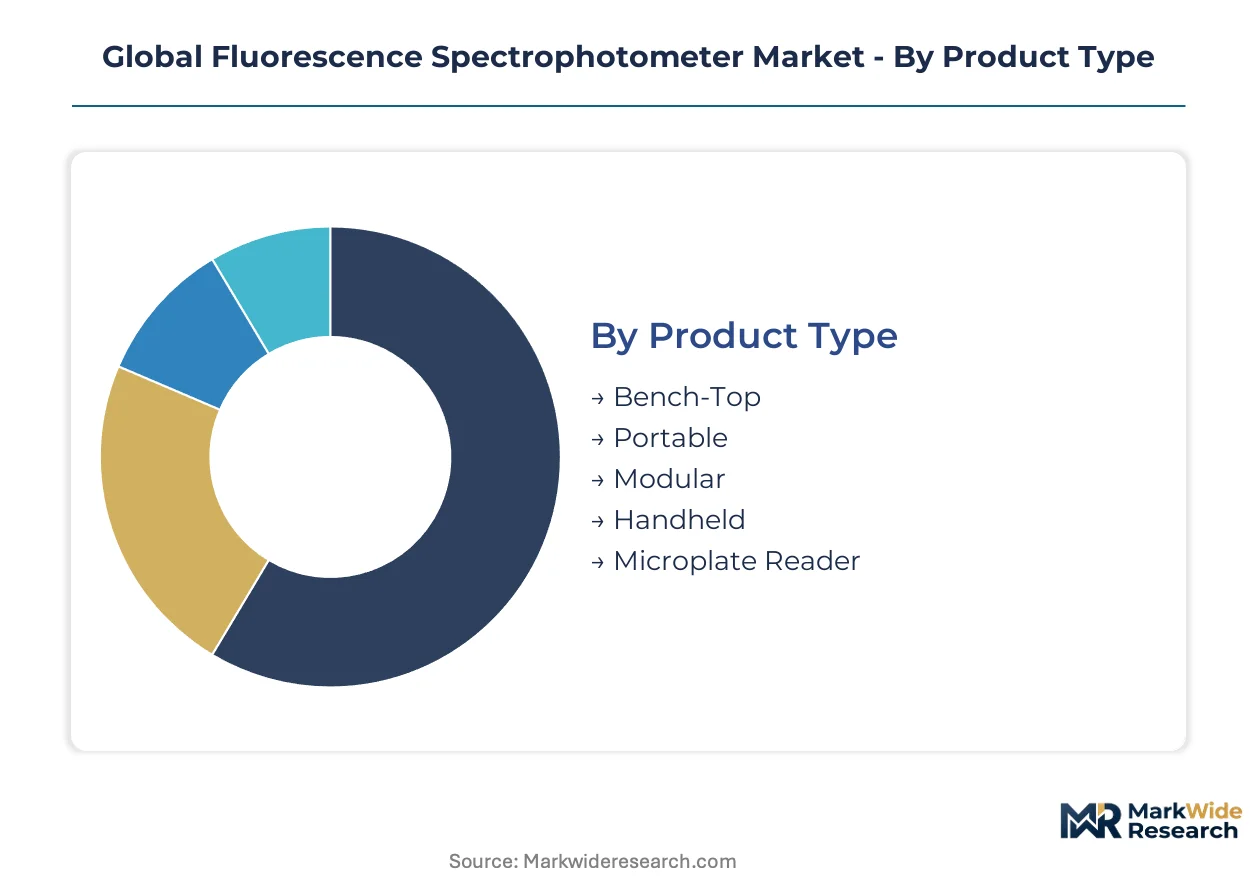
Fluorescence spectrophotometer purchasing patterns split sharply between high-volume routine testing and premium research-grade instrumentation. Vendors configure optical architectures, detector sensitivity, and software ecosystems differently across these tiers to capture divergent budget cycles and compliance requirements.
Product Type:
Bench-top systems dominate unit shipments through pharmaceutical quality control workflows, while modular configurations command attention from multi-modal research facilities seeking optical reconfigurability.
- Bench-Top:Fixed optical path instruments with integrated excitation sources and photomultiplier detection serve high-throughput pharmaceutical testing laboratories in Germany and the United States. Thermo Fisher Scientific leverages installed base density here to lock in multi-year calibration service contracts across North American clients.
- Modular:Reconfigurable optical benches with interchangeable gratings, detectors, and sample compartments attract academic consortia running multi-modal experiments. Demand concentrates in China's Shanghai biotech corridor as domestic CROs scale analytical capabilities beyond standard assays.
- Portable:Battery-powered units with solid-state excitation suit field environmental monitoring where EPA and EEA mandate tighter pollutant detection thresholds.
- Handheld:Single-wavelength excitation devices target rapid screening applications in food safety inspections.
- Microplate Reader:High-density sample formats integrate with automated liquid handling for drug discovery workflows.
Today's leader: Bench-Top. Tomorrow's challenger: Modular.
Technology:
Steady-state architectures anchor commercial volume, but time-resolved methods extract premium pricing from materials science and life science research demanding kinetic resolution.
- Steady-State:Continuous-wave excitation with synchronous emission detection forms the mature core of pharmaceutical quality control. FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping features in instruments sold to US pharmaceutical end users, extending replacement cycles.
- Time-Resolved:Picosecond-scale pulsed excitation with gated detection captures fluorescence decay kinetics for advanced materials characterization. Horiba Ltd. anchors market position here through proprietary detector technology that sustains premium pricing in German and Japanese academic consortia.
- Laser-Induced:High-intensity monochromatic excitation enables single-molecule detection sensitivity for specialized biochemical applications.
- Fluorescence Lifetime:Quantitative decay curve analysis supports Förster resonance energy transfer studies in protein interaction research.
- Phase Modulation:Frequency-domain lifetime measurements offer alternative kinetic resolution with simpler instrumentation than time-domain methods.
Steady-state retains volume dominance; time-resolved climbs the fastest on research premiumization.
Application:
Pharmaceutical testing commands the largest installed base, though environmental monitoring gains regulatory tailwind from tightening detection mandates.
- Pharmaceutical Testing:Active ingredient quantification, impurity profiling, and dissolution testing drive instrument deployment in QC laboratories. EMA's analytical method validation guidelines under ICH Q2(R1) force software qualification protocol upgrades across European installations.
- Environmental Monitoring:Trace pollutant detection in water and soil samples accelerates as China's MEE and the US EPA lower permissible concentration thresholds. Picomolar detection limits now enable quantitative analysis of persistent organic compounds previously below measurable range.
- Food Safety Analysis:Mycotoxin and allergen screening applications expand with FSSAI and EFSA tightening contamination limits.
- Biochemical Research:Protein folding, enzyme kinetics, and membrane dynamics studies utilize intrinsic and extrinsic fluorophores.
- Forensic Analysis:Latent fingerprint visualization and questioned document examination employ specialized excitation wavelengths.
Pharmaceutical testing anchors current revenue; environmental monitoring shows steepest expansion trajectory.
End User:
Procurement authority concentrates in centralized core facilities rather than distributed individual laboratories, reshaping vendor sales approaches.
- Research Institutes:Multi-instrument core facilities in Germany and Japan consolidate time-resolved fluorescence procurement for shared access across materials science and life science departments. Photonics engineering talent scarcity in picosecond detector design limits competitive vendor entry.
- Biotechnology Firms:Boston and San Diego clusters negotiate fleet-wide service agreements separate from capital purchases, shifting vendor relationships toward recurring revenue models.
- Academic Laboratories:Individual PI laboratories with constrained capital budgets favor entry-level steady-state configurations.
- Chemical Companies:Process analytical technology applications integrate fluorescence sensors into manufacturing lines.
- Forensic Labs:Government-funded facilities in the United States and United Kingdom standardize on validated protocols for evidentiary reliability.
Research institutes dominate premium tier procurement; biotechnology firms reshape contract structures toward subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical testing laboratories outpace China's domestic CROs in fluorescence spectrophotometer density per facility, though Shanghai's biotech corridor is closing the gap through accelerated analytical capability investments.
United States
FDA 21 CFR Part 11 compliance mandates reshape electronic record-keeping requirements for pharmaceutical quality control laboratories. Boston and San Diego biotech clusters negotiate fleet-wide service agreements that shift vendor relationships toward subscription economics. Environmental monitoring applications expand as the EPA tightens pollutant detection thresholds for water and soil analysis.
Germany
EMA's analytical method validation guidelines under ICH Q2(R1) force software qualification protocol upgrades across European pharmaceutical installations. Munich and Heidelberg academic consortia consolidate time-resolved fluorescence procurement in multi-instrument core facilities. The EU MDR framework tightens analytical instrument validation requirements, accelerating replacement cycles for legacy systems.
China
NMPA implementation of GB standards for analytical instrument performance raises technical barriers for imported systems in domestic biotech laboratories. Shanghai's biotech corridor concentrates demand as domestic CROs scale analytical capabilities beyond standard assays. The country's MEE lowers permissible concentration thresholds for environmental pollutant detection, expanding fluorescence spectrophotometer deployment in water monitoring stations.
Japan
METI funding for advanced materials research channels investment toward picosecond-scale kinetic resolution instrumentation. Tokyo and Osaka academic institutions anchor demand for time-resolved fluorescence systems in shared-access core facilities. Domestic photonics engineering expertise in detector design sustains competitive positioning in premium research-grade segments.
India
CDSCO tightening of quality control mandates for domestic drug manufacturers creates instrument demand in pharmaceutical testing workflows. Mumbai and Hyderabad manufacturing clusters scale analytical capabilities to meet export compliance requirements. FSSAI contamination limit revisions for food safety expand fluorescence-based mycotoxin screening applications.
Global Fluorescence Spectrophotometer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated leadership in premium research-grade systems and fragmented competition in routine pharmaceutical testing configurations. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with integrated service ecosystems, precision optics specialists with captive detector technology, and analytical platform vendors with software-centric recurring revenue models. Competitive positioning hardens through multi-year calibration service bundling and cloud-connected remote diagnostics integration rather than hardware differentiation alone.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify scale-driven platform strategies that leverage installed base density to capture recurring service revenue. Horiba Ltd. and Edinburgh Instruments Ltd. occupy specialist positions anchored in proprietary optical component expertise. PerkinElmer Inc. and Agilent Technologies Inc. represent analytical platform vendors extending software ecosystems into automated workflow integration. Bruker Corporation and Shimadzu Corporation sit within the precision instrumentation archetype with heritage in detector engineering and optical path optimization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Horiba Ltd. |
| PerkinElmer Inc. |
| Agilent Technologies Inc. |
| Bruker Corporation |
| Shimadzu Corporation |
| Danaher Corporation |
| Edinburgh Instruments Ltd. |
| JASCO Corporation |
| Others |
Supply & Pricing Matrix
Family-owned precision optics specialists in Germany and Japan anchor the upper tier of fluorescence spectrophotometer manufacturing, their multi-generational balance sheets enabling patient capital allocation toward captive detector development that sustains premium pricing power against private-equity-rolled contract manufacturers competing on volume.
Pricing Analysis
Capacity additions in China's analytical instrument sector are reshaping price floors for entry-level steady-state systems, compressing margins on standardized configurations while time-resolved platforms sustain three-tier pricing structure across premium, standard, and economy levels based on detector sensitivity grades and FDA 21 CFR Part 11 software certification tiers. Price differentiation hinges on picosecond resolution capability and bundled calibration service contracts. Cost compression in bench-top segments is intensifying because domestic CROs in Shanghai negotiate fleet discounts. Academic laboratories in India and Southeast Asia exhibit highest price sensitivity; German pharmaceutical QC labs show least.
Supply Chain Analysis
China's GB standards implementation and India's phased manufacturing program are reshaping sourcing patterns for imported optical subassemblies, pushing multinational vendors toward joint ventures with domestic fabricators. Specialized photomultiplier tubes and ruled diffraction gratings draw from concentrated production in Japan, Germany, and the United States. Supply chain risk centers on single-source vulnerability for picosecond detector modules from Tokyo and Osaka engineering houses. Distribution runs through authorized service networks that bundle installation qualification with hardware delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorescence spectrophotometry has entered a late-cycle quality phase where instrument buyers prioritize picomolar detection thresholds and validated electronic records over unit cost, concentrating procurement authority in core facilities with multi-year service budgets.
For Market Incumbents: Cement recurring revenue lock-in by extending cloud-connected calibration subscriptions to installed bases of bench-top systems in North American pharmaceutical clusters, while deepening backward integration into photomultiplier tube supply through exclusive partnerships with Hamamatsu and Hamamatsu-class Japanese detector houses to defend against mass spectrometry substitution in impurity profiling workflows. For New Entrants and Emerging Players: Launch via modular configuration sales targeting China's Shanghai biotech corridor CROs, which seek reconfigurable optical paths without legacy LIMS integration burdens. White-space sits in portable environmental monitoring units for EPA-mandated water testing stations and handheld food safety devices for FSSAI compliance in Indian state laboratories. Go-to-market should emphasize rapid deployment without validation protocol delays. For Investors and Strategic Acquirers: Valuations sit cheapest among precision optics specialists with captive picosecond detector technology and established academic consortia relationships. Long-term viability frames around 5-10 year service contract visibility rather than hardware replacement cycles. Target acquisition profile encompasses German and Japanese mid-caps with proprietary optical benches and undermonetized remote diagnostics capabilities. Watch NMPA enforcement of GB standards for imported instruments as inflection signal on China market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Service Launch | Transforms transactional hardware sales into multi-year recurring revenue streams across FDA-regulated pharmaceutical laboratories. |
| Picosecond Detector Technology Acquisition | Secures proprietary kinetic resolution capability that sustains premium pricing in German and Japanese academic core facilities. |
| Modular Configuration Platform Expansion | Captures demand from Shanghai CROs scaling beyond standard assays into multi-modal fluorescence experiments. |
| Environmental Monitoring Application Development | Aligns with EPA and China MEE tightening of pollutant detection thresholds in water and soil analysis protocols. |
| India Pharmaceutical Testing Market Entry | Addresses CDSCO quality control mandates driving instrument demand in Mumbai and Hyderabad manufacturing clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with analytical instrument procurement managers at pharmaceutical QC laboratories, core facility directors at German and Japanese research institutes, and fluorescence spectrophotometer service heads at North American biotech firms with secondary validation against SEC 10-K filings, NMPA registration databases, and EMA analytical method validation guidance documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Historical reference periods anchored the forecast window through verified replacement cycle data and regulatory compliance deadline clustering across the analysis window. Segmentation dimensions modeled include product architecture, detection technology tier, application workflow, and end-user procurement authority concentration. CAGRs derived from instrument shipment trajectories weighted by average selling price evolution and service contract attachment rates. Industry-specific inputs encompassed photonics engineering graduate pipeline data and regulatory inspection citation frequencies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control disruption scenarios affecting German and Japanese optical component flows. Forecasts reflect assumptions regarding steady-state to time-resolved technology mix shifts and China domestic CRO capital expenditure continuity. Regulatory enforcement intensity from FDA, EMA, and NMPA represents primary revision trigger. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market