
 Asia-Pacific Digital Oilfield Market | 2026-2036
Asia-Pacific Digital Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Oilfield Market Outlook
Carbon steel sensor housings is hardening as the dominant material choice for downhole monitoring equipment in high-pressure, high-temperature reservoirs. SLB leverages its integrated drilling and evaluation portfolio to anchor digital twin deployments across Southeast Asian offshore concessions. Baker Hughes competes through proprietary fiber-optic sensing systems that sustain real-time reservoir surveillance in China's Tarim Basin.
Asia-Pacific digital oilfield denotes the convergence of automation, data analytics, and networked instrumentation applied to hydrocarbon exploration, production, and reservoir management, typically operating at pressures exceeding 15,000 psi and temperatures above 175°C to enable remote operational command. The primary purpose centers on maximizing recovery factors while minimizing unplanned downtime in maturing basins. Monitoring Solutions currently occupies the largest product category share as operators prioritize well integrity and pipeline surveillance across Indonesia's aging infrastructure. Machine Learning represents the fastest-expanding technology segment, with predictive maintenance algorithms displacing scheduled intervention programs in Australian LNG train operations. Production Optimization commands the dominant application margin pool, particularly where artificial lift automation intersects with declining reservoir pressure regimes.
China's MIIT issues mandatory industrial IoT connectivity standards for state-owned energy assets, while Australia's NOPSEMA enforces functional safety requirements for offshore digital control systems. The EU AI Act's extraterritorial reach shapes vendor qualification protocols for European-headquartered service providers operating across Asia-Pacific concessions. Stakeholders must weigh sovereign data localization mandates against cross-border cloud architecture efficiency when architecting regional digital oilfield platforms.
Market Dynamics
China's MIIT mandates for industrial IoT connectivity on state-owned energy assets are compressing deployment timelines across Sichuan Basin shale operations and Tarim Basin deep reservoirs, forcing vendors to pre-certify hardware against sovereign data localization requirements.
Growth Catalysts
- Dual Carbon Goals:China's national emissions targets are accelerating sensor deployment across aging onshore fields to optimize recovery rates and minimize venting.
- Subsea Infrastructure Aging:Australia's North West Shelf operators are replacing manual well intervention with automated monitoring to sustain plateau production.
- Fiber-Optic Telemetry:Real-time distributed temperature sensing is penetrating high-pressure reservoirs previously inaccessible to conventional electronics.
Market Restraints
- Carbon Steel Supply Concentration:Downhole housing fabrication depends on a narrow supplier base concentrated in East Asian foundries, exposing procurement to input cost volatility.
- Hydrogen Sulfide Compatibility:Sour gas reservoirs in Southeast Asia impose material limitations that disqualify standard sensor alloys, forcing expensive custom metallurgy.
- Cross-Border Data Friction:Australia's data sovereignty frameworks conflict with cloud architectures optimized for regional headquarters in Singapore, fragmenting platform design.
Strategic Opportunities
- Indonesia's Mature Infrastructure:Pipeline integrity monitoring remains underpenetrated across Sumatra's aging trunk lines, creating whitespace for predictive corrosion analytics.
- AI-Edge Convergence:On-device machine learning inference at wellhead locations is opening new service models that bypass latency constraints of centralized processing.
- Malaysia's Digital Incentives:Tax credits for Industry 4.0 capital expenditure are lowering adoption barriers for independent operators in offshore Peninsular blocks.
Industry Challenges
- Petrotechnical Talent Scarcity:Data science competency gaps persist among field engineering teams in Australia's remote offshore facilities, delaying algorithm deployment.
- Legacy SCADA Integration:Brownfield facilities across Southeast Asia require costly protocol translation layers to connect 1990s-era control systems to modern IoT platforms.
- Functional Safety Certification:Australia's NOPSEMA mandates for SIL-rated digital controls extend vendor qualification timelines by 12-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Oilfield Market |
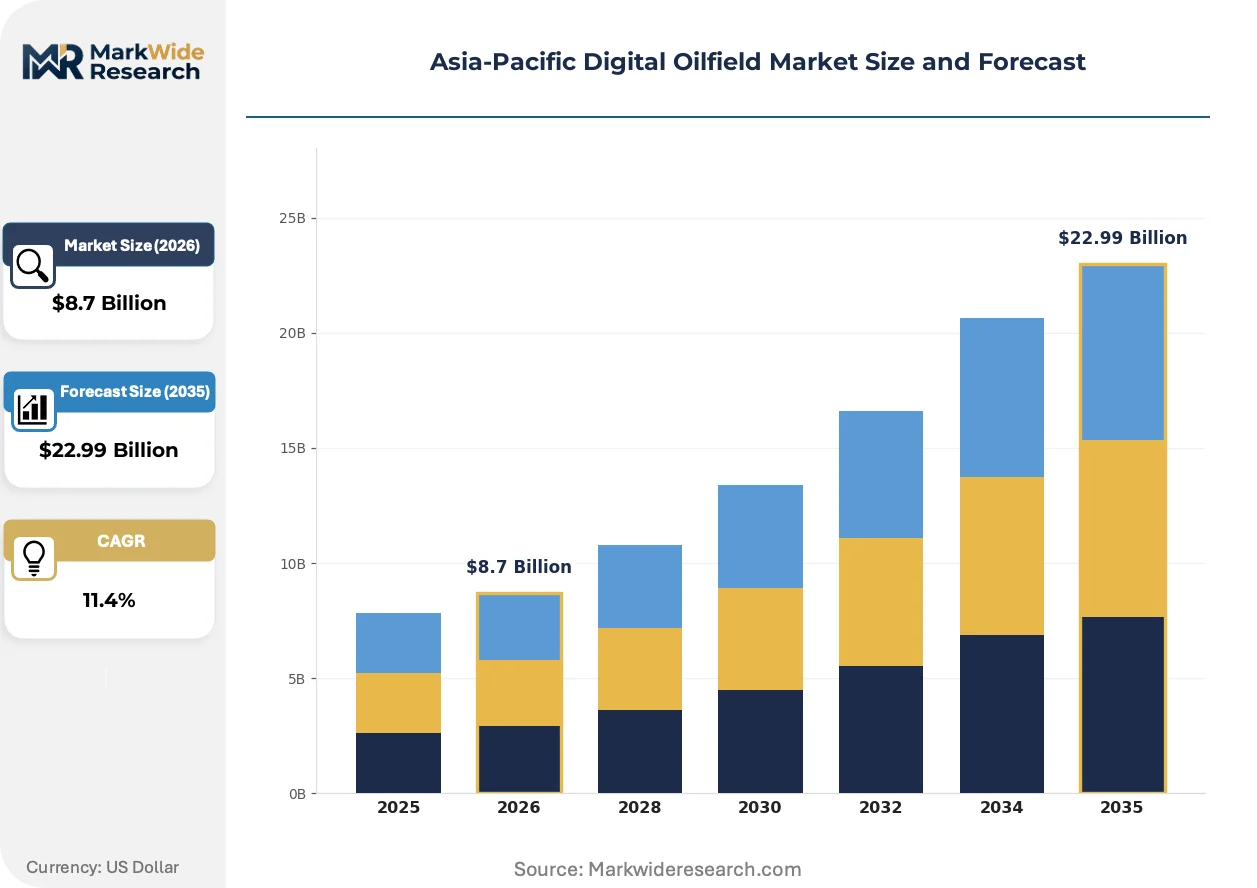
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management Software, Automation Tools, Monitoring Solutions, Visualization Software Technology: IoT Solutions, Big Data Analytics, Cloud Computing, Machine Learning End User: Oilfield Operators, Service Providers, Equipment Manufacturers, Consultants Application: Production Optimization, Asset Management, Risk Management, Environmental Monitoring |
| Companies Covered | Weatherford, Emerson, SLB, PetroChina, ABB, Halliburton, Siemens, Schlumberger, Baker Hughes, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Oilfield Market Strategic Shifts
Edge computing architectures are collapsing the latency gap between subsurface sensing and surface decision-making, enabling autonomous well responses that were previously gated by satellite bandwidth constraints.
Carbon steel sensor housings are overtaking exotic alloy alternatives in HPHT reservoir applications by delivering comparable pressure containment at 40% lower unit cost. Australian offshore operators are standardizing on these housings for new subsea completions. This cost compression is overtaking historical material specifications that prioritized corrosion resistance over capital efficiency.
China's MIIT industrial IoT connectivity standards are mandating domestic encryption protocols for all state-owned energy assets. Vendors must re-engineer firmware to satisfy GB/T cryptographic requirements before hardware deployment. The Sichuan Basin shale segment is absorbing the longest compliance timelines due to simultaneous cybersecurity and functional safety audits.
Buyer procurement patterns are fragmenting as national oil companies unbundle digital service contracts from integrated drilling packages. Independent software vendors are capturing standalone analytics contracts that previously flowed to field service majors. This disintermediation is most visible in Indonesia, where Pertamina's digital transformation program favors modular vendor selection over single-source accountability.
Asia-Pacific Digital Oilfield Market Segmentation
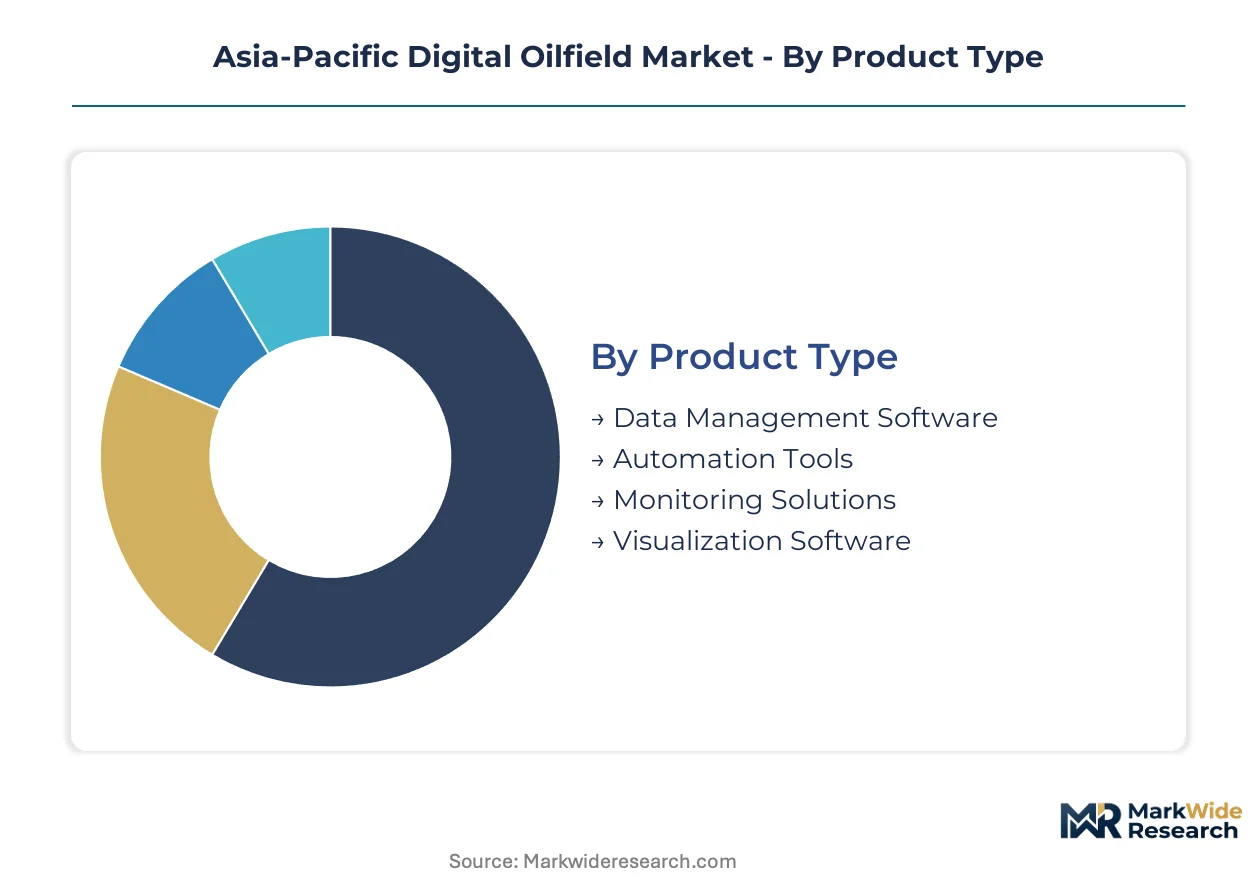
Segmentation in the Asia-Pacific digital oilfield market reveals divergent technology maturity across product categories and end-user sophistication. Understanding these divides exposes where procurement budgets concentrate and which deployment models vendors must architect.
Product Type:
Volume leadership sits with established infrastructure categories, while premium pricing attaches to software layers that integrate disparate hardware systems.
- Monitoring Solutions:Encompasses downhole pressure gauges, pipeline surveillance sensors, and subsea instrumentation packages. Demand concentrates across Indonesia's aging trunk lines and Australia's North West Shelf, where well integrity mandates from NOPSEMA force continuous surveillance investment.
- Data Management Software:Centralizes reservoir characterization, production accounting, and regulatory reporting workflows. China's Sichuan Basin shale operators are prioritizing domestic-certified platforms that satisfy MIIT data localization requirements while handling multi-pad drilling datasets.
- Automation Tools:Artificial lift controllers and wellhead valve actuators that execute setpoint adjustments without operator intervention.
- Visualization Software:3D reservoir modeling and real-time drilling dashboards deployed in collaborative decision centers.
Mature deployment sits with Monitoring Solutions. Newer deployment is concentrated in Data Management Software.
Technology:
Adoption timelines split between connectivity infrastructure requiring capital-intensive field installation and algorithmic layers deployable through software licenses.
- Machine Learning:Predictive maintenance models trained on historical failure signatures and production optimization algorithms that adjust choke settings autonomously. Australian LNG train operators are displacing scheduled maintenance programs with condition-based interventions, compressing unplanned downtime intervals.
- IoT Solutions:Edge devices, wireless telemetry networks, and protocol gateways bridging field instrumentation to enterprise systems. China's MIIT mandates for industrial IoT connectivity are accelerating deployment across Tarim Basin state-owned assets, though GB/T cryptographic compliance extends qualification cycles.
- Big Data Analytics:Reservoir simulation acceleration and pattern recognition across multi-variate production datasets.
- Cloud Computing:Scalable compute resources for seismic processing and centralized data lakes accessible to distributed engineering teams.
Established infrastructure dominates IoT Solutions. Machine Learning is gaining share fastest as operator confidence in algorithmic recommendations hardens.
End User:
Procurement authority fragments as national oil companies unbundle integrated service contracts, creating entry points for specialized vendors.
- Oilfield Operators:National oil companies and international oil companies holding exploration and production licenses. Pertamina's digital transformation program in Indonesia favors modular vendor selection over single-source accountability, opening standalone analytics contracts to independent software vendors.
- Service Providers:Drilling contractors and well intervention specialists deploying digital tools as competitive differentiators. These firms face compressed margins when operators push digital costs onto day-rate structures rather than separate technology line items.
- Equipment Manufacturers:Original equipment suppliers embedding sensors and connectivity into capital equipment prior to field delivery.
- Consultants:Advisory firms architecting digital roadmaps and managing vendor qualification processes for resource-constrained independents.
Contract concentration remains with Oilfield Operators. Service Providers are expanding digital capabilities fastest to defend rig market share.
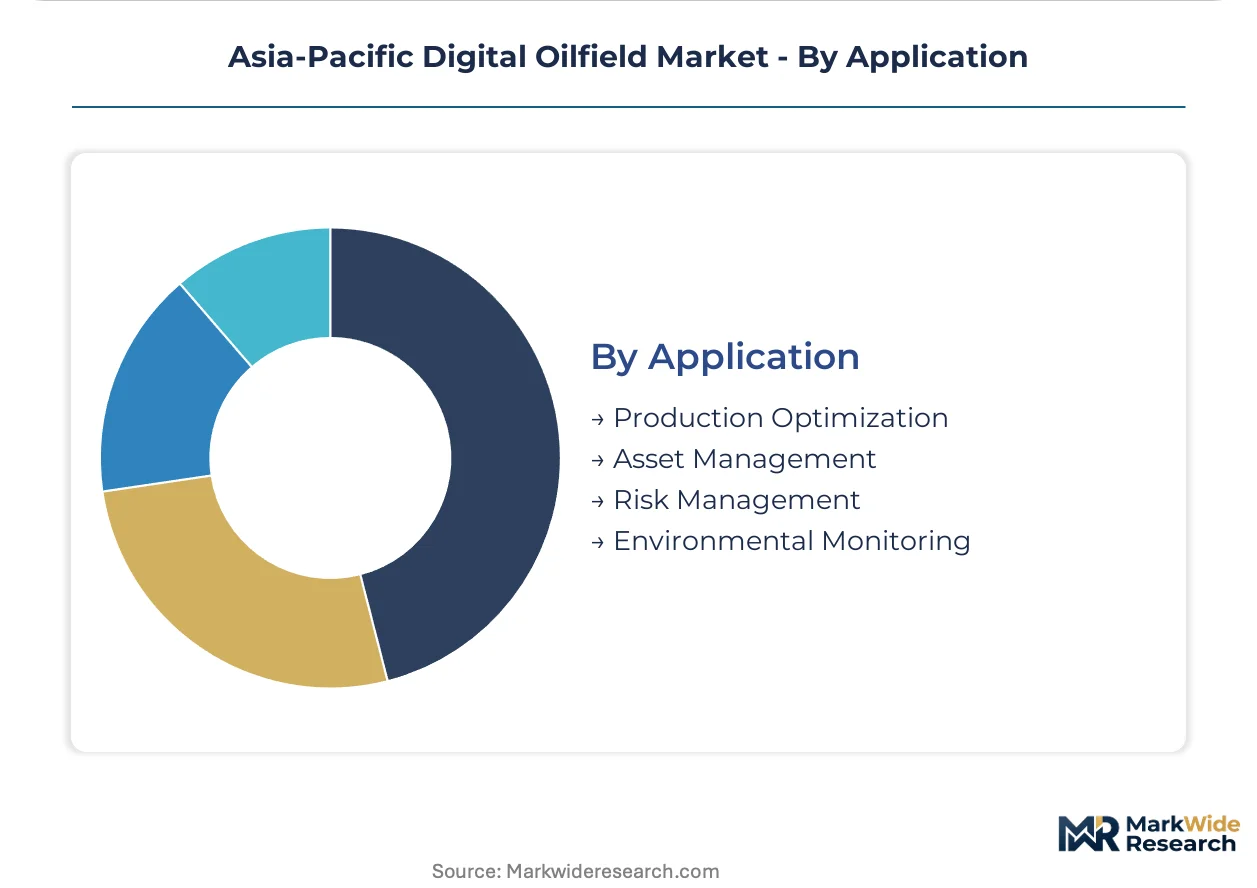
Application:
Margin capture aligns with applications directly tied to hydrocarbon recovery rates rather than compliance or administrative functions.
- Production Optimization:Artificial lift automation, choke management, and gas-lift optimization that sustains plateau rates in declining reservoirs. Australia's North West Shelf deepwater projects command the dominant margin pool where artificial lift automation intersects with depressurizing formations.
- Asset Management:Equipment reliability tracking, spare parts forecasting, and maintenance scheduling across distributed facilities. Malaysia's offshore Peninsular blocks are absorbing expanded deployment as Industry 4.0 tax credits lower adoption barriers for independents.
- Risk Management:Blowout preventer monitoring, well control simulation, and emergency shutdown system verification.
- Environmental Monitoring:Methane detection, produced water quality tracking, and emissions reporting automation.
Production Optimization holds established deployment depth. Environmental Monitoring is climbing the fastest as China's dual carbon goals harden venting penalties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for digital oilfield solutions concentrates in China's shale basins and Australia's deepwater provinces, where state mandates and production decline curves intersect to force technology adoption.
China
Sichuan Basin shale operators deploy downhole monitoring under MIIT industrial IoT mandates that compress procurement timelines. GB/T cryptographic standards require domestic firmware re-engineering, extending vendor qualification cycles. Tarim Basin deep reservoirs absorb the longest compliance timelines due to simultaneous cybersecurity and functional safety audits.
Australia
North West Shelf operators replace manual well intervention with automated monitoring to sustain plateau production in aging subsea infrastructure. NOPSEMA enforces SIL-rated functional safety requirements for offshore digital control systems. Perth-based engineering clusters coordinate deployment of fiber-optic sensing systems across the continental shelf.
Indonesia
Pertamina's digital transformation program favors modular vendor selection over single-source accountability, opening standalone analytics contracts. Pipeline integrity monitoring remains underpenetrated across Sumatra's aging trunk lines. Jakarta-headquartered procurement teams prioritize predictive corrosion analytics for brownfield infrastructure.
Malaysia
Tax credits for Industry 4.0 capital expenditure lower adoption barriers for independent operators in offshore Peninsular blocks. Asset management applications expand across distributed facilities as margin-conscious independents automate equipment reliability tracking. Kuala Lumpur serves as the regional hub for vendor qualification and platform architecture.
Japan
Technology licensing partnerships connect domestic automation specialists to Southeast Asian offshore concessions. METI industrial digitization guidelines shape vendor selection criteria for Japanese engineering contractors operating abroad. Osaka-based sensor manufacturers supply telemetry hardware for high-pressure reservoir applications.
Asia-Pacific Digital Oilfield Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service majors anchoring bundled drilling-and-digital packages while independent software vendors capture unbundled analytics contracts. The vendor base organizes around three archetypes: full-service portfolio holders, component specialists with sensing expertise, and national oil company affiliates with captive demand access. Competitive intensity manifests through M&A activity targeting predictive analytics capabilities and strategic partnerships bridging legacy SCADA systems to cloud-native architectures.
Within the integrated service tier, SLB and Baker Hughes exemplify divergent positioning strategies—SLB anchors digital twin deployments through drilling portfolio integration, while Baker Hughes occupies a position emphasizing proprietary fiber-optic sensing systems for real-time reservoir surveillance. Halliburton represents the scale-driven archetype with artificial lift automation intersecting production optimization workflows. Among state-affiliated entities, PetroChina sits within a distinct category where sovereign data localization requirements create captive demand for domestically certified platforms.
| Leading Market Players |
|---|
| Weatherford |
| Emerson |
| SLB |
| PetroChina |
| ABB |
| Halliburton |
| Siemens |
| Schlumberger |
| Baker Hughes |
| Others |
Value Chain & Pricing Dynamics
Petrotechnical talent clusters in Perth and Singapore compress labor-cost differentials between premium digital twin deployments and standard monitoring packages, widening pricing-tier spreads as vendors pass through certification premiums for GB/T-compliant firmware engineering.
Pricing Analysis
Volume leadership concentrates in standardized IoT sensor hardware while margin capture sits with integrated software layers. Three-tier pricing structure across premium, standard, and economy levels separates SIL-rated subsea systems from onshore SCADA retrofits and basic telemetry modules. Price differentiation hinges on GB/T cryptographic certification grade and after-sales service bundling. Cost compression in economy-tier hardware is intensifying because carbon steel housing fabrication draws from a narrow East Asian foundry base. National oil companies exhibit lowest price sensitivity given sovereign mandate compliance deadlines, while independent operators in Malaysia's offshore Peninsular blocks demonstrate highest sensitivity as tax credit thresholds constrain capital allocation.
Supply Chain Analysis
GB/T cryptographic certification and NOPSEMA SIL-rating requirements gate hardware qualification timelines, compressing effective supplier pools. Manufacturing concentrates in China, Japan, and South Korea, with domestic encryption protocol engineering tethered to Shenzhen and Beijing firmware development centers. Raw material dependencies center on high-grade carbon steel billets, fiber-optic sensing cables, and high-temperature semiconductor substrates. Single-source vulnerability runs through East Asian foundry capacity for downhole pressure housings. Distribution runs through integrated service majors anchoring bundled drilling-and-digital packages alongside independent software vendors capturing unbundled analytics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story where GB/T cryptographic certification bottlenecks prop pricing premiums for compliant vendors serving China's state-owned energy assets.
For Market Incumbents: Acquire predictive analytics software specialists to anchor digital twin deployments against unbundling pressure from Pertamina's modular procurement program. Deepen backward integration into carbon steel housing fabrication to offset East Asian foundry concentration risk. Prioritize SIL-rated control system certification investment to defend against European-headquartered competitors facing EU AI Act extraterritorial compliance costs. For New Entrants and Emerging Players: Independent software vendors with edge-AI inference capabilities represent the most penetrable channel partner type for bypassing integrated service major dominance. Target pipeline integrity monitoring whitespace across Sumatra's aging trunk lines where predictive corrosion analytics remain underdeployed. Lead with on-device machine learning service models that circumvent latency constraints of centralized cloud architectures. For Investors and Strategic Acquirers: Re-rating potential sits with domestic-certified platform developers given China's MIIT mandate acceleration and captive demand from Sinopec and PetroChina digital transformation programs. Long-term viability favors vendors with sovereign data localization architecture already deployed. Watch GB/T cryptographic compliance timeline compression as the inflection signal indicating vendor qualification backlog clearing.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Firmware Re-engineering | GB/T cryptographic compliance unlocks access to Sichuan Basin shale procurement pipelines. |
| Fiber-Optic Sensing Capacity Buildout | Real-time distributed temperature monitoring penetrates Tarim Basin HPHT reservoirs previously inaccessible. |
| Edge-AI Platform Integration | On-device inference at Australian wellhead locations bypasses satellite bandwidth constraints. |
| Predictive Corrosion Analytics Partnership | Standalone contracts with Pertamina displace integrated service major bundling in Indonesia. |
| SIL-Rated Control System Certification | NOPSEMA compliance anchors North West Shelf subsea automation procurement decisions. |
Study Parameters
Multi-period observation of MIIT mandate implementation timelines, NOPSEMA certification backlogs, and Pertamina procurement pattern shifts anchored the trend analysis, supplemented by interviews with digital oilfield engineering directors, GB/T compliance officers at state-owned operators, subsea automation procurement leads at Australian LNG facilities, and edge-AI platform architects. Secondary validation drew from MIIT industrial IoT standard filings, NOPSEMA functional safety guidance documents, Australian Bureau of Statistics energy capital expenditure data, and China Petroleum and Chemical Industry Federation digitization reports. Bottom-up sensor deployment counts and top-down operator technology budget disclosures were triangulated to constrain volume estimates.
The input-output matrix framed projections across hardware, software, and service revenue streams segmented by product type, technology maturity, end-user procurement authority, and application margin profile. CAGRs were derived from regression against historical adoption curves in analogous industrial IoT verticals, with cross-validation against operator-stated digital transformation timelines. Forecast inputs incorporated GB/T cryptographic qualification cycle lengths, carbon steel housing supply elasticity, and fiber-optic telemetry deployment rates in HPHT reservoirs.
Caveats apply where MIIT mandate enforcement intensity, NOPSEMA regulatory reinterpretation, or abrupt shifts in China's dual carbon goal implementation could materially shift the outlook. Forecasts reflect documented assumptions about vendor qualification timeline stability and sovereign data localization policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Mud Balance Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Thailand Oil and Gas Market