
 Russian Federation Oil and Gas Downstream Market | 2026-2036
Russian Federation Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Oil and Gas Downstream Market Analytics
Russia's aviation fuel segment is pivoting toward import-substitution grades as domestic air traffic recovers. PJSC Rosneft Oil Company leverages its Angarsk and Tuapse refining assets to dominate jet fuel output in Siberia and the Black Sea basin. PJSC Lukoil Oil Company sustains a competitive edge through its Norsi and Volgograd refineries, which specialize in high-octane gasoline for the Central Federal District. PAO NOVATEK anchors its downstream position through Arctic LNG condensate processing, diverting NGL streams toward domestic petrochemical offtake.
Russian Federation oil and gas downstream operations encompass crude oil refining, natural gas processing, and the manufacture of petroleum derivatives including motor fuels, olefins, aromatics, and base oils, with typical refinery complexity indices ranging from 5 to 12 depending on coking and hydrocracking intensity. The primary purpose centers on converting raw hydrocarbons into transport fuels, chemical feedstocks, and industrial lubricants that supply Russia's automotive, aviation, and manufacturing sectors. Refined fuels occupies the largest revenue pool among product types, though margin compression in straight-run gasoline is pushing operators toward deeper conversion units. Petrochemicals represents the fastest-expanding segment as Gazprom Neft's Omsk and Tobolsk complexes expand ethylene and polypropylene capacity to serve Central Asian export routes.
Russia's Federal Service for Environmental, Technological and Nuclear Supervision (Rostekhnadzor) enforces industrial safety rules for refining and petrochemical facilities, while the Federal Antimonopoly Service monitors wholesale fuel pricing to prevent regional supply distortions. The Technical Regulation of the Customs Union (TR CU 013/2011) mandates Euro-5 equivalent fuel standards, forcing refinery modernization toward hydrotreating and isomerization investments. Stakeholders must monitor how sanctions-driven equipment sourcing constraints affect catalyst replacement cycles and delayed coker uptime across Russia's aging refinery fleet.
Market Dynamics
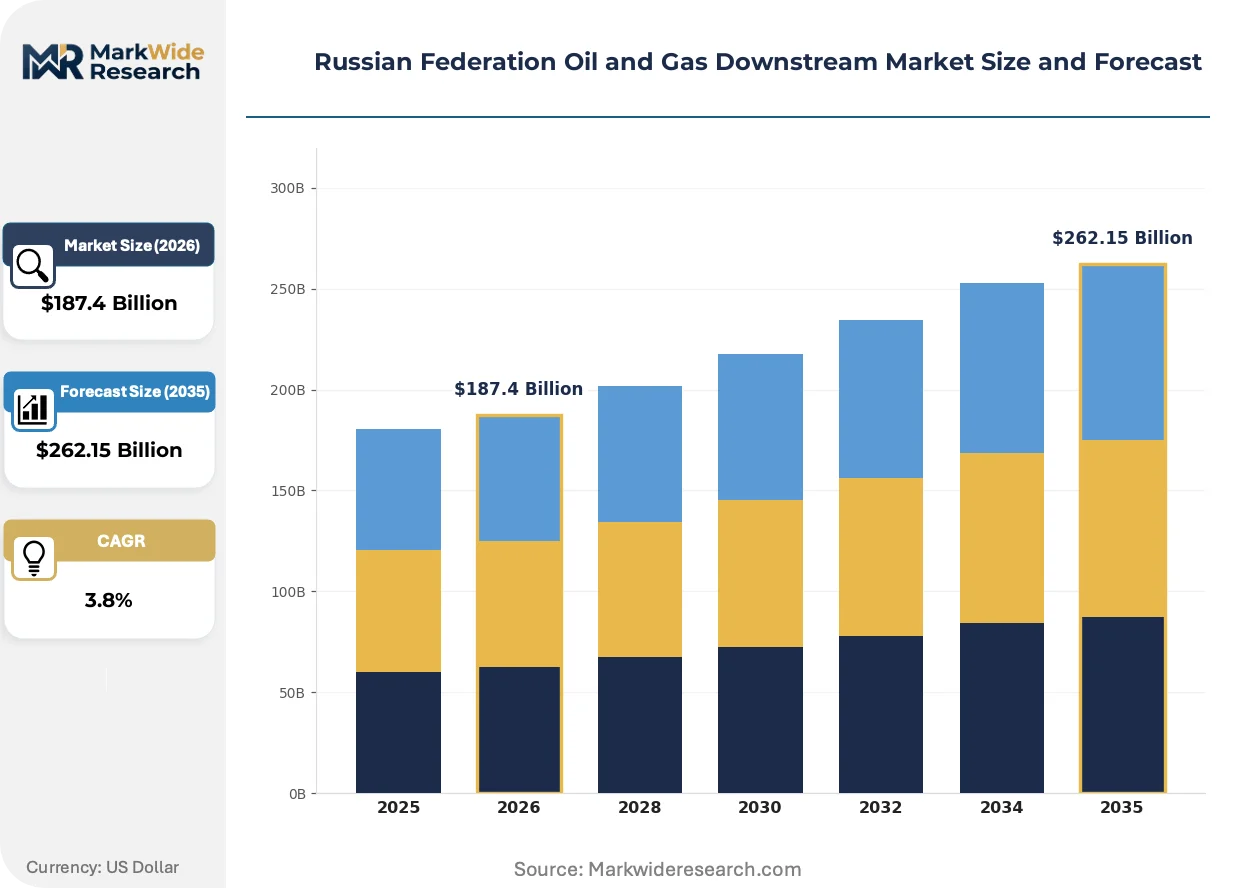
Rostekhnadzor's enforcement of TR CU 013/2011 Euro-5 fuel standards is forcing refinery modernization across Russia's aging downstream infrastructure, compressing margins for straight-run gasoline while accelerating hydrocracking and isomerization investments.
Growth Catalysts
- Polymer manufacturing expansion:Domestic ethylene and polypropylene capacity additions at Tobolsk and Omsk complexes are pulling NGL streams from Arctic LNG projects into captive petrochemical feedstock supply.
- Aviation fuel import substitution:Recovery in domestic air traffic is redirecting jet fuel output from export markets toward import-substitution grades certified for Russian air carriers.
- Volga-Ural corridor concentration:Integrated refinery-petrochemical complexes in Samara and Ulyanovsk oblasts anchor supply security for Central Federal District manufacturing demand.
Market Restraints
- Catalyst sourcing constraints:Sanctions-driven equipment procurement restrictions are extending hydrotreating catalyst replacement cycles at hydrocracking units.
- Refinery complexity limitations:Nelson complexity indices below 7 at older Siberian facilities limit deep conversion of residual fuel oil into higher-value distillates.
- Wholesale pricing controls:Federal Antimonopoly Service monitoring of regional fuel markets constrains margin capture during crude price volatility.
Strategic Opportunities
- Central Asian export routing:Petrochemical output from Russian complexes can displace Middle Eastern supply into Kazakhstan and Uzbekistan polymer markets.
- Arctic condensate processing:Yamal and Gydan peninsula gas field liquids offer underutilized feedstock for domestic aromatic production.
- Hydrogen refinery integration:Steam methane reforming units at Angarsk and Tuapse refineries can pivot toward low-carbon hydrogen for hydrodesulfurization.
Industry Challenges
- Delayed coker maintenance expertise:Specialized welding and refractory skills for high-temperature coke drum repair face generational workforce gaps.
- Legacy distributed control system migration:Refinery automation upgrades from 1990s-era SCADA architectures require phased shutdown coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Oil and Gas Downstream Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalts Distribution Channel: Retail, Wholesale, Direct Sales, E-Commerce End User: Automotive Sector, Industrial Users, Residential Consumption, Aviation Service Type: Transportation, Storage, Refining, Marketing |
| Companies Covered | PJSC Rosneft Oil Company, PJSC Lukoil Oil Company, PAO NOVATEK, PJSC Gazprom, PJSC Surgutneftegas, Gazprom Neft, Bashneft, Tatneft, Transneft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Oil and Gas Downstream Market Evolving Landscape
Refinery digitalization and feedstock flexibility investments are reshaping Russia's downstream competitive calculus, with operators prioritizing real-time optimization over static capacity expansion.
Residue hydrocracking technology is consolidating Russian refinery upgrade priorities, converting vacuum residuum into diesel and naphtha streams. Operators at Komsomolsk and Kirishi refineries are adopting ebullated-bed reactors to process heavier Urals crude slates. This conversion capability is consolidating market position for complexes with coking intensity above 10, leaving straight-run refineries exposed to fuel oil margin erosion.
Rostekhnadzor's 2023 amendments to industrial safety rules for oil refining facilities mandate probabilistic risk assessment methodologies for fired heater and reactor integrity management. Facility operators must submit quantitative risk analysis for hydrofluoric acid alkylation units and delayed coking drums. The Volga-Ural refining cluster faces the steepest compliance timeline, with legacy units at Samara and Syzran requiring structural retrofit documentation by 2026.
Refinery procurement patterns are fragmenting equipment vendor relationships as original Western licensors exit the market. Russian operators are qualifying Chinese and Indian catalyst suppliers for hydrotreating and reforming applications, with quality verification cycles extending 18-24 months. This supplier rotation is most visible at greenfield petrochemical integrations in Tobolsk, where polymerization catalyst qualification delays are compressing project commissioning schedules.
Russian Federation Oil and Gas Downstream Market Segmentation
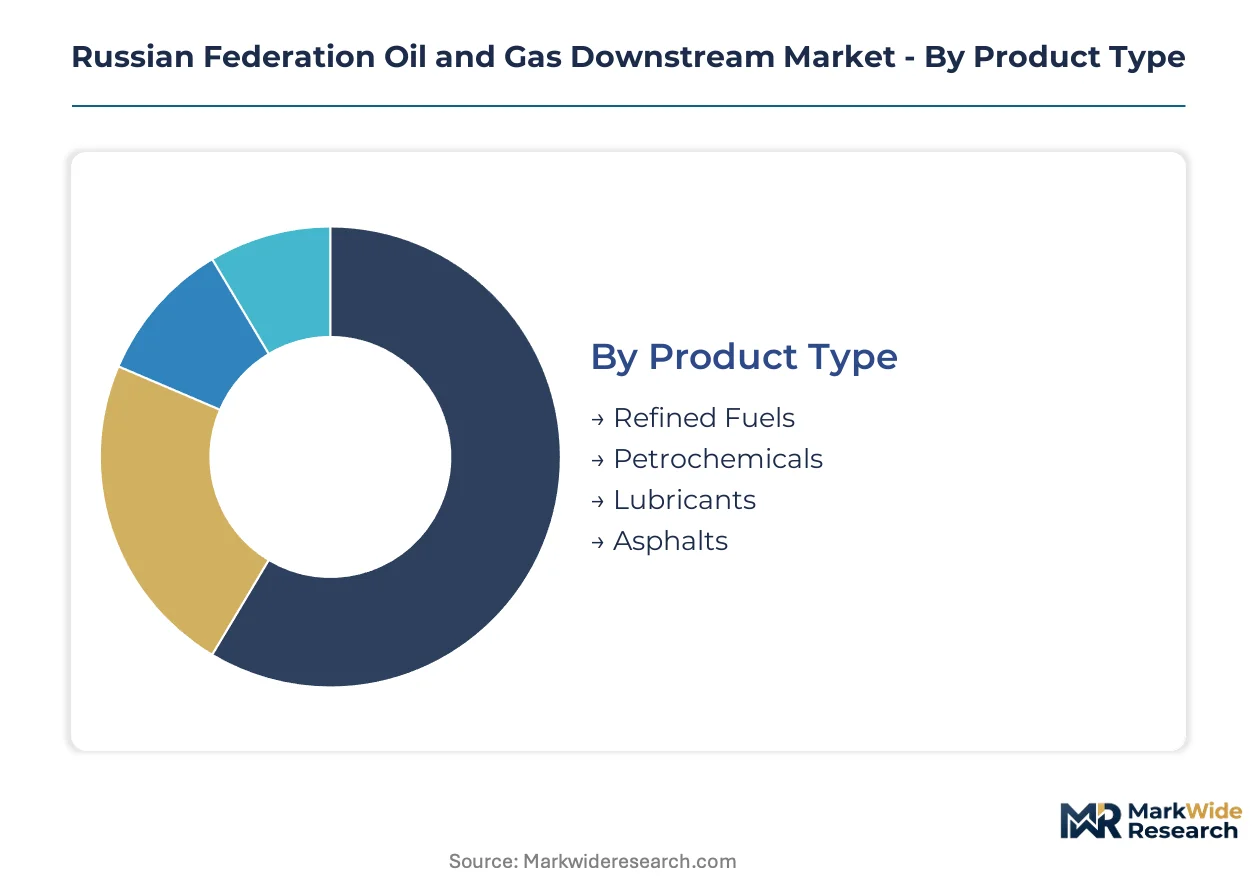
Segmentation reveals how Russia's downstream value chain fragments across product specifications, logistics pathways, and customer contracting modes. Understanding these divides exposes where margin capture concentrates and where infrastructure gaps persist.
Product Type:
Supply concentrates in refined fuels, though petrochemicals is gaining share fastest as Tobolsk and Omsk complexes expand.
- Refined Fuels:Motor gasoline, diesel, and fuel oil dominate throughput at Angarsk, Tuapse, and Volgograd refineries. Demand clusters along the Volga-Ural corridor where Central Federal District automotive and industrial offtake absorbs two-thirds of domestic gasoline output. Federal Antimonopoly Service wholesale pricing controls compress margins during crude volatility.
- Petrochemicals:Ethylene, propylene, and aromatic streams from Gazprom Neft's Omsk and Tobolsk facilities feed domestic polymer manufacturing. Central Asian export routes into Kazakhstan and Uzbekistan pull incremental supply westward, displacing Middle Eastern feedstock.
- Lubricants:Base oil production at Kirishi and Perm refineries serves industrial machinery and automotive service fill markets.
- Asphalts:Vacuum residuum processing for road construction concentrates in seasonal demand cycles across Siberian infrastructure projects.
Today's leader: Refined Fuels. Tomorrow's challenger: Petrochemicals.
Distribution Channel:
Cost tier differentiation separates high-touch retail networks from bulk wholesale contracting.
- Retail:Branded station networks owned by Rosneft and Lukoil dominate consumer gasoline and diesel sales. Site-level pricing responds to regional supply conditions and competitor positioning within 50-kilometer catchments.
- Wholesale:Large-volume contracts supply industrial boilers, agricultural machinery fleets, and independent fuel distributors. Federal Antimonopoly Service monitors these transactions to prevent regional supply distortions.
- Direct Sales:Refinery-to-consumer pipelines and dedicated rail shipments serve captive industrial users with predictable offtake profiles.
- E-Commerce:Digital fuel ordering platforms remain nascent, constrained by logistics integration requirements and payment settlement infrastructure.
Wholesale volumes anchor revenue stability. Retail margins face the steepest regulatory pressure.
End User:
Application-driven demand splits between mobility fuels and stationary industrial consumption.
- Automotive Sector:Passenger vehicle gasoline demand concentrates in Moscow and St. Petersburg metropolitan areas. Euro-5 fuel standards enforced by Rostekhnadzor mandate hydrotreating investments that upgrade octane ratings.
- Industrial Users:Manufacturing plants, mining operations, and power generation facilities consume diesel and residual fuel oil. Siberian extractive industries source from Angarsk and Komsomolsk refinery supply basins.
- Residential Consumption:LPG and kerosene serve remote settlements beyond pipeline grid coverage, particularly in Arctic and Far Eastern regions.
- Aviation:Jet fuel offtake from Rosneft's Tuapse and Angarsk assets pivots toward import-substitution grades as domestic air traffic recovers.
Automotive demand holds volume dominance. Aviation is climbing the fastest on route restoration.
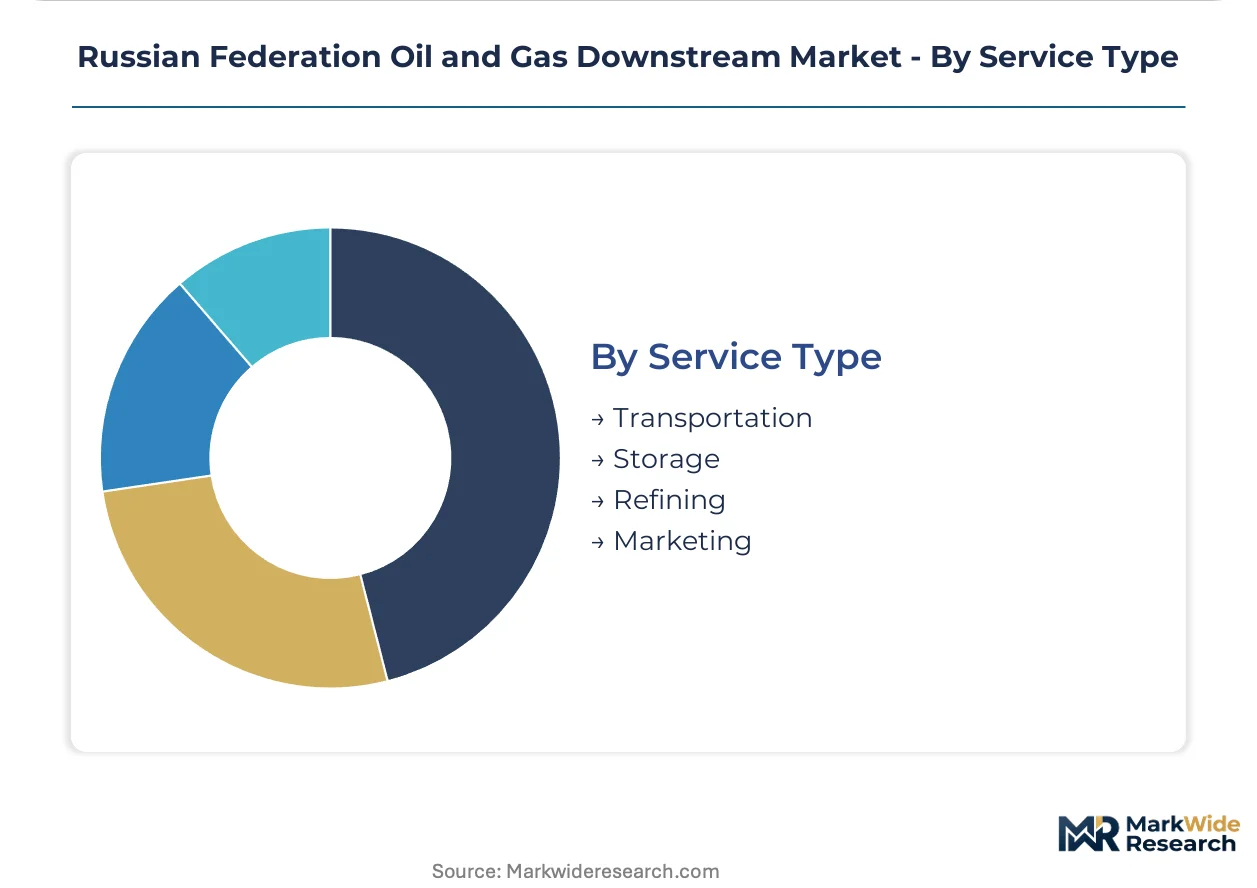
Service Type:
Margin maturity varies sharply across the value chain, with refining commanding capital intensity and marketing capturing price volatility.
- Transportation:Pipeline trunk systems operated by Transneft move crude to refineries and products to distribution terminals. Rail and river barge networks supplement capacity to remote consumption centers.
- Storage:Tank farm capacity at Kozmino, Ust-Luga, and other port terminals buffers export scheduling against vessel availability.
- Refining:Conversion complexity at hydrocracking and delayed coking units determines distillate yield from Urals crude slates. Nelson complexity indices below 7 at older Siberian facilities limit residual fuel oil upgrading.
- Marketing:Branded product sales and term contract negotiation sit at the customer interface, exposed to competitor pricing and regulatory intervention.
Refining absorbs the capital deployment. Marketing delivers the margin volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting investment toward sub-regions with streamlined licensing timelines and lower environmental compliance costs, concentrating new capacity in areas where Rostekhnadzor enforcement intensity varies.
Volga-Ural Corridor
Samara and Ulyanovsk oblasts host integrated refinery-petrochemical complexes supplying Central Federal District manufacturing demand. Rostekhnadzor's Euro-5 fuel standards enforcement accelerates hydrotreating investments at Samara and Syzran facilities. The Samara refinery cluster processes Urals crude into high-octane gasoline for Moscow metropolitan automotive consumption.
Siberian Basin
Angarsk and Komsomolsk refineries serve extractive industries and remote settlements with diesel and residual fuel oil. The region's Nelson complexity indices below 7 limit deep conversion capabilities at older facilities. Komsomolsk refinery adopts ebullated-bed residue hydrocracking to upgrade vacuum residuum into distillate streams.
Black Sea Basin
Tuapse refinery anchors jet fuel output for recovering domestic aviation traffic and export markets. Federal Antimonopoly Service wholesale pricing monitoring constrains margin capture during crude price volatility. The facility leverages pipeline connectivity to supply import-substitution grades certified for Russian air carriers.
Arctic Zone
Yamal and Gydan peninsula gas field condensates feed Arctic LNG projects with underutilized NGL streams for domestic petrochemical offtake. PAO NOVATEK processes condensate through specialized fractionation units. Tobolsk petrochemical complexes divert these streams toward ethylene and polypropylene capacity expansion.
Northwestern Port Belt
Ust-Luga and Kirishi facilities balance export scheduling against vessel availability through tank farm buffering capacity. The Kirishi refinery produces base oils for industrial machinery and automotive service fill markets. St. Petersburg metropolitan gasoline demand pulls supply through dedicated product pipelines.
Russian Federation Oil and Gas Downstream Market Competitive Landscape
Capacity expansion dominates the current landscape as operators retrofit aging facilities for Euro-5 compliance and deeper conversion economics. The market structure consolidates around state-affiliated integrated oil companies with captive upstream supply and vertically held distribution networks. Three archetypes define competitive positioning: upstream-integrated majors with full value chain control, mid-tier regionals with geographic specialization, and infrastructure-dominant pipeline operators. Strategic moves center on hydrocracking unit additions and petrochemical integration projects.
Within the integrated major tier, PJSC Rosneft Oil Company, PJSC Lukoil Oil Company, and PAO NOVATEK occupy positions defined by refining asset scale and feedstock access. Rosneft exemplifies the complexity-driven archetype through Angarsk and Tuapse conversion capacity. Lukoil represents the regional-specialist model with Norsi and Volgograd high-octane gasoline focus. NOVATEK anchors the condensate-processing segment through Arctic LNG liquids integration. These structures illustrate how upstream control and geographic asset placement determine downstream competitive position.
| Leading Market Players |
|---|
| PJSC Rosneft Oil Company |
| PJSC Lukoil Oil Company |
| PAO NOVATEK |
| PJSC Gazprom |
| PJSC Surgutneftegas |
| Gazprom Neft |
| Bashneft |
| Tatneft |
| Transneft |
| Others |
Value Network & Pricing Analysis
Sovereign-backed integrated oil companies anchor Russian downstream pricing discipline through captive upstream supply and vertically held distribution networks, compressing third-party margin capture while channeling fuel flows toward state-mandated wholesale benchmarks. This ownership pattern tethers refinery gate pricing to Federal Antimonopoly Service monitoring protocols, constraining spot-market volatility even as crude slates fluctuate.
Pricing Analysis
Retailer markup layers separate refinery gate prices from consumer pump levels, with Rosneft and Lukoil branded networks capturing geographic premiums in Moscow and St. Petersburg catchments. Pricing stratifies across Euro-5 certified, Euro-4 transitional, and industrial-grade fuel tiers, with certification grade and volume scale driving differentiation. Cost compression in straight-run gasoline intensifies as hydrocracking investments raise unit processing costs. Independent distributors exhibit highest price sensitivity, while captive industrial offtakers accept term premiums for supply security.
Supply Chain Analysis
Catalyst supply rests on Chinese and Indian specialty chemical producers as Western licensors exit, extending qualification cycles for hydrotreating and reforming applications. Urals crude feedstock draws from West Siberian and Volga-Ural extraction basins, while refinery equipment sourcing hinges on domestic fabrication and Asian import channels. Single-source vulnerability concentrates in advanced reactor internals and proprietary process control systems. Distribution runs through Transneft pipeline trunk systems, rail networks, and river barge corridors to remote consumption centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russian downstream margin expansion hinges on residue hydrocracking adoption and petrochemical integration, with conversion complexity upgrades displacing fuel oil exposure into higher-value distillate and polymer feedstock pools.
For Market Incumbents: Lock in feedstock advantage through Arctic condensate offtake agreements with NOVATEK's Yamal and Gydan projects, securing NGL streams for Tobolsk and Omsk petrochemical expansion. Prioritize hydrocracking catalyst inventory buffers against sanctions-driven procurement delays. Defend position by accelerating delayed coker maintenance programs before Rostekhnadzor's 2026 compliance deadlines compress contractor availability. For New Entrants and Emerging Players: Digital procurement platforms for industrial fuel offtake present the most penetrable entry vector, targeting Siberian mining and extractive operations beyond pipeline grid coverage with mobile tanker and drum logistics. White-space concentrates in specialty aromatic production from underutilized Arctic gas field liquids. Pursue toll-processing arrangements with existing refineries rather than greenfield capacity, leveraging stranded condensate streams from Gydan peninsula developments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional refiners with Nelson complexity indices below 7 and stranded fuel oil exposure, offering retrofit optionality if conversion technology licenses become available. Long-term viability favors complexes with demonstrated petrochemical integration pathways and Central Asian export corridor access. Watch hydrocracking unit commissioning schedules at Komsomolsk and Kirishi as inflection indicators for sector-wide margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Hydrocracking Unit Addition | Ebullated-bed reactors at Komsomolsk upgrade vacuum residuum into diesel and naphtha streams, displacing fuel oil margin erosion. |
| Arctic Condensate Processing Integration | NOVATEK's Yamal NGL fractionation feeds Tobolsk ethylene expansion, anchoring polymer export competitiveness into Central Asia. |
| Delayed Coker Integrity Retrofit | Rostekhnadzor-mandated probabilistic risk assessments force structural documentation at Samara and Syzran legacy units by 2026. |
| Catalyst Supplier Diversification | Chinese and Indian hydrotreating catalyst qualification extends 18-24 month verification cycles, compressing project commissioning schedules. |
| Hydrogen Refinery Integration | Steam methane reforming pivots at Angarsk and Tuapse toward low-carbon hydrogen for hydrodesulfurization, aligning with Euro-5 standards. |
Research Methodology
Direct dialogue with refinery operations managers, petrochemical procurement leads at polymer manufacturers, Transneft logistics planners, and Rostekhnadzor compliance officers grounded qualitative assessment, cross-referenced with customs export data, EIA international energy statistics, SEC filings of listed Russian oil majors, and technical regulation amendments from the Eurasian Economic Commission. Bottom-up capacity modeling triangulated against top-down demand projections from automotive and aviation sector offtake patterns.
Bottom-up refinery throughput modeling by unit configuration and Nelson complexity index combined with top-down sectoral demand elasticity estimates across the projection horizon. Segmentation dimensions encompassed product type, distribution channel, end-use sector, and regional supply basin. CAGRs derived from capacity expansion timelines, regulatory compliance deadlines, and feedstock availability curves. Forecast inputs incorporated Urals crude slate quality trends and Arctic LNG condensate volume projections.
The model assumes a particular technology adoption path for residue hydrocracking and ebullated-bed reactor deployment; alternative pathways for coking intensity upgrades or catalytic cracking retrofits would alter the outlook for fuel oil displacement and distillate yield. Forecasts reflect assumptions regarding sanctions duration, equipment sourcing feasibility, and Central Asian export market penetration. A small set of triggers—Rostekhnadzor enforcement intensity, catalyst procurement breakthroughs, and aviation traffic recovery velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Unconventional Gas Market
Oil & Gas
Frac Stack Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Brazil Oil and Gas Market