
 Modular Gas Processing Plants Market | 2026-2036
Modular Gas Processing Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Gas Processing Plants Market Foresight
Multi-source procurement for modular gas processing equipment is shifting from consolidated EPC contracts toward specialized vendor ecosystems. Technip Energies leverages its cryogenic distillation expertise to anchor large-scale LNG modular projects across multiple continents. Siemens Energy AG competes through integrated digital twin offerings that extend plant lifecycle value beyond hardware supply. Black & Veatch sustains its position by dominating utility-scale gas treatment engineering in North American shale plays.
Modular gas processing plants are prefabricated, transportable systems engineered for hydrocarbon conditioning, dehydration, and contaminant removal at throughput capacities typically ranging from five to over five hundred million standard cubic feet per day. These units deploy skid-mounted process trains, pressure vessels, and control systems factory-assembled for rapid site installation, serving primary purposes of natural gas sweetening, NGL recovery, and pipeline specification compliance. Fully modular systems command premium pricing due to reduced field construction risk and accelerated revenue timelines, while membrane technology segments attract capital as operators seek lower-energy alternatives to amine-based chemical absorption for carbon dioxide removal. Skid-mounted solutions occupy the highest volume tier among product configurations, though mobile plants represent the fastest-expanding category for remote field and emergency response applications.
The EPA enforces methane performance standards under New Source Performance Standards Subpart OOOOa, compelling facility upgrades that favor modular retrofit architectures over greenfield construction. OSHA process safety management requirements and DOT pipeline safety regulations further shape equipment certification and material specification protocols for interstate gas transport. Stakeholders must monitor evolving carbon border adjustment mechanisms and emerging low-carbon fuel standards that will determine competitive positioning of gas processing infrastructure investments.
Market Dynamics
Offshore operators and Permian Basin midstream companies are compressing field development timelines through prefabricated skid-mounted architectures that displace conventional stick-built construction. This structural shift toward factory-integrated process trains is compressing capital deployment cycles and reshaping vendor relationships across the natural gas value chain.
Growth Catalysts
- EPA Methane Performance Standards:New Source Performance Standards Subpart OOOOa mandate facility upgrades that favor modular retrofit solutions over greenfield construction. Pipeline operators in the Gulf Coast region face compliance deadlines that accelerate equipment replacement cycles.
- Membrane Separation Technology:Polymeric and mixed-matrix membrane systems for carbon dioxide removal are displacing energy-intensive amine absorption at smaller-scale facilities. Remote field operators in the Permian Basin deploy these units to reduce operational expenditure and eliminate chemical handling logistics.
- Midstream Infrastructure Constraints:Persistent gathering and processing bottlenecks in the Delaware and Midland sub-basins create immediate demand for rapid-deployment gas treatment capacity. Private equity-backed midstream developers prioritize speed-to-market over absolute unit economics.
Market Restraints
- Specialized Alloy Supply Concentration:Pressure vessel fabrication depends on limited domestic sources of chromium-molybdenum steel plate and corrosion-resistant cladding materials. Disruptions at North American specialty steel mills propagate directly into modular fabrication lead times.
- Interstate Transport Certification Friction:DOT pipeline safety regulations and state-level permitting variations create jurisdictional complexity for mobile plant deployments. Cross-border equipment movement between Texas, New Mexico, and Louisiana requires redundant inspection protocols.
- Amine-Based System Incumbency:Established chemical absorption infrastructure at legacy facilities creates switching costs that delay membrane technology penetration. Operator familiarity with triethylene glycol dehydration and methyl diethanolamine sweetening slows alternative adoption.
Strategic Opportunities
- Remote Arctic and Subarctic Development:Northern Alberta and Alaska North Slope projects require fully modular architectures due to seasonal construction windows and limited local labor pools. These environments command premium pricing for cold-climate engineered packages.
- Digital Twin Integration:Convergence of process simulation software with edge computing hardware enables predictive maintenance offerings that extend vendor revenue streams beyond equipment supply. Siemens Energy and similar integrators capture lifecycle value through subscription-based optimization services.
- Hydrogen Blending Infrastructure:Emerging pipeline specifications for hydrogen-natural gas mixtures create demand for modified gas treatment trains capable of handling shifted molecular weight distributions and embrittlement-sensitive metallurgy.
Industry Challenges
- Skilled Welding and Inspection Talent Scarcity:ASME Section VIII pressure vessel certification and API 1104 pipeline welding qualifications face generational workforce gaps. Fabrication yards compete for qualified radiographic testing technicians and certified welding inspectors.
- Legacy Control System Integration:Brownfield deployments require protocol translation between modern skid-mounted distributed control systems and existing SCADA architectures. OPC-UA and Modbus interoperability consumes engineering hours unanticipated in original project scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Gas Processing Plants Market |
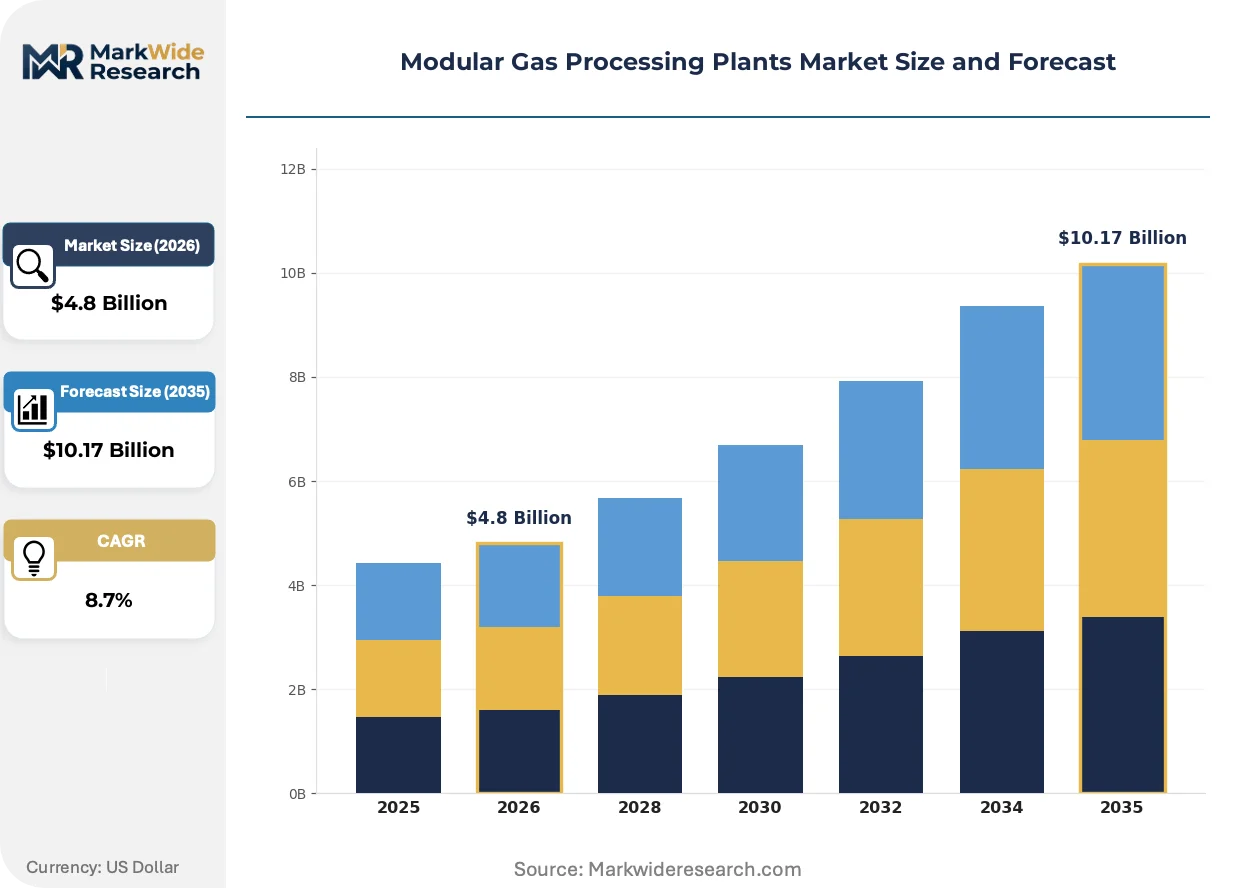
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Units, Fully Modular Systems, Skid-Mounted Solutions, Mobile Plants Application: Natural Gas Treatment, LNG Processing, Oil & Gas Separation, Biogas Upgrading End User: Energy Producers, Industrial Gas Users, Renewable Energy Facilities, Offshore Operators Technology: Membrane Technology, Adsorption Processes, Cryogenic Distillation, Chemical Absorption |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Black & Veatch, General Electric Company, Technip Energies, JGC Holdings Corporation, Honeywell International Inc., Siemens Energy AG, Linde Engineering, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Gas Processing Plants Market Shifts & Advancements
Electrification of process heating and compression systems is displacing gas-fired mechanical drives across modular plant designs. This technology rotation is compressing carbon intensity metrics and opening new procurement channels for renewable-powered field operations.
Electrified compression trains using high-speed permanent magnet motors and variable frequency drives are electrifying gas processing unit operations that historically depended on gas turbine or reciprocating engine drivers. Permian Basin operators with access to grid-connected or behind-the-meter solar capacity deploy these configurations to satisfy Scope 1 emissions accounting requirements. The technology is electrifying competitive differentiation among EPC bidders as carbon intensity becomes a weighted evaluation criterion.
EPA enforcement of methane performance standards under New Source Performance Standards Subpart OOOOa is tightening leak detection and repair protocols across new and modified facilities. This regulatory pressure is accelerating capital allocation toward sealed compressor packages and closed-loop venting systems. Gulf Coast processing complexes face the most immediate compliance timelines and are driving specification changes that propagate to equipment vendors.
Service contracting is fragmenting from consolidated EPC wrap arrangements toward specialized vendor ecosystems where cryogenic, membrane, and dehydration subsystems are procured independently. Midstream operators with in-house engineering capabilities disaggregate responsibility to optimize subsystem performance and accelerate schedule accountability. This pattern is most visible among Permian Basin independents with established vendor qualification programs and repeat-order relationships.
Modular Gas Processing Plants Market Segmentation
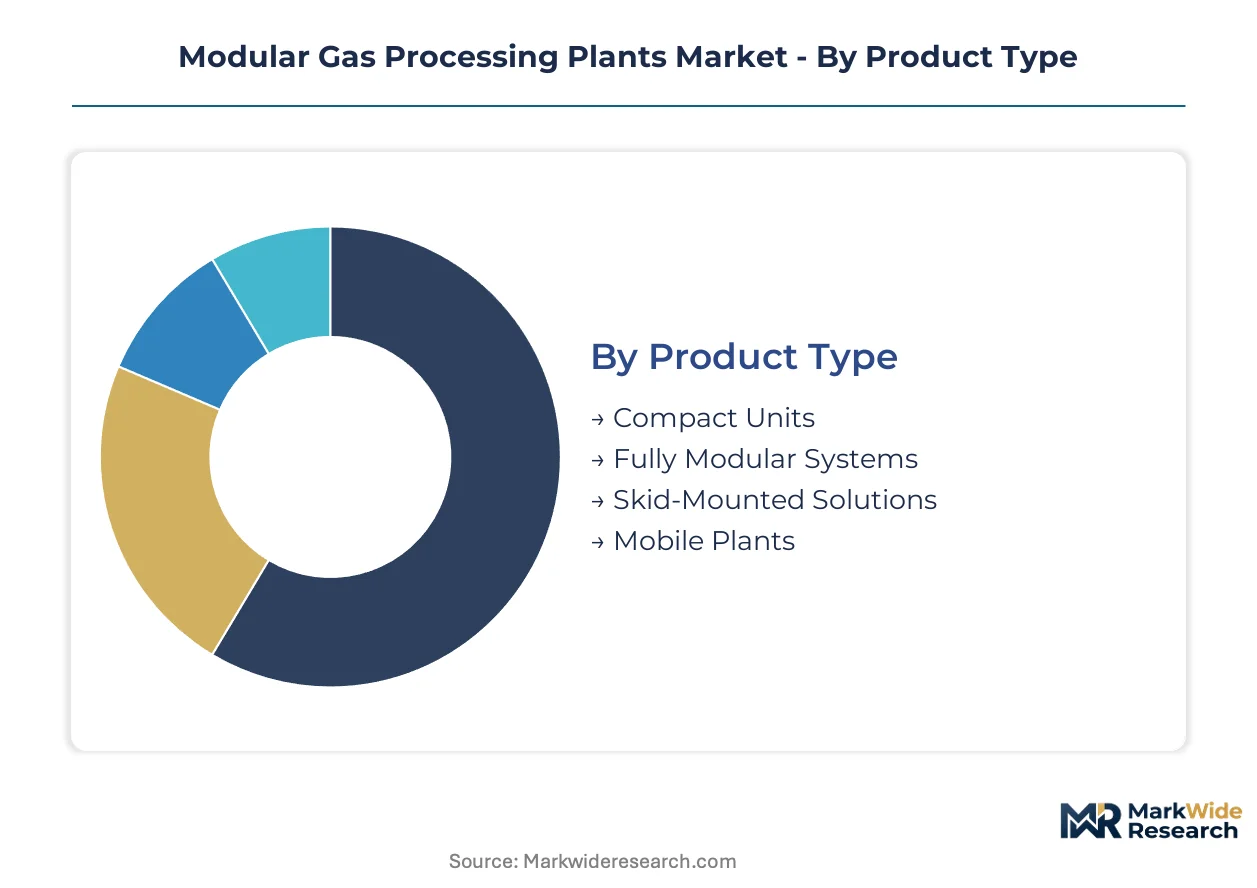
Modular gas processing plants fragment across four distinct dimensions that determine procurement patterns, engineering specifications, and vendor selection criteria. Each segmentation axis reveals divergent margin structures and deployment timelines that shape competitive positioning across the natural gas value chain.
Product Type:
Skid-mounted solutions dominate current procurement volumes while fully modular systems command the steepest price premiums for accelerated field deployment.
- Skid-Mounted Solutions:Factory-assembled process trains mounted on structural steel skids enable rapid site installation with minimal civil works. Permian Basin midstream developers deploy these units to compress gathering system bottlenecks where speed-to-market outweighs absolute capital efficiency.
- Fully Modular Systems:Complete plant architectures with integrated utilities, control systems, and building envelopes deliver maximum schedule compression for remote Arctic developments in Alberta and Alaska. These configurations attract premium pricing due to eliminated field construction risk and reduced labor dependency.
- Compact Units:Reduced-footprint systems serve satellite dehydration and conditioning at marginal wellhead locations where throughput requirements fall below centralized facility scale.
- Mobile Plants:Trailer-mounted or containerized configurations enable emergency response and temporary processing during facility turnarounds, gaining traction among Gulf Coast operators managing hurricane season contingency planning.
Today's leader: Skid-mounted solutions. Tomorrow's challenger: Mobile plants.
Application:
Natural gas treatment absorbs the majority of current capital allocation while biogas upgrading presents the steepest expansion trajectory driven by renewable fuel certification schemes.
- Natural Gas Treatment:Sweetening, dehydration, and contaminant removal to achieve pipeline specifications represents the foundational use case. EPA methane performance standards under Subpart OOOOa compel facility upgrades across Texas and Louisiana production corridors.
- Biogas Upgrading:Carbon dioxide and hydrogen sulfide removal from anaerobic digestion output to produce renewable natural gas qualifies for California LCFS credits and federal RNG production incentives.
- LNG Processing:Small-scale liquefaction trains for peak shaving and remote field monetization deploy modular cryogenic packages where pipeline takeaway remains constrained.
- Oil & Gas Separation:Three-phase separation and gas conditioning at wellpad locations reduce trucking requirements and flare volumes across North Dakota Bakken and New Mexico Delaware Basin developments.
Foundation volume rests with natural gas treatment. Emerging volume is concentrating in biogas upgrading.
End User:
Energy producers drive procurement scale through repeat-order programs while offshore operators generate the most demanding specification requirements for space-constrained platform installations.
- Energy Producers:Upstream and midstream natural gas operators with established vendor qualification programs leverage standardized designs across multi-basin portfolios to compress engineering cycles and accelerate fabrication starts.
- Offshore Operators:Platform and FPSO developers require weight-optimized, space-efficient process trains with marine-grade certifications and explosion-proof electrical classifications.
- Industrial Gas Users:Petrochemical and refining complexes procure modular treatment capacity for hydrogen production feedstock conditioning and fuel gas quality management.
- Renewable Energy Facilities:Landfill gas and agricultural digester operators seek containerized upgrading systems to access renewable natural gas offtake contracts with utilities.
Procurement scale concentrates with energy producers. Specification complexity peaks with offshore operators.
Technology:
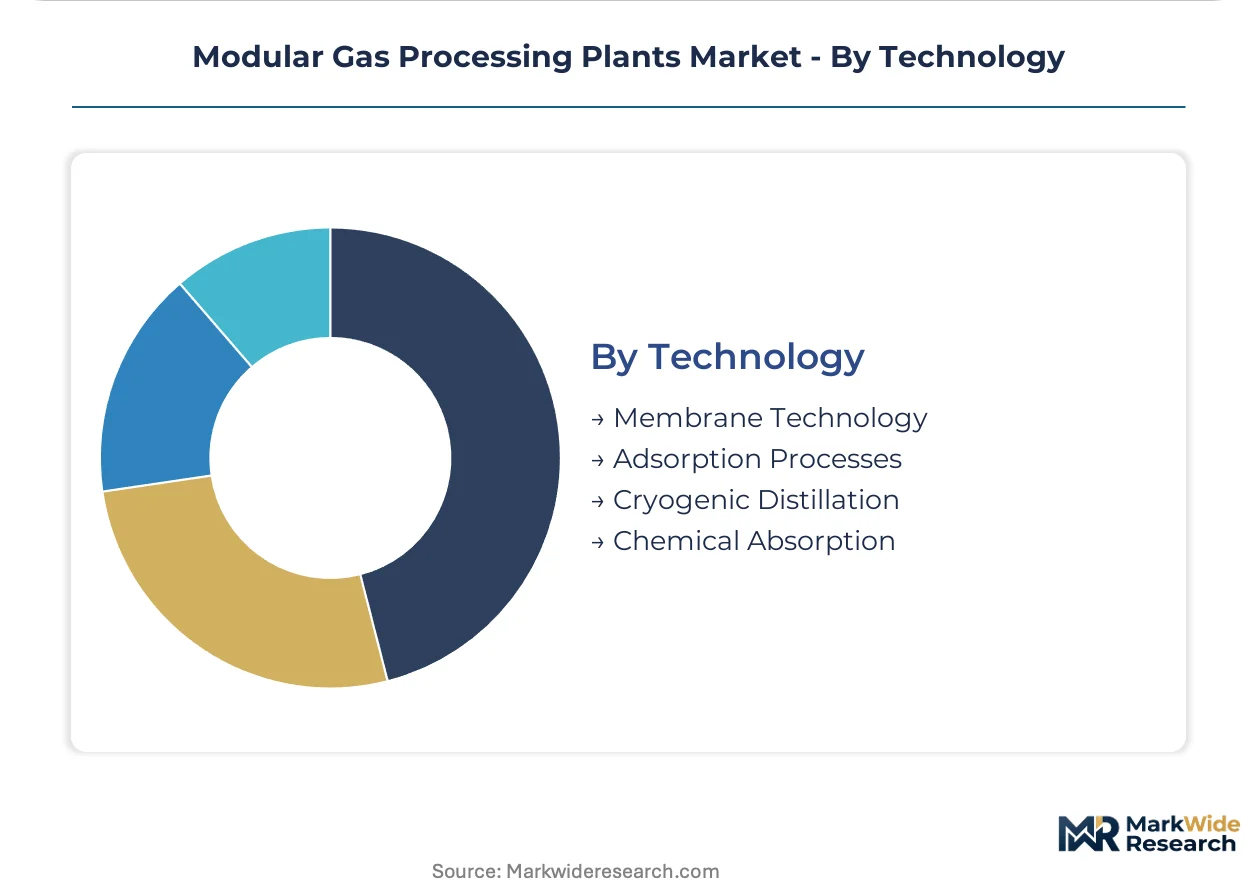
Chemical absorption retains incumbent position at legacy facilities while membrane technology displaces amine-based systems at smaller-scale and remote field locations seeking operational expenditure reduction.
- Membrane Technology:Polymeric and mixed-matrix membranes for carbon dioxide removal eliminate chemical handling logistics and reduce energy consumption compared to thermal regeneration systems. Permian Basin remote field operators deploy these units where staffing constraints limit amine system maintenance.
- Chemical Absorption:Methyl diethanolamine and other amine-based sweetening systems maintain dominance at high-capacity facilities where established operator familiarity and proven reliability outweigh switching costs.
- Cryogenic Distillation:Low-temperature separation processes enable high-recovery NGL extraction and helium recovery at large-scale centralized processing complexes.
- Adsorption Processes:Pressure swing and temperature swing adsorption systems target dehydration and trace contaminant removal where membrane selectivity proves insufficient.
Incumbent technology: Chemical absorption. Technology gaining share fastest: Membrane systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors regional demand concentration for modular gas processing infrastructure, with field development timelines compressing across multiple continents as operators deploy prefabricated architectures.
United States
Midstream bottlenecks in the Delaware and Midland sub-basins drive immediate demand for rapid-deployment gas treatment capacity. EPA methane performance standards under Subpart OOOOa compel facility upgrades across Texas and Louisiana production corridors. Gulf Coast processing complexes face accelerated compliance timelines that propagate specification changes to equipment vendors.
Canada
Northern Alberta oil sands and conventional gas developments require fully modular architectures due to seasonal construction windows. The country's national environmental regulator enforces methane reduction mandates that favor retrofit modular solutions over greenfield construction. Calgary-based engineering clusters concentrate procurement decision-making for Arctic-capable engineered packages.
Saudi Arabia
Eastern Province gas processing expansions integrate skid-mounted solutions to accelerate field development schedules. The national hydrocarbon regulator maintains stringent emissions protocols that drive sealed compressor package specifications. Jubail Industrial City hosts fabrication yards supplying modular units for domestic and export markets.
United Arab Emirates
Offshore platform developments in Abu Dhabi generate demanding specification requirements for space-constrained process trains. The national environmental authority enforces marine-grade certification standards for explosion-proof electrical classifications. Dubai and Abu Dhabi engineering hubs coordinate procurement for FPSO and platform installations.
Australia
Western Australia LNG and conventional gas projects deploy modular cryogenic packages where pipeline takeaway remains constrained. The national safety regulator mandates process safety management requirements that shape equipment certification protocols. Perth engineering offices manage procurement for remote field developments across the Northwest Shelf.
Modular Gas Processing Plants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and specialized subsystem niches. The vendor ecosystem stratifies between consolidated EPC integrators and specialized component suppliers. Three archetypes dominate: cryogenic distillation specialists, membrane technology purveyors, and integrated digital solution providers. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through regional fabrication alliances.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd and General Electric Company exemplify scale-driven positions spanning multiple energy infrastructure verticals. Siemens Energy AG anchors the digital-integrated tier, while Technip Energies represents the project-execution specialist archetype focused on large-scale modular deployments. Black & Veatch occupies a position within North American utility-scale engineering services.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Black & Veatch |
| General Electric Company |
| Technip Energies |
| JGC Holdings Corporation |
| Honeywell International Inc. |
| Siemens Energy AG |
| Linde Engineering |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Captive fabrication integration at Gulf Coast and Jubail Industrial City yards anchors supply positioning and pricing power for modular gas processing equipment. This vertical control over pressure vessel welding and skid assembly compresses cost pass-through timelines while insulating tier-one vendors from spot market volatility in specialty alloys.
Pricing Analysis
Input-cost pass-through from chromium-molybdenum steel plate and corrosion-resistant cladding materials dominates pricing dynamics for skid-mounted systems. Project-based contract structures prevail, with price differentiation driven by ASME Section VIII certification tier and customization scope for Arctic-rated packages. Pricing pressure stems from private equity-backed midstream developers prioritizing speed-to-market over capital efficiency. Small-scale Permian Basin independents exhibit highest price sensitivity, while offshore operators in the UAE and Australia accept premium positioning for marine-grade specifications.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale buyer demand from integrated operators, while specialized vendor ecosystems serve disaggregated procurement patterns among Permian Basin independents. Geographic supply concentrates in the United States, Saudi Arabia, and the United Arab Emirates, with fabrication drawing from Korean and Japanese specialty steel sources. Raw material dependencies center on chromium-molybdenum plate, nickel-based cladding, and high-grade welding consumables. Single-source vulnerability at North American specialty steel mills constitutes the primary structural risk. Distribution runs through consolidated EPC integrators for complex projects and direct vendor relationships for repeat-order programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular gas processing plants market functions as a regulatory compounder, with EPA methane performance standards under Subpart OOOOa generating sustained retrofit demand across Texas and Louisiana production corridors.
For Market Incumbents: Acquire membrane technology specialists to neutralize displacement risk from polymeric and mixed-matrix systems at smaller-scale facilities. Consolidate welding and inspection talent pools through regional fabrication yard investments in the Permian Basin and Gulf Coast, countering generational workforce gaps that threaten capacity expansion timelines. For New Entrants and Emerging Players: Launch via containerized mobile plant configurations targeting hurricane season contingency planning among Gulf Coast operators and remote Arctic field developments in Northern Alberta. White-space concentration exists in biogas upgrading for agricultural digester operators seeking California LCFS credit qualification, with lowest incumbent saturation in sub-50 mmscfd throughput tiers. For Investors and Strategic Acquirers: Roll-up economics work for digital-integrated subsystem specialists because midstream operators with in-house engineering capabilities are disaggregating procurement from consolidated EPC wraps. Target vendors with predictive maintenance platforms and edge computing hardware for predictive maintenance subscriptions. Watch EPA enforcement intensity and carbon border adjustment mechanism developments as inflection indicators for retrofit capital allocation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Polymeric CO2 removal systems displace amine absorption at remote Permian Basin locations. |
| Digital Twin Platform Integration | Siemens Energy and similar integrators capture lifecycle value through subscription optimization services. |
| Arctic-Capable Engineering Certification | Cold-climate packages command premium pricing in Northern Alberta and Alaska North Slope developments. |
| Specialized Alloy Backward Integration | Captive supply of chromium-molybdenum plate insulates fabrication timelines from mill disruption risk. |
| Hydrogen Blending Infrastructure Development | Modified gas treatment trains address emerging pipeline specifications for hydrogen-natural gas mixtures. |
Research Methodology
Coverage spans the United States, Canada, Saudi Arabia, the United Arab Emirates, and Australia, with primary inputs from each market cluster. The analysis combines structured interviews with EPC contractors, midstream procurement directors, and fabrication yard operations managers with secondary validation through EPA enforcement databases, FERC infrastructure filings, and EIA production statistics. Bottom-up triangulation across project announcement tracking and top-down reconciliation against national methane reduction targets ensures methodological rigor.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models segmentation dimensions including product configuration, application type, end-user category, and technology pathway alongside regional regulatory cluster effects. CAGRs were derived from equipment deployment timelines tied to compliance deadlines and field development schedules. Industry-specific forecast inputs incorporate gathering system bottleneck severity indices and membrane technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA enforcement intensity fluctuations and specialty steel supply disruption scenarios. Forecasts reflect assumptions regarding methane regulation continuity and midstream capital commitment velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Global Oil and Gas Analytics Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Pumpjack Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market