
 Oilfield Drill Bits Sales Market | 2026-2036
Oilfield Drill Bits Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Drill Bits Sales Market Insights
Independent shale operators are redrawing procurement priorities in the Oilfield Drill Bits Sales Market, shifting volume toward suppliers who deliver consistent footage and reduced non-productive time. Baker Hughes Company leverages in-house diamond synthesis to control PDC cutter quality from substrate to finished insert. Schlumberger Limited anchors its position through integrated drilling contracts that bundle bits with downhole telemetry. National Oilwell Varco competes on manufacturing scale, running multiple forge and machining centers across North America.
Oilfield drill bits are cutting tools engineered to pulverize or shear rock formations during hydrocarbon extraction, typically incorporating tungsten carbide inserts, polycrystalline diamond compact cutters, or milled steel teeth on forged cone bodies, with specifications governing IADC codes for bearing design, tooth configuration, and formation suitability. PDC bits dominate North American shale applications where directional drilling demands high rate-of-penetration in medium-hard formations, while roller cone variants retain share in abrasive and interbedded geologies where impact loading exceeds PDC durability thresholds. Tricone bits still occupy substantial replacement demand in mature onshore basins where operators prioritize tool cost over footage records.
API Q2 and ISO 10424-1 govern material certification, dimensional tolerance, and performance testing for drill bit qualification, with NHTSA and DOT surface-transport rules indirectly shaping logistics costs for oversized forging shipments. EPA emissions standards for onshore drilling operations are pushing operators toward bits that minimize drilling days and associated engine runtime. Stakeholders must monitor how directional drilling intensity and regulatory compliance costs reshape supplier selection criteria and bit technology roadmaps.
Market Dynamics
Pad drilling and extended-reach laterals are multiplying bit consumption per wellbore, forcing suppliers to optimize cutter durability and directional steerability rather than simply maximizing rate-of-penetration in vertical holes.
Growth Catalysts
- Extended-reach laterals:Permian Basin operators now drill 15,000-foot laterals requiring three to four bit trips per well, expanding replacement demand.
- API Q2 material certification:Tightened standards for tungsten carbide substrates are filtering out low-grade imports and elevating qualified supplier volumes.
- Geothermal drilling expansion:Hard-rock geothermal projects in Nevada and Utah are adopting oilfield PDC technology for crystalline basement penetration.
Market Restraints
- Synthetic diamond supply concentration:High-quality polycrystalline diamond substrate production clusters in three Asian manufacturing centers, creating single-source vulnerability.
- Tungsten carbide powder volatility:Mining disruptions in African ore sources transmit directly to insert fabrication costs.
- ISO 10424-1 testing timelines:Extended qualification protocols for new cutter geometries delay product commercialization by 8-14 months.
Strategic Opportunities
- Geothermal energy transition:European geothermal developers in Germany and France seek bits rated for 200°C bottom-hole temperatures.
- Digital bit selection platforms:Machine-learning tools that match formation logs to specific cutter layouts are gaining traction among independent operators.
- EU Green Deal drilling efficiency mandates:Carbon-intensity disclosures favor bits that minimize engine runtime per meter drilled.
Industry Challenges
- Directional drilling specialist shortage:Bit designers with expertise in steerable motor compatibility command premium compensation and extended recruitment cycles.
- Legacy MWD integration:New bit telemetry systems require retrofit compatibility with 1990s-era measurement-while-drilling infrastructure still deployed in mature basins.
- Cutter intellectual property:Patent thickets around leached-polycrystalline diamond geometries constrain design freedom for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Drill Bits Sales Market |
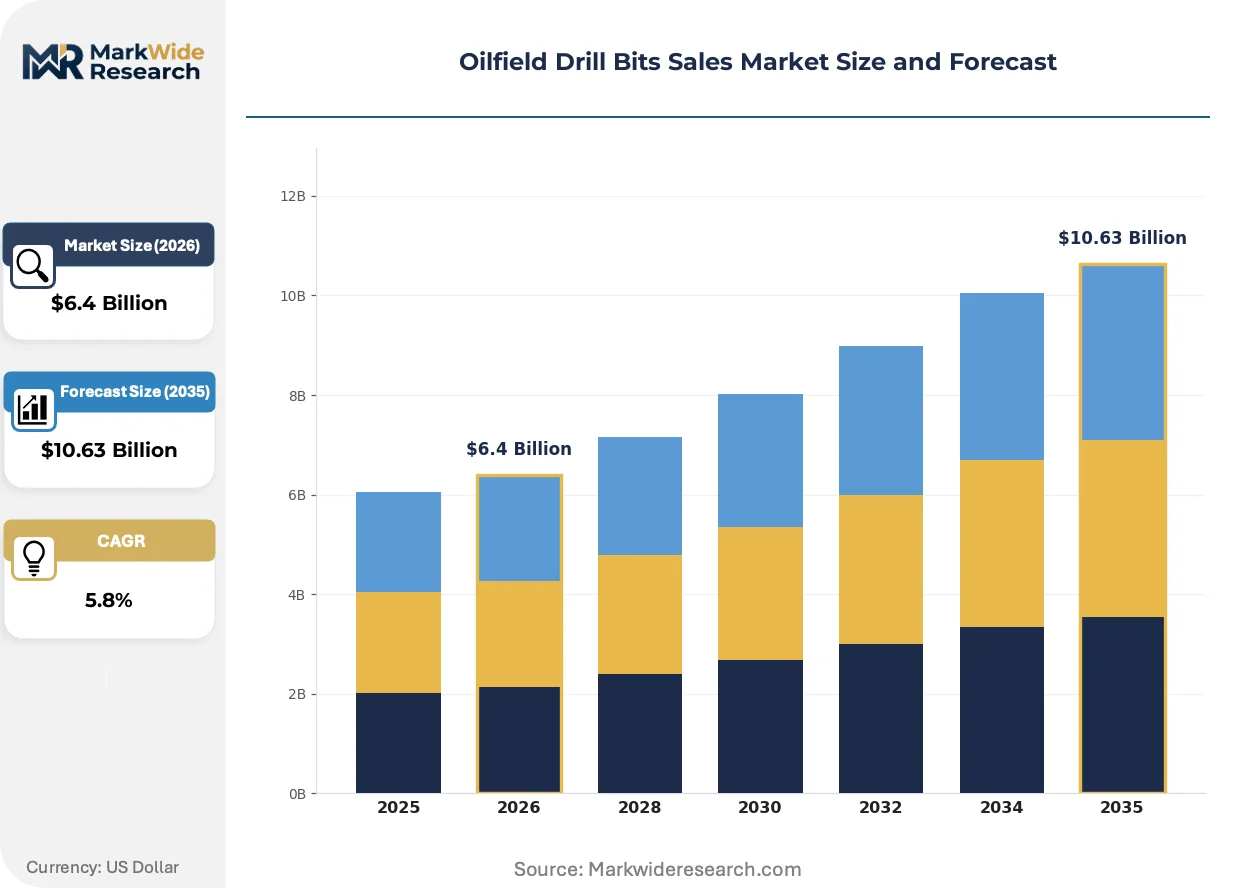
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bit Type: Diamond, Tricone, PDC, Roller Cone Material: Carbide, Steel, Composite, Ceramics Application: Onshore, Offshore, Mining, Exploration Drilling Technique: Rotary, Directional, Horizontal, Vertical |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, National Oilwell Varco, Varel International, Atlas Copco, Drill King International, Drilling Products, Kingdream Public Limited Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Drill Bits Sales Market Trends and Innovations
Real-time formation evaluation and predictive cutter wear modeling are compressing the traditional trial-and-error cycle of bit selection, enabling operators to specify performance contracts tied to footage guarantees rather than tool rental rates.
Thermally stable polycrystalline (TSP) cutters with engineered cobalt depletion are displacing conventional PDC inserts in high-temperature shale intervals where thermal degradation previously limited run lengths. Bakken operators in North Dakota have adopted TSP-enhanced layouts for 12,000-foot laterals, reducing bit trips from three to two per well. The technology is displacing premium steel-tooth roller cone residual demand in medium-hard carbonate stringers.
EPA methane performance standards for new and modified oil and gas facilities are accelerating bit specifications that minimize connection time and reduce total drilling days. Operators in the Permian and Eagle Ford now weight bit selection toward footage-per-day metrics rather than instantaneous rate-of-penetration. Service companies respond by integrating anti-balling coatings and optimized nozzle configurations that sustain ROP in sticky clay formations without excessive reaming.
Integrated drilling contracts bundle bits with downhole motors and telemetry in single-line-item pricing, collapsing the traditional separation between tool supplier and directional service provider. Large independents in the Delaware Basin have shifted 60% of bit procurement to these bundled arrangements, marginalizing standalone bit vendors. The model concentrates procurement authority with integrated service companies and compresses price transparency for cutter-grade differentiation.
Oilfield Drill Bits Sales Market Segmentation
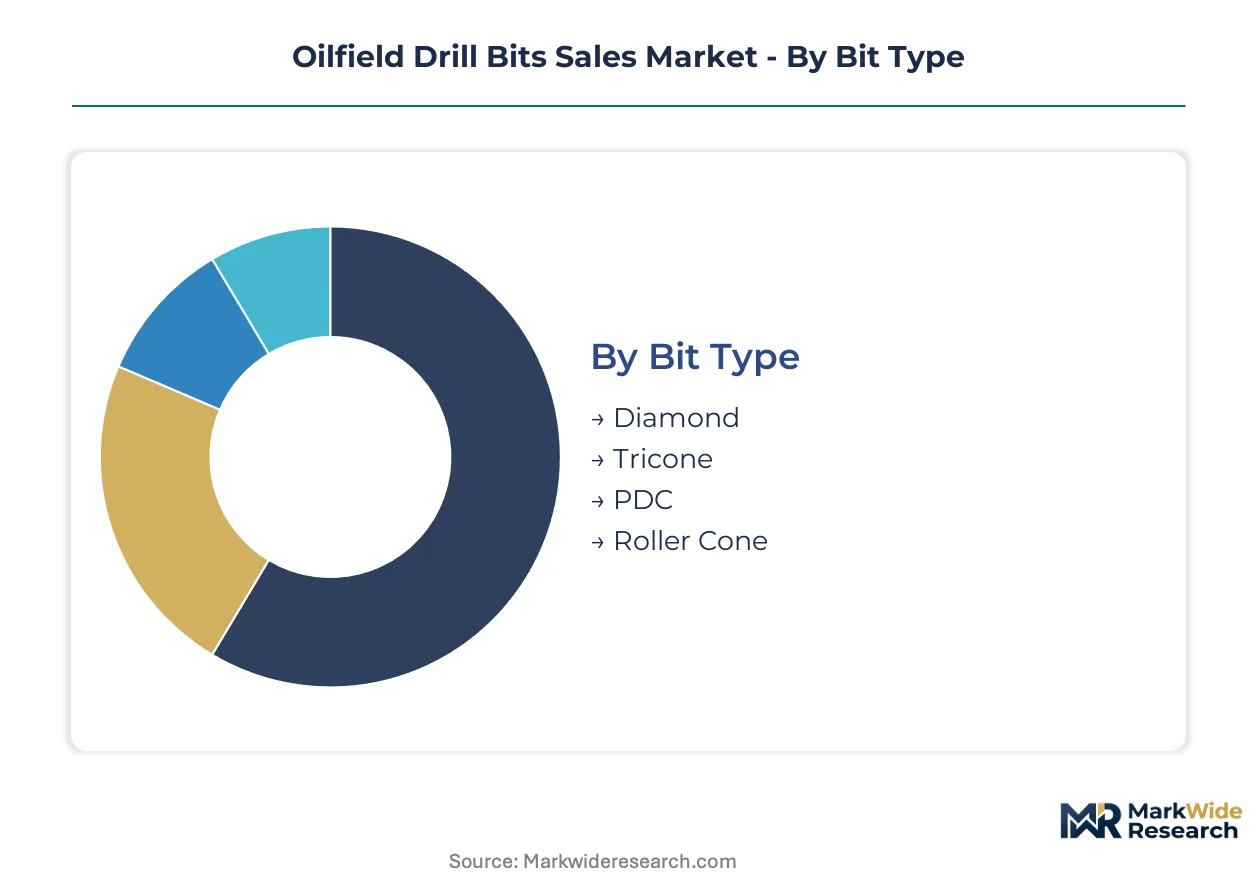
Bit specification choices in the Oilfield Drill Bits Sales Market cascade through procurement budgets, inventory stocking, and supplier qualification protocols. Operators align cutter material and body geometry with formation hardness, directional complexity, and regulatory footage requirements.
Bit Type:
API Q2 certification requirements and ISO 10424-1 performance testing create divergent compliance burdens across bit architectures, elevating documentation costs for complex designs.
- PDC:Polycrystalline diamond compact cutters bond synthetic diamond to tungsten carbide substrates for shearing action in medium-hard shale. Permian Basin laterals exceeding 15,000 feet consume three to four PDC bits per wellbore, with footage guarantees now standard in procurement contracts.
- Roller Cone:Forged steel cones with milled teeth or tungsten carbide inserts crush rock through impact and compression loading. Operators in interbedded formations across West Texas retain roller cone deployment where PDC thermal degradation risk exceeds replacement economics.
- Tricone:Three-cone rotary designs dominate mature basin replacement cycles where drilling intensity has declined and tool cost outweighs footage optimization.
- Diamond:Natural and synthetic diamond-impregnated bits penetrate the hardest crystalline formations in geothermal and deep exploration targets.
Established volume favors PDC configurations; emerging adoption favors diamond-impregnated designs for high-temperature geothermal penetration.
Material:
Raw material sourcing geography and ore processing concentration expose bit fabricators to supply volatility that propagates through tiered pricing structures.
- Tungsten Carbide:Sintered tungsten carbide-cobalt composites form the structural backbone of roller cone inserts and PDC substrates. African ore supply disruptions transmit directly to insert fabrication costs, compressing margins for non-integrated suppliers.
- Steel:Forged alloy steel bodies for roller cone and tricone bits leverage established North American forging capacity with shorter lead times than carbide-intensive alternatives.
- Composite:Polymer-matrix and hybrid material bits reduce weight for specialized coiled-tubing and slim-hole applications.
- Ceramics:Aluminum oxide and silicon nitride components address thermal stability thresholds beyond carbide limits in geothermal and deep gas drilling.
Procurement concentration clusters on carbide-dependent architectures; pilot deployment is climbing fastest for ceramic-enhanced high-temperature layouts.
Application:
Regulatory jurisdiction and emissions accountability reshape bit selection criteria across drilling environments, with EPA methane standards accelerating footage-per-day specifications.
- Onshore:Pad drilling and extended-reach laterals multiply bit consumption per wellbore in Texas and New Mexico shale plays. Delaware Basin operators now specify bits with anti-balling coatings and optimized nozzle configurations to sustain rate-of-penetration in sticky clay intervals.
- Offshore:Jack-up and semi-submersible rigs demand bits with redundant sealing and premium metallurgy for corrosive deepwater environments. Day-rate economics prioritize single-run footage over tool cost, favoring PDC with thermal-stable cutter enhancements.
- Mining:Blasthole and exploration drilling in hard-rock copper and iron ore applications adopt oilfield PDC technology for penetration efficiency.
- Exploration:Wildcat and appraisal drilling in frontier basins retains roller cone flexibility for unpredictable formation sequences.
Revenue gravity centers on onshore shale applications; offshore specification intensity produces the steepest margin expansion trajectory.
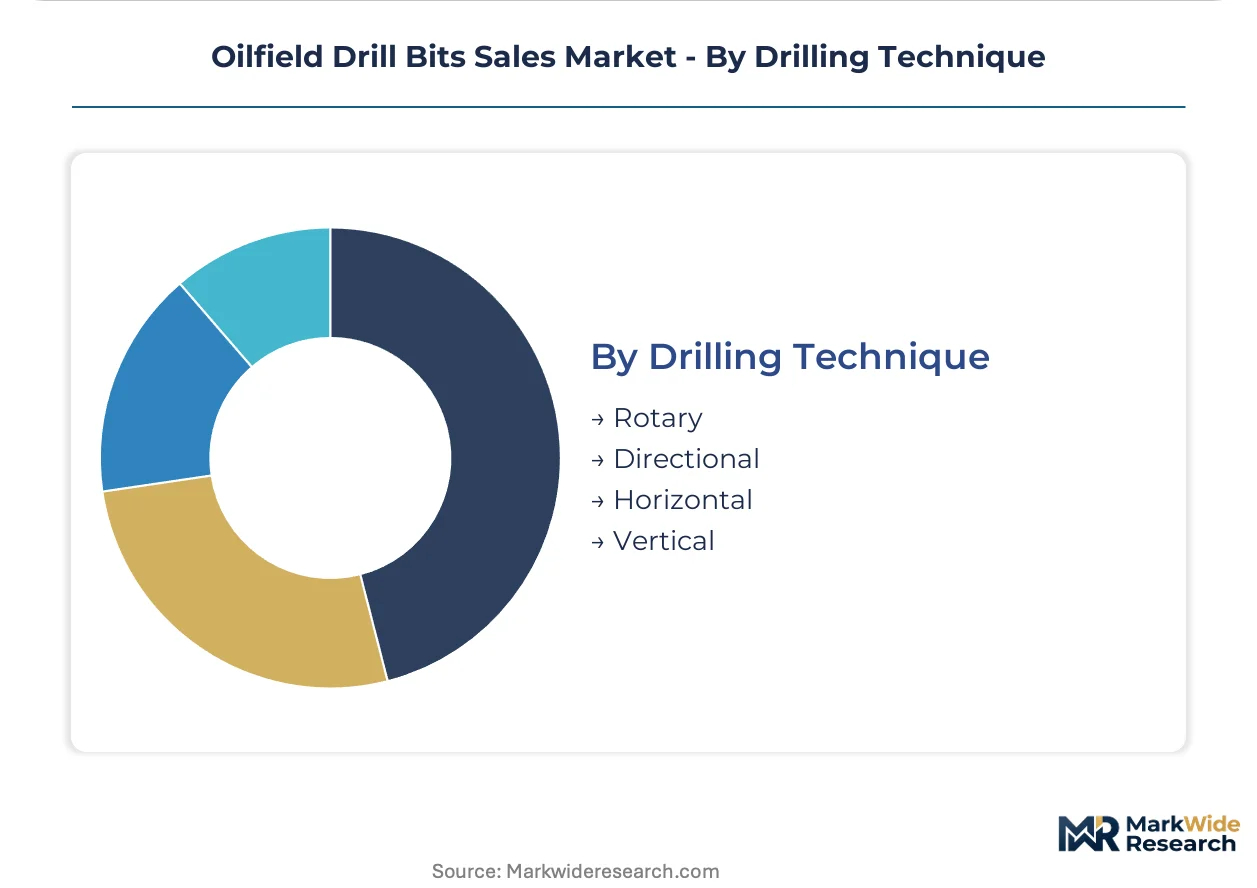
Drilling Technique:
Directional complexity and steerability requirements differentiate cutter layout optimization, with motor compatibility and build-rate predictability driving design priorities.
- Directional:Steerable motor and rotary steerable system compatibility demands asymmetric cutter layouts and gauge protection engineered for predictable toolface response. Bakken operators specify directional-optimized PDC for 12,000-foot laterals with dogleg severity management.
- Horizontal:Extended-reach lateral sections require bits that balance rate-of-penetration with directional holding in homogeneous shale targets.
- Rotary:Conventional rotary table drilling persists in vertical well programs and mining applications where steerability is not required.
- Vertical:Straight-hole drilling in conventional reservoirs and water well applications prioritizes cost efficiency over directional capability.
Deployment scale favors horizontal section bits; capability investment is concentrating fastest on directional steerability engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-manufactured drill bits flow primarily to shale operators in Texas and New Mexico, while Chinese fabricators supply carbide substrates to Southeast Asian assembly plants. German precision-tooling exports reach North Sea drilling contractors through Rotterdam transshipment hubs.
United States
Permian Basin laterals exceeding 15,000 feet consume three to four bits per wellbore, with Delaware Basin operators specifying anti-balling coatings for sticky clay intervals. EPA methane performance standards for new facilities accelerate footage-per-day specifications over instantaneous rate-of-penetration metrics. Houston hosts the densest cluster of directional drilling service companies, where integrated contracts now bundle bits with downhole telemetry.
China
Synthetic diamond substrate production concentrates in three manufacturing centers supplying polycrystalline diamond compact cutters globally. GB standards and MIIT industrial policy guide domestic bit qualification protocols for state-owned oilfield service procurement. Sichuan-Chongqing shale plays drive regional consumption of PDC bits rated for 200°C bottom-hole temperatures in deep gas targets.
Germany
European geothermal developers in the Upper Rhine Valley seek bits rated for crystalline basement penetration at 200°C thresholds. EU Green Deal drilling efficiency mandates favor carbon-intensity disclosures that minimize engine runtime per meter drilled. Bavaria's precision-machining corridor supplies gauge protection components and steerable motor compatibility systems to North Sea contractors.
Saudi Arabia
Horizontal drilling intensity in the Ghawar and Khurais fields sustains demand for premium PDC configurations with thermal-stable cutter enhancements. The country's national oil company procurement frameworks prioritize footage guarantees and reduced non-productive time in integrated service contracts. Eastern Province fabrication yards assemble roller cone variants for abrasive carbonate stringers where impact loading exceeds PDC durability thresholds.
Brazil
Pre-salt carbonate drilling in the Santos Basin retains roller cone flexibility for interbedded formations where unpredictable sequences favor impact-crushing action. ANVISA-equivalent petroleum regulator specifications govern material certification for deepwater bit deployments. Rio de Janeiro serves as the procurement hub for jack-up and semi-submersible rig operators prioritizing single-run footage over tool cost.
Oilfield Drill Bits Sales Market Competitive Landscape
Player mix skews toward integrated oilfield service conglomerates with captive bit manufacturing divisions. The vendor base concentrates around three strategic tiers: diamond synthesis specialists controlling substrate quality from raw material to finished insert; forge-and-machine scale operators running multiple North American production centers; and regional fabricators competing on lead time for replacement tricone demand. Dominant competitive moves include backward integration into tungsten carbide powder processing and technology licensing agreements for leached-polycrystalline diamond geometries.
Among US-based integrated service providers, Schlumberger Limited, Baker Hughes Company, and Halliburton Company occupy positions exemplifying the bundled-contract archetype, where bits anchor single-line-item pricing alongside downhole motors and telemetry systems. These entities represent the premium-tier vector where procurement authority concentrates and price transparency for cutter-grade differentiation compresses. Chinese specialists including Kingdream Public Limited Company sit within the manufacturing-scale tier, supplying carbide-intensive architectures to Asia-Pacific shale and geothermal markets.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| National Oilwell Varco |
| Varel International |
| Atlas Copco |
| Drill King International |
| Drilling Products |
| Kingdream Public Limited Company |
| Others |
Pricing and Supply Chain Analysis
Integrated drilling contracts lock in multi-year bit supply commitments while collapsing price transparency for cutter-grade differentiation, binding Permian Basin operators to footage-guarantee structures that obscure true per-insert costs beneath bundled line-item pricing.
Pricing Analysis
Next-generation thermally stable polycrystalline cutter layouts command 35-50% premiums over conventional PDC configurations, while legacy steel-tooth roller cone variants trade at commodity-equivalent levels in mature basin replacement cycles. Three-tier pricing structure across premium thermal-stable, standard leached-PDC, and economy import-grade cutters stratifies procurement budgets, with API Q2 certification tiers and footage-guarantee terms driving differentiation. Pricing pressure stems from integrated service bundling that marginalizes standalone bit vendors and compresses margin visibility. Independent shale operators exhibit highest price sensitivity in tricone replacement demand, while offshore contractors prioritize single-run footage over tool cost.
Supply Chain Analysis
Strategic stockpiling of tungsten carbide powder and synthetic diamond substrates dominates inventory strategy among North American forge operators, buffering against African ore supply disruptions and Asian polycrystalline diamond production concentration. Synthetic diamond substrate fabrication clusters in China, with tungsten carbide powder processing anchored in the US and Germany, while finished bit assembly distributes across Texas, Oklahoma, and Alberta. Raw material dependencies center on cobalt-bound tungsten carbide composites, synthetic diamond feedstock, and forged alloy steel bodies. Single-source vulnerability in high-quality polycrystalline diamond substrate production creates supply chain risk. Distribution runs through integrated service company procurement networks and independent distributor channels serving replacement tricone demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from real-time bit telemetry and predictive wear analytics is expanding faster than hardware sales, as footage-guarantee contracts embed recurring diagnostics fees that outpace standalone tool margins.
For Market Incumbents: Consolidate procurement authority through deeper backward integration into tungsten carbide powder processing, securing captive supply against African ore volatility. Expand thermal-stable polycrystalline cutter manufacturing capacity in Texas to meet Permian Basin 200°C bottom-hole temperature specifications. Defensive priority centers on patent licensing agreements for leached-polycrystalline diamond geometries that constrain mid-tier design freedom. For New Entrants and Emerging Players: Differentiate on geothermal-rated bit architectures for European developers in Germany and France seeking crystalline basement penetration at 200°C thresholds. Target white-space in ceramic-enhanced high-temperature layouts for deep Sichuan-Chongqing gas targets. Penetrable entry point sits with independent shale operators in the Delaware Basin seeking standalone bit vendors outside integrated contract structures. Go-to-market angle emphasizes machine-learning formation-matching platforms that optimize cutter layout selection. For Investors and Strategic Acquirers: Capital is best deployed toward diamond synthesis specialists controlling substrate quality from raw material to finished insert, capturing margin concentration in the supply chain's most defensible tier. Long-term viability across the analysis window hinges on thermal-stable polycrystalline technology roadmaps and geothermal expansion trajectories. Acquisition target archetype: mid-tier manufacturers with API Q2 certification infrastructure and underutilized forge capacity. Signal to watch: footage-guarantee contract penetration rates crossing thresholds that marginalize standalone bit vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Powder | Captive supply from African ore sources insulates margin compression from mining disruption volatility. |
| Thermal-Stable Polycrystalline Cutter Scale-Up | 200°C-rated inserts capture premium positioning in Permian extended-reach laterals and geothermal targets. |
| Machine-Learning Bit Selection Platform Launch | Formation-matching algorithms differentiate procurement value for independent operators outside bundled contracts. |
| Geothermal Certification Pathway Investment | EU Green Deal efficiency mandates favor carbon-intensity disclosures minimizing engine runtime per meter. |
| Integrated Telemetry System Partnership | Real-time wear analytics embed recurring revenue layers exceeding standalone hardware margins. |
Research Methodology
The analysis maps PDC, roller cone, tricone, and diamond-impregnated bit architectures, each validated through drilling engineers, procurement managers at independent shale operators, directional drilling service coordinators, and aftermarket distribution heads. Primary interviews with bit designers, forge operators, and carbide powder processors combined with secondary validation from API specification documentation, ISO 10424-1 test protocols, EPA methane performance standard filings, and customs trade data for tungsten carbide imports. Bottom-up volume builds triangulated against top-down expenditure estimates from exploration budget disclosures.
Consistency checks against rig count trajectories, footage-per-well trends, and replacement cycle frequencies validated output ranges across the projection horizon. Segmentation dimensions modeled include bit type, cutter material grade, application environment, and drilling technique complexity. CAGRs derived from rig activity intensity projections, lateral length expansion curves, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporate Permian Basin drilling intensity differentials and geothermal project development pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained shale lateral length expansion and API Q2 certification enforcement continuity; material deviation would warrant model refresh. Forecasts embed assumptions regarding synthetic diamond substrate supply stability and tungsten carbide ore sourcing geography. Revision becomes warranted when integrated contract penetration crosses thresholds that structurally alter standalone bit vendor viability or when geothermal drilling adoption accelerates beyond baseline scenario parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drilling Services Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Mud Balance Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
North America Shale Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Australia Oil and Gas Market