
 Germany Electric Vehicle Battery Manufacturing Market | 2026-2036
Germany Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Manufacturing Market Insights
Project finance tied to gigafactory construction is rewriting competitive entry conditions in German battery manufacturing. PowerCo leverages its captive offtake agreements with Volkswagen Group to anchor capacity commitments at its Salzgitter site. CATL sustains cost leadership through integrated cathode material production at its Erfurt facility. LG Energy Solution differentiates via high-nickel cell chemistry R&D executed from its Frankfurt R&D center.
Germany electric vehicle battery manufacturing encompasses the industrial production of electrochemical energy storage systems, typically lithium-ion cells with nickel-cobalt-manganese or lithium-iron-phosphate cathodes assembled into modules and packs for traction applications. These systems function as the primary propulsion power source, replacing internal combustion engines in road vehicles through reversible electrochemical reactions. Lithium-ion products dominate current output, though solid-state chemistries represent the fastest-growing development pipeline as OEMs target higher energy densities. Among end users, OEMs capture the largest value pool through long-term supply agreements, while fleet operators represent the fastest-growing demand segment as logistics electrification accelerates.
KBA type-approval requirements and the EU Battery Regulation's recycled-content mandates shape product specifications and market access conditions for manufacturers serving German vehicle producers. REACH compliance for chemical substances in electrolytes and separator materials adds further compliance layers to imported cell components. Stakeholders must monitor how delegated acts under the EU Battery Regulation define performance thresholds and carbon intensity benchmarks that will determine which production assets qualify for preferential OEM sourcing.
Market Dynamics
EU Battery Regulation carbon footprint declarations are forcing German OEMs to source from localized cell production rather than Asian imports, restructuring supplier qualification criteria around verified supply chain emissions data.
Growth Catalysts
- Baden-Württemberg Gigafactory Clustering:Concentrated cathode precursor and separator supplier networks within 150 kilometers of assembly plants compress logistics costs and inventory cycles for cell manufacturers.
- REACH Electrolyte Compliance:Pre-registered chemical substance inventories enable faster market authorization for domestically formulated electrolyte salts versus imported alternatives subject to full registration timelines.
- Logistics Fleet Electrification:Commercial vehicle operators in Lower Saxony and North Rhine-Westphalia are signing 7-10 year battery service contracts that guarantee offtake volumes for local production lines.
Market Restraints
- Lithium Hydroxide Import Dependence:Battery-grade lithium hydroxide feedstock concentrates in Chilean and Australian hard-rock spodumene processing, exposing German cell plants to freight rate volatility and currency fluctuation.
- Graphite Anode Supply Concentration:Synthetic and natural graphite for anode active material originates predominantly from Heilongjiang province processing facilities, creating single-source vulnerability for European battery manufacturers.
- EU Battery Regulation Delegated Acts:Pending technical specifications for recycled content verification and carbon intensity calculation methodologies delay final investment decisions on greenfield plant expansions.
Strategic Opportunities
- Solid-State Electrolyte Convergence:Sulfide-based ceramic electrolyte manufacturing combines thin-film deposition expertise from semiconductor equipment suppliers with existing roll-to-roll electrode coating infrastructure.
- Thuringia LFP Chemistry Expansion:Lithium-iron-phosphate cell production for entry-segment passenger vehicles remains underdeveloped relative to nickel-cobalt-manganese capacity, opening margin recovery potential through simpler thermal management requirements.
- Second-Life Stationary Storage:Retired automotive battery packs from Munich and Stuttgart fleet operators create a feedstock stream for grid-scale energy storage refurbishment before final recycling.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:German technical universities produce fewer than 400 specialized battery cell engineers annually against projected demand from Salzgitter, Erfurt, and planned Upper Palatinate facilities.
- KBA Type-Approval Timeline Compression:New cell formats require 18-24 month homologation cycles that misalign with 12-month vehicle platform launch schedules, forcing parallel development cost duplication.
- Dry Electrode Coating Scale-Up:Solvent-free electrode manufacturing reduces energy intensity but requires precision calendering equipment that lacks established maintenance protocols in European supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Manufacturing Market |
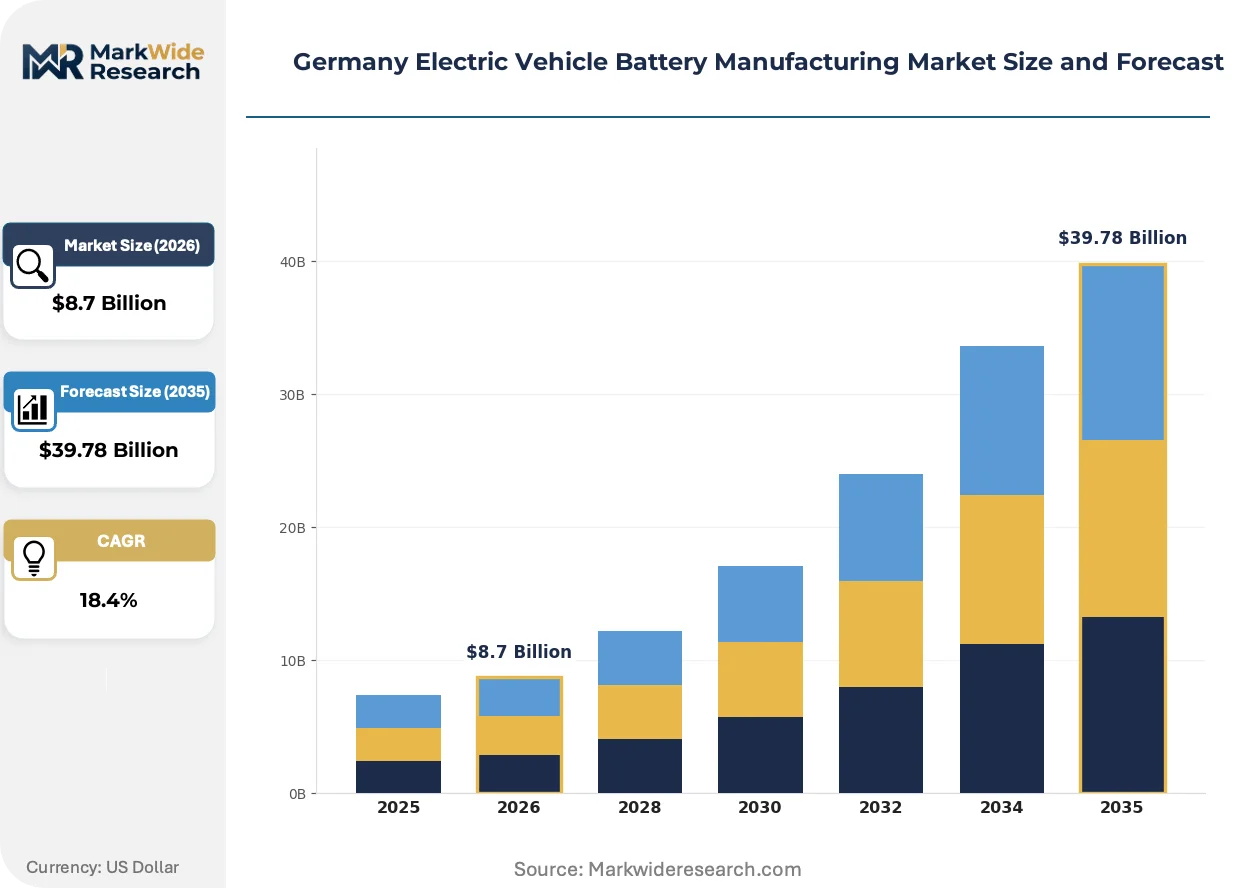
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid State, Nickel-Metal Hydride, Lead-Acid End User: OEMs, Aftermarket Providers, Fleet Operators, Consumers Technology: Fast Charging, Wireless Charging, Battery Management Systems, Energy Density Improvements Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | CATL, LG Energy Solution, Samsung SDI, PowerCo, BMZ Group, VARTA AG, AKASOL, DRÄXLMAIER Group, LEAPENERGY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Manufacturing Market Trends and Innovations
Solid-state cell architectures and dry electrode manufacturing processes are collapsing conventional lithium-ion production economics, while regulatory pressure on supply chain traceability reconfigures procurement relationships between German OEMs and material suppliers.
Silicon-dominant anode formulations are collapsing the energy density gap between current-generation NCM cells and next-generation solid-state targets. BMW Group and Mercedes-Benz AG have accelerated qualification timelines for silicon oxide blends exceeding 10% weight fraction, compressing the commercialization window for pure silicon nanowire alternatives. Cell suppliers with established roll-to-roll slurry coating lines are retrofitting binder systems to accommodate silicon volume expansion without requiring entirely new capital equipment.
EU Battery Regulation delegated acts on carbon footprint methodology are mandating granular scope 3 emissions disclosure from mine to module. German OEM procurement teams are disqualifying cell suppliers unable to provide batch-level lithium, cobalt, and nickel provenance documentation, shifting contract awards toward vertically integrated producers with captive mining offtake. This regulatory friction most severely impacts mid-tier cell manufacturers dependent on spot-market cathode active material.
Fleet operators are consolidating battery procurement through energy-as-a-service platforms rather than capital purchase models. Logistics providers in the Rhine-Ruhr corridor are outsourcing cell ownership to specialized asset managers who retain residual value risk and handle end-of-life logistics, transferring balance sheet burden from vehicle operators to financial intermediaries. This structural shift is most advanced among parcel delivery networks subject to municipal zero-emission zone mandates in Cologne, Düsseldorf, and Dortmund.
Germany Electric Vehicle Battery Manufacturing Market Segmentation
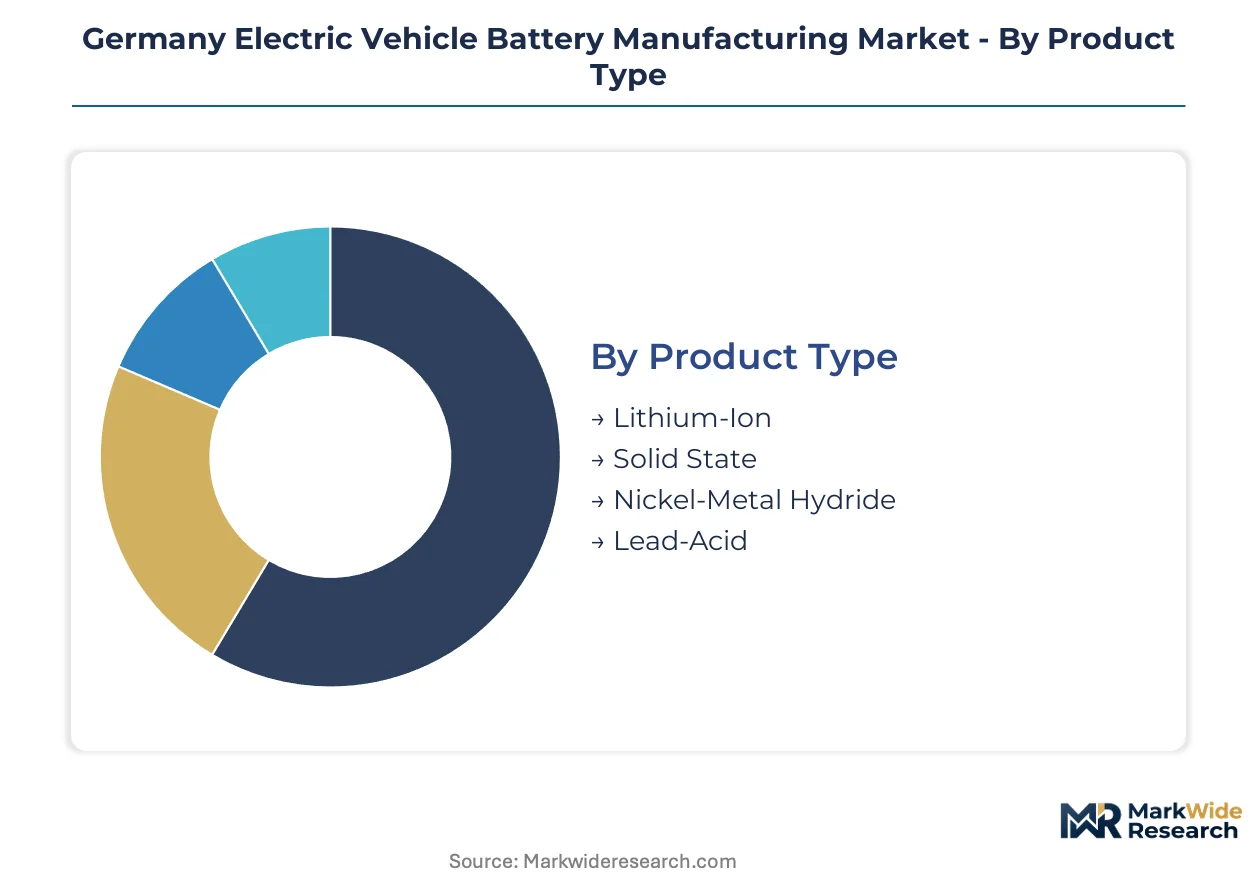
German battery manufacturing segments exhibit divergent investment cycles, with cell chemistry formats turning over every 5-7 years while application categories shift on 12-18 month vehicle platform timelines. Procurement patterns across these dimensions determine which production assets capture preferential OEM offtake under EU Battery Regulation compliance frameworks.
Product Type:
Cycle times vary sharply: lithium-ion formats iterate on 18-month cathode chemistry revisions, solid-state architectures require 4-6 year development horizons, while legacy lead-acid maintains decade-long replacement schedules for commercial starter applications.
- Lithium-Ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathode configurations constitute current production capacity at Salzgitter and Erfurt facilities. Demand concentrates in Baden-Württemberg passenger vehicle assembly plants where 800V architectures require high-rate discharge performance.
- Solid State:Sulfide-based ceramic electrolyte cells promise energy densities exceeding 400 Wh/kg through elimination of liquid electrolyte fire risk. Pilot lines in Bavaria and North Rhine-Westphalia target qualification completion ahead of premium OEM platform launches.
- Nickel-Metal Hydride:Toyota-affiliated suppliers maintain limited production for hybrid electric vehicle applications where cost sensitivity outweighs energy density requirements.
- Lead-Acid:Starter battery manufacturing persists in Saxony for internal combustion vehicle residual production and commercial vehicle auxiliary power units.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive OEM supply agreements from operational expenditure models emerging in fleet segments.
- OEMs:Volkswagen Group, BMW Group, and Mercedes-Benz AG negotiate multi-year capacity reservations with minimum volume guarantees and carbon footprint verification requirements under delegated acts.
- Fleet Operators:Logistics providers in Lower Saxony and North Rhine-Westphalia are consolidating procurement through battery-as-a-service contracts that transfer residual value risk to specialized asset managers.
- Aftermarket Providers:Independent repair networks source replacement packs for out-of-warranty vehicles, facing KBA type-approval barriers that favor OEM-certified remanufacturing channels.
- Consumers:Direct retail channel remains underdeveloped for traction batteries due to installation complexity and safety certification requirements.
OEMs dominate installed base. Fleet operators are climbing the fastest.
Technology:
Application context determines which performance vectors command premium positioning versus commoditization pressure.
- Fast Charging:350kW capable cell architectures with enhanced thermal management enable 10-80% state-of-charge cycles in under 20 minutes for highway corridor deployment.
- Battery Management Systems:State-of-estimation algorithms and cell balancing electronics differentiate pack-level offerings through predictive maintenance integration and warranty term extension.
- Energy Density Improvements:Silicon-dominant anode blending and high-nickel cathode ratios push gravimetric performance boundaries for premium passenger vehicle range targets.
- Wireless Charging:Inductive pad systems for fleet depot automation remain pre-commercial in German applications due to efficiency penalties and infrastructure standardization gaps.
Battery Management Systems dominate installed base. Fast Charging is gaining share fastest.
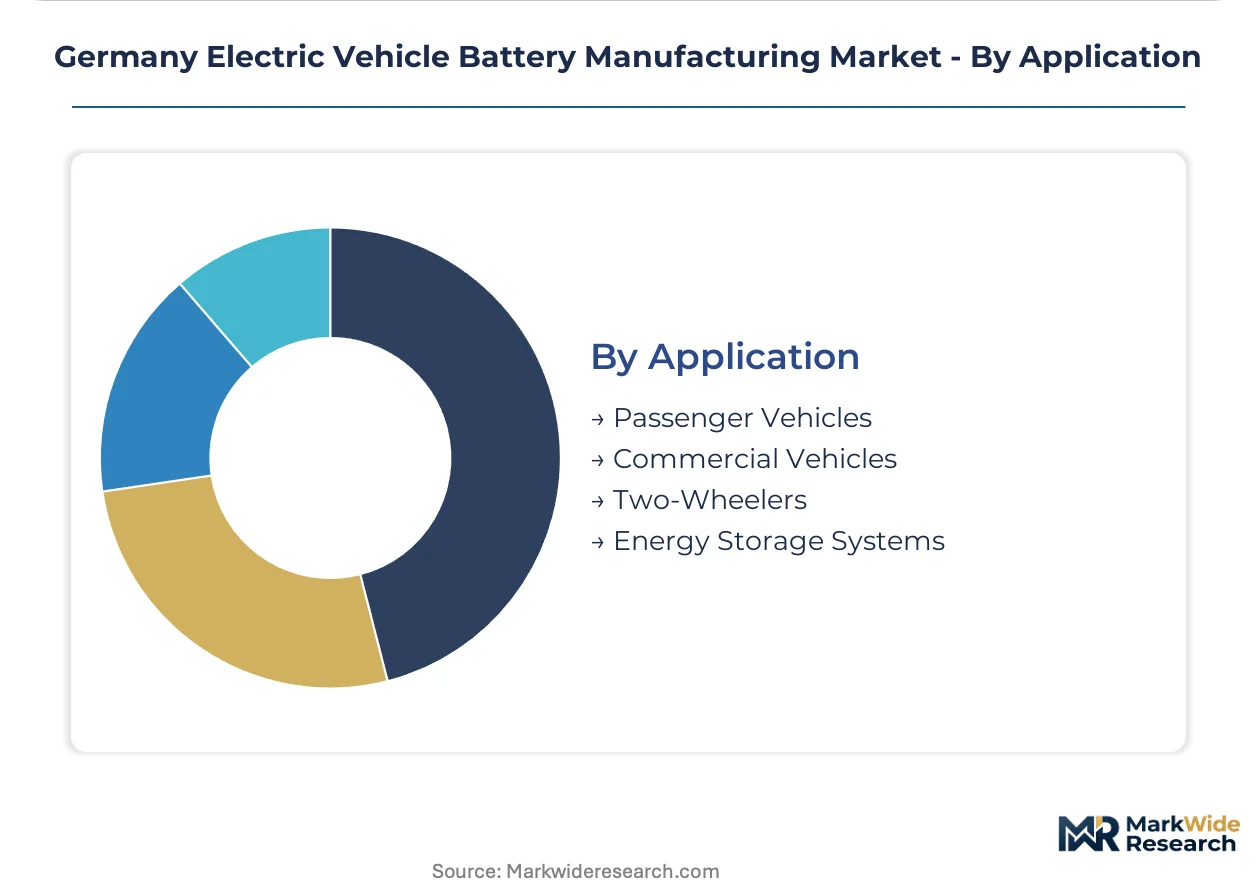
Application:
Volume concentration and margin structure diverge across mobility categories with distinct duty cycles and regulatory treatment.
- Passenger Vehicles:C-segment and D-segment platforms drive cell format standardization, with 590mm prismatic modules achieving scale economies across multiple OEM architectures.
- Commercial Vehicles:Heavy-duty truck and bus applications in the Rhine-Ruhr corridor favor LFP chemistry for thermal stability under continuous high-load operation with 7-10 year service life requirements.
- Energy Storage Systems:Second-life automotive pack refurbishment and dedicated grid-scale production create demand for cells with relaxed power density specifications and enhanced cycle life.
- Two-Wheelers:Micromobility applications in Berlin and Munich municipal zones utilize smaller format cylindrical cells with simplified thermal management.
Passenger Vehicles dominate installed base. Energy Storage Systems represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federal subsidies under the European Battery Innovation program and state-level investment guarantees are redirecting cell production capacity from Asian supply chains toward domestic gigafactory development. This policy architecture is concentrating manufacturing assets in specific Länder where automotive OEM assembly networks and chemical industry infrastructure overlap.
Baden-Württemberg
Passenger vehicle electrification at Mercedes-Benz and Porsche assembly plants drives cathode active material demand. The state's Ministry of Economic Affairs coordinates site development permits for cell manufacturing adjacent to existing powertrain facilities. Stuttgart and Heilbronn host precursor chemical suppliers feeding gigafactory clusters in the Neckar-Alb region.
Lower Saxony
Volkswagen Group's PowerCo subsidiary anchors industrial demand with multi-gigawatt capacity commitments at its Salzgitter site. KBA type-approval proximity accelerates prototype-to-production cycles for new cell formats. The Braunschweig-Wolfsburg corridor concentrates separator film and electrolyte salt suppliers within 100-kilometer logistics radius.
North Rhine-Westphalia
Commercial vehicle fleet operators in the Rhine-Ruhr corridor negotiate battery-as-a-service contracts with 7-10 year duration. The state's chemical industry heritage provides process engineering talent for electrode coating operations. Düsseldorf and Cologne host R&D facilities targeting LFP chemistry optimization for heavy-duty truck thermal management.
Thuringia
CATL's Erfurt facility exploits existing automotive supplier networks from the former East German precision engineering base. The Thuringian Ministry of Economy markets brownfield industrial sites with grid connection capacity for cell production expansion. Jena and Eisenach provide electrochemical engineering graduates from renovated technical university programs.
Bavaria
BMW Group's 46-series cylindrical cell qualification programs drive demand for high-nickel cathode pilot lines. The Bavarian State Government's High-Tech Agenda funds solid-state electrolyte research consortia linking Munich universities to equipment manufacturers. Ingolstadt and Dingolfing assembly plants require localized pack integration capacity to meet EU Battery Regulation carbon footprint thresholds.
Germany Electric Vehicle Battery Manufacturing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across German battery manufacturing. The market exhibits tiered concentration with integrated cell producers holding supply agreement leverage against modular pack assemblers. Three archetypes dominate: Asian-headquartered integrated manufacturers with European production bases, German OEM-captive cell producers with guaranteed offtake, and mid-scale pack integrators serving commercial vehicle retrofit markets. Capacity reservation contracts and carbon footprint verification capabilities constitute the primary competitive battlegrounds.
Among Asian-headquartered integrated manufacturers, CATL and LG Energy Solution exemplify the scale-driven archetype with established European production footprints. Samsung SDI occupies a position bridging premium automotive supply relationships with energy storage system diversification. These three entities anchor the competitive structure through their control over cathode material integration and cell format standardization.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Samsung SDI |
| PowerCo |
| BMZ Group |
| VARTA AG |
| AKASOL |
| DRÄXLMAIER Group |
| LEAPENERGY |
| Others |
Pricing and Supply Chain Analysis
Salzgitter's gigafactory cluster concentrates cathode precursor production capacity within 150 kilometers of Volkswagen Group assembly plants, compressing logistics costs and amplifying pricing power for localized cell suppliers against Asian import alternatives subject to EU Battery Regulation carbon footprint penalties.
Pricing Analysis
Certification level under EU Battery Regulation delegated acts creates the primary spread between qualified and non-qualified suppliers. Contract-based long-term offtake agreements dominate, with volume scale and carbon intensity verification as key price differentiation drivers. Cost compression in nickel-cobalt-manganese cells is intensifying because of silicon-anode retrofit investments. Fleet operators demonstrate highest price sensitivity through battery-as-a-service procurement, while premium OEMs prioritize carbon footprint compliance over unit cost.
Supply Chain Analysis
CATL's Erfurt facility and LG Energy Solution's Wroclaw-adjacent operations anchor European contract-manufacturing concentration for German OEM demand. Battery-grade lithium hydroxide draws from Chilean and Australian processing, synthetic graphite feeds from Heilongjiang province facilities, and separator films originate from South Korean extrusion plants. Single-source vulnerability in anode active material creates structural exposure to trade policy shifts. Distribution runs through captive OEM supply agreements with KBA type-approval integration rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German battery manufacturing exhibits fragmentation opportunity as EU Battery Regulation compliance requirements splinter procurement qualifications and create tiered supplier niches around carbon footprint verification capabilities.
For Market Incumbents: Pre-empt qualification bottlenecks by accelerating KBA type-approval pipelines for solid-state cell formats before delegated acts harden performance thresholds. Secure backward integration into lithium hydroxide offtake from Australian hard-rock spodumene operations to insulate against freight rate volatility. Lock in 7-10 year fleet service contracts in Lower Saxony to defend installed base against Asian cost leaders.
For New Entrants and Emerging Players: Thuringia LFP chemistry capacity remains underpenetrated relative to nickel-cobalt-manganese saturation, offering margin recovery through simpler thermal management and entry-segment vehicle targeting. Second-life stationary storage refurbishment in Munich and Stuttgart fleet corridors presents asset-light service model entry. Pursue battery-as-a-service platform partnerships with Rhine-Ruhr logistics operators to bypass capital-intensive cell manufacturing scale requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-focused asset managers retaining residual value risk through energy-as-a-service contracts. Long-term viability centers on producers with verified scope 3 emissions disclosure and captive mining offtake. Monitor delegated act implementation timelines for recycled content verification methodologies as inflection indicator for qualification-capable asset premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Pilot Line Deployment | Bavarian research consortia link Munich universities to equipment suppliers for sulfide-based ceramic manufacturing scale-up. |
| Silicon-Dominant Anode Retrofit | BMW Group and Mercedes-Benz AG qualification programs compress commercialization timelines for 10% weight fraction oxide blends. |
| LFP Chemistry Expansion in Thuringia | CATL's Erfurt facility exploits brownfield industrial sites with grid connection capacity for entry-segment passenger vehicle supply. |
| Battery-as-a-Service Platform Launch | Rhine-Ruhr logistics providers outsource cell ownership to asset managers handling end-of-life logistics under municipal zero-emission mandates. |
| Second-Life Stationary Storage Refurbishment | Retired automotive packs from Munich and Stuttgart fleets create feedstock streams for grid-scale energy storage before final recycling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of KBA type-approval databases, EU Battery Regulation delegated act drafts, and automotive production registration records. Executives at cell manufacturers, OEM platform engineers, cathode precursor suppliers, and fleet procurement directors provided structured input. Bottom-up capacity buildout tracking triangulates against top-down OEM electrification commitment aggregation.
Forecast inputs span cell chemistry format adoption curves, vehicle platform launch schedules, and EU Battery Regulation compliance phase-in trajectories. Segmentation dimensions include propulsion architecture, cathode chemistry configuration, end-user contract structure, and regional production cluster. CAGRs derive from installed base replacement cycles and greenfield capacity commissioning timelines across the analysis window.
Practitioners should monitor lithium hydroxide freight rate volatility, delegated act publication schedules, and silicon-anode qualification completion rates for early signals of forecast revision. Quarterly review of KBA type-approval throughput and PowerCo offtake contract renegotiation terms is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Japan EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market