
 Europe Wood Pellet Heating Systems Market | 2026-2036
Europe Wood Pellet Heating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wood Pellet Heating Systems Market Foresight
EN 303-5 certification for heating boilers is redrawing competitive boundaries across the European supply base. Viessmann leverages its testing laboratory network to fast-track compliance cycles for residential pellet boilers. Fröling anchors its position through specialized fabrication of high-efficiency combustion chambers for central European utilities.
Wood pellet heating systems convert compressed biomass feedstock into thermal energy through controlled gasification or grate combustion, typically achieving 85-95% efficiency in modern condensing configurations. Pellet boilers dominate installed value across multi-family housing and small commercial estates, while combined systems that integrate solar thermal or heat pump circuits capture the fastest-growing project pipeline. Smart control technology stratifies margin pools, with remote monitoring modules commanding premium pricing over manual equivalents in German and Austrian retrofit markets.
The EU Green Deal and F-Gas Regulation are tightening carbon accounting for building heat, while Ecodesign requirements under the European Commission's framework mandate minimum efficiency thresholds for new installations. National implementations vary: Germany's Federal Emission Control Act enforces stricter particulate limits than baseline EU standards, and Austria's regional subsidy offices tie funding to ÖNORM-certified equipment. Stakeholders must track how REPowerEU funding tranches shift between member states as fossil bridge fuel strategies evolve.
Market Dynamics
REPowerEU funding tranches are redirecting subsidy flows toward decentralized biomass heat, compressing installation timelines for residential pellet boilers across the Alpine corridor. This capital reallocation is reshaping competitive positioning among equipment fabricators and distribution networks.
Growth Catalysts
- EU Green Deal carbon accounting:Tightened building heat emissions standards under the European Commission's framework mandate biomass retrofits in existing housing stock.
- Multi-family housing retrofits:German and Austrian municipal housing associations are consolidating procurement for pellet boiler installations across estate portfolios.
- Condensing combustion technology:Modern configurations achieving 85-95% thermal efficiency are displacing legacy oil-fired systems in Bavarian and Slovenian districts.
Market Restraints
- Wood pellet feedstock volatility:Sawmill residue supply concentrates in Nordic and Baltic processing clusters, exposing central European buyers to transport cost swings.
- EN 303-5 certification timelines:Boiler testing laboratory capacity constraints in Germany and Austria extend product approval cycles by 4-8 months.
- Air-source heat pump substitution:REPowerEU subsidies increasingly flow toward electric alternatives in grid-decarbonized regions of France and the Netherlands.
Strategic Opportunities
- Solar thermal convergence:Combined pellet-solar systems that integrate heat pump circuits are capturing the fastest-growing project pipeline in northern Italy.
- Slovenian district heating:Underpenetrated municipal networks in Ljubljana and Maribor present white space for centralized pellet boiler installations.
- Smart control premium modules:Remote monitoring technology commands pricing power over manual equivalents in German and Austrian retrofit markets.
Industry Challenges
- ÖNORM certification complexity:Austria's regional subsidy offices tie funding to equipment standards that vary across federal states, fragmenting compliance workflows.
- Combustion chamber fabrication capex:High-efficiency chamber production requires specialized welding and ceramic lining investment that mid-cap fabricators struggle to fund.
- Legacy oil infrastructure integration:Retrofit projects must reconcile pellet boiler hydraulics with existing radiator networks designed for higher-temperature fossil heat.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wood Pellet Heating Systems Market |
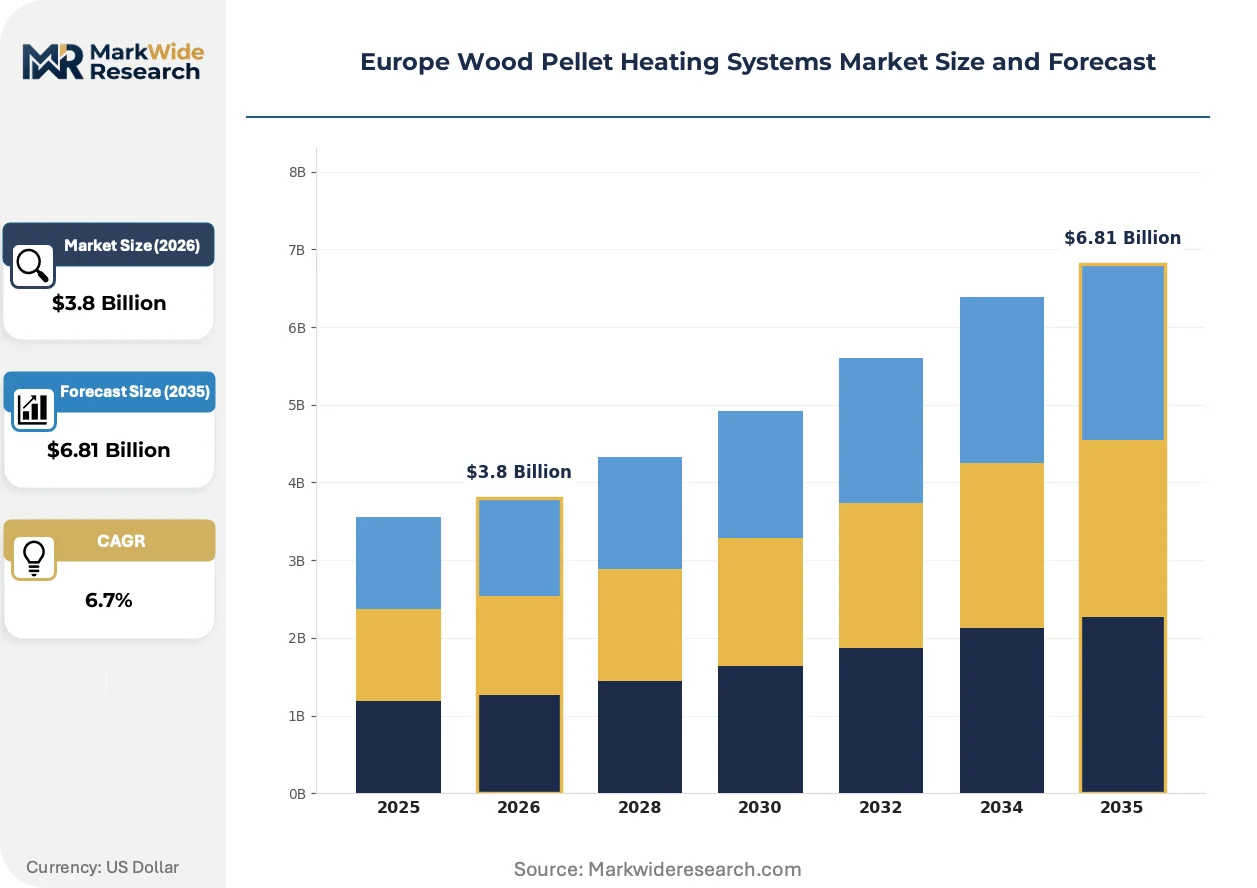
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellet Stoves, Pellet Boilers, Pellet Furnaces, Combined Systems End User: Residential, Commercial, Industrial, Government Installation Type: Vertical, Horizontal, Modular, Integrated Control Technology: Manual, Automatic, Smart, Remote |
| Companies Covered | Stora Enso Oyj, Drax Group PLC, Viessmann, Pfeifer Group, German Pellets GmbH, ÖkoFEN, AS Graanul Invest, Fröling, ETA Heiztechnik, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wood Pellet Heating Systems Market Shifts & Advancements
Smart control architecture is fragmenting traditional equipment value chains, separating hardware fabrication from software-enabled service layers. This decoupling creates new margin pools for connected heating platforms.
Lambda sensor-controlled combustion is fragmenting boiler performance tiers. The technology modulates air-fuel ratios in real-time, enabling consistent efficiency across varying pellet moisture content. Austrian and German residential installers are specifying lambda-equipped units for 60% of new retrofit quotes. Equipment without this capability is compressing into price-sensitive replacement markets in eastern Europe.
The EU F-Gas Regulation is tightening carbon accounting thresholds for building heat, accelerating biomass eligibility in national subsidy schemes. Member states must report embodied emissions for heating equipment procurement above defined capacity thresholds. German Federal Emission Control Act implementations enforce stricter particulate limits than baseline EU standards, forcing fabricators to maintain dual certification tracks.
Buyer procurement is consolidating around turn-key energy service contracts rather than equipment-only purchases. Housing associations in Bavaria and Baden-Württemberg now require 10-year thermal output guarantees bundled with installation. This shift compresses margins for pure-play boiler suppliers while expanding recurring revenue for integrated service providers. The pattern is most visible in German multi-family retrofits where capital constraints favor operational expenditure models.
Europe Wood Pellet Heating Systems Market Segmentation
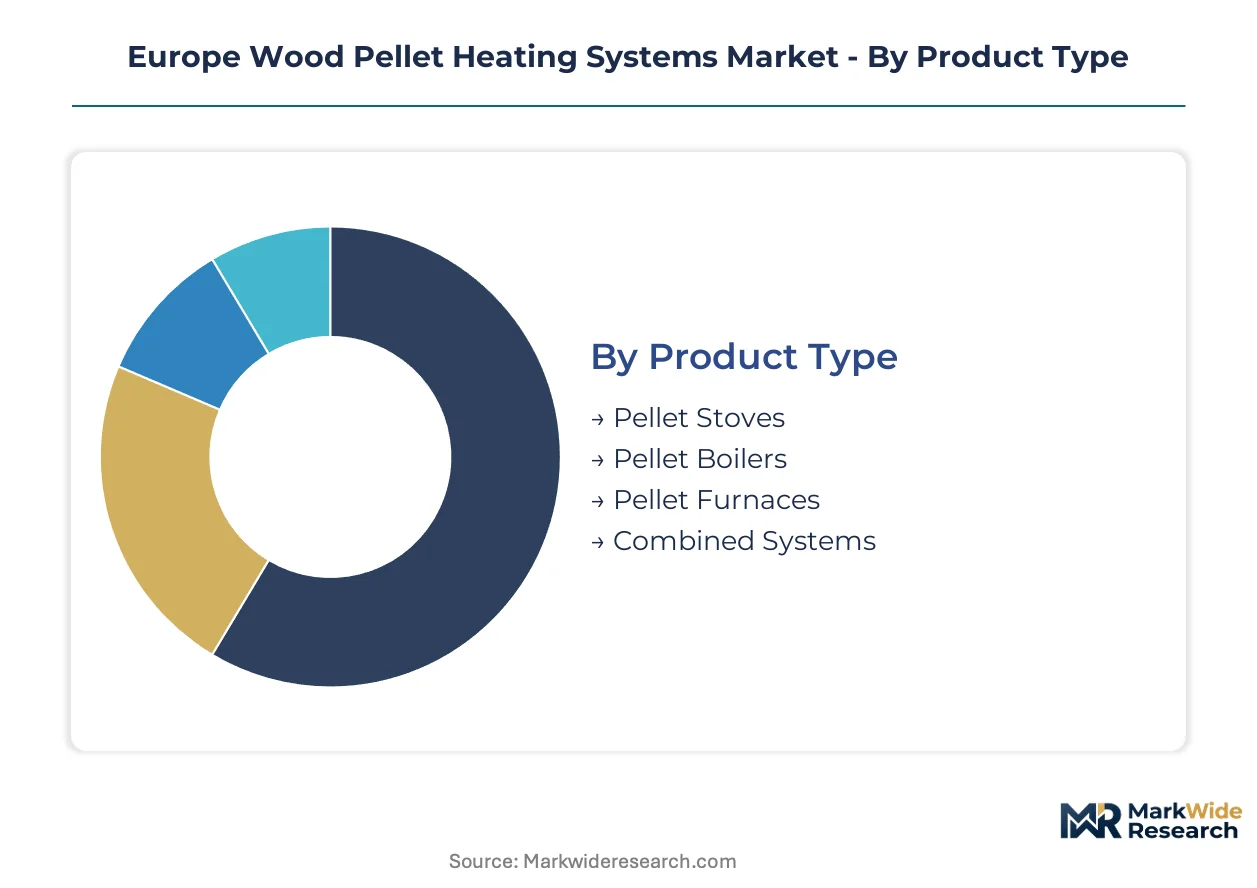
Wood pellet heating systems fragment across product architecture, end-use scale, installation topology, and control sophistication. Each dimension carries distinct certification burdens under EU Ecodesign and national implementations like Germany's Federal Emission Control Act.
Product Type:
EN 303-5 certification tiers separate residential from commercial equipment, with condensing efficiency thresholds tightening fastest for boiler categories.
- Pellet Boilers:Central heating units achieving 85-95% thermal efficiency in condensing configurations dominate multi-family housing retrofits across Bavaria and Baden-Württemberg. German municipal housing associations consolidate procurement for estate-wide installations, compressing vendor margins through volume bundling.
- Combined Systems:Integrated pellet-solar-heat pump hybrids capture the steepest expansion trajectory in northern Italy's Alpine districts. These configurations qualify for stacked REPowerEU subsidies while addressing seasonal load variability that pure pellet systems cannot match.
- Pellet Stoves:Room-scale units serve single-family retrofits in Austrian federal states with fragmented ÖNORM certification requirements.
- Pellet Furnaces:High-capacity units for industrial process heat concentrate in Slovenian district heating pilots.
Pellet boilers handle the majority of installed value; combined systems are climbing the fastest on project pipeline share.
End User:
Subsidy accessibility and capital intensity stratify procurement patterns across customer categories, with operational expenditure models gaining traction in capital-constrained segments.
- Residential:Single-family and multi-family retrofits in Germany and Austria drive volume, with smart control modules commanding premium pricing over manual equivalents. Lambda sensor-equipped boilers now specify into 60% of new Austrian retrofit quotes.
- Commercial:Small estates and hospitality operations in Slovenia's underpenetrated municipal networks present white space for centralized installations with 10-year thermal output guarantees.
- Industrial:Process heat applications concentrate in Nordic sawmill clusters with captive feedstock access.
- Government:Public building mandates under EU Green Deal carbon accounting accelerate biomass eligibility in national procurement schemes.
Residential captures the dominant share of unit installations; commercial is expanding most quickly on turn-key energy service contract adoption.
Installation Type:
Legacy infrastructure compatibility and hydronic integration complexity determine retrofit feasibility, particularly where existing radiator networks were designed for higher-temperature fossil heat.
- Integrated:Factory-assembled systems with pre-configured hydraulics reduce on-site commissioning time for German multi-family retrofits facing compressed REPowerEU installation timelines.
- Modular:Scalable configurations allow capacity expansion for growing commercial estates without full system replacement.
- Vertical:Compact footprints suit Alpine corridor basements with constrained mechanical room dimensions.
- Horizontal:Low-profile designs accommodate crawl-space installations in older Slovenian housing stock.
Integrated systems dominate new construction and full retrofits; modular configurations are gaining share fastest in phased commercial expansions.
Control Technology:
Margin stratification between hardware fabrication and software-enabled service layers fragments traditional equipment value chains, with remote monitoring creating recurring revenue pools.
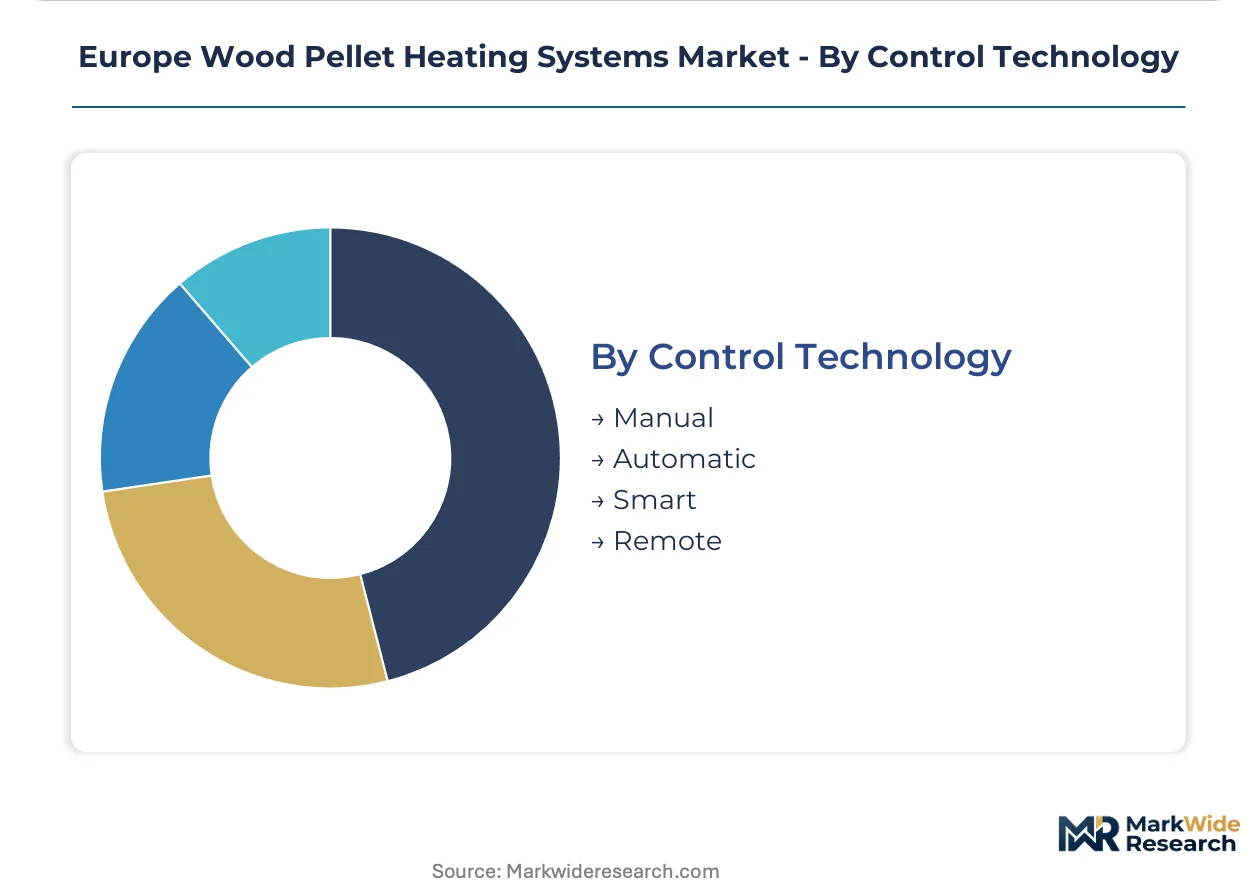
- Smart:Lambda sensor-controlled combustion with real-time air-fuel modulation enables consistent efficiency across varying pellet moisture content. Remote monitoring modules command pricing premiums in German and Austrian markets where housing associations require performance guarantees.
- Automatic:Programmable thermostatic control without network connectivity serves price-sensitive replacement markets in eastern Europe.
- Manual:Basic operator-adjusted settings persist in legacy installations and budget retrofits.
- Remote:Cloud-connected diagnostics and predictive maintenance capabilities expand fastest under turn-key service contracts bundling installation with long-term thermal output commitments.
Smart control handles the majority of new retrofit specifications; remote-enabled platforms are expanding most quickly on service contract bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel and Tauern Railway corridor underwrite Alpine pellet logistics, connecting Baltic sawmill clusters to Bavarian boiler fabricators through Innsbruck and Salzburg intermodal terminals.
Germany
Federal housing associations in Bavaria and Baden-Württemberg consolidate procurement for estate-wide pellet boiler retrofits. The Federal Emission Control Act enforces stricter particulate limits than baseline EU Ecodesign standards. Viessmann's testing laboratory network in Allendorf accelerates EN 303-5 certification cycles for residential condensing units.
Austria
Regional subsidy offices across Tyrol, Styria, and Upper Austria tie funding to ÖNORM-certified equipment with lambda sensor-controlled combustion. The national climate and energy strategy mandates biomass heat in public building refurbishments above defined capacity thresholds. Fröling anchors high-efficiency combustion chamber fabrication from its Upper Austrian base for central European utility contracts.
Italy
Alpine districts in South Tyrol and Trentino drive combined pellet-solar-heat pump hybrid installations that qualify for stacked REPowerEU subsidies. The national thermal account mechanism rewards building-level efficiency upgrades with transferable tax credits. Northern Italian installers specify smart control modules for 60% of new retrofit quotes in the Bolzano corridor.
Slovenia
Municipal networks in Ljubljana and Maribor present underpenetrated white space for centralized pellet boiler installations with 10-year thermal output guarantees. The national long-term climate strategy identifies district heating biomass conversion as a priority decarbonization pathway. Slovenian procurement offices favor integrated factory-assembled systems to compress on-site commissioning timelines.
Sweden
Nordic sawmill residue supply concentrates in Västerbotten and Gävleborg counties, exposing central European buyers to Baltic Sea freight cost volatility. The national carbon tax framework elevates pellet competitiveness against fossil heating oil in detached housing retrofits. Stora Enso's pellet production clusters in Härnösand and Varkaus supply feedstock through dedicated bulk terminal networks.
Europe Wood Pellet Heating Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification capacity and regional subsidy navigation. The vendor base stratifies into three tiers: integrated energy service providers bundling installation with long-term thermal guarantees, pure-play boiler fabricators competing on condensing efficiency specifications, and pellet producers securing captive feedstock through sawmill partnerships. Consolidation pressure concentrates among mid-cap fabricators unable to fund specialized combustion chamber welding and ceramic lining investment. Dominant competitive moves include backward integration into pellet supply chains and technology licensing partnerships for lambda sensor-controlled combustion systems.
Among German and Austrian fabricators, Viessmann, Fröling, and ÖkoFEN occupy positions within the premium-tier boiler segment. Viessmann represents the listed conglomerate archetype with diversified heating technology portfolios. Fröling exemplifies the family-owned specialist model focused on high-efficiency combustion engineering. ÖkoFEN sits within the Austrian private fabricator tier with concentrated regional subsidy office relationships. These three anchors illustrate how certification laboratory access and ÖNORM compliance workflows separate competitive positions across the Alpine corridor procurement landscape.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Drax Group PLC |
| Viessmann |
| Pfeifer Group |
| German Pellets GmbH |
| ÖkoFEN |
| AS Graanul Invest |
| Fröling |
| ETA Heiztechnik |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Baltic pellet producers and Alpine corridor utilities lock in both feedstock access and price visibility across multi-year horizons, insulating German and Austrian housing associations from spot market volatility while compressing margins for uncontracted mid-cap buyers.
Pricing Analysis
Volume-discount tiering structures separate municipal housing association procurement from single-family retrofits, with EN 303-5 certification grade and lambda sensor inclusion driving price differentiation between premium and standard equipment tiers. Cost compression in manual-control boilers is intensifying because air-source heat pump subsidies are siphoning REPowerEU capital toward electric alternatives. Single-family residential buyers in eastern Europe exhibit the highest price sensitivity, while German multi-family associations prioritize performance guarantees over unit economics.
Supply Chain Analysis
Brenner Base Tunnel rail capacity acts as a chokepoint for pellet flows from Nordic sawmill clusters to Bavarian boiler fabricators, with Innsbruck and Salzburg intermodal terminals determining delivery reliability across the Alpine corridor. Feedstock supply draws from Sweden, Finland, and Estonia, while combustion chamber fabrication rests on specialized ceramic lining and precision welding inputs. Single-source vulnerability concentrates in Baltic Sea freight lanes exposed to winter ice constraints. Distribution runs through vertically integrated energy service providers bundling installation with long-term thermal output commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's wood pellet heating market sits in early-cycle expansion, with REPowerEU subsidy tranches accelerating biomass retrofits ahead of F-Gas Regulation carbon accounting deadlines.
For Market Incumbents: Consolidate laboratory certification capacity to compress EN 303-5 approval timelines as testing backlogs extend product launch windows. Acquire specialized combustion chamber fabrication capabilities to defend against mid-cap fabricators seeking Austrian utility contracts. Air-source heat pump substitution in grid-decarbonized regions presents the most acute substitution threat. For New Entrants and Emerging Players: ÖNORM fast-track certification through Tyrol and Styria regional subsidy offices unlocks Austrian federal state procurement pipelines. Slovenian district heating networks in Ljubljana and Maribor offer the most penetrable white space for centralized boiler installations. Position through turn-key energy service contracts bundling 10-year thermal guarantees to bypass capital-constrained municipal procurement barriers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated energy service providers with captive pellet supply agreements and remote monitoring platform revenue. The 5-10 year viability window favors asset-light service models over pure-play fabrication exposed to commodity feedstock swings. Watch REPowerEU funding tranche reallocation between member states as the critical inflection signal for geographic exposure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pellet Supply | Captive feedstock access insulates German fabricators from Baltic freight cost volatility. |
| Lambda Sensor Technology Licensing | Real-time combustion control separates premium boiler tiers in Austrian retrofit specifications. |
| Remote Monitoring Platform Deployment | Cloud-connected diagnostics create recurring revenue pools beyond equipment-only sales. |
| ÖNORM Certification Fast-Tracking | Regional subsidy office relationships accelerate funding access in Tyrol and Styria. |
| Turn-Key Service Contract Bundling | Operational expenditure models align with Bavarian housing association capital constraints. |
Research Methodology
Operator-level perspectives from boiler fabrication engineers, municipal housing association procurement directors, regional subsidy office administrators, and pellet supply chain managers anchored the qualitative base. Secondary validation drew from EU Ecodesign implementation documents, REPowerEU funding allocation disclosures, EN 303-5 certification registries, and Nordic sawmill production statistics. Bottom-up equipment shipment data triangulated against top-down subsidy disbursement records to establish market sizing boundaries.
Sensitivity analysis tested forecast outputs against variable REPowerEU funding trajectories and feedstock cost assumptions across the projection horizon. Segmentation modeling incorporated product architecture, end-use scale, installation topology, and control sophistication dimensions alongside combustion efficiency tier. CAGRs derived from fitted adoption curves reflecting regulatory deadline effects and housing stock retrofit penetration rates. Lambda sensor specification share and turn-key contract adoption velocity served as industry-specific demand indicators.
Decision-makers should treat outputs as directional under sustained REPowerEU biomass subsidy commitment and stable Baltic pellet supply assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation carbon accounting thresholds and air-source heat pump subsidy competitiveness evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market