
 South and Central America Oil Field Services Market | 2026-2036
South and Central America Oil Field Services Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America Oil Field Services Market Analytics
Independent oil producers is redrawing procurement priorities across the South and Central America oil field services landscape, shifting contract structures toward integrated service packages. Schlumberger leverages its digital drilling portfolio to anchor long-term relationships with pre-salt operators. Halliburton competes through specialized completion technologies tailored to high-pressure carbonate reservoirs. Baker Hughes Company differentiates via artificial lift systems optimized for subsea tieback architectures.
Oil field services encompass the specialized equipment, technical labor, and engineered systems required to drill, complete, maintain, and enhance hydrocarbon production from subsurface reservoirs, with pressure ratings often exceeding 15,000 psi and temperature tolerances surpassing 150°C for deepwater applications. Drilling services command the largest revenue pool given sustained pre-salt activity, while completion services represent the fastest-growing segment as operators target complex carbonate formations requiring multi-stage fracture designs. Hydraulic fracturing technology occupies a niche but expanding position as Argentina's Vaca Muerta shale development matures, though artificial lift systems dominate the installed base across mature Brazilian offshore fields.
Brazil's ANP mandates local content requirements that reshape contractor selection criteria, while Argentina's environmental impact assessments under provincial jurisdiction constrain fracturing water management practices. ANVISA in Brazil and the national hydrocarbon regulators in Colombia and Mexico enforce occupational safety standards for offshore platforms that elevate service provider compliance costs. Stakeholders must monitor regulatory divergence across Mercosur and Pacific Alliance frameworks when structuring cross-border service contracts.
Market Dynamics
Brazil's ANP local content mandates are restructuring contractor selection criteria across pre-salt licensing rounds, forcing service providers to reconfigure supply chains and joint venture structures to maintain bidding eligibility.
Growth Catalysts
- Deepwater exploration licensing:Brazil's ANP accelerated pre-salt auction schedules are expanding the addressable rig and subsea equipment market. Operators commit to multi-well development programs requiring integrated service packages.
- Vaca Muerta shale maturation:Argentina's unconventional reservoir development is pulling hydraulic fracturing fleets and pressure pumping capacity southward. Provincial regulators in Neuquén are streamlining environmental permitting timelines for horizontal well pads.
- Digital drilling adoption:Real-time downhole telemetry systems are reducing non-productive time in high-pressure carbonate formations. Pre-salt operators deploy automated managed pressure drilling to contain formation kicks.
Market Restraints
- Specialized labor scarcity:Deepwater project engineering expertise concentrates in southeast Brazil, creating wage inflation and crew rotation bottlenecks for contractors operating across multiple basins.
- Import equipment lead times:Subsea blowout preventers and high-pressure riser systems face 18-24 month manufacturing queues from specialized foundries in Asia-Pacific, constraining rig activation schedules.
- ANP local content thresholds:Increasing domestic sourcing requirements for drilling packages elevate procurement complexity for international service firms lacking established Brazilian manufacturing partnerships.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil-led consortium activity is creating first-mover positioning for subsea installation and floating production hookup contractors ahead of regional supply base development.
- Colombia unconventional pilots:Ecopetrol's shale appraisal programs in the Middle Magdalena Valley offer testing grounds for fracture designs adapted to local geomechanical conditions.
- Carbon capture integration:Pre-salt CO2-rich gas streams are driving demand for separation and reinjection engineering, opening adjacent service lines for reservoir monitoring and plume tracking.
Industry Challenges
- Subsea system integration complexity:Tying back high-pressure pre-salt wells to floating production units requires synchronized coordination between drilling, completion, and subsea hardware specialists across contracted boundaries.
- ANVISA offshore medical certification:Brazilian health regulator mandates for hyperbaric medicine readiness and emergency evacuation protocols extend crew onboarding timelines and elevate training costs for platform service personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America Oil Field Services Market |
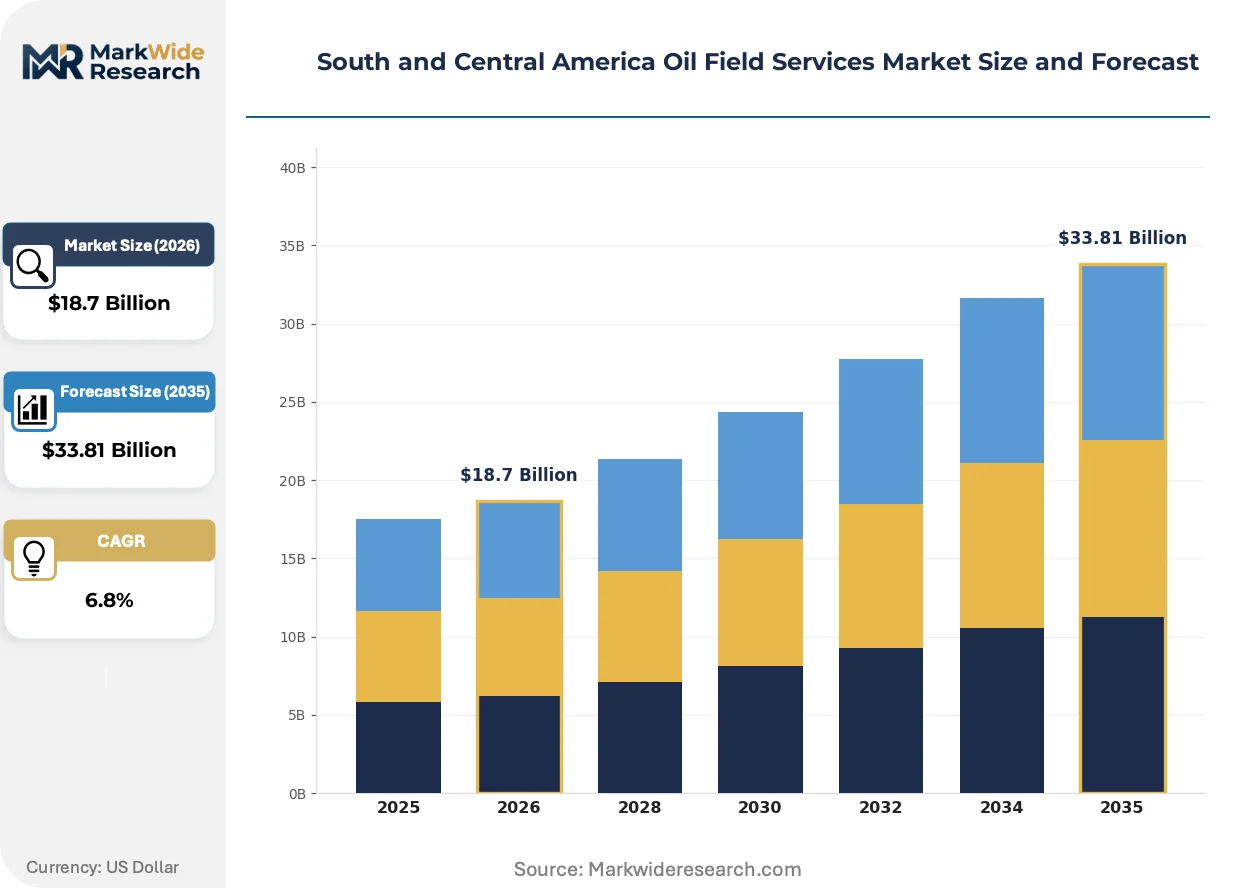
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Completion, Production, Workover Technology: Artificial Lift, Hydraulic Fracturing, Enhanced Oil Recovery, Remote Monitoring Delivery Mode: Onshore, Offshore, Modular, Integrated Customer Type: National Oil Companies, Independent Oil Producers, Service Contractors, Others |
| Companies Covered | Weatherford International, NOV Inc, Schlumberger, Archer, Transocean, Halliburton, TechnipFMC, Expro International, Baker Hughes Company, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America Oil Field Services Market Evolving Landscape
Automation and modular system architectures are compressing project delivery timelines across deepwater developments. Service providers are repositioning around data-centric operating models that separate hardware deployment from performance optimization.
Managed pressure drilling technology is decomposing conventional riser-based circulation systems in pre-salt applications. Petrobras and international partners are deploying closed-loop drilling packages to maintain constant bottom-hole pressure across narrow drilling windows. This capability is decomposing the historical premium commanded by specialized high-temperature drilling contractors.
ANP's updated local content calculation methodology is tightening domestic sourcing verification for subsea tree assemblies and wellhead connectors. Foreign manufacturers must now demonstrate in-country welding, machining, or assembly operations to qualify equipment toward percentage thresholds. Deepwater project procurement teams are restructuring supplier tiers to capture credit for Brazilian-fabricated high-pressure forgings.
Integrated service contracting is displacing discrete equipment rental arrangements across Santos Basin developments. Operators bundle drilling, completion, and subsea installation under single accountability structures with incentive fees tied to production uptime. This consolidation is most visible in Brazil, where pre-salt cluster economics favor long-term alliance frameworks over transactional spot hiring.
South and Central America Oil Field Services Market Segmentation
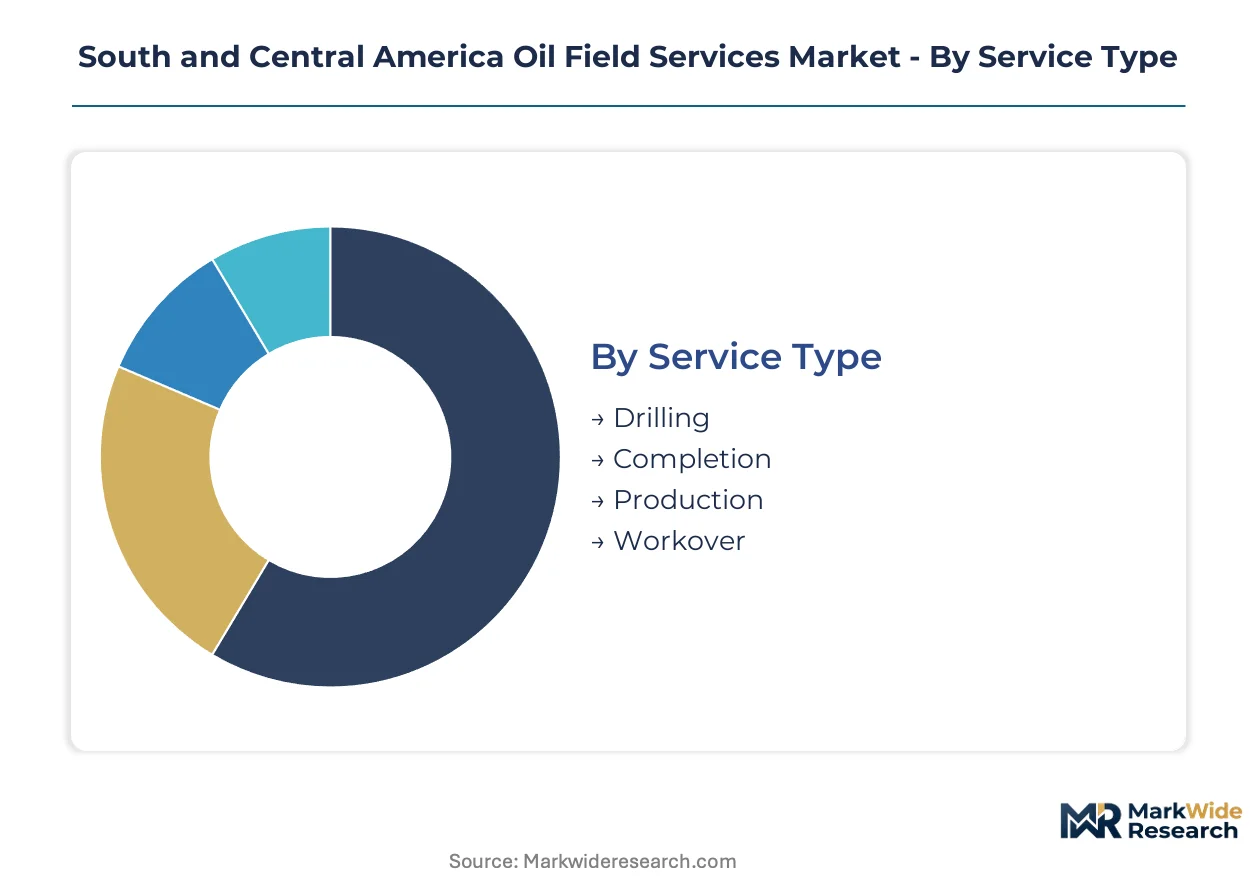
Segmentation reveals how service providers configure delivery architectures across Brazil's pre-salt cluster versus Argentina's unconventional plays. Channel strategies diverge sharply between integrated packages for deepwater operators and modular arrangements for shale developers.
Service Type:
Channel mix varies by contract complexity, with integrated service providers bundling multiple service types under single accountability structures while independent contractors specialize in discrete segments.
- Drilling:Rotary and directional drilling systems rated above 15,000 psi anchor pre-salt development programs across Brazil's Santos Basin. Demand concentrates with Petrobras and international partners executing multi-well campaigns where rig day rates and managed pressure drilling capabilities determine contractor selection.
- Completion:Multi-stage fracture designs and intelligent well completions address high-pressure carbonate formations in deepwater environments. Argentina's Vaca Muerta shale maturation is pulling completion equipment southward as Neuquén basin operators scale horizontal well programs.
- Production:Subsea production systems and floating facility hookups sustain output from mature Brazilian offshore fields.
- Workover:Well intervention and maintenance services extend field life across declining reservoirs in Colombia's Llanos Basin.
Drilling dominates installed base. Completion is where expansion concentrates.
Technology:
Cost tier separation is pronounced, with premium-tier technologies commanding multi-year development cycles and economy-tier solutions serving mature field maintenance.
- Artificial Lift:Electric submersible pumps and gas lift systems optimized for subsea tieback architectures maintain production from Brazil's Campos Basin mature fields. Deployment concentrates with operators seeking to defer abandonment costs through enhanced recovery from existing wellbores.
- Hydraulic Fracturing:Pressure pumping fleets and proppant logistics networks enable unconventional reservoir development. Argentina's Vaca Muerta formation is absorbing imported fracturing capacity as provincial regulators streamline pad permitting timelines.
- Enhanced Oil Recovery:CO2 injection and chemical flooding applications target pre-salt carbonate sweep efficiency.
- Remote Monitoring:Real-time downhole telemetry and automated well control systems reduce non-productive time.
Artificial Lift dominates installed base. Hydraulic Fracturing is where expansion concentrates.
Delivery Mode:
Application context dictates delivery architecture, with offshore environments requiring integrated solutions and onshore shale plays favoring modular equipment redeployment.
- Onshore:Mobile drilling rigs and fracturing spreads serve Argentina's Vaca Muerta and Colombia's unconventional pilots. Demand concentrates with independent producers executing pad drilling programs where equipment mobility and supplier responsiveness outweigh capital intensity.
- Offshore:Drillships, semisubmersibles, and dedicated service vessels anchor Brazil's pre-salt development. Deepwater project teams require synchronized logistics across drilling, completion, and subsea installation phases.
- Modular:Containerized processing equipment and skid-mounted power systems enable rapid field deployment.
- Integrated:Single-contractor accountability for full field development spans design through production startup.
Offshore dominates installed base. Onshore is where expansion concentrates.
Customer Type:
Volume concentration aligns with capital deployment scale, with national oil companies driving long-cycle investments and independent producers pursuing shorter-payback opportunities.
- National Oil Companies:Petrobras, Ecopetrol, and YPF anchor regional service demand through multi-billion dollar development programs. Procurement concentrates in Brazil where ANP local content mandates reshape contractor qualification criteria.
- Independent Oil Producers:ExxonMobil-led consortia in Guyana and shale-focused operators in Argentina's Neuquén province represent emerging demand pockets. These entities prioritize flexible contracting terms and technology transfer provisions.
- Service Contractors:Subspecialized firms provide discrete technical capabilities under tiered supply arrangements.
- Others:Financial investors and trading houses occasionally charter production capacity.
National Oil Companies dominate installed base. Independent Oil Producers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos Basin pre-salt pipeline network and Macaé service port complex anchor Brazil's position as the regional demand center. These infrastructure assets enable synchronized logistics for drillship provisioning and subsea equipment staging across deepwater blocks.
Brazil
Petrobras commands pre-salt development through multi-well drilling campaigns in the Santos Basin. ANP local content mandates require domestic sourcing verification for subsea tree assemblies. The Macaé industrial cluster hosts fabrication yards producing high-pressure forgings for wellhead connectors.
Argentina
Vaca Muerta shale maturation pulls hydraulic fracturing capacity into the Neuquén Basin. Provincial regulators streamline environmental permitting timelines for horizontal well pads. The Neuquén city cluster concentrates pressure pumping fleet deployment and proppant logistics networks.
Colombia
Ecopetrol pilots unconventional appraisal programs in the Middle Magdalena Valley. The national hydrocarbon regulator enforces occupational safety standards for onshore drilling operations. Bogotá-based procurement teams structure integrated service contracts for Llanos Basin workover campaigns.
Guyana
ExxonMobil-led consortium activity drives floating production installation demand offshore the Stabroek Block. The country's environmental protection agency oversees offshore drilling permit issuance. Georgetown serves as the emerging logistics hub for subsea contractor mobilization.
Mexico
Pemex maintains shallow-water workover demand across mature Campeche Bay fields. The National Hydrocarbons Commission regulates contract terms for private upstream participation. Ciudad del Carmen anchors the offshore service supply chain for southern Gulf of Mexico operations.
South and Central America Oil Field Services Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven integrated providers anchor deepwater contracts while regional boutiques capture niche maintenance work. The market organizes around three archetypes: full-service multinationals with digital drilling portfolios, equipment-focused specialists with modular system architectures, and local-content-compliant joint ventures formed to satisfy ANP bidding requirements. Competitive moves center on strategic partnerships with Brazilian fabricators and portfolio diversification into carbon capture engineering.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes Company occupy positions defined by their respective technology specializations. Schlumberger exemplifies the digital-first archetype through its managed pressure drilling and real-time telemetry offerings. Halliburton represents the completion-technology specialist model with high-pressure carbonate reservoir expertise. Baker Hughes Company anchors the artificial lift and subsea systems segment. These three entities structure their Brazilian presence around ANP-compliant joint venture arrangements, with local partners providing fabrication credentials for wellhead and riser components.
| Leading Market Players |
|---|
| Weatherford International |
| NOV Inc |
| Schlumberger |
| Archer |
| Transocean |
| Halliburton |
| TechnipFMC |
| Expro International |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Closed-loop drilling packages substituting conventional riser-based circulation systems are redrawing procurement economics across Brazil's pre-salt cluster while compressing margins for legacy high-temperature drilling contractors. This equipment transition simultaneously shifts fabrication demand toward Asian-Pacific foundries and erodes the premium pricing historically commanded by specialized managed pressure drilling providers.
Pricing Analysis
Volume-discount tiering structures separate integrated service packages for Petrobras-led consortia from modular spot arrangements for independent Neuquén shale operators. Pricing stratifies across premium tiers for ANP-compliant local content bundles, standard tiers for international joint ventures with Brazilian fabrication partners, and economy tiers for mature Campos Basin workover campaigns. Cost compression in the standard tier is intensifying because Halliburton and Schlumberger are bundling digital drilling telemetry with completion hardware to capture pre-salt market share. Independent producers in Argentina exhibit highest price sensitivity due to provincial environmental compliance costs, while ExxonMobil-led Guyana consortia prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Strait of Malacca transit routes for high-pressure forgings from South Korean and Japanese specialized foundries underpin subsea tree assembly timelines across Santos Basin developments. Equipment sourcing draws from Singapore for subsea installation vessels, Brazil's Macaé industrial cluster for wellhead connector fabrication, and the U.S. Gulf Coast for managed pressure drilling control systems. Single-source vulnerability concentrates in Asia-Pacific blowout preventer manufacturing where 18-24 month order backlogs constrain rig activation schedules. Distribution runs through Petrobras-certified logistics hubs in Rio de Janeiro state for deepwater projects, with Neuquén city clusters serving Vaca Muerta fracturing fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
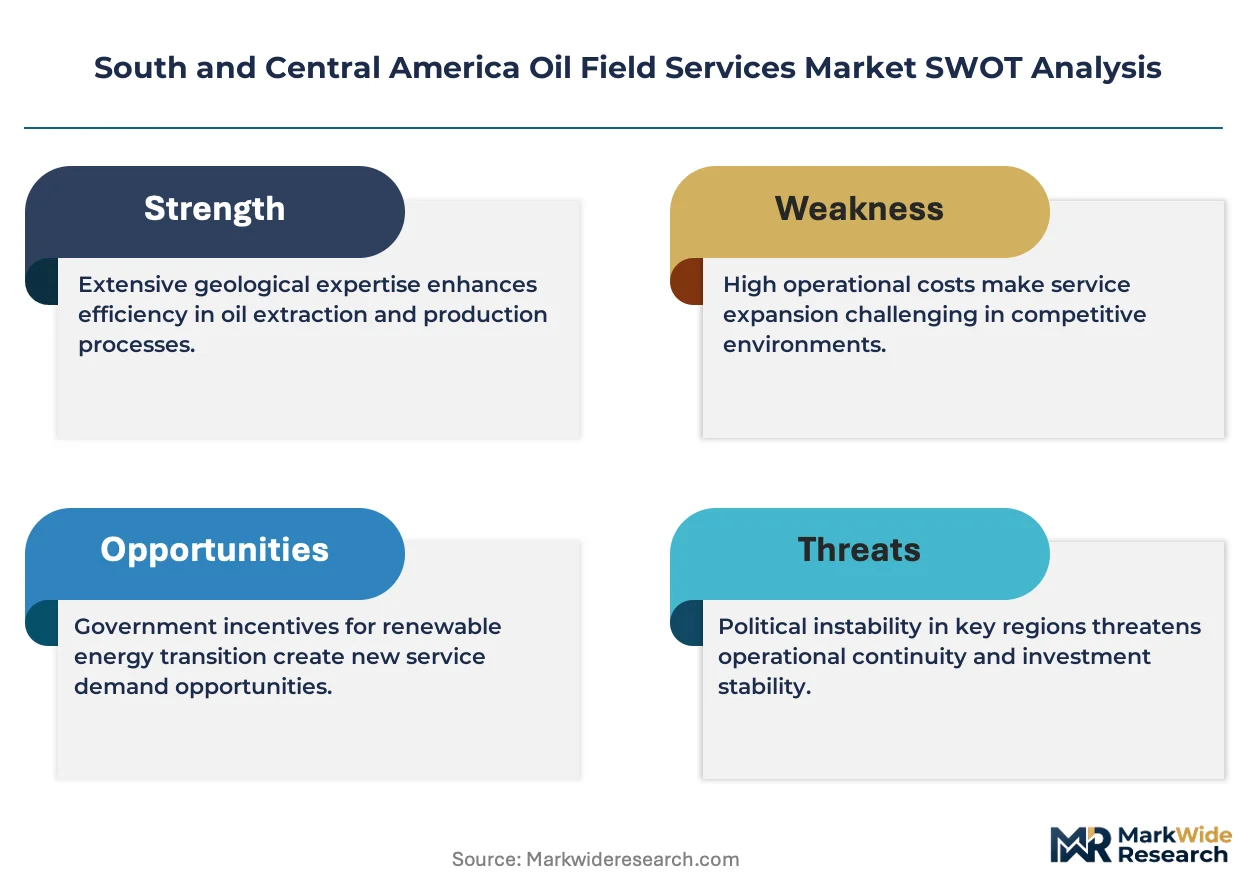
Fragmentation opportunity concentrates in the gap between ANP-mandated local content thresholds and international service providers' limited Brazilian manufacturing partnerships, as pre-salt licensing rounds accelerate demand for compliant integrated packages.
For Market Incumbents: Secure backward integration into Brazilian high-pressure forging fabrication through joint ventures with Macaé yard operators to defend pre-salt bidding eligibility against ANP local content enforcement. Anchor long-term alliance frameworks with Petrobras that bundle digital drilling telemetry, completion design, and subsea installation under single accountability structures with incentive fees tied to production uptime. For New Entrants and Emerging Players: Lead with modular hydraulic fracturing fleet deployment in Argentina's Neuquén Basin where provincial regulators are streamlining environmental permitting timelines for horizontal well pads. Target carbon capture engineering services for pre-salt CO2-rich gas separation and reinjection as Petrobras pilots plume tracking technologies, using technology transfer provisions as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Brazilian fabrication specialists holding ANP-certified welding and machining credentials for wellhead components. Long-term viability hinges on exposure to pre-salt development programs with 5-10 year production horizons rather than mature basin workover dependency. Watch ANP local content threshold adjustments as the inflection signal determining which international service providers retain bidding eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| ANP-Compliant Joint Venture Formation | Local fabrication partnerships satisfy local content verification for subsea tree assembly procurement. |
| Digital Drilling Portfolio Expansion | Real-time telemetry capabilities anchor long-term pre-salt operator relationships against commoditization. |
| Vaca Muerta Fracturing Fleet Deployment | Pressure pumping capacity captures Neuquén Basin shale maturation as provincial permitting accelerates. |
| Carbon Capture Engineering Capability | CO2 separation and reinjection expertise opens adjacent service lines for pre-salt reservoir monitoring. |
| Guyana-Suriname Basin First-Mover Positioning | Subsea installation contractors establish supply base relationships ahead of regional infrastructure development. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANP licensing round documentation, Petrobras procurement disclosures, and provincial environmental regulator filings in Neuquén. Primary interviews engaged drilling project managers at national oil companies, supply chain directors at integrated service providers, fabrication yard operators in Macaé, and regulatory compliance officers at ANVISA. Secondary sources included customs data for subsea equipment imports, SEC filings from listed oil field services firms, and basin-specific production databases. Bottom-up rig count and fleet deployment estimates triangulate against top-down addressable market calculations from operator capital expenditure announcements.
Segmentation dimensions modeled span service type, technology tier, delivery mode, and customer archetype across the projection horizon. The analytical framework incorporates ANP local content threshold trajectories, pre-salt well complexity coefficients, and Vaca Muerta shale well spacing assumptions. CAGRs derive from operator-announced drilling campaign schedules and equipment day-rate trending. Forecast inputs include deepwater rig activation timelines and fracturing fleet redeployment patterns from North American basins.
Underlying assumptions cover sustained ANP local content enforcement, stable provincial environmental permitting timelines in Neuquén, and uninterrupted Asia-Pacific foundry output for high-pressure forgings, with deviation risk concentrated in Brazilian regulatory threshold adjustments and extended subsea equipment manufacturing queues. Revision becomes warranted when ANP local content verification methodologies tighten beyond current joint venture structuring capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Frac Tree Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Frac Stack Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Sand Screen Sales Market