
 Oil and Gas Corrosion Protection Market | 2026-2036
Oil and Gas Corrosion Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Corrosion Protection Market Intelligence
The capability gap between integrated coating formulators and regional applicators is collapsing as offshore project specifications demand factory-applied fusion-bonded epoxy systems with automated quality certification. SLB leverages its subsea technology portfolio to bundle corrosion management with digital monitoring contracts. Hempel A/S anchors its position through captive supply of zinc-rich primers and silicone topcoats purpose-built for North Sea atmospheric zones. Sherwin-Williams Company competes by controlling distribution through dedicated oilfield service branches in Houston and Aberdeen.
Oil and gas corrosion protection encompasses engineered barrier systems—typically comprising epoxy-phenolic primers, glass-flake reinforced vinyl esters, or sacrificial zinc/aluminum metallics applied at 250–500 micron dry film thickness—to prevent electrochemical degradation of carbon steel infrastructure exposed to brine, sour gas, and cyclic temperature stress. Pipeline applications dominate value capture due to kilometer-scale linear asset bases and regulatory-driven reinspection intervals, while cathodic protection systems represent the fastest-growing technology category as operators retrofit impressed-current arrays to aging subsea gathering lines. Coatings retain the largest product-type margin pool because formulation specialization creates switching costs once a specification qualifies for a given field.
NACE SP0169, ISO 15589, and the EPA's National Pollutant Discharge Elimination System collectively dictate material selection, installation protocol, and environmental release thresholds for corrosion protection systems across US waters and interstate pipeline corridors. The EU's REACH framework and MDR-derived substance restrictions further constrain inhibitor chemistries available to North Sea and Mediterranean operators, compressing the approved vendor list for critical applications. Stakeholders must monitor how regulatory divergence between the EPA's emerging PFAS restrictions and ECHA's candidate list updates will force reformulation investments and potentially invalidate decade-long coating qualification databases.
Market Dynamics
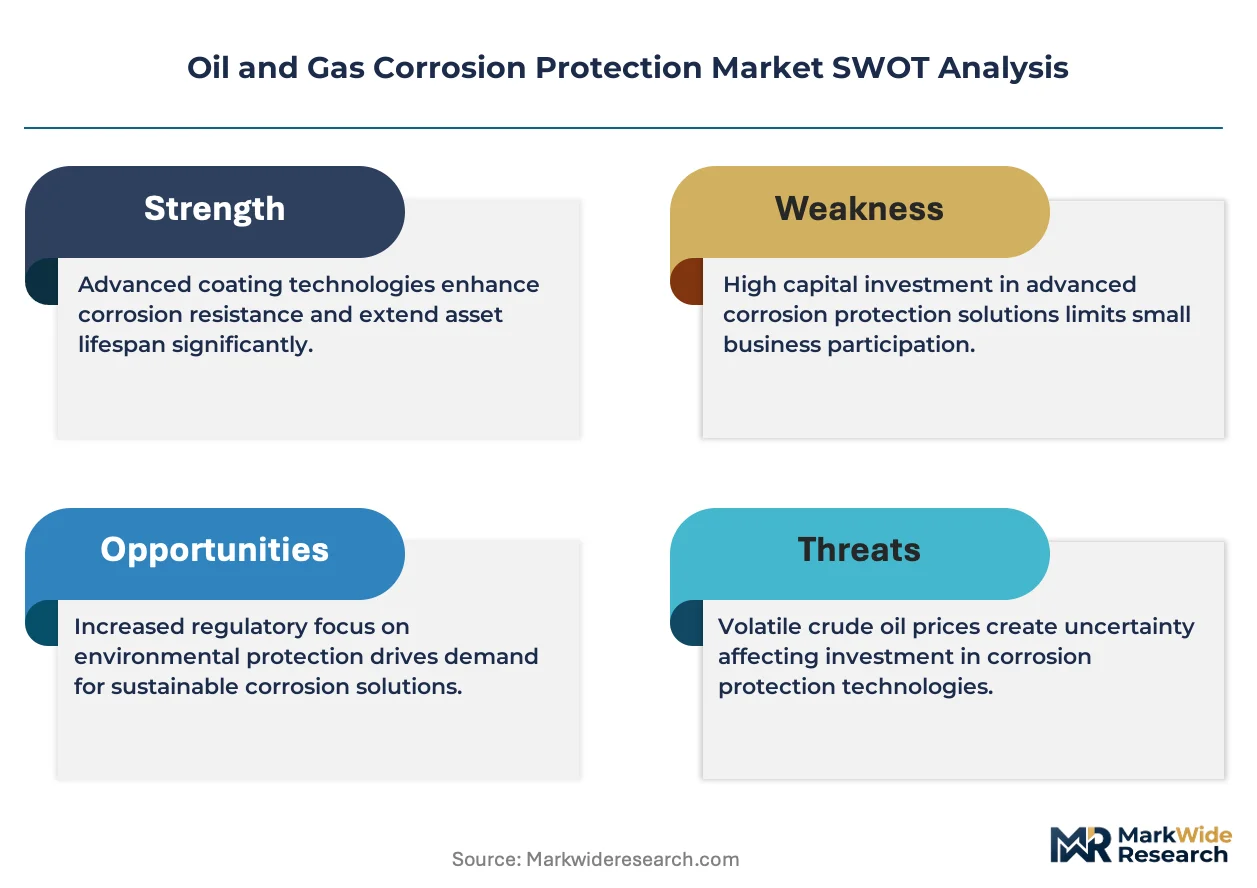
Offshore exploration at depths exceeding 1,500 meters is forcing operators to abandon conventional field-applied coatings in favor of factory-certified fusion-bonded epoxy systems with automated inspection protocols.
Growth Catalysts
- EPA National Pollutant Discharge Elimination System mandates:Pipeline integrity reinspection intervals are compressing replacement cycles for aging subsea gathering lines across US interstate corridors.
- Cathodic protection retrofit programs:Impressed-current array installations on aging North Sea infrastructure are accelerating technology refresh rates for electrochemical mitigation systems.
- Deepwater Brazil pre-salt development:Petrobras-led projects require specification-grade coating systems qualified to NORSOK M-501 for splash zone and subsea applications.
Market Restraints
- Zinc feedstock price volatility:Sacrificial metallics formulations face margin compression when London Metal Exchange zinc prices spike above threshold levels.
- EU REACH substance restrictions:Chromate-based corrosion inhibitors are being phased from approved vendor lists, forcing qualification restarts for critical North Sea applications.
- Epoxy resin supply concentration:Bisphenol-A and amine hardener production clusters in Northeast Asia create geographic vulnerability for coating formulators.
Strategic Opportunities
- West African offshore licensing rounds:Ghana and Senegal deepwater blocks lack established coating qualification databases, creating first-mover specification advantages.
- EU Green Deal carbon border adjustments:Low-carbon coating manufacturing processes will receive preferential treatment in public tender evaluations.
- Digital twin integration:Corrosion monitoring sensor data fused with predictive analytics platforms enables subscription-based asset management contracts.
Industry Challenges
- NACE coating inspector certification bottlenecks:Qualified personnel shortages delay project mobilization for offshore platform maintenance windows.
- Legacy pipeline coating compatibility:New epoxy systems require extensive adhesion testing against existing asphalt enamel and coal tar layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Corrosion Protection Market |
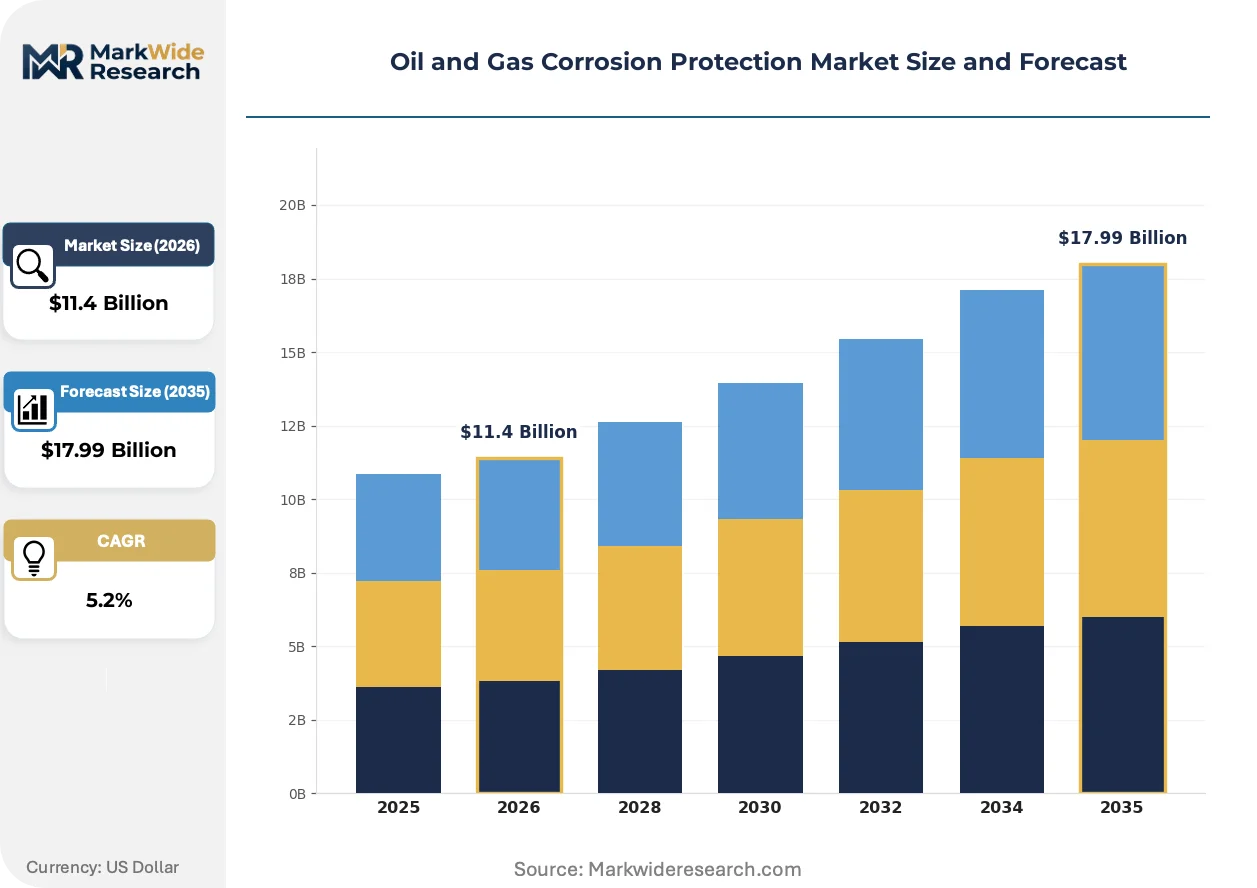
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.99 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Inhibitors, Cathodic Protection, Anodes Application: Pipeline, Offshore Platforms, Onshore Facilities, Storage Tanks Technology: Corrosion Monitoring, Protective Coating, Electrochemical, Chemical Inhibition End User: Oil Producers, Gas Distributors, Refining Companies, Service Providers |
| Companies Covered | 3M, Sherwin-Williams Company, SLB, Hempel A/S, Jotun Group, Cortec Corporation, PPG Industries, Akzo Nobel, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Corrosion Protection Market Strategic Shifts & Innovations
Protective coating specifications are bifurcating between commodity maintenance applications and engineered systems requiring digital traceability from raw material batch to field installation.
Thermoplastic powder coatings are fragmenting traditional liquid epoxy dominance in pipeline girth weld applications. Midstream operators in the Permian Basin are specifying fusion-bonded nylon and polypropylene systems for directional drilling pull-through operations. This material shift is fragmenting the supplier base as resin compounders without powder extrusion capability lose specification access.
EU F-Gas Regulation phase-down schedules are forcing reformulation of polyurethane foam insulation systems used in subsea flowline corrosion protection. Manufacturers must substitute hydrofluoroolefin blowing agents ahead of 2030 reduction targets. Arctic LNG projects in Norway and Russia are most exposed given cryogenic thermal insulation requirements.
Integrated service contracting is compressing traditional coating procurement cycles. Major operators in the US Gulf Coast now bundle corrosion protection with inspection and maintenance under multi-year asset integrity agreements. This model displaces spot purchasing through distributors and concentrates volume with formulators capable of field service deployment.
Oil and Gas Corrosion Protection Market Segmentation
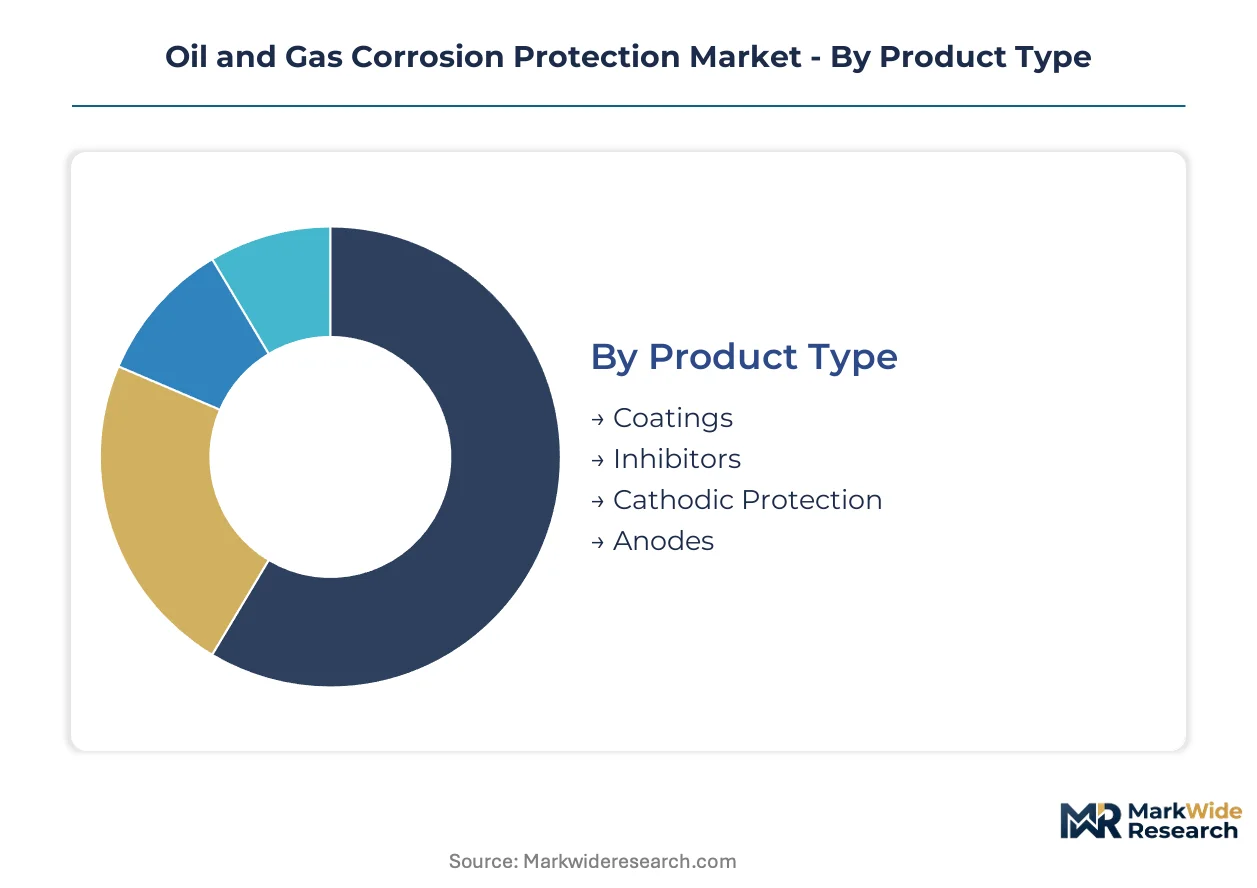
Corrosion protection procurement patterns diverge sharply across asset types and regulatory jurisdictions. Specification-grade systems for subsea infrastructure command qualification timelines that commodity maintenance programs cannot accommodate.
Product Type:
EPA NPDES discharge thresholds and EU REACH substance restrictions create divergent approval pathways for each chemistry class across Atlantic basin operations.
- Coatings:Epoxy-phenolic primers and glass-flake vinyl esters applied at 250–500 micron dry film thickness dominate carbon steel protection. Pipeline operators in the US Gulf Coast corridor specify fusion-bonded epoxy for new construction, while North Sea platforms demand NORSOK M-501 qualified silicone topcoats for atmospheric zone durability.
- Cathodic Protection:Impressed-current arrays and sacrificial anode systems deliver electrochemical mitigation for subsea gathering lines. Retrofit installations on aging North Sea infrastructure are climbing the fastest as operators replace depleted zinc anodes ahead of regulatory reinspection deadlines.
- Inhibitors:Film-forming amines and volatile corrosion inhibitors protect internal pipeline surfaces from sour gas attack.
- Anodes:Zinc and aluminum sacrificial metallics provide galvanic protection for platform structural members and subsea equipment.
Established volume favors Coatings; emerging adoption favors Cathodic Protection.
Application:
Asset lifecycle stage determines specification rigor more than geography.
- Pipeline:Kilometer-scale linear infrastructure drives the largest absolute demand for external coating systems and internal inhibition programs. US interstate corridors face compressed replacement cycles under EPA integrity mandates, while Brazil pre-salt developments require factory-applied fusion-bonded epoxy qualified to Petrobras specifications.
- Offshore Platforms:Splash zone and atmospheric protection demands multi-layer systems with automated quality certification. Gulf of Mexico operators specify thermal-spray aluminum for fireproofing compatibility alongside corrosion resistance.
- Onshore Facilities:Refinery maintenance cycles and tank farm expansions drive replacement volumes for conventional epoxy and polyurethane systems.
- Storage Tanks:Internal linings for crude and product storage require chemical-resistant coatings compatible with varying sulfur content.
Pipeline captures the dominant share of specification-grade procurement; Offshore Platforms command the steepest expansion trajectory as exploration moves beyond 1,500 meter depths.
Technology:
Digital integration is fragmenting traditional chemistry-based procurement models.
- Protective Coating:Barrier systems remain the foundational technology for external corrosion prevention across all asset classes. Application method—spray, brush, or fusion-bond—determines qualification requirements more than resin chemistry alone.
- Corrosion Monitoring:Sensor networks and predictive analytics platforms enable subscription-based asset management contracts. Integrated service providers bundle monitoring with maintenance under multi-year agreements that displace spot coating purchases.
- Electrochemical:Cathodic protection systems and anode technologies deliver active corrosion control for submerged and buried structures.
- Chemical Inhibition:Injector programs and batch treatments protect internal surfaces where coatings cannot adhere.
Protective Coating retains the largest installed base; Corrosion Monitoring is gaining share fastest through digital twin integration.
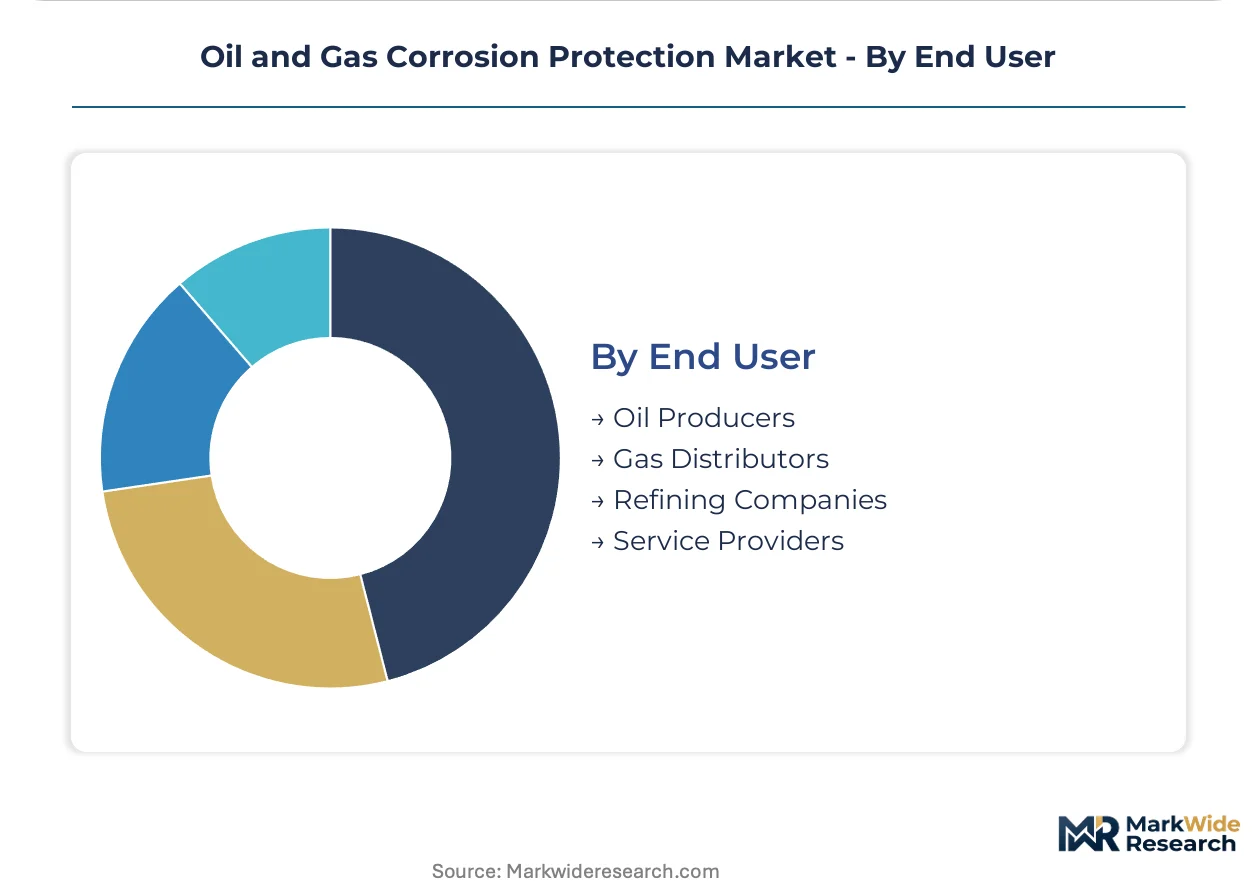
End User:
Procurement concentration varies with vertical integration depth.
- Oil Producers:Integrated majors and national oil companies specify coating systems for upstream exploration and production assets. Deepwater projects in West Africa and Brazil demand qualified vendor lists that exclude regional applicators lacking factory certification capability.
- Refining Companies:Downstream operators schedule maintenance turnarounds that drive cyclical demand for tank lining and process vessel protection systems.
- Gas Distributors:Midstream pipeline operators balance integrity mandate compliance with cost control across extensive linear networks.
- Service Providers:Oilfield service contractors procure corrosion protection as part of integrated asset integrity packages.
Oil Producers dominate specification authority; Refining Companies generate the most predictable replacement demand through scheduled maintenance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast corridor consumes specification-grade fusion-bonded epoxy systems for new pipeline construction, while North Sea operators prioritize NORSOK M-501 qualified silicone topcoats for atmospheric durability. This chemistry-mix differential separates Atlantic basin procurement patterns.
United States
EPA National Pollutant Discharge Elimination System mandates compress integrity reinspection intervals for interstate pipeline corridors. The agency's emerging PFAS restrictions threaten to invalidate decade-long coating qualification databases. Houston anchors the largest concentration of dedicated oilfield service branches serving midstream operators across the Permian Basin.
Norway
Petrobras-led pre-salt developments in neighboring Brazil indirectly drive Norwegian coating exports qualified to NORSOK M-501 for splash zone applications. ECHA candidate list updates under REACH constrain chromate-based inhibitor availability for North Sea platforms. Stavanger hosts the primary cluster of subsea technology providers bundling corrosion management with digital monitoring contracts.
Brazil
Deepwater pre-salt fields beyond 1,500 meters demand factory-certified fusion-bonded epoxy systems with automated inspection protocols. ANVISA and national petroleum regulator ANP jointly oversee environmental release thresholds for coating chemistries. Rio de Janeiro concentrates specification authority for Petrobras vendor qualification programs.
United Kingdom
Aging North Sea infrastructure accelerates impressed-current cathodic protection retrofit programs ahead of regulatory reinspection deadlines. The EU F-Gas Regulation phase-down forces reformulation of polyurethane foam insulation systems used in subsea flowlines. Aberdeen maintains dedicated oilfield service branches serving platform maintenance windows.
Germany
EU Green Deal carbon border adjustments will confer preferential treatment on low-carbon coating manufacturing processes in public tender evaluations. ECHA substance restrictions compress approved vendor lists for critical applications. The industrial corridor along the Rhine hosts formulation specialists supplying zinc-rich primers to North Sea operators.
Oil and Gas Corrosion Protection Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the oil and gas corrosion protection market. The upper tier commands specification authority through captive supply of qualified coating systems and digital asset integrity platforms. The specialist tier competes on regional applicator relationships and maintenance-turnaround responsiveness. Two strategic archetypes dominate: integrated service providers bundling corrosion management with monitoring contracts, and formulation specialists controlling raw material supply chains. Competitive moves concentrate on backward integration into resin production and geographic expansion through dedicated oilfield service branches.
Within the integrated service tier, SLB leverages its subsea technology portfolio to anchor subscription-based asset management offerings. Among European formulation specialists, Hempel A/S and Akzo Nobel occupy positions defined by captive supply of zinc-rich primers and silicone topcoats purpose-built for harsh atmospheric zones. Sherwin-Williams Company exemplifies the distribution-control archetype through dedicated branches in Houston and Aberdeen.
| Leading Market Players |
|---|
| 3M |
| Sherwin-Williams Company |
| SLB |
| Hempel A/S |
| Jotun Group |
| Cortec Corporation |
| PPG Industries |
| Akzo Nobel |
| Axalta Coating Systems |
| Others |
Cost & Logistics Intelligence
Long-term asset integrity contracts lock in supply access and price visibility for coating formulators serving Petrobras and US Gulf Coast midstream operators. These multi-year agreements bundle factory-certified fusion-bonded epoxy systems with digital monitoring, compressing spot market participation and anchoring margin stability against zinc feedstock volatility.
Pricing Analysis
After-sales service revenue from inspection and maintenance contracts drives lifetime value for integrated providers. Three-tier pricing structure across NORSOK M-501 qualified, API-standard, and maintenance-grade coating systems separates specification authority from commodity replacement. Cost compression in sacrificial metallics intensifies when London Metal Exchange zinc prices spike. Midstream pipeline operators exhibit highest price sensitivity; deepwater project developers prioritize qualification over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for amine hardener and epoxy resin shipments. Bisphenol-A production clusters in China, South Korea, and Japan anchor raw material supply. Formulation hinges on zinc concentrate flows from Australia and Peru. Single-source vulnerability in specialty silicone resin creates qualification bottlenecks for North Sea atmospheric coatings. Distribution runs through dedicated oilfield service branches in Houston, Aberdeen, and Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive moat where decade-long coating qualification databases under EPA and NORSOK regimes create switching costs that entrench incumbent positions.
For Market Incumbents: Compound specification authority by backward integration into zinc-rich primer resin production and captive supply of NORSOK M-501 qualified silicone topcoats. Threats from digital twin platforms bundling corrosion monitoring with predictive analytics demand counter-investment in sensor network deployment. Priority lever: factory certification capability expansion in Brazil and West Africa to capture pre-salt and deepwater licensing rounds. For New Entrants and Emerging Players: Differentiate on low-carbon coating manufacturing processes aligned with EU Green Deal carbon border adjustment criteria. White-space targets include Ghana and Senegal offshore blocks lacking established qualification databases, plus polyurethane foam insulation reformulation for Arctic LNG projects facing F-Gas Regulation phase-down. Go-to-market angle: digital traceability from raw material batch to field installation. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive resin supply chains and established NORSOK or Petrobras vendor qualifications. Long-term viability centers on regulatory entrenchment durability across the Atlantic basin. Acquisition target archetype: regional applicators with automated quality certification capability. Signal to watch: EPA PFAS restriction finalization invalidating legacy coating databases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of zinc-rich primers insulates margin from London Metal Exchange volatility. |
| Factory Certification Capability Expansion | Automated quality protocols qualify formulators for Petrobras pre-salt specifications. |
| Digital Twin Platform Integration | Sensor-fused predictive analytics enable subscription-based asset management contracts. |
| Low-Carbon Manufacturing Transition | EU Green Deal carbon border adjustments confer tender preference on qualifying producers. |
| NORSOK M-501 Qualification Investment | Silicone topcoat approval unlocks North Sea splash zone specification access. |
Research Approach
Initial hypotheses were tested against primary input from coating formulator R&D directors, offshore platform maintenance managers, midstream pipeline integrity engineers, and oilfield service procurement leads and refined through secondary validation. Sources included EPA NPDES discharge filings, NORSOK qualification registries, SEC 10-K disclosures from listed chemical companies, and customs data on epoxy resin trade flows. Bottom-up project pipeline analysis and top-down macroeconomic triangulation anchored volume estimates.
Variance decomposition across product type, application asset class, technology integration level, and end-user vertical shaped the analytical framework. Modeled dimensions included coating chemistry class, cathodic protection system architecture, and geographic regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated deepwater project sanctioning timelines and integrity reinspection interval compression under EPA mandates.
The analysis sits within stated boundaries; outcomes outside sustained offshore capital expenditure, stable zinc feedstock pricing, or unaltered REACH substance restrictions would require recalibration. Forecasts reflect documented assumptions on regulatory trajectory and project development velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iron Ore Mining Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Wellhead System Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Digital Oilfield Solutions Market