
 Oil and Gas Pipe Market | 2026-2036
Oil and Gas Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pipe Market Insights
Buyer concentration among supermajor oil companies and national oil companies is restructuring procurement dynamics across the supply base. Tenaris S.A. leverages its integrated seamless pipe mills in Argentina and Mexico to serve Latin American offshore projects. Vallourec S.A. anchors its position through premium connection technology for high-pressure deepwater wells. Nippon Steel Corporation competes on advanced ultra-high-strength grades for sour service environments.
Oil and gas pipe denotes hollow cylindrical sections manufactured from carbon steel, stainless steel, or alloy compositions, typically produced through seamless extrusion or electric resistance welding to API 5L, ASTM, or ISO 3183 specifications, designed to transport hydrocarbons under pressures exceeding 1,000 psi across gathering, transmission, and distribution networks. Seamless pipe commands premium positioning in high-pressure upstream and deepwater applications where burst resistance and fatigue performance justify unit cost premiums. Welded pipe dominates midstream trunk lines and onshore gathering systems where diameter flexibility and scale economies drive procurement decisions. Carbon steel retains volume leadership across downstream and refining applications, though alloy steel grades are gaining share in corrosive shale plays and subsea tiebacks.
API standards govern dimensional, material, and testing requirements for line pipe in North American hydrocarbon infrastructure, while the EPA enforces methane leak detection and repair protocols that accelerate replacement of aging cast-iron and low-grade steel distribution networks. In Europe, the EU Green Deal and F-Gas Regulation indirectly pressure gas transmission operators to demonstrate pipeline integrity and minimize fugitive emissions through upgraded materials and inspection regimes. Stakeholders must monitor regulatory divergence between jurisdictions that mandate domestic content or impose divergent testing protocols, as these rules will determine which mill configurations and metallurgical capabilities sustain market access.
Market Dynamics
API 5L specification tightening and EPA methane emissions enforcement are compressing supplier margins while accelerating replacement cycles for aging distribution infrastructure across North American hydrocarbon networks.
Growth Catalysts
- Deepwater pre-salt expansion:Brazil's offshore basins are driving procurement of corrosion-resistant alloy grades for high-pressure subsea tiebacks.
- EU Green Deal pipeline integrity mandates:F-Gas Regulation compliance is forcing European gas transmission operators to upgrade inspection regimes and materials.
- LNG export corridor development:Australia's Queensland and Western Australia facilities are expanding cryogenic-grade large-diameter welded pipe demand.
Market Restraints
- Scrap steel cost volatility:Electric arc furnace feedstock prices swing with Turkish and Vietnamese import demand, squeezing welded pipe mill margins.
- Seamless capacity concentration:Argentina, Mexico, and Italy host the majority of global rotary piercing capacity, creating geographic supply risk.
- Composite pipe substitution:Reinforced thermoplastic pipes from TechnipFMC and Baker Hughes are capturing shallow-water gathering applications.
Strategic Opportunities
- Sour service metallurgy:Ultra-high-strength chrome-molybdenum grades for hydrogen sulfide-rich shale plays remain underpenetrated outside the Permian and Bakken.
- Carbon capture transport infrastructure:CO2 pipeline specifications under development by ISO TC 67/SC 2 create new diameter and pressure class requirements.
- Digital twin integration:Real-time corrosion monitoring combined with predictive maintenance is opening subscription revenue models for pipe suppliers.
Industry Challenges
- ASME Section IX welder certification backlogs:Specialized orbital welding qualifications for sour service applications face 6-9 month training pipeline constraints.
- Legacy ERP integration:Mill traceability systems must interface with operator digital twin platforms, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pipe Market |
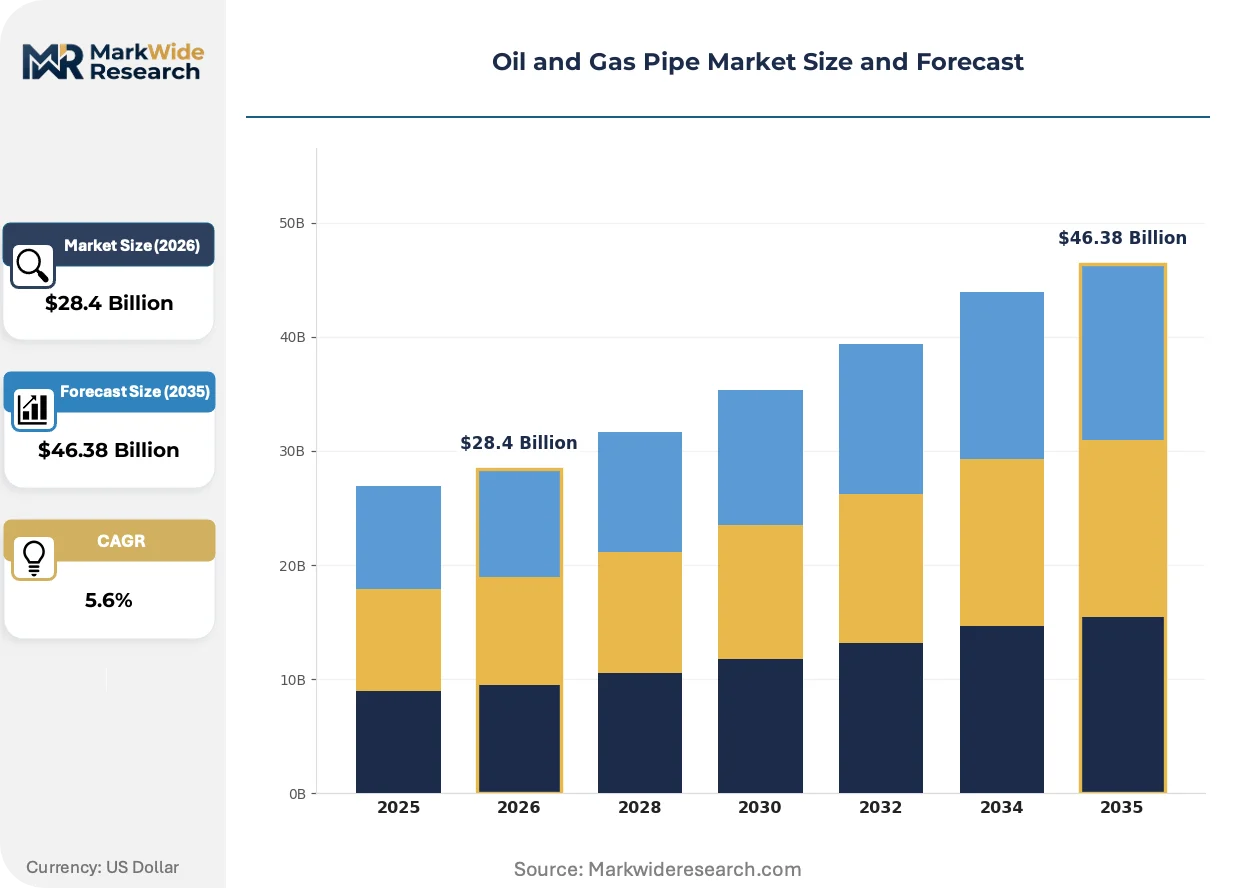
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $46.38 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipe Type: Seamless, Welded, Lined, Coated Material: Carbon Steel, Stainless Steel, Alloy Steel, Polyethylene Application: Downstream, Midstream, Upstream, Refining End User: Oil Companies, Gas Producers, Contractors, Utilities |
| Companies Covered | Tenaris S.A., Vallourec S.A., TMK Group, ArcelorMittal S.A., U.S. Steel Corporation, OMK Steel Ltd, ChelPipe Group, Nippon Steel Corporation, EVRAZ plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pipe Market Trends and Innovations
Material science advances and regulatory enforcement patterns are fragmenting procurement specifications while compressing acceptable defect thresholds across upstream and midstream applications.
Automated ultrasonic testing with phased-array probe configurations is decentralizing quality assurance from centralized third-party labs to mill-floor inspection stations. Major offshore contractors in the Gulf of Mexico and West Africa now require 100% automated weld inspection before shipment acceptance. This shift is decentralizing the traditional NDT service provider landscape and compressing lead times for critical path deliveries.
EPA methane leak detection and repair protocols are mandating optical gas imaging surveys and continuous monitoring installations across transmission and distribution networks. Pipeline operators must replace cast-iron and unprotected steel mains with polyethylene or coated steel alternatives to demonstrate compliance. Gathering systems in the Permian and Appalachian basins face the most aggressive replacement timelines due to density of older infrastructure.
Integrated mill-to-wellhead service contracts are consolidating procurement decisions under fewer engineering-procurement-construction firms. Supermajor operators in Brazil and Australia now bundle pipe supply with threading, logistics, and installation support through single-source agreements. This concentration is most visible in deepwater projects where schedule certainty outweighs unit cost optimization.
Oil and Gas Pipe Market Segmentation
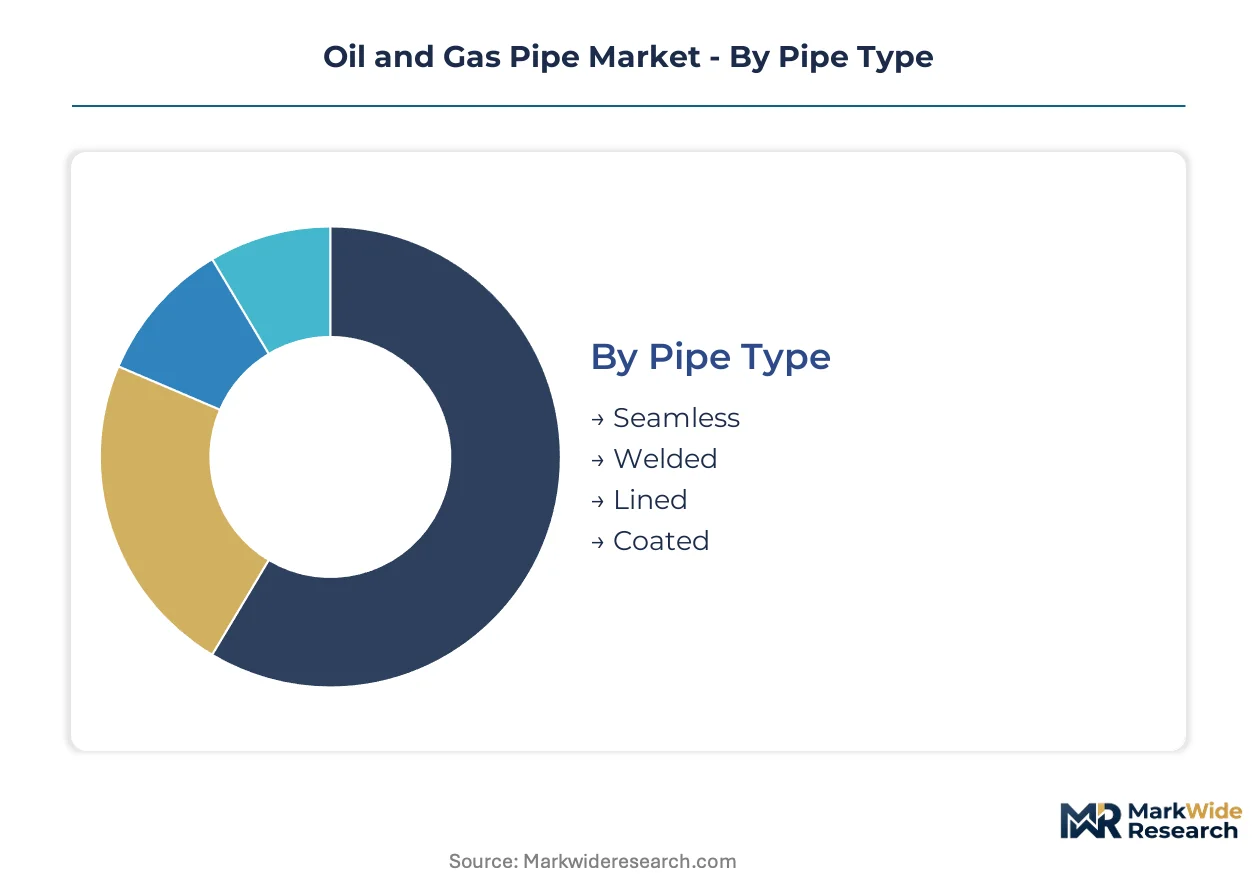
Pipe specification divergence across pressure regimes and corrosion environments fragments procurement into distinct technical tiers. Each segmentation dimension carries direct implications for mill configuration, certification requirements, and margin structure across the supply base.
Pipe Type:
Volume leadership sits with welded configurations, while seamless commands unit price premiums in critical service applications.
- Seamless:Manufactured through rotary piercing or extrusion without longitudinal welds, delivering uniform circumferential strength for burst-critical service. Demand concentrates in Brazil's pre-salt basins and West African deepwater tiebacks where API 5L X80+ grades and fatigue resistance justify cost premiums.
- Welded:Produced via electric resistance welding or submerged arc welding from hot-rolled coil, offering diameter flexibility from 4 to 56 inches. Midstream trunk lines across Australia's Queensland LNG corridors and Permian gathering systems drive procurement scale where pressure ratings permit longitudinal seam construction.
- Lined:Carbon steel substrate with corrosion-resistant polymer or glass-reinforced epoxy internal lining for sour service environments.
- Coated:External fusion-bonded epoxy or three-layer polyethylene coating systems for subsea burial and atmospheric corrosion protection.
Today's leader: Welded. Tomorrow's challenger: Seamless.
Material:
Cost tier stratification runs from commodity carbon grades through engineered alloy formulations.
- Carbon Steel:API 5L Grades B through X70 dominate transmission and distribution networks where cost efficiency outweighs corrosion resistance. Replacement cycles for aging cast-iron mains under EPA methane rules are accelerating demand across Appalachian and Permian basin utilities.
- Alloy Steel:Chrome-molybdenum and nickel-enhanced grades for high-pressure sour service in hydrogen sulfide-rich formations. Procurement is expanding among offshore contractors in the Gulf of Mexico where NACE MR0175/ISO 15156 compliance is mandatory.
- Stainless Steel:300-series and duplex grades for cryogenic LNG service and chloride-rich subsea environments.
- Polyethylene:High-density and medium-density grades for low-pressure distribution replacement programs and rural gathering lateral lines.
Carbon steel retains volume dominance. Alloy steel is climbing the fastest on deepwater specification tightening.
Application:
Upstream and midstream segments are diverging on pressure class and inspection protocol requirements.
- Upstream:Gathering systems and flowlines from wellhead to processing facilities, spanning onshore shale plays and subsea production risers. Automated ultrasonic testing with phased-array verification is becoming mandatory for offshore contractors in West Africa.
- Midstream:Long-distance transmission trunk lines and interstate pipeline networks where diameter scale and weld productivity drive mill economics. FERC certificate requirements and EPA methane monitoring mandates are compressing acceptable defect thresholds.
- Downstream:Refinery process piping and product distribution terminals operating under ASME B31.3 and API 570 inspection regimes.
- Refining:High-temperature catalytic cracking and hydroprocessing units requiring creep-resistant alloy grades.
Midstream commands current procurement volume. Upstream is gaining share fastest on deepwater pre-salt expansion.
End User:
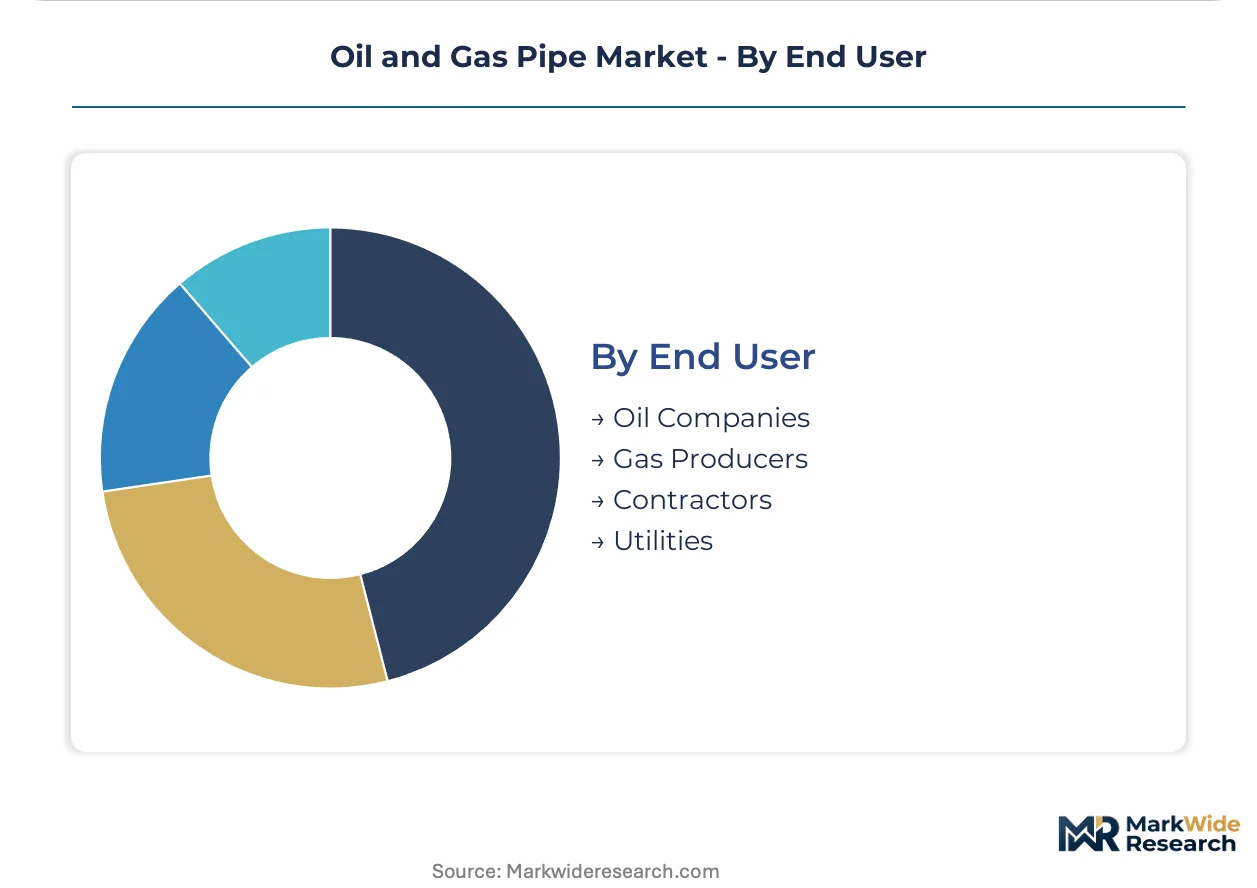
Customer concentration among integrated operators is restructuring contract terms toward bundled service models.
- Oil Companies:Supermajor and national oil company operators specifying integrated mill-to-wellhead procurement for schedule certainty in Brazil and Australia deepwater projects.
- Gas Producers:Independent and integrated gas operators focused on gathering system integrity and methane emissions compliance under EPA LDAR protocols.
- Contractors:Engineering-procurement-construction firms consolidating pipe supply with threading, logistics, and installation support through single-source agreements.
- Utilities:Local distribution companies replacing legacy cast-iron and bare steel mains with coated steel or polyethylene alternatives.
Contractors anchor current procurement decisions. Utilities represent the steepest expansion trajectory on infrastructure replacement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welders certified to ASME Section IX and API 1104 standards concentrate in Houston, Dammam, and Singapore, anchoring fabrication capacity for sour service and deepwater applications.
United States
Gulf of Mexico offshore contractors are expanding procurement of corrosion-resistant alloy grades for high-pressure subsea tiebacks. EPA methane emissions rules and FERC certificate requirements are accelerating replacement of aging cast-iron distribution mains. Houston anchors the largest concentration of orbital welding qualification centers, where 6-9 month certification backlogs constrain contractor capacity.
Brazil
Pre-salt basin development is driving demand for seamless API 5L X80+ grades with fatigue-resistant properties. ANP regulatory frameworks mandate domestic content thresholds for subsea equipment procurement. Rio de Janeiro hosts engineering-procurement-construction firms bundling pipe supply with installation support through single-source agreements.
Australia
Queensland and Western Australia LNG export facilities are expanding cryogenic-grade large-diameter welded pipe procurement. The country's pipeline integrity regime under NOPSEMA requires continuous monitoring installations to minimize fugitive emissions. Perth serves as the coordination hub for integrated mill-to-wellhead service contracts across offshore projects.
Saudi Arabia
Gas field development and master gas system expansion are increasing specification-grade seamless pipe procurement. Saudi Aramco's in-kingdom total value add program mandates local fabrication and metallurgical processing. Dammam's industrial city hosts specialized heat treatment facilities for sour service chrome-molybdenum grades.
China
West-to-east gas pipeline Phase IV and shale gas gathering networks are scaling demand for high-frequency welded line pipe. GB standards and MIIT industrial policy are tightening material traceability and defect threshold requirements. Baoji in Shaanxi province concentrates seamless mill capacity serving domestic pressure vessel and boiler applications.
Oil and Gas Pipe Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The supply base exhibits moderate consolidation, with rotary piercing capacity concentrated among Argentine, Mexican, and Italian mill operators. Three archetypes dominate: integrated seamless producers with captive steelmaking, welded pipe specialists with electric arc furnace feedstock flexibility, and technology licensors of premium connection systems. Capacity expansion and strategic partnerships represent the dominant competitive vectors as operators seek schedule certainty for deepwater projects.
Within the integrated seamless tier, Tenaris S.A. and Vallourec S.A. occupy positions anchored in Latin American and European mill networks respectively. Nippon Steel Corporation exemplifies the advanced metallurgy archetype, representing capabilities in ultra-high-strength sour service grades. These three entities illustrate how geographic mill placement and metallurgical specialization stratify competitive positioning across upstream and midstream procurement channels.
| Leading Market Players |
|---|
| Tenaris S.A. |
| Vallourec S.A. |
| TMK Group |
| ArcelorMittal S.A. |
| U.S. Steel Corporation |
| OMK Steel Ltd |
| ChelPipe Group |
| Nippon Steel Corporation |
| EVRAZ plc |
| Others |
Pricing and Supply Chain Analysis
Seamless-to-welded grade divergence creates a dual-track pricing architecture where API 5L X80+ fatigue-resistant specifications command unit premiums in Brazil's pre-salt basins while electric-resistance-welded configurations compete on coil-feedstock economies across Permian gathering systems. This bifurcation concentrates pricing power with rotary piercing mills in Argentina and Mexico while squeezing welded pipe margins through Turkish scrap volatility.
Pricing Analysis
Capacity additions in China's Baoji seamless corridor are reshaping price floors for API 5L X70+ grades, pressuring Latin American mill premiums. Contract-based long-term offtake dominates supermajor procurement in deepwater projects, while spot-market transactions govern midstream trunk line purchases. Price differentiation rests on NACE MR0175 sour service certification and automated ultrasonic testing compliance. Cost compression in welded pipe intensifies as Vietnamese scrap import demand swings electric arc furnace feedstock costs. Independent gas producers in Appalachia exhibit highest price sensitivity; Brazilian pre-salt operators show least sensitivity due to schedule-certainty premiums.
Supply Chain Analysis
Single-source vulnerability sits with seamless rotary piercing capacity concentrated in Argentina, Mexico, and Italy. Raw material flows draw from Turkish scrap yards, Australian iron ore, and Chinese hot-rolled coil. The supply chain hinges on ASME Section IX welder certification chokepoints in Houston and Dammam. Distribution runs through engineering-procurement-construction bundlers consolidating mill-to-wellhead logistics for deepwater projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EPA methane compliance costs in US distribution networks and ANP domestic content thresholds in Brazilian subsea procurement, creating divergent margin structures for identical metallurgical grades.
For Market Incumbents: Deploy captive seamless mill networks to defend position against composite pipe substitution in shallow-water gathering applications. Backward integration into chrome-molybdenum billet supply secures sour service grade availability. Capacity rationalization in European welded pipe addresses scrap cost volatility exposure. For New Entrants and Emerging Players: Premium-to-economy price spreads in cryogenic LNG line pipe create entry space for specialized coating and lining service providers. Target Australia's Queensland corridor where NOPSEMA integrity mandates outpace local metallurgical capacity. Go-to-market through digital twin integration subscriptions bypasses capital-intensive mill construction. For Investors and Strategic Acquirers: Consolidation pressure builds where ASME welder certification backlogs constrain contractor throughput against deepwater project timelines. Long-term viability favors rotary piercing capacity with pre-qualified sour service grades. Watch ANP domestic content enforcement as inflection signal for Latin American supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Mill Capacity Expansion | Captures pre-salt specification premiums in Brazil's ANP-regulated procurement environment. |
| Automated Ultrasonic Testing Integration | Compresses third-party NDT lead times for West African offshore contractors. |
| Sour Service Metallurgy Licensing | Monetizes NACE MR0175-compliant grades across Permian and Bakken shale plays. |
| Digital Twin Platform Partnership | Opens recurring revenue from real-time corrosion monitoring subscriptions. |
| Scrap-to-Billet Backward Integration | Insulates welded pipe margins from Turkish and Vietnamese feedstock volatility. |
Research Methodology
Direct dialogue with procurement directors at supermajor oil companies, welding qualification supervisors at Houston certification centers, metallurgical engineers at seamless mill operators, and EPA compliance officers at Appalachian gas utilities grounded the qualitative foundation. Secondary validation drew from API specification bulletins, FERC certificate filings, ANP regulatory decrees, and customs trade data for alloy steel pipe imports. Bottom-up mill capacity modeling and top-down hydrocarbon infrastructure spend analysis provided triangulation.
Segment-level projections across seamless and welded pipe types, carbon through alloy material grades, and upstream through downstream applications fed into the analytical framework over the projection horizon. CAGRs derived from weighted average of infrastructure replacement cycles, regulatory compliance deadlines, and deepwater project sanctioning rates. CO2 pipeline specification development under ISO TC 67/SC 2 and composite pipe substitution thresholds informed scenario boundaries.
Caveats apply where EPA methane rule enforcement intensity or Brazilian pre-salt development pacing could materially shift the outlook. Forecasts embed assumptions regarding scrap cost normalization and welder certification throughput expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Frac Stack Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Tight Gas Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Digital Oilfield Services Market