
 Oceania Telemedicine Market | 2026-2036
Oceania Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Oceania Telemedicine Market Intelligence
Rural healthcare delivery is restructuring demand patterns across Oceania. Philips Healthcare leverages integrated diagnostic imaging platforms to anchor hospital network partnerships in Australia. Teladoc Health competes through employer-focused virtual care contracts spanning corporate clients in Sydney and Melbourne. AMD Global Telemedicine specializes in portable examination systems designed for remote Indigenous health clinics operating beyond fixed infrastructure.
Telemedicine encompasses real-time clinical services delivered through synchronous video, asynchronous store-and-forward imaging, and remote patient monitoring hardware with FDA 510(k) or TGA conformity assessment clearance. Video conferencing platforms dominate current deployment volume, while wearable devices with embedded biosensors represent the fastest-expanding technology segment as cardiac and glucose monitoring migrate from clinic to home settings. Monitoring services capture expanding margin pools as chronic disease management shifts toward subscription-based remote oversight models.
Australia's Therapeutic Goods Administration regulates software-as-medical-device classifications, while New Zealand's Health Information Standards Organisation mandates interoperability protocols for cross-platform data exchange. Australia's Digital Health Agency and New Zealand's Te Whatu Ora jointly shape procurement standards that determine market access for international platform vendors. Stakeholders must track evolving cybersecurity requirements under Australia's Essential Eight framework and position for integrated care funding reforms that reward outcomes over episodic billing.
Market Dynamics
Rural specialist access gaps across Australia's Northern Territory and New Zealand's South Island are forcing platform vendors to reconfigure deployment models around portable diagnostic hardware and satellite-enabled connectivity rather than conventional clinic-based video systems.
Growth Catalysts
- Digital Health Agency procurement standards:Australia's interoperability mandates for cross-platform data exchange are accelerating certified vendor onboarding into public hospital networks.
- Remote Indigenous health clinics:Fixed infrastructure deficits in Australia's outback communities are pulling portable examination systems into routine diagnostic workflows.
- Te Whatu Ora funding reforms:New Zealand's shift toward integrated care budgets rewards outcomes-based virtual oversight models over episodic fee-for-service billing.
Market Restraints
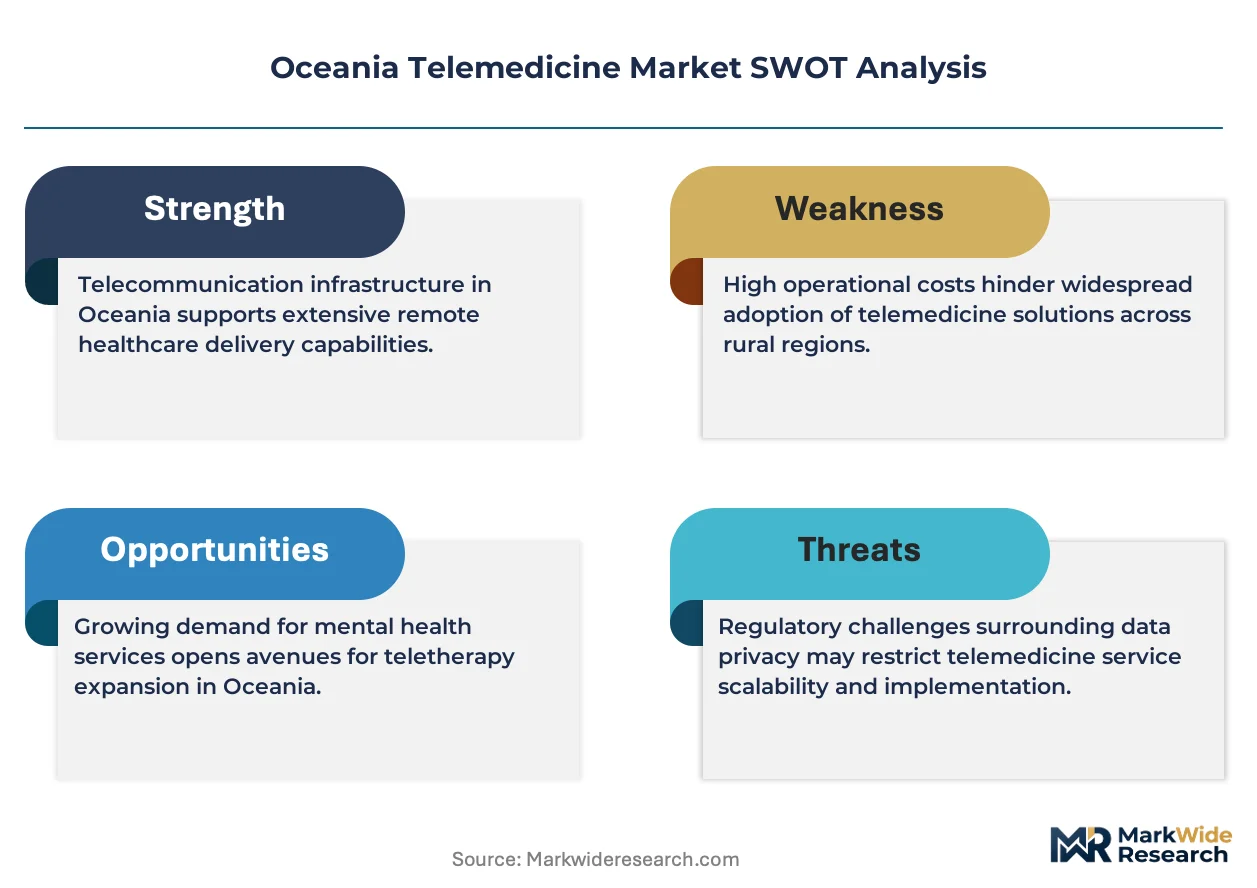
- TGA software-as-medical-device classification complexity:Australia's regulatory framework imposes extended conformity assessment timelines on AI-enabled diagnostic modules.
- Satellite bandwidth cost volatility:Remote clinic connectivity depends on geostationary link pricing that fluctuates with orbital slot scarcity.
- Specialist workforce concentration:Clinical expertise pools in Sydney, Melbourne, Auckland, and Wellington, constraining synchronous consultation availability for rural time zones.
Strategic Opportunities
- New Zealand's South Island rural districts:Specialist access gaps in Otago and Southland remain underpenetrated by asynchronous store-and-forward imaging platforms.
- Cardiac implantable biosensor convergence:Integration between pacemaker remote monitoring and telemedicine dashboards creates subscription-based chronic disease management white space.
- Australia's Essential Eight cybersecurity framework:Compliance requirements for critical infrastructure protection are creating procurement preference for hardened platform architectures.
Industry Challenges
- Interoperability engineering talent scarcity:Health Information Standards Organisation protocol implementation requires specialized integration expertise that outpaces regional training pipeline output.
- Legacy hospital information system integration friction:Cerner and Epic deployments in major Australian health networks resist seamless API connectivity with emerging telemedicine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oceania Telemedicine Market |
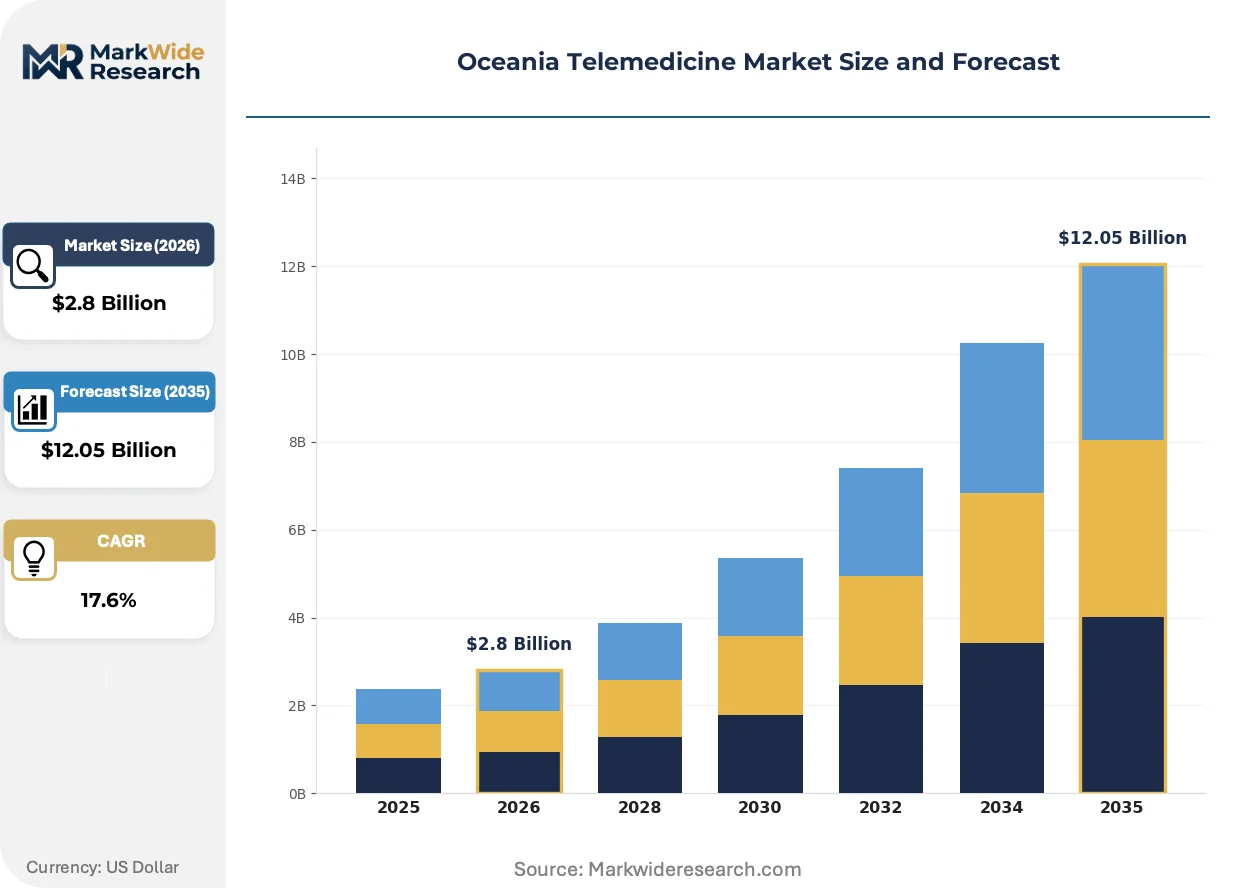
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Remote Monitoring, Mobile Health Apps, Wearable Devices End User: Healthcare Providers, Patients, Insurance Companies, Corporate Clients Service Type: Consultation Services, Diagnostic Services, Monitoring Services, Emergency Services Delivery Model: SaaS, PaaS, IaaS, Managed Services |
| Companies Covered | Teladoc Health, Philips Healthcare, GE Healthcare, Medtronic, AMD Global Telemedicine, GlobalMed, Amwell, Talkspace, Sumitomo Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oceania Telemedicine Market Strategic Shifts & Innovations
Platform architecture decisions are pivoting toward edge-computing diagnostics and regulatory-grade cybersecurity as baseline competitive requirements rather than premium differentiators.
Wearable cardiac monitors with embedded arrhythmia detection algorithms are electrifying chronic disease management workflows. Australia's remote Indigenous health services are deploying these devices at scale for post-discharge oversight. This technology is compressing the interval between physiological event detection and clinician intervention from days to minutes.
Australia's Therapeutic Goods Administration expanded software-as-medical-device classifications in 2021 to capture AI diagnostic modules previously exempt from pre-market review. This reclassification is forcing platform vendors to submit conformity assessments for machine learning-enabled image analysis tools. Remote radiology interpretation services are responding by segregating AI-assisted reads from fully automated diagnostic outputs to manage regulatory exposure.
Employer-sponsored virtual care contracts are displacing traditional health insurer intermediaries in metropolitan Australia. Corporate procurement teams in Sydney and Melbourne are negotiating direct platform relationships that bundle primary care, mental health, and chronic disease management into per-employee-per-month pricing. This channel shift is most visible among ASX-listed companies with 500-plus workforces seeking to reduce group health premium inflation.
Oceania Telemedicine Market Segmentation
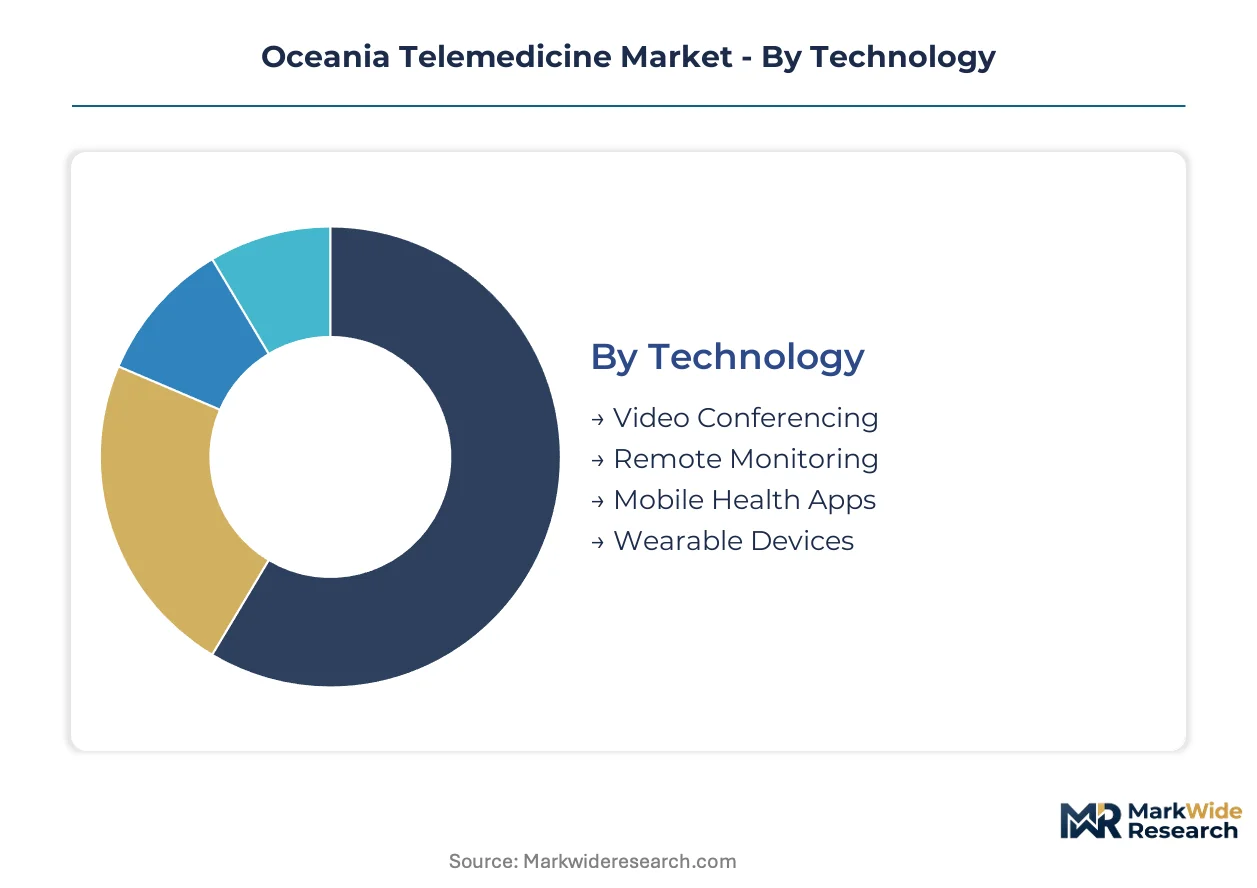
Telemedicine platforms in Oceania require precise segmentation to capture how technology layers integrate with clinical workflows. Australia's Therapeutic Goods Administration software classifications and New Zealand's interoperability mandates create distinct deployment patterns across each segment boundary.
Technology:
Integration depth varies sharply: video conferencing operates as standalone infrastructure, while wearable devices embed biosensors into continuous physiological streams.
- Video Conferencing:Real-time synchronous platforms with TGA-certified encryption protocols anchor hospital network deployments. Demand concentrates in Australia's Northern Territory remote clinics where satellite-enabled links bridge specialist access gaps.
- Remote Monitoring:Hardware-software combinations track cardiac rhythms, glucose levels, and respiratory metrics through cloud-connected dashboards. New Zealand's South Island rural districts are pulling these systems into chronic disease management workflows as Te Whatu Ora shifts toward integrated care budgets.
- Mobile Health Apps:Patient-facing interfaces for appointment scheduling and asynchronous messaging.
- Wearable Devices:Embedded biosensors with FDA 510(k) or TGA conformity assessment clearance for arrhythmia detection.
Volume placements concentrate in video conferencing infrastructure; the faster expansion belongs to remote monitoring hardware as chronic disease management migrates from clinic to home settings.
End User:
Procurement authority determines platform configuration complexity, with healthcare providers demanding clinical-grade integrations that patients bypass through direct-to-consumer channels.
- Healthcare Providers:Public hospital networks and remote Indigenous health clinics require TGA-certified platforms with Epic and Cerner API connectivity. Australia's Digital Health Agency procurement standards are filtering uncertified vendors from public tenders.
- Patients:Direct consumers accessing mental health and primary care through employer-sponsored or out-of-pocket arrangements. Sydney and Melbourne corporate workforces are negotiating per-employee-per-month bundles that displace traditional insurer intermediaries.
- Insurance Companies:Payors integrating telemedicine into policy benefits and claims workflows.
- Corporate Clients:ASX-listed entities with 500-plus workforces seeking premium inflation containment through direct platform contracts.
Healthcare providers dominate current procurement volume; patient-direct channels are climbing the fastest as employer sponsorship reshapes metropolitan access patterns.
Service Type:
Margin structure diverges across episodic billing versus subscription-based oversight models.
- Consultation Services:Synchronous video encounters for primary care, mental health, and specialist referrals. Australia's remote Indigenous communities depend on these for routine access to physicians concentrated in coastal cities.
- Monitoring Services:Continuous physiological oversight through wearable-integrated dashboards generating recurring revenue. New Zealand's integrated care funding reforms reward outcomes-based virtual oversight over fee-for-service billing.
- Diagnostic Services:Store-and-forward imaging and AI-assisted radiology interpretation with TGA software-as-medical-device classification compliance.
- Emergency Services:Triage and stabilization guidance for remote locations awaiting transport.
Consultation services capture the largest transaction volume; monitoring services exhibit the steepest expansion trajectory as chronic disease management shifts toward subscription economics.
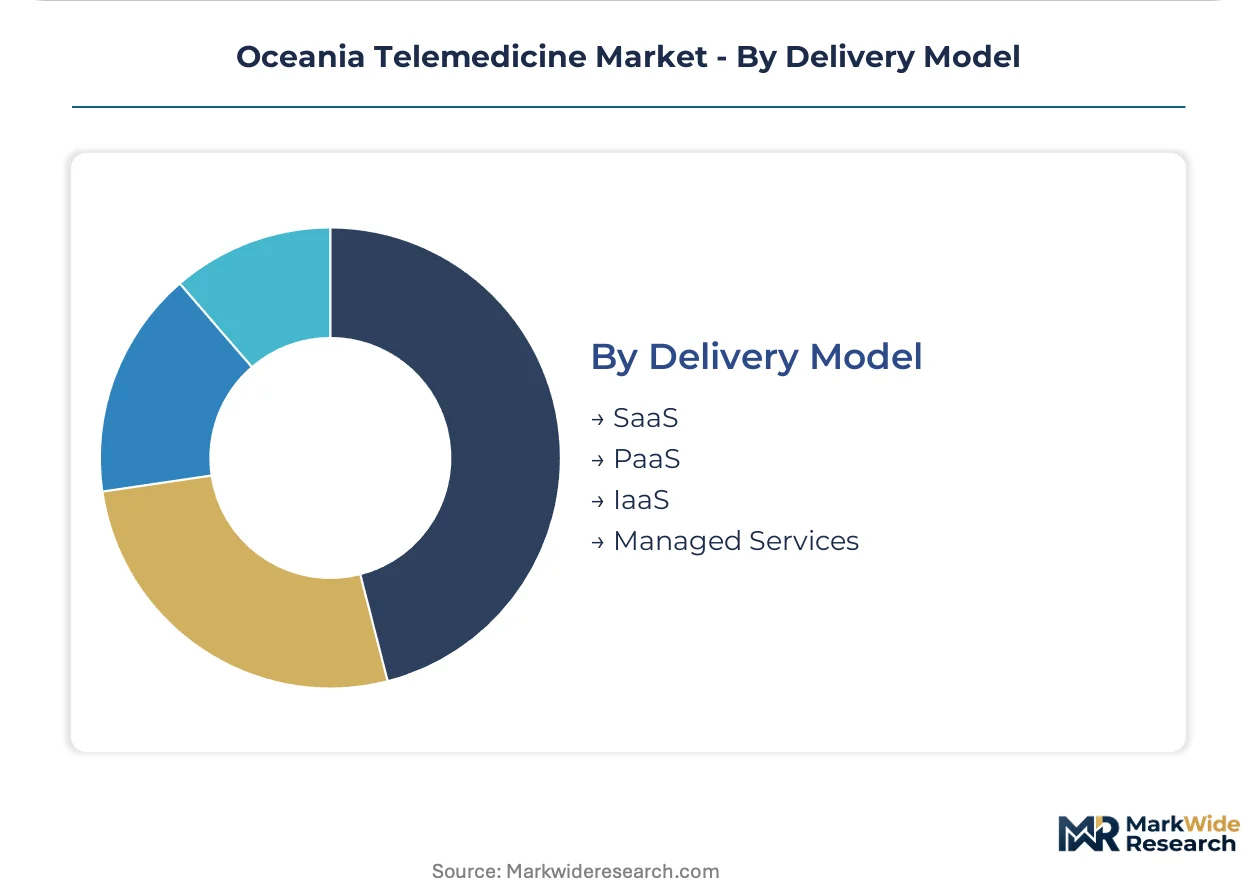
Delivery Model:
Technical ownership responsibilities shift from vendor-controlled infrastructure to client-managed deployments.
- SaaS:Cloud-hosted platforms with vendor-managed security patching and feature updates. Australia's Essential Eight cybersecurity framework creates procurement preference for hardened SaaS architectures in critical infrastructure protection.
- Managed Services:Outsourced platform operation including connectivity provisioning and clinical workflow integration. New Zealand's Health Information Standards Organisation protocol implementation requirements are pulling specialized integration expertise into managed arrangements.
- PaaS:Development environments for custom telemedicine application builds.
- IaaS:Raw compute and storage resources with maximum client configuration control.
SaaS deployments hold the widest current footprint; managed services are gaining share fastest as interoperability engineering talent scarcity forces outsourcing of complex integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Remote Area Health Corps tax incentives and New Zealand's Health Information Standards Organisation procurement frameworks concentrate telemedicine investment in designated rural service zones across both nations.
Australia
Remote Indigenous health clinics in the Northern Territory and Western Australia drive demand for portable examination systems and satellite-enabled connectivity. The Therapeutic Goods Administration software-as-medical-device classification mandates conformity assessments for AI diagnostic modules entering public hospital networks. Sydney and Melbourne corporate clusters are negotiating direct employer-sponsored virtual care contracts that bypass traditional health insurers.
New Zealand
South Island rural districts in Otago and Southland exhibit persistent specialist access gaps that pull asynchronous store-and-forward imaging platforms into chronic disease workflows. Te Whatu Ora integrated care funding reforms reward outcomes-based virtual oversight over episodic fee-for-service billing. Auckland and Wellington concentrate clinical expertise pools while satellite-linked clinics serve dispersed rural populations.
Papua New Guinea
Fixed infrastructure deficits across highland provinces and island chains necessitate satellite-dependent telemedicine deployments for basic diagnostic reach. The national health department partners with Australian aid programs to provision portable examination hardware. Port Moresby anchors specialist referral networks while remote clinics rely on store-and-forward imaging for preliminary triage.
Fiji
Outer island health posts require maritime-serviced telemedicine equipment resistant to humidity and salt corrosion. The Ministry of Health and Medical Services coordinates with Australian development agencies on digital health infrastructure grants. Suva concentrates tertiary care capacity while remote island clinics depend on intermittent connectivity for specialist consultation access.
Solomon Islands
Scattered archipelago geography drives demand for solar-powered portable diagnostic kits with offline-capable data storage. The National Referral Hospital in Honiara manages teleradiology partnerships with Australian providers for complex case review. Provincial health centers leverage intermittent satellite bandwidth for emergency consultation triage during weather-limited transport windows.
Oceania Telemedicine Market Key Industry Players
Top-tier vendors anchor hospital network procurement, while mid-tier specialists and regional integrators compete on portable hardware customization and managed service contracts. Platform certification under Australia's Therapeutic Goods Administration and New Zealand's interoperability standards filters uncertified competitors from public tenders. Two strategic archetypes dominate: integrated diagnostic imaging conglomerates and portable examination system specialists. Competitive positioning depends on Epic and Cerner API connectivity depth plus Essential Eight cybersecurity framework compliance.
Among North American platform providers, Teladoc Health and Amwell occupy positions within employer-sponsored virtual care channels, while Philips Healthcare anchors integrated diagnostic imaging partnerships with Australian hospital networks. AMD Global Telemedicine exemplifies the portable examination system specialist archetype serving remote Indigenous health clinics beyond fixed infrastructure.
| Leading Market Players |
|---|
| Teladoc Health |
| Philips Healthcare |
| GE Healthcare |
| Medtronic |
| AMD Global Telemedicine |
| GlobalMed |
| Amwell |
| Talkspace |
| Sumitomo Corporation |
| Others |
Cost & Logistics Intelligence
Interoperability engineering talent concentration in Australia's major metropolitan hubs compresses labor-cost differentials between Sydney-based platform developers and regional system integrators, widening pricing-tier spreads across TGA-certified premium deployments and uncertified economy alternatives.
Pricing Analysis
Short lead-time premiums for TGA software-as-medical-device conformity assessments command substantial markups over standard-queue submissions. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade hospital network contracts from employer-sponsored virtual care bundles and direct-to-consumer app subscriptions. Pricing pressure stems from satellite bandwidth cost volatility in remote clinic deployments. Corporate clients in Sydney and Melbourne exhibit lowest price sensitivity due to premium inflation containment mandates, while remote Indigenous health services face acute budget constraints.
Supply Chain Analysis
Direct-to-healthcare-provider channels handle enterprise hospital network demand, while distributor-mediated pathways serve remote clinic hardware procurement. Component manufacturing concentrates in China, South Korea, and Taiwan for biosensor modules, cloud infrastructure, and satellite connectivity terminals. Raw material dependencies include lithium-ion cells for wearable power systems, semiconductor wafers for edge-computing diagnostics, and rare earth elements for precision sensor arrays. Single-source vulnerability in geostationary satellite orbital slot allocation creates supply chain risk for remote connectivity provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's Therapeutic Goods Administration software-as-medical-device classification complexity creates a cost-of-compliance barrier that rewards early certification investment and filters speculative entrants from public procurement channels.
For Market Incumbents: Extend TGA certification coverage into AI-enabled diagnostic modules before regulatory scope expansion hardens compliance moats. Deepen Epic and Cerner API connectivity to lock hospital network switching costs. Counter emerging portable examination system specialists by integrating satellite-enabled connectivity into managed service bundles for remote Indigenous health clinics.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in employer-sponsored virtual care channels creates entry space for mid-tier platforms bundling primary care and mental health. Target New Zealand's South Island rural districts where asynchronous store-and-forward imaging remains underpenetrated. Pursue direct corporate procurement relationships in Melbourne and Sydney that bypass traditional health insurer intermediaries.
For Investors and Strategic Acquirers: The window for entry favors platform vendors with hardened Essential Eight cybersecurity architectures and established Te Whatu Ora procurement relationships. Long-term viability hinges on outcomes-based revenue models aligned with integrated care funding reforms. Monitor Te Whatu Ora budget allocation shifts toward virtual oversight as the inflection signal for subscription revenue acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software Certification | Conformity assessment clearance unlocks public hospital network procurement under Digital Health Agency standards. |
| Epic and Cerner API Integration | Seamless connectivity with legacy hospital information systems reduces deployment friction in major Australian health networks. |
| Satellite Connectivity Partnership | Geostationary link provisioning enables specialist consultation access beyond terrestrial infrastructure limits. |
| Essential Eight Compliance Program | Cybersecurity framework adherence creates procurement preference for critical infrastructure protection mandates. |
| Te Whatu Ora Reimbursement Strategy | Outcomes-based pricing alignment captures integrated care budget shifts away from episodic fee-for-service billing. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings in this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from TGA filings, Te Whatu Ora budget disclosures, and satellite operator tariff schedules. Bottom-up platform deployment counts and top-down healthcare expenditure triangulation anchored market sizing.
Rate-of-change decomposition across technology segments, end-user procurement channels, service type revenue models, and delivery model ownership structures informed the analytical framework. CAGRs were derived from segment-level growth trajectory modeling. Forecast inputs included Te Whatu Ora integrated care budget allocation patterns and Australia's Digital Health Agency procurement standard evolution.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time satellite bandwidth pricing introduce uncertainty bands around remote deployment cost projections. Forecasts reflect assumptions regarding regulatory timeline stability and funding reform implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Online Therapy Services Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Telepathology Service Market
Telemedicine
US Telemedicine Market
Telemedicine
US Telehealth Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Telestroke Services Market
Telemedicine
India Telehealth Services Market
Telemedicine
GCC Telemedicine Market