
 Telestroke Services Market | 2026-2036
Telestroke Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telestroke Services Market Analytics
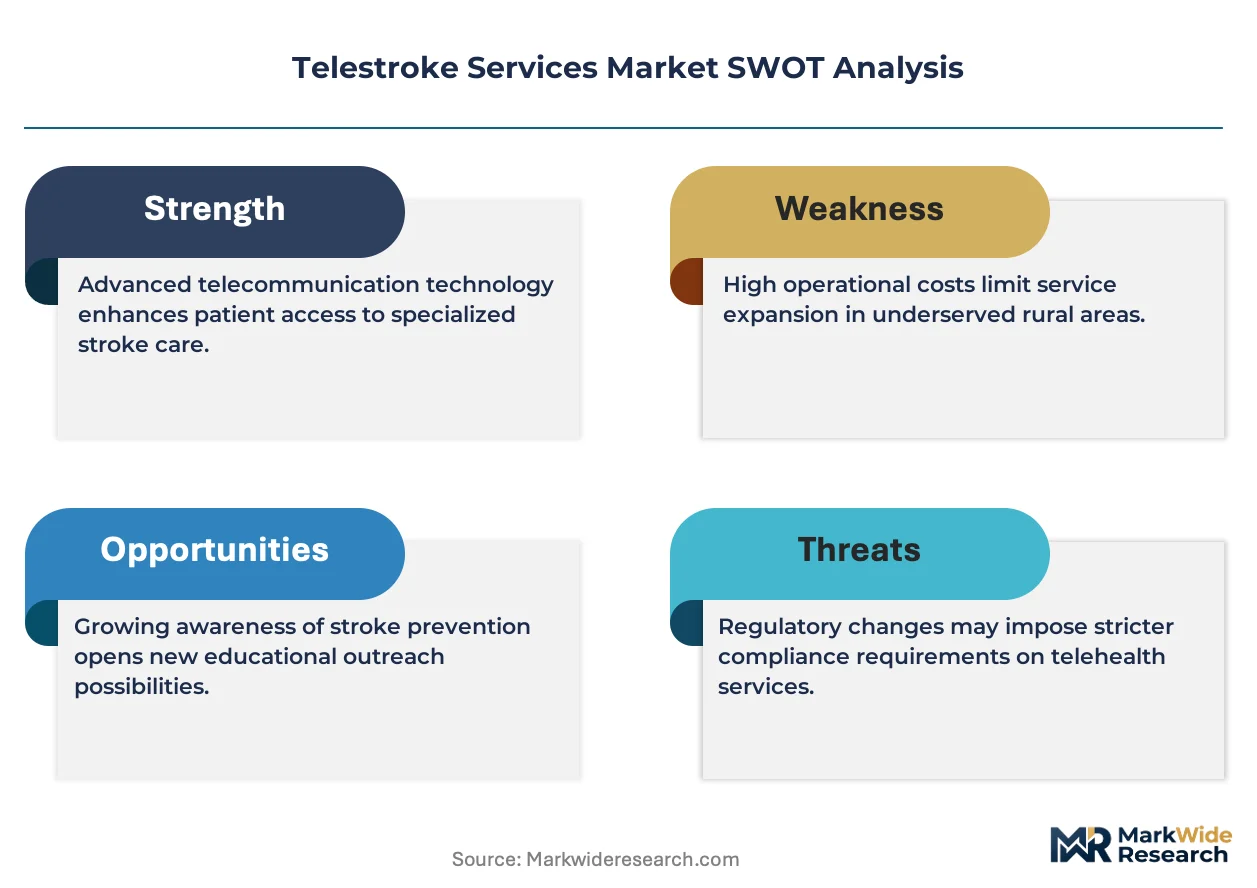
Cloud-based infrastructure is consolidating as the dominant delivery backbone for telestroke platforms, replacing legacy on-premise hardware that required dedicated IT staffing at each hospital node. Teladoc Health leverages its enterprise-scale video architecture to serve multi-hospital networks across dispersed geographies. Eagle Telemedicine anchors its competitive position through neurologist-staffed command centers that sustain 24/7 response protocols for emergency consultation. Sevaro Health differentiates by specializing in acute stroke triage workflows that integrate directly with emergency department admission systems.
Telestroke services encompass real-time audio-visual consultation, diagnostic image transmission, and remote neurologist assessment to guide thrombolytic therapy decisions within critical treatment windows. The technical stack requires sub-30-second connection latency, DICOM-compliant imaging relays, and HIPAA-encrypted data channels to support time-sensitive clinical interventions. Video conferencing technology leads current deployment volumes due to established reimbursement pathways and minimal hardware requirements at spoke facilities. Emergency consultation services command the highest per-episode margins, while rehabilitation support represents the fastest-expanding segment as post-acute care shifts toward home-based monitoring models.
FDA oversight of Software as a Medical Device intersects with state-level telehealth prescribing regulations and CMS reimbursement policies to shape market access conditions for telestroke vendors. HIPAA security rules and state medical board licensing requirements create compliance complexity that favors vendors with dedicated regulatory operations. Stakeholders must monitor evolving FDA guidance on AI-assisted diagnostic tools, as algorithm-driven image interpretation threatens to reshape competitive positioning among established platform providers.
Market Dynamics
Cloud-based infrastructure is consolidating as the dominant delivery backbone for telestroke platforms, replacing legacy on-premise hardware that required dedicated IT staffing at each hospital node. This technical shift compresses deployment timelines and reduces capital barriers for rural spoke facilities seeking specialist neurology coverage.
Growth Catalysts
- Reimbursement parity laws:United States state-level mandates requiring equivalent payment for telehealth and in-person stroke consultations eliminate financial disincentives for provider adoption. Rural hospital networks accelerate enrollment as margin pressure from specialist shortages intensifies.
- 24/7 neurologist command centers:Staffed response protocols sustain sub-30-second connection latency for thrombolytic therapy decisions. Emergency departments gain access to specialist assessment without maintaining costly on-call rosters.
- DICOM-compliant imaging relays:Standardized diagnostic transmission enables seamless integration with existing radiology infrastructure. Spoke facilities leverage existing CT and MRI investments without parallel hardware procurement.
Market Restraints
- State medical board licensing fragmentation:Interstate practice restrictions require neurologists to hold multiple state licenses. Compliance complexity favors vendors with dedicated regulatory operations but raises staffing costs for multi-state coverage.
- HIPAA security rule enforcement variance:Audit intensity differs across state jurisdictions, creating uncertainty for platform providers. Penalty exposure concentrates in states with active attorney general enforcement.
- Legacy EHR integration costs:Proprietary admission systems at spoke hospitals demand custom API development. Integration timelines extend 6-18 months per facility, delaying revenue recognition.
Strategic Opportunities
- Post-acute rehabilitation monitoring:Home-based recovery tracking represents an underpenetrated extension of acute telestroke services. Wearable integration enables continuous functional assessment beyond hospital discharge.
- AI-assisted image interpretation:Algorithm-driven diagnostic tools promise to compress specialist response times for hemorrhagic stroke detection. FDA Software as a Medical Device pathways are clarifying approval requirements.
- Southeastern United States network density:Elevated stroke incidence rates and hospital consolidation create acute specialist access gaps. Regional hub-and-spoke configurations achieve critical mass for dedicated command center economics.
Industry Challenges
- Neurologist workforce scarcity:Fellowship-trained vascular specialists concentrate in academic medical centers. Recruitment for telestroke command centers competes with lucrative private practice and academic appointments.
- Sub-30-second latency engineering:Network architecture must guarantee connection speeds for time-sensitive interventions. Rural broadband infrastructure gaps in spoke facility locations degrade service reliability.
- CMS reimbursement policy volatility:Telehealth flexibilities enacted during public health emergencies face expiration pressure. Coverage uncertainty delays hospital capital commitment to platform contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telestroke Services Market |
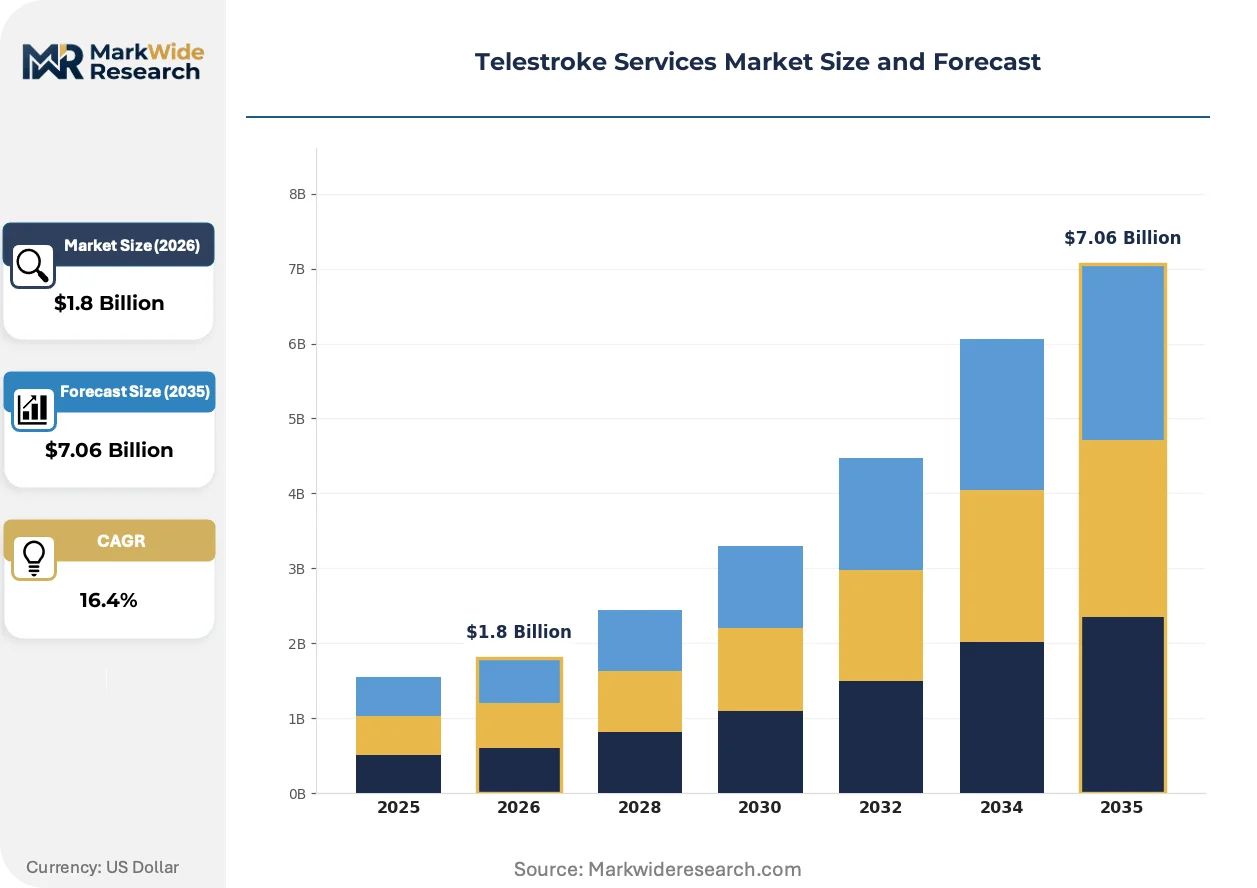
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Remote Patient Monitoring, Image Transmission, Data Analytics Service Type: Emergency Consultation, Follow-Up Care, Evaluation Services, Rehabilitation Support End User: Healthcare Providers, Hospitals, Rehabilitation Centers, Home Care Services Delivery Model: SaaS, PaaS, On-Premise, Hybrid |
| Companies Covered | Teladoc Health, American Well, Eagle Telemedicine, Sevaro Health, Access TeleCare, Providence, Lakewood Health System, TeleSpecialists, DispatchHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telestroke Services Market Evolving Landscape
Artificial intelligence and machine learning architectures are actively reshaping diagnostic workflows within telestroke platforms. These technologies promise to compress decision timelines while introducing new regulatory complexity around algorithm validation.
Machine learning algorithms for hemorrhage detection and large vessel occlusion identification are integrating into commercial telestroke platforms. Academic medical centers in the United States and Germany pilot these tools for pre-hospital triage decisions. The technology is integrating emergency medical services dispatch with hospital preparation protocols, collapsing door-to-needle intervals.
FDA guidance on Software as a Medical Device is clarifying approval pathways for AI-assisted diagnostic tools. Pre-submission programs enable vendors to align algorithm validation studies with regulatory expectations. Stroke imaging interpretation tools face heightened scrutiny due to the irreversible consequences of thrombolytic therapy decisions.
Hospital procurement departments now demand outcome-based contracting for telestroke services. Traditional per-consultation fee structures face displacement from episode-based pricing tied to door-to-needle time performance. Southeastern United States health systems lead this transition, linking vendor compensation to measurable quality metrics.
Telestroke Services Market Segmentation
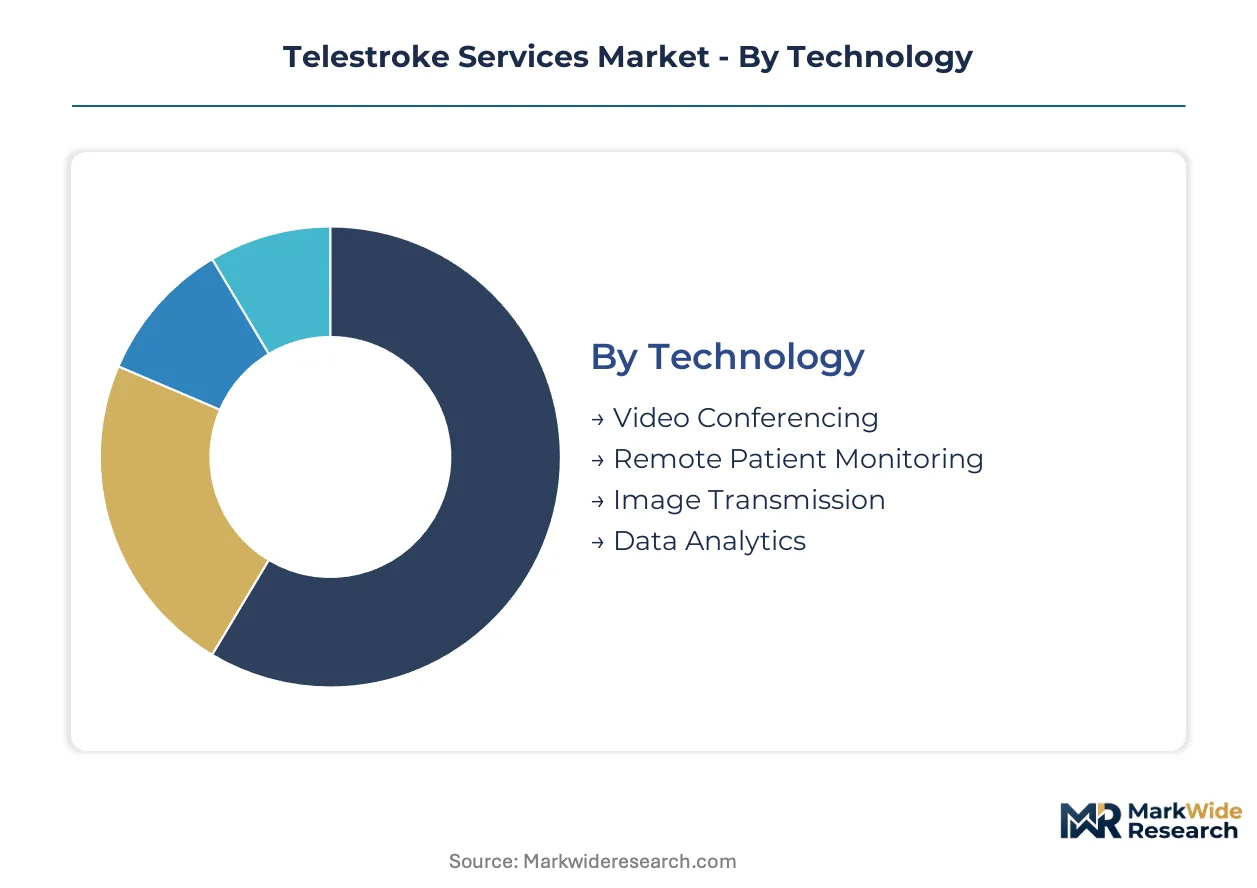
Telestroke service configurations vary dramatically across deployment contexts, with technology infrastructure and care delivery models determining both clinical utility and economic viability for spoke facilities. Segment differentiation reflects the tension between time-critical emergency workflows and longitudinal post-acute monitoring requirements.
Technology:
Technical specifications differentiate buyers by latency tolerance, imaging integration depth, and IT staffing constraints at rural endpoints.
- Video Conferencing:Real-time audio-visual platforms establish sub-30-second connection protocols for thrombolytic therapy decisions. Demand concentrates in southeastern United States rural networks where CMS reimbursement parity eliminates financial barriers for emergency department adoption.
- Image Transmission:DICOM-compliant relay systems enable seamless CT and MRI transmission to command center neurologists. Academic medical centers in Germany and the United States drive deployment as pre-hospital triage integration compresses door-to-needle intervals.
- Remote Patient Monitoring:Continuous physiological tracking extends specialist oversight beyond acute episodes.
- Data Analytics:Algorithm-driven outcome measurement supports value-based contracting with hospital procurement departments.
Video conferencing leads volumes today; image transmission is gaining share fastest as AI-assisted hemorrhage detection matures.
Service Type:
Clinical application intensity shapes procurement patterns, with emergency workflows commanding premium pricing against routine follow-up services.
- Emergency Consultation:24/7 neurologist-staffed response protocols guide time-sensitive thrombolytic decisions within critical treatment windows. Rural hospital networks in the southeastern United States accelerate adoption as workforce shortages intensify specialist access gaps.
- Rehabilitation Support:Home-based functional recovery tracking enables continuous post-discharge assessment through wearable integration. Medicare Advantage plans in Florida and Texas expand coverage as post-acute care shifts toward community-based monitoring models.
- Follow-Up Care:Scheduled remote consultations manage medication adherence and secondary prevention.
- Evaluation Services:Diagnostic confirmation and treatment eligibility assessments support transfer decisions.
Emergency consultation commands margin concentration today; rehabilitation support shows the steepest expansion trajectory as bundled payment models mature.
End User:
Facility type determines integration complexity, with acute care sites requiring immediate EHR connectivity against home settings demanding consumer-grade accessibility.
- Hospitals:Emergency departments and stroke units require HIPAA-encrypted channels with guaranteed latency for thrombolytic therapy windows. Rural critical access hospitals in Mississippi and Alabama drive enrollment as consolidation eliminates on-site neurology coverage.
- Home Care Services:Post-acute monitoring platforms deploy wearable-enabled functional assessment for discharged patients. Medicare-certified home health agencies in Georgia and South Carolina pilot remote rehabilitation as readmission penalty exposure intensifies.
- Healthcare Providers:Multi-specialty group practices integrate telestroke for outpatient stroke risk management.
- Rehabilitation Centers:Inpatient and outpatient therapy facilities extend specialist oversight for recovery protocols.
Hospitals anchor current deployment volumes; home care services are expanding most quickly as payment models shift toward episode-based accountability.
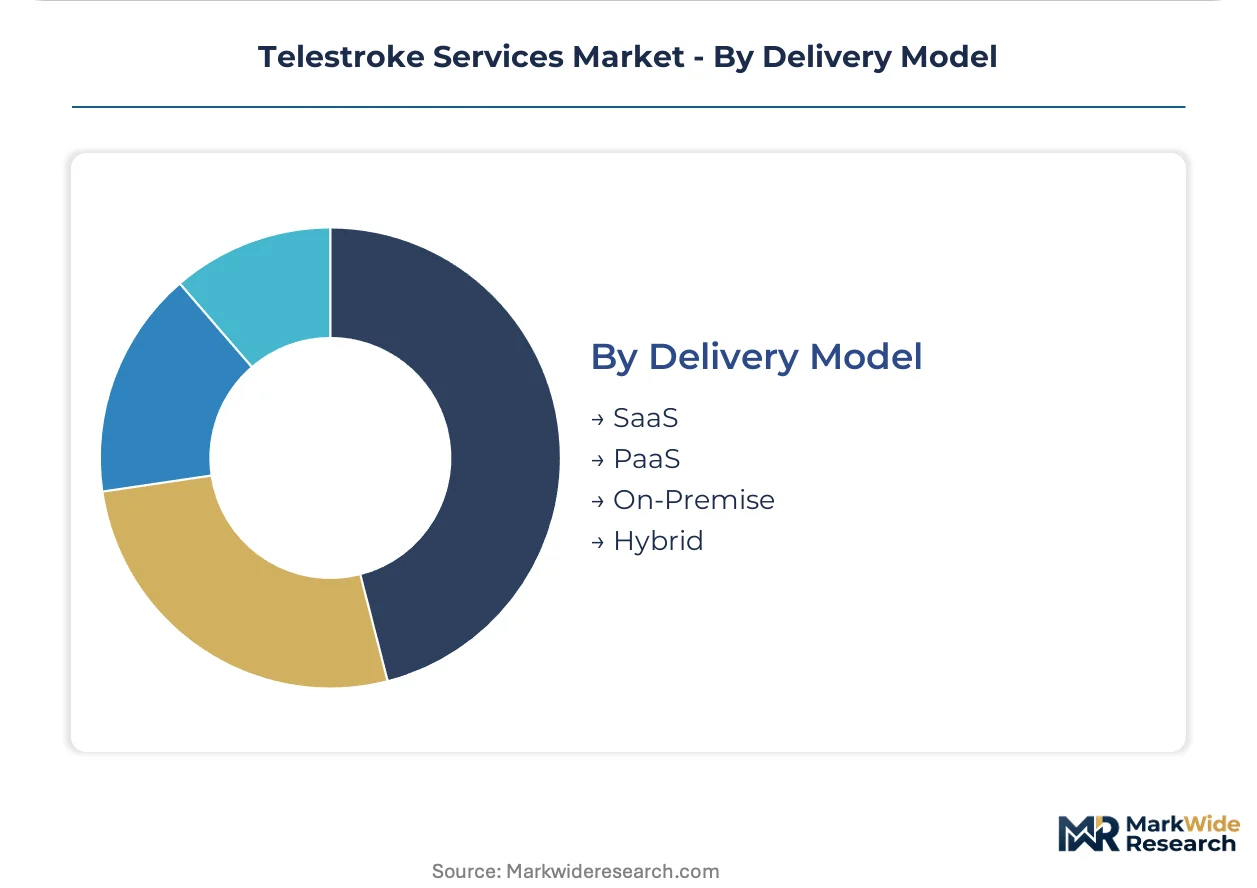
Delivery Model:
Capital structure preferences divide buyers between subscription flexibility and control requirements for sensitive patient data.
- SaaS:Cloud-hosted platforms eliminate dedicated IT staffing requirements at spoke facilities. Rural hospital networks across Arkansas and Louisiana select subscription models to compress deployment timelines and avoid hardware procurement cycles.
- Hybrid:Mixed cloud-local architectures balance data sovereignty concerns with scalability needs. Health systems in North Carolina and Tennessee deploy hybrid stacks to maintain on-premise imaging storage while leveraging cloud-based video infrastructure.
- PaaS:Platform layers enable custom workflow development for specialized triage protocols.
- On-Premise:Legacy hardware installations persist in facilities with restrictive data residency policies.
SaaS dominates current procurement volumes; hybrid configurations are climbing the fastest as security and scalability requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States anchors telestroke service deployment, where stroke incidence rates and rural hospital consolidation generate acute demand for remote neurology coverage. State-level reimbursement parity laws and expanding telehealth licensing frameworks accelerate provider participation across dispersed geographies. Regional hub-and-spoke configurations achieve critical mass for dedicated command center economics.
United States
Rural hospital networks across Mississippi and Alabama accelerate adoption as workforce shortages intensify specialist access gaps. CMS reimbursement parity eliminates financial disincentives for emergency department enrollment. The southeastern cluster spanning Florida, Georgia, and South Carolina leads deployment volumes as hospital consolidation eliminates on-site neurology coverage.
Germany
Academic medical centers pilot AI-assisted hemorrhage detection for pre-hospital triage decisions. EMA regulatory frameworks clarify Software as a Medical Device approval pathways for algorithm-driven diagnostic tools. The Baden-Württemberg and Bavaria regions concentrate telestroke innovation as university hospitals integrate emergency medical services dispatch with hospital preparation protocols.
United Kingdom
NHS England stroke pathway redesigns mandate 24/7 specialist assessment availability for thrombolytic therapy windows. MHRA oversight intersects with NHS reimbursement policies to shape platform procurement conditions. London and the Southeast anchor deployment as integrated care systems consolidate rural spoke facility networks.
Canada
Provincial health authorities expand telestroke coverage across northern and remote communities facing neurologist scarcity. Health Canada regulatory clarity supports platform licensing for multi-provincial service delivery. Ontario and Quebec concentrate deployment volumes as academic medical centers establish hub-and-spoke networks with critical access hospitals.
Australia
Rural health districts leverage telestroke platforms to address geographic isolation from metropolitan stroke units. TGA oversight of Software as a Medical Device intersects with state-level telehealth prescribing regulations. New South Wales and Victoria anchor adoption as metropolitan teaching hospitals extend specialist coverage to regional emergency departments.
Telestroke Services Market Competitive Landscape
Global majors compete with regional champions across technology infrastructure and clinical staffing models, creating a tiered vendor landscape. Enterprise-scale video architecture providers face competition from neurologist-staffed command center specialists and acute workflow integrators. Two strategic archetypes dominate: cloud-platform operators leveraging existing telehealth infrastructure, and clinical-service specialists building dedicated stroke-response protocols. Competitive moves concentrate on strategic partnerships with hospital networks and technology licensing for imaging integration.
Within the enterprise platform tier, Teladoc Health and American Well occupy positions as scale-driven operators with multi-specialty telehealth infrastructure. Eagle Telemedicine and Sevaro Health exemplify the clinical-specialist archetype, anchoring competitive positioning through dedicated neurology staffing and acute triage workflow integration. Access TeleCare represents the regional-network model, sitting within hub-and-spoke configurations that achieve command center economics through geographic concentration.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| Eagle Telemedicine |
| Sevaro Health |
| Access TeleCare |
| Providence |
| Lakewood Health System |
| TeleSpecialists |
| DispatchHealth |
| Others |
Value Network & Pricing Analysis
Hospital procurement departments demanding outcome-based contracting for telestroke services force vendors to restructure cost bases around measurable quality metrics rather than per-consultation fees. This shift compresses margins for legacy pricing models while rewarding investments in AI-assisted triage tools that demonstrably reduce door-to-needle intervals.
Pricing Analysis
Neurologist staffing costs and cloud infrastructure fees pass through directly to spoke facility contracts, with SaaS-tiered subscription models dominating rural hospital procurement. Price differentiation hinges on response time guarantees and FDA Software as a Medical Device certification status for AI modules. Pricing pressure intensifies as Medicare Advantage plans in Florida and Texas expand bundled payment pilots that cap vendor compensation. Critical access hospitals in Mississippi and Alabama exhibit highest price sensitivity due to thin operating margins, while academic medical centers in Germany and the United States prioritize outcome-linked premiums over base rates.
Supply Chain Analysis
Domestic-content mandates in United States federal healthcare procurement programs reshape vendor sourcing toward HIPAA-compliant data centers within national borders. Cloud infrastructure concentrates in the United States, Germany, and United Kingdom where regulatory clarity supports health data residency requirements. The technical stack draws from specialized DICOM imaging hardware, encrypted video conferencing platforms, and FDA-validated algorithm modules. Single-source vulnerability concentrates in neurologist workforce pipelines, as fellowship-trained vascular specialists remain tethered to academic medical centers. Distribution runs through direct enterprise sales to hospital networks and GPO-negotiated contracts for multi-facility systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telestroke services present a margin-expansion trajectory as cloud infrastructure commoditizes and AI-assisted diagnostics command outcome-based premiums. Cost compression in SaaS delivery models frees capital for neurologist command center staffing and regulatory certification investments.
For Market Incumbents: Hedge against workforce scarcity by securing exclusive staffing contracts with academic medical centers in the southeastern United States. Build backward integration into AI algorithm development to capture value from FDA Software as a Medical Device approvals, insulating margins from pure-platform commoditization. For New Entrants and Emerging Players: Rural critical access hospitals in Alabama and Mississippi represent the most penetrable buyer archetype, as consolidation eliminates on-site neurology coverage and CMS reimbursement parity eliminates financial barriers. Home-based rehabilitation monitoring offers secondary white-space expansion as Medicare Advantage bundled payments mature. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-specialist platforms possessing dedicated neurologist staffing and established FDA regulatory pathways. Long-term viability hinges on command center economics achieving critical mass across hub-and-spoke networks. Watch for CMS telehealth flexibility extensions as the inflection signal for hospital capital commitment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | AI-assisted hemorrhage detection tools require FDA validation for reimbursement eligibility in United States emergency departments. |
| Hospital System Partnership | Hub-and-spoke configurations with Baptist Health or Tenet achieve command center economics through geographic concentration. |
| Neurologist Staffing Contract | Exclusive agreements with Emory or University of Alabama secure 24/7 specialist coverage for rural spoke facilities. |
| Platform Integration | DICOM-compliant imaging relays integrate with Cerner and Epic EHR systems to compress deployment timelines. |
| Reimbursement Strategy | Outcome-based contracting with CMS and Medicare Advantage plans ties vendor compensation to door-to-needle performance. |
Research Methodology
Multiple input streams — structured interviews with telestroke platform executives, hospital procurement managers, and CMS policy specialists; secondary validation through FDA 510(k) filings, hospital GPO contract databases, and CMS Medicare claims data; and academic medical center pilot study publications — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured deployment timelines, pricing structures, and neurologist staffing models across vendor archetypes.
Historical growth trajectories were cross-referenced against panel input from health system technology officers and telehealth regulatory attorneys. The analytical framework modeled volume and value across technology infrastructure, service type intensity, end-user facility category, and delivery model architecture. CAGRs were derived from spoke facility enrollment curves and reimbursement policy evolution across the projection horizon. Forecast inputs incorporated rural hospital consolidation rates and AI algorithm validation timelines.
Underlying measurement precision varies by segment; emergency consultation services and SaaS deployment models carry tighter precision than nascent rehabilitation monitoring and hybrid architectures. Forecasts reflect documented assumptions regarding CMS telehealth parity persistence and FDA AI guidance finalization. Stroke incidence demographic shifts and neurologist fellowship graduation rates present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
India Telehealth Services Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Tele-ICU Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Remote Healthcare Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Global Telehealth Market
Telemedicine
India Telemedicine Market
Telemedicine
Video Telemedicine Market