
 Asia-Pacific Ehealth Market | 2026-2036
Asia-Pacific Ehealth Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ehealth Market Outlook
Government-funded hospital networks is redrawing procurement priorities across the Asia-Pacific Ehealth landscape. Tencent Healthcare leverages its super-app ecosystem to anchor digital front-door services across tier-2 Chinese cities. Siemens Healthineers AG sustains R&D intensity in AI-powered diagnostic imaging workflows for radiology departments. Tata Consultancy Services competes on systems integration strength, embedding ehealth modules into existing hospital ERP architectures across India and Southeast Asia.
Ehealth encompasses digital technologies, telecommunications infrastructure, and software platforms that enable remote delivery, management, and exchange of health services and medical information between patients and providers. These systems integrate encrypted data transmission protocols, interoperable health record standards, and real-time biometric sensors to support clinical decision-making outside traditional facility settings. Telemedicine platforms currently occupy the largest revenue pool within product type categories, while wearable devices represent the fastest-expanding segment driven by glucose monitors and cardiac patches. Among technology layers, cloud computing dominates infrastructure spending, though artificial intelligence commands the highest margin concentration through diagnostic algorithms and predictive analytics tools.
Japan's PMDA and Australia's TGA enforce cybersecurity and data integrity standards that shape product certification timelines for connected medical devices entering their markets. India's CDSCO and China's NMPA maintain divergent approval pathways for software-as-medical-device classifications, fragmenting regional go-to-market strategies for platform vendors. The EU AI Act's extraterritorial reach into Asia-Pacific export markets adds compliance complexity for AI diagnostic tools sold into European patient populations. Stakeholders must monitor evolving reimbursement code expansions across national health insurance schemes to anticipate which application areas will unlock sustainable revenue streams.
Market Dynamics
Government reimbursement code expansions are compressing sales cycles for connected care platforms across Asia-Pacific hospital procurement offices. Federal telehealth coverage decisions in Australia and India's PLI scheme for medical electronics are forcing vendors to reconfigure pricing and localization strategies simultaneously.
Growth Catalysts
- Telehealth reimbursement codes:Australia's federal coverage for chronic disease management creates immediate budget line-item access for remote monitoring platforms in aged-care facilities.
- Medical electronics manufacturing incentives:India's PLI scheme stimulates domestic production of cardiac patches and glucose monitors, reducing import dependency for hospital networks.
- Cloud infrastructure scaling:Southeast Asian public hospital networks are accelerating procurement of connected care platforms through centralized government IT frameworks.
Market Restraints
- Fragmented software-as-medical-device pathways:India's CDSCO and China's NMPA maintain divergent classification criteria, forcing vendors to duplicate clinical validation studies.
- Cybersecurity certification delays:Japan's PMDA and Australia's TGA enforce data integrity standards that extend product launch timelines by 8-14 months for connected devices.
- Legacy ERP integration costs:Hospital networks in tier-2 Chinese cities face capital intensity when embedding ehealth modules into existing administrative architectures.
Strategic Opportunities
- EU AI Act extraterritorial compliance:Vendors building GDPR-aligned data governance for European exports gain competitive positioning in Australia's TGA and Japan's PMDA review queues.
- Tier-2 city hospital digitization:Chinese municipal health bureaus outside Beijing and Shanghai are procuring digital front-door services without incumbent vendor lock-in.
- Interoperable health record convergence:HL7 FHIR standard adoption across Singapore and South Korea creates white space for middleware vendors bridging legacy and modern systems.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized firmware developers for real-time biometric sensors command premium compensation in Bangalore and Shenzhen labor markets.
- Multi-jurisdiction patent navigation:AI diagnostic algorithm vendors face IP complexity when deploying predictive analytics tools across PMDA, TGA, and NMPA jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ehealth Market |
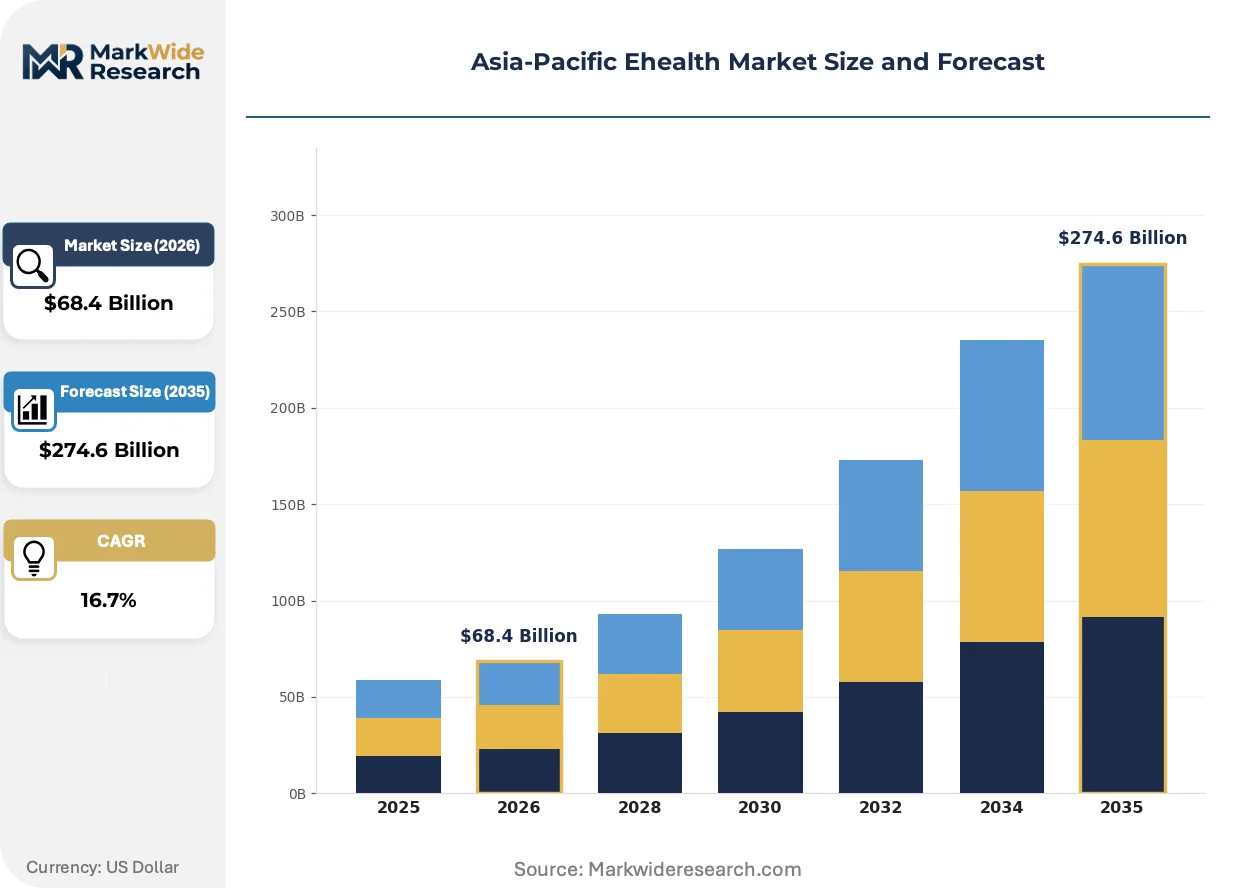
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $274.6 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Wearable Devices, Health Apps, EHR Systems Technology: Cloud Computing, Artificial Intelligence, Mobile Health, Blockchain End User: Hospitals, Patients, Healthcare Providers, Insurers Application: Disease Management, Remote Monitoring, Mental Health, Rehabilitation |
| Companies Covered | GE HealthCare Technologies, Inc., Koninklijke Philips N.V., IBM Corporation, Medtronic PLC, Siemens Healthineers AG, Cisco Systems, Inc., Teladoc Health, Inc., Tencent Healthcare, Tata Consultancy Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ehealth Market Strategic Shifts
Real-time biometric sensor networks are compressing the gap between acute and ambulatory care settings across Asia-Pacific health systems. Platform vendors must now architect for continuous glucose monitoring and cardiac patch data streams that feed directly into clinical decision support systems.
Edge computing architectures for wearable glucose monitors and cardiac patches are fragmenting the traditional cloud-centric data flow model. Tier-2 Chinese hospitals are piloting local inference nodes that process biometric signals before transmission to central servers. This topology reduces latency for critical alerts while creating new vendor categories for on-premise medical edge hardware.
Australia's TGA and Japan's PMDA are tightening cybersecurity pre-market requirements for connected medical devices entering their jurisdictions. Vendors must now submit software bill of materials and penetration testing documentation alongside traditional clinical evidence. AI diagnostic tools face the steepest compliance burden, with review timelines extending as regulators scrutinize algorithm update protocols.
Hospital procurement offices across Southeast Asia are consolidating vendor relationships through framework agreements that bundle hardware, software, and maintenance into multi-year contracts. This model displaces point-solution purchasing and favors systems integrators with existing ERP relationships. India's public hospital networks show the most pronounced shift, with state-level tenders now specifying interoperability with national health stack standards.
Asia-Pacific Ehealth Market Segmentation
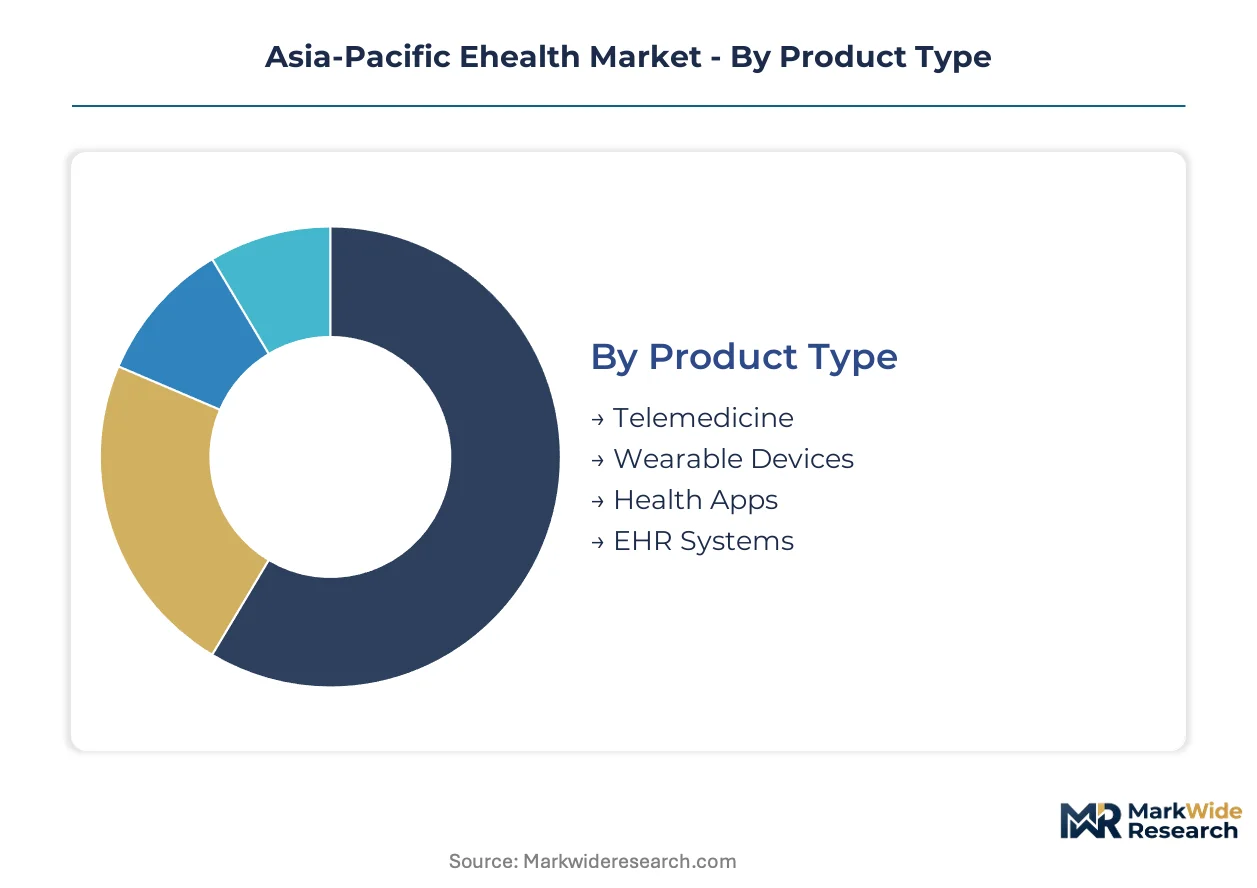
Asia-Pacific Ehealth procurement channels diverge sharply across segment categories. Hospital procurement offices favor integrated platform bundles, while direct-to-consumer channels dominate wearable device flows. Understanding these channel dynamics determines vendor go-to-market economics and partnership requirements.
Product Type:
Channel concentration varies dramatically by product category, with hospital networks driving bulk contracts for infrastructure-heavy segments while retail and pharmacy channels capture consumer-facing devices.
- Telemedicine:Real-time video consultation platforms with integrated prescription workflows and clinical documentation modules. Australian aged-care facilities and India's public hospital networks are expanding procurement through centralized government IT frameworks, with federal reimbursement codes creating immediate budget access for chronic disease management deployments.
- Wearable Devices:Continuous biometric monitoring hardware including glucose sensors, cardiac patches, and pulse oximeters with encrypted data transmission protocols. India's PLI scheme for medical electronics is stimulating domestic manufacturing capacity, reducing import dependency for hospital networks while enabling cost-competitive scaling in tier-2 Chinese cities.
- Health Apps:Consumer-facing mobile applications for symptom tracking, medication adherence, and wellness coaching with varying degrees of clinical validation.
- EHR Systems:Interoperable electronic health record platforms supporting HL7 FHIR standards for data exchange across provider networks.
Telemedicine dominates installed base across Asia-Pacific hospital procurement offices. Wearable Devices is where expansion concentrates, climbing the fastest as glucose monitors and cardiac patches penetrate ambulatory care settings.
Technology:
Margin profiles stratify across technology layers, with infrastructure components commanding volume scale while algorithmic tools capture premium pricing through diagnostic performance differentiation.
- Cloud Computing:Distributed server infrastructure enabling elastic storage and compute for health data workloads with regional data residency compliance. Southeast Asian public hospital networks are accelerating procurement through centralized government frameworks, with Singapore and South Korea leading health record modernization investments.
- Artificial Intelligence:Machine learning algorithms for diagnostic imaging interpretation, predictive analytics, and clinical decision support with regulatory scrutiny on update protocols. Japan's PMDA and Australia's TGA are extending review timelines by 8-14 months as they scrutinize algorithm transparency and cybersecurity documentation for AI diagnostic tools.
- Mobile Health:Cellular and WiFi-enabled platforms optimized for smartphone delivery in low-bandwidth environments.
- Blockchain:Distributed ledger architectures for health record authentication and supply chain traceability with limited production deployment.
Cloud Computing anchors current infrastructure spending. Artificial Intelligence is where margin expansion concentrates, with diagnostic algorithms commanding premium pricing through performance-based contracting models.
End User:
Procurement authority and budget cycles create distinct sales motion requirements across customer types, from multi-year framework agreements with hospital networks to individual subscription conversions for patient-direct platforms.
- Hospitals:Integrated delivery networks with centralized IT procurement functions and legacy ERP integration requirements. Tier-2 Chinese municipal health bureaus are procuring digital front-door services without incumbent vendor lock-in, creating white space for systems integrators embedding ehealth modules into existing administrative architectures.
- Patients:Individual consumers purchasing direct-to-consumer devices and subscription services through retail pharmacy and e-commerce channels. Australia's federal telehealth reimbursement expansion for chronic disease management is unlocking sustainable revenue streams for remote monitoring platforms in aged-care facilities.
- Healthcare Providers:Individual clinicians and small group practices selecting point solutions for specific clinical workflows.
- Insurers:Payers integrating ehealth platforms into benefit design and population health management programs.
Hospitals dominate contract value concentration. Patients is where volume scaling concentrates, with direct-to-consumer channels expanding most quickly across India and Southeast Asia.
Application:
Reimbursement code availability and clinical evidence requirements shape segment maturity, with established categories benefiting from regulatory clarity while emerging applications face validation timelines.
- Disease Management:Structured programs for chronic condition monitoring with protocolized intervention triggers and care coordinator dashboards. Australia's TGA reimbursement framework for chronic disease management is compressing sales cycles for connected care platforms in aged-care facilities, creating immediate budget line-item access.
- Remote Monitoring:Continuous ambulatory surveillance with automated alert generation for clinical deterioration events. Real-time biometric sensor networks are compressing the gap between acute and ambulatory care settings, with edge computing architectures in tier-2 Chinese hospitals processing signals locally before cloud transmission.
- Mental Health:Digital therapeutic interventions for behavioral health conditions with varying regulatory classification across jurisdictions.
- Rehabilitation:Remote physical therapy and post-acute recovery monitoring with motion sensing and adherence tracking.
Disease Management dominates current reimbursement coverage. Remote Monitoring is where technology investment concentrates, gaining share fastest as cardiac patches and glucose monitors feed directly into clinical decision support systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia-Pacific Ehealth Market relies on submarine cable networks linking Singapore, Hong Kong, and Sydney to underpin cloud infrastructure for telehealth platforms. Data center clusters in these hubs process biometric streams from wearable devices across the region.
China
Tier-2 municipal health bureaus in Chengdu and Wuhan are procuring digital front-door services without incumbent vendor lock-in. NMPA maintains divergent software-as-medical-device pathways that force vendors to duplicate clinical validation studies. The Yangtze River Delta cluster anchors edge computing pilots for cardiac patch data processing in local hospitals.
India
State-level public hospital tenders specify interoperability with national health stack standards, compressing procurement timelines. CDSCO classification criteria for AI diagnostic tools remain distinct from neighboring jurisdictions, fragmenting go-to-market strategies. Bangalore and Hyderabad labor markets command premium compensation for firmware developers specializing in real-time biometric sensors.
Japan
Tokyo's Kanto region concentrates demand for AI-powered diagnostic imaging workflows in radiology departments. PMDA enforces cybersecurity pre-market requirements that extend product launch timelines by 8-14 months for connected devices. Osaka's Kansai corridor hosts validation facilities scrutinizing software bill of materials for glucose monitor exports.
Australia
Federal telehealth reimbursement codes for chronic disease management create immediate budget line-item access in aged-care facilities. TGA data integrity standards shape certification timelines for cardiac patches entering the market. Sydney and Melbourne hospital networks are consolidating vendor relationships through multi-year framework agreements bundling hardware and software.
South Korea
Seoul Capital Area health systems lead HL7 FHIR standard adoption, creating white space for middleware vendors bridging legacy and modern architectures. MFDS maintains alignment with TGA cybersecurity protocols for connected medical devices. Busan-Ulsan corridor manufacturers supply encrypted transmission modules for regional glucose monitor production.
Asia-Pacific Ehealth Market Competitive Environment
Listed leaders compete with private specialists across infrastructure scale and regulatory navigation capabilities. The vendor base stratifies into three tiers: diversified conglomerates with hospital ERP integration strength, pure-play telehealth platforms with reimbursement expertise, and domestic champions leveraging manufacturing incentives. Systems integrators embed ehealth modules into existing administrative architectures, while AI diagnostic specialists concentrate on algorithm transparency documentation. Competitive moves center on framework agreement consolidation and multi-jurisdiction patent portfolio expansion.
Within the diversified technology tier, GE HealthCare Technologies, Inc. and Siemens Healthineers AG occupy positions anchored by diagnostic imaging workflows and hospital infrastructure relationships. Tencent Healthcare exemplifies the domestic champion archetype, leveraging super-app ecosystems to anchor digital front-door services across tier-2 Chinese cities. These three entities represent distinct strategic postures: conglomerate-scale platform bundling, specialized diagnostic AI development, and consumer-facing ecosystem integration.
| Leading Market Players |
|---|
| GE HealthCare Technologies, Inc. |
| Koninklijke Philips N.V. |
| IBM Corporation |
| Medtronic PLC |
| Siemens Healthineers AG |
| Cisco Systems, Inc. |
| Teladoc Health, Inc. |
| Tencent Healthcare |
| Tata Consultancy Services |
| Others |
Value Chain & Pricing Dynamics
Domestic cardiac patch manufacturing under India's PLI scheme is displacing imported glucose monitor assemblies from Southeast Asian hospital procurement pipelines, simultaneously compressing landed costs for tier-2 Chinese municipal health bureaus and eroding premium pricing power held by legacy device distributors across Australia and Japan.
Pricing Analysis
Volume-discount tiering structures separate framework-agreement hospital networks from spot-purchasing aged-care facilities across the Asia-Pacific Ehealth landscape. Pricing stratifies across premium, standard, and economy tiers differentiated by TGA/PMDA certification grade and after-sales service bundling. Cost compression in economy-tier wearable hardware is intensifying because domestic Indian manufacturing capacity is scaling faster than procurement budget expansion. Public hospital networks in Southeast Asia exhibit highest price sensitivity, while Japanese radiology departments show least sensitivity due to diagnostic performance contracting models.
Supply Chain Analysis
India and China anchor glucose monitor and cardiac patch production for Asia-Pacific hospital networks, with South Korea supplying encrypted transmission modules. Component sourcing draws from Taiwanese semiconductor foundries for sensor microcontrollers and Japanese precision optics for diagnostic imaging hardware. Single-source vulnerability concentrates in firmware development talent pools across Bangalore and Shenzhen. Distribution runs through government IT framework agreements in Southeast Asia and direct-to-consumer pharmacy channels for wearable devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory pathway fragmentation across PMDA, TGA, CDSCO, and NMPA jurisdictions is creating specialization niches for compliance-native vendors and middleware specialists bridging divergent certification requirements.
For Market Incumbents: Fortify framework agreement positions in Australian aged-care facilities by embedding AI diagnostic modules into existing Siemens and GE imaging workflows before CDSCO harmonization pressures pricing. Deepen backward integration into domestic Indian cardiac patch manufacturing through PLI-aligned joint ventures to neutralize emerging pure-play hardware entrants. Prioritize software bill of materials documentation investments to preempt PMDA cybersecurity review timeline extensions. For New Entrants and Emerging Players: Anchor in tier-2 Chinese municipal health bureaus procuring digital front-door services without Tencent ecosystem lock-in, where white space exists for HL7 FHIR-native middleware bridging legacy hospital ERP systems. Target India's state-level public hospital tenders specifying national health stack interoperability as the most penetrable procurement channel. Pursue systems integration partnerships with Tata Consultancy Services rather than direct hospital sales approaches. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms holding Australian federal reimbursement code expertise but lacking AI diagnostic algorithm portfolios. Long-term viability hinges on regulatory navigation capabilities across multiple Asia-Pacific jurisdictions rather than single-market scale. Watch for CDSCO-NMPA software-as-medical-device pathway convergence as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Securing TGA chronic disease management codes unlocks immediate budget access in Australian aged-care procurement. |
| Hospital System Partnership | Framework agreements with Southeast Asian public networks displace point-solution vendors through bundled multi-year contracts. |
| Software Companion Development | FHIR-native middleware bridging legacy ERP architectures captures tier-2 Chinese hospital digitization spending. |
| CE Marking Pathway | GDPR-aligned data governance for EU AI Act compliance accelerates PMDA and TGA review queue positioning. |
| Regulatory Approval Pathway | CDSCO software-as-medical-device classification expertise fragments less than dual NMPA-PMDA submission capabilities. |
Study Parameters
A standing panel of hospital procurement managers, biomedical firmware engineers, GPO contracts specialists, and CDSCO regulatory consultants provided ongoing calibration across primary fieldwork and secondary source triangulation. Primary inputs combined structured interviews with tier-1 and tier-2 Chinese municipal health bureau directors alongside Indian state-level tender documentation analysis. Secondary validation drew from TGA cybersecurity guidance updates, NMPA software classification bulletins, Australian Medicare Benefits Schedule reimbursement code amendments, and PLI scheme beneficiary disclosures. Bottom-up wearable device shipment modeling and top-down hospital IT budget allocation surveys were cross-referenced for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, technology layer, end-user procurement authority, and application reimbursement maturity. CAGRs were derived from elasticity-adjusted adoption curves incorporating regulatory timeline uncertainty. Forecast inputs included PMDA pre-market review duration assumptions and HL7 FHIR standard penetration rates across Singapore and South Korea health systems.
Underlying assumptions cover sustained PLI scheme funding, stable submarine cable connectivity for cloud infrastructure, and incremental reimbursement code expansion, with deviation risk concentrated in cybersecurity certification timeline extensions and firmware talent compensation inflation. Recalibration cycles align with material shifts in national health insurance scheme coverage decisions and software-as-medical-device classification harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Telepsychiatry Market
Telemedicine
Telepathology Service Market
Telemedicine
Global Telehealth Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Europe Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telehealth Services Market
Telemedicine
Global Virtual Care Market
Telemedicine
Teledermatology Market
Telemedicine
India Telemedicine Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Global Tele Intensive Care Unit Market