
 US Telemedicine Market | 2026-2036
US Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
US Telemedicine Market Analysis
Rural hospital systems is consolidating virtual specialty access as the fastest-growing demand channel for telemedicine platforms. Teladoc Health leverages its nationwide physician network to sustain coverage in underserved counties. American Well anchors enterprise contracts with regional health plans seeking white-label infrastructure. MDLive differentiates through behavioral health integration that competes with traditional outpatient models.
Telemedicine denotes the remote delivery of clinical services via real-time audiovisual communication, store-and-forward imaging, or remote patient monitoring devices transmitting physiologic data at minimum 128 kbps bandwidth. Its primary purpose extends diagnostic reach and chronic disease management beyond physical facility constraints. Video consultations command the largest revenue share among service types, while remote monitoring exhibits the steepest growth trajectory as RPM reimbursement broadens under CMS rules. AI-powered solutions within the technology segment attract concentrated R&D investment, though cloud-based platforms still occupy the majority of deployed infrastructure.
FDA oversight of Software as a Medical Device intersects with HIPAA privacy mandates and state-level medical board licensing requirements to create a complex compliance architecture for platform operators. CMS reimbursement policies, particularly the Medicare Physician Fee Schedule and originating site waivers, directly determine provider willingness to adopt virtual modalities. Stakeholders must monitor DEA rulemaking on telehealth prescribing flexibilities and state parity law enforcement as the decisive variables shaping sustainable platform economics.
Market Dynamics
The DEA's evolving Ryan Haight Act enforcement is compressing controlled-substance prescribing workflows and forcing platform operators to rebuild their compliance architectures around in-person examination requirements.
Growth Catalysts
- CMS originating site waivers:Medicare reimbursement flexibility removes facility-based barriers for rural beneficiaries seeking specialty consultations. Federally qualified health centers leverage this to deploy remote patient monitoring at scale.
- Behavioral health parity mandates:State-level enforcement of mental health coverage equivalence drives payer investment in virtual psychiatric intake and ongoing therapy management.
- Rural hospital specialist shortages:Cardiology and neurology gaps in Appalachian and Southwestern counties create immediate demand pull for asynchronous store-and-forward diagnostic platforms.
Market Restraints
- State medical board licensing fragmentation:Interstate practice restrictions force platforms to maintain redundant credentialing systems, elevating administrative overhead.
- HIPAA-compliant infrastructure costs:End-to-end encryption and Business Associate Agreement complexity disproportionately burden smaller regional telehealth vendors.
- Broadband bandwidth thresholds:FCC minimum speed requirements for real-time video exclude households below 25 Mbps, capping addressable market penetration in tribal lands and persistent poverty counties.
Strategic Opportunities
- Medicare Advantage chronic care management:Hierarchical condition category scoring incentives align plan sponsors with remote monitoring for heart failure and diabetes populations.
- AI-powered clinical decision support:Natural language processing integration with electronic health records is compressing documentation burden for primary care telehealth encounters.
- Veterans Affairs community care networks:The VA's Mission Act expansion creates procurement channels for platforms serving former service members in non-VA facility catchment areas.
Industry Challenges
- Cross-state malpractice jurisdiction:Telehealth encounters spanning multiple state lines generate unresolved liability allocation between originating and delivering sites.
- Legacy EHR interoperability:HL7 FHIR implementation gaps force manual data reconciliation between virtual care platforms and hospital core systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Telemedicine Market |
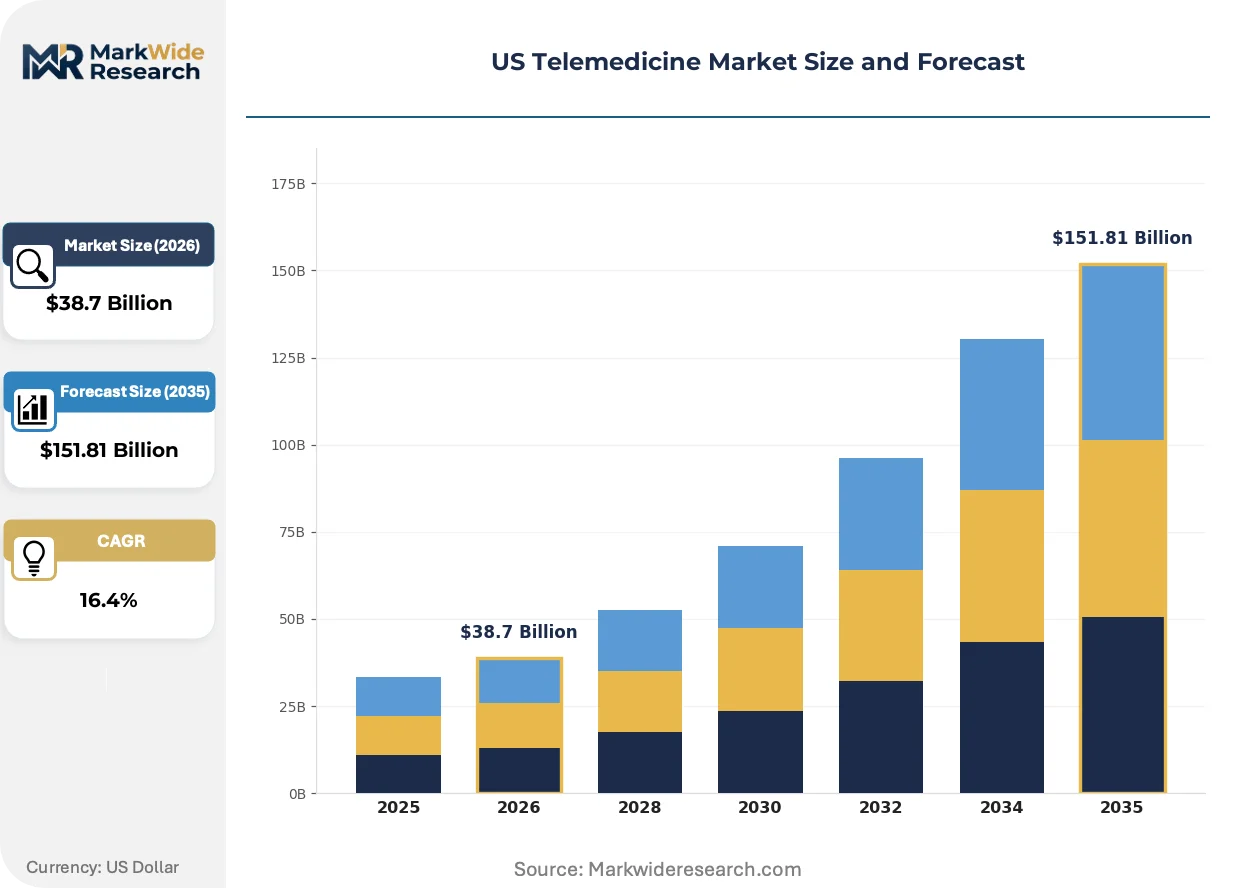
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Consultations, Remote Monitoring, Mobile Health, Asynchronous Messaging Technology: AI-powered Solutions, Cloud-based Platforms, Wearable Devices, Telehealth Software End User: Healthcare Providers, Patients, Insurance Companies, Employers Delivery Mode: Distant Care, In-home Service, Emergency Response, Scheduled Appointments |
| Companies Covered | Teladoc Health, American Well, MDLive (Evernorth), Zoom Video Communications, Doctor On Demand (Included Health), Twilio, Doximity, GE Healthcare, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Telemedicine Market Emerging Trajectories
Platform operators are racing to embed ambient clinical intelligence into consultation workflows while federal rulemaking on prescribing flexibilities remains unresolved. The competitive frontier centers on reducing clinician cognitive load without sacrificing diagnostic fidelity.
Remote patient monitoring devices with cellular-enabled biometric sensors are electrifying chronic disease management outside traditional facility walls. Medicare Advantage plans serving congestive heart failure populations in Florida and Arizona are deploying these tools to reduce thirty-day readmission exposure. The technology is compressing the interval between physiological decompensation and clinical intervention.
DEA special registration pathways for telehealth-controlled substances are reshaping platform compliance investment priorities. The proposed framework requires technology-enabled identity verification and real-time prescription monitoring system integration. Behavioral health platforms serving opioid use disorder populations face the steepest adaptation curve as these rules finalize.
Employer-sponsored virtual primary care is displacing traditional occupational health clinic relationships among self-insured manufacturing and logistics employers. Third-party administrators in Texas and Ohio are bundling these services with chronic condition navigation. The shift is most visible in sectors with distributed workforces lacking on-site medical infrastructure.
US Telemedicine Market Segmentation
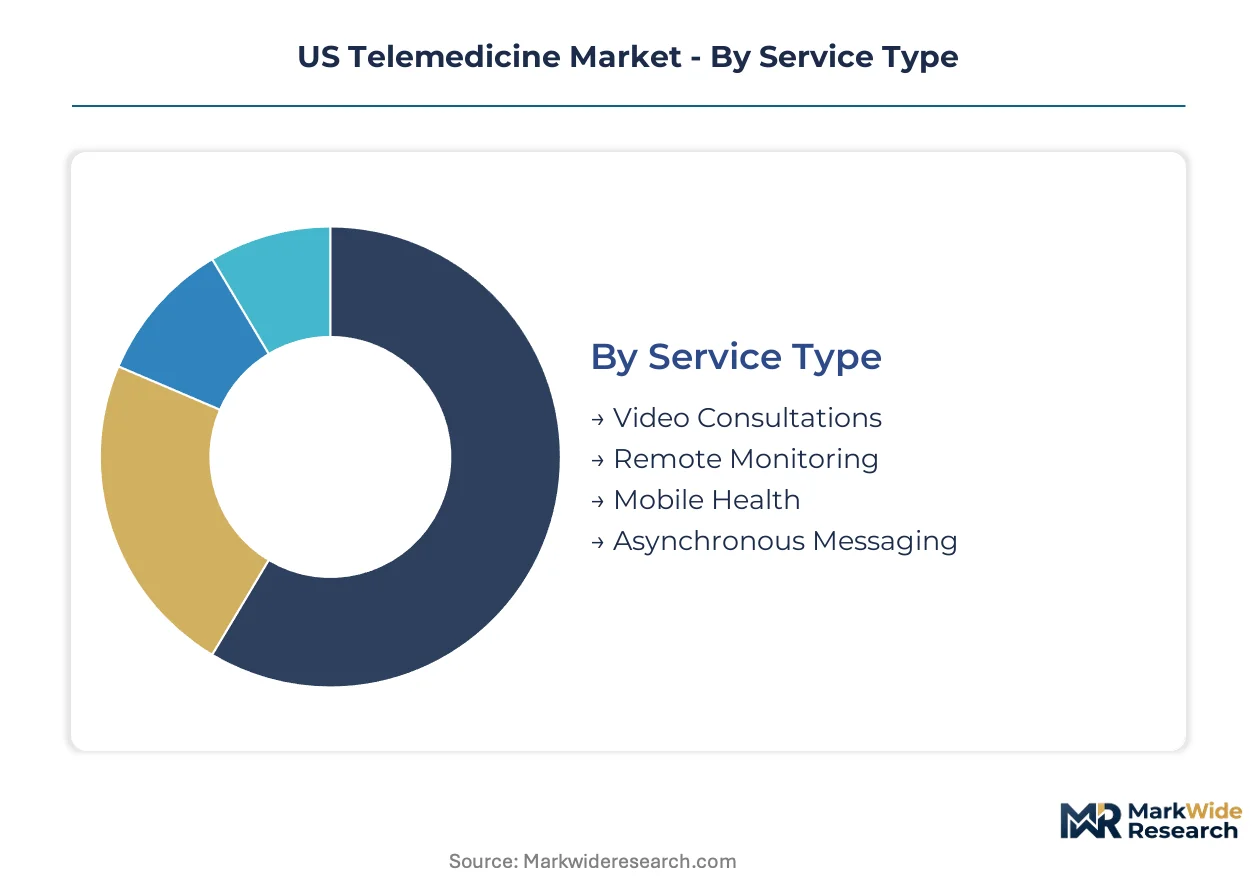
Telemedicine segmentation reveals how reimbursement structures and care delivery models fragment platform investment priorities. Service type and technology choices determine whether vendors capture Medicare Advantage chronic care contracts or employer-sponsored primary care relationships.
Service Type:
Volume concentrates in synchronous encounters, while premium economics favor longitudinal monitoring relationships.
- Video Consultations:Real-time audiovisual encounters requiring minimum 128 kbps bandwidth. Demand clusters in Medicare Advantage specialty access across Florida and Arizona, where CMS originating site waivers remove facility barriers for rural beneficiaries seeking cardiology and neurology consults.
- Remote Monitoring:Cellular-enabled biometric sensors transmitting physiologic data for chronic disease management. Deployment concentrates in congestive heart failure populations served by Medicare Advantage plans seeking thirty-day readmission reduction, with CMS reimbursement broadening under Physician Fee Schedule rules.
- Mobile Health:Smartphone-based symptom checkers and medication adherence tools.
- Asynchronous Messaging:Store-and-forward clinical communication without real-time interaction.
Mature deployment sits with Video Consultations. Newer deployment is concentrated in Remote Monitoring.
Technology:
Cloud infrastructure absorbs capital-light entrants; AI differentiation commands R&D prioritization.
- Cloud-based Platforms:HIPAA-compliant hosted infrastructure with Business Associate Agreement frameworks. Regional health plans in Texas and Ohio leverage white-label deployments for employer-sponsored virtual primary care, displacing traditional occupational health clinic relationships among self-insured manufacturing employers.
- AI-powered Solutions:Natural language processing integrated with electronic health records for clinical decision support. Investment concentrates on ambient clinical intelligence that compresses documentation burden during primary care telehealth encounters without sacrificing diagnostic fidelity.
- Wearable Devices:Consumer-grade and medical-grade biometric sensors with cellular connectivity.
- Telehealth Software:Point solutions for scheduling, billing, and encounter documentation.
Cloud-based Platforms anchor current infrastructure spend. AI-powered Solutions capture the steepest expansion trajectory as vendors race to reduce clinician cognitive load.
End User:
Payer sponsorship determines platform sustainability; direct-to-consumer models face margin compression.
- Healthcare Providers:Hospital systems and physician groups deploying virtual care for specialist shortage mitigation. Rural Appalachian and Southwestern counties drive demand for asynchronous store-and-forward diagnostic platforms addressing cardiology and neurology gaps.
- Insurance Companies:Medicare Advantage sponsors and commercial payers integrating telehealth into benefit design. Hierarchical condition category scoring incentives align plan sponsors with remote monitoring for heart failure and diabetes populations across the Southeast.
- Patients:Direct-pay consumers accessing virtual care outside insurance networks.
- Employers:Self-insured entities bundling virtual primary care with chronic condition navigation.
Healthcare Providers represent entrenched demand. Insurance Companies are gaining share fastest as parity mandates deepen payer investment.
Delivery Mode:
Emergency applications command premium pricing; scheduled encounters compete on network breadth.
- Scheduled Appointments:Pre-arranged virtual visits with established provider relationships. Federally qualified health centers leverage CMS originating site waivers to deploy remote patient monitoring at scale for chronically ill rural beneficiaries.
- Emergency Response:On-demand acute care triage and stabilization guidance. Demand concentrates in Veterans Affairs community care networks serving former service members in non-VA facility catchment areas under Mission Act expansion.
- Distant Care:Cross-state specialist consultation for underserved regions.
- In-home Service:Integration with home health and skilled nursing workflows.
Scheduled Appointments dominate encounter volume. Emergency Response is expanding most quickly as platform operators seek urgent care market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed rural counties concentrate telemedicine infrastructure investment through federal tax incentives. Appalachian and Southwestern hospital systems leverage these designations to deploy virtual specialty networks. CMS reimbursement waivers amplify deployment velocity in federally qualified health center catchment areas.
Southeast
Medicare Advantage chronic care management drives demand concentration across Florida and Georgia. CMS originating site waivers remove facility barriers for rural beneficiaries seeking cardiology consultations. Miami-Dade and Atlanta metropolitan clusters anchor behavioral health platform deployment for dual-eligible populations.
Southwest
Remote patient monitoring expands fastest in Arizona and New Mexico congestive heart failure populations. DEA Ryan Haight Act enforcement compresses controlled-substance prescribing workflows for border-state platforms. Phoenix and Tucson health systems integrate cellular-enabled biometric sensors for thirty-day readmission reduction.
Appalachia
Specialist shortages in cardiology and neurology create immediate demand for asynchronous store-and-forward diagnostics. FCC broadband thresholds exclude households below 25 Mbps, capping penetration in persistent poverty counties. West Virginia and eastern Kentucky hospital systems consolidate virtual access through regional network partnerships.
Texas
Employer-sponsored virtual primary care displaces traditional occupational health relationships among self-insured manufacturing employers. Third-party administrators bundle chronic condition navigation with telehealth access. Dallas-Fort Worth and Houston metropolitan areas anchor white-label platform contracts for regional health plans.
Pacific Northwest
Veterans Affairs community care networks under Mission Act expansion create procurement channels for former service members. Seattle and Portland metropolitan clusters concentrate AI-powered clinical decision support development. HIPAA-compliant cloud infrastructure investment accelerates among regional telehealth vendors serving tribal health organizations.
US Telemedicine Market Vendor Landscape
Top-tier vendors anchor enterprise health plan contracts, while mid-tier specialists compete on vertical integration depth. The vendor base stratifies across three tiers: national physician network operators, white-label infrastructure providers, and point-solution telehealth software vendors. Two strategic archetypes dominate: platform operators bundling multiple service modalities, and infrastructure specialists licensing core technology stacks. M&A activity concentrates on behavioral health integration capabilities, while strategic partnerships target EHR interoperability certification.
Among publicly traded platform operators, Teladoc Health exemplifies the national network archetype through its physician coverage model. American Well occupies a position within the white-label infrastructure tier, serving regional health plan sponsorship requirements. MDLive represents behavioral health integration specialists competing with traditional outpatient frameworks.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| MDLive (Evernorth) |
| Zoom Video Communications |
| Doctor On Demand (Included Health) |
| Twilio |
| Doximity |
| GE Healthcare |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure migration from on-premise data centers to HIPAA-compliant hosted environments is compressing platform operating costs while concentrating vendor relationships among three hyperscale providers. This shift simultaneously reduces capital expenditure barriers for new entrants and elevates switching costs for established operators locked into multi-year Business Associate Agreement frameworks.
Pricing Analysis
Short lead-time deployments command premium pricing as health systems accelerate virtual care rollouts ahead of DEA rulemaking deadlines. The dominant model structures three-tier pricing across enterprise, mid-market, and direct-to-consumer levels, with differentiation driven by EHR integration depth and clinician network breadth. Cost compression in the mid-market tier is intensifying because regional health plans are consolidating vendor relationships around white-label platforms. Direct-to-consumer segments exhibit highest price sensitivity, while Medicare Advantage sponsors demonstrate lowest sensitivity due to HCC scoring incentives.
Supply Chain Analysis
Workforce availability constraints in India and the Philippines are elevating compensation for clinical documentation specialists supporting ambient intelligence development. Hardware supply concentrates in Taiwan, China, and South Korea for cellular-enabled biometric sensors, while software development draws from domestic US talent pools concentrated in Seattle and Boston corridors. Single-source vulnerability sits with FDA-cleared pulse oximetry modules. Distribution runs through GPO contracts with hospital purchasing committees and direct enterprise sales to Medicare Advantage plan sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US telemedicine market functions as a cost-of-compliance story where DEA Ryan Haight Act enforcement creates a barrier-to-entry moat favoring platforms with established controlled-substance prescribing infrastructure.
For Market Incumbents: Acquire behavioral health intake platforms to consolidate position ahead of parity mandate enforcement. Defensive consolidation should prioritize asynchronous diagnostic capabilities addressing rural cardiology and neurology gaps, while channel control investments target EHR interoperability certification to lock out point-solution competitors. For New Entrants and Emerging Players: AI-powered ambient clinical intelligence offers the most penetrable wedge for market entry. White-space targets concentrate on Veterans Affairs community care networks under Mission Act expansion and employer-sponsored virtual primary care among self-insured manufacturing employers in Texas and Ohio. Go-to-market positioning should emphasize documentation burden reduction for primary care clinicians. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by health plans seeking vertical integration into virtual care delivery. Long-term viability favors platforms with demonstrated Medicare Advantage contract renewals and DEA special registration pathway compliance. The signal to watch is CMS originating site waiver permanence as inflection indicator for rural infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| DEA Special Registration Compliance | Controlled-substance prescribing authorization under Ryan Haight Act enforcement creates platform differentiation. |
| EHR Interoperability Certification | HL7 FHIR implementation locks in hospital system relationships and displaces point-solution competitors. |
| Behavioral Health Platform Integration | Mental health parity mandates drive payer investment in virtual psychiatric intake and therapy management. |
| Cellular-Enabled RPM Deployment | Medicare Advantage heart failure populations in Florida and Arizona demand thirty-day readmission reduction tools. |
| Medicare Advantage Contract Expansion | HCC scoring incentives align plan sponsors with remote monitoring for chronic disease populations across the Southeast. |
Methodological Framework
Document review covered FDA 510(k) filings, CMS Medicare Physician Fee Schedule releases, and DEA rulemaking dockets, complemented by interviews with telehealth platform executives, hospital system CMIOs, Medicare Advantage plan medical directors, and GPO contracts managers. Secondary validation drew from SEC 10-K disclosures, hospital procurement databases, and state medical board licensing records. Bottom-up encounter volume estimates triangulated against top-down reimbursement flow analysis.
Model outputs project service-type and technology-segment revenue trajectories across the analysis window, with segmentation by delivery mode, end-user category, and regional regulatory cluster. CAGRs derived from historical Medicare reimbursement trend analysis and payer contract renewal patterns. Forecast inputs incorporated DEA rulemaking timelines, FCC broadband deployment maps, and CMS originating site waiver permanence scenarios.
Several conditions sit outside the modeled scope, including unscheduled DEA rulemaking reversals, state medical board interstate compact withdrawals, and macroeconomic shocks to employer-sponsored insurance coverage. Forecasts reflect documented assumptions about reimbursement stability and regulatory continuity. Material deviation in DEA telehealth prescribing flexibility or CMS waiver permanence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Online Therapy Services Market
Telemedicine
US Virtual Care Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
India Telemedicine Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Telestroke Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telemedicine Service Market