
 North America and Europe Ehealth Market | 2026-2036
North America and Europe Ehealth Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Ehealth Market Intelligence
Subscription-based SaaS financing is tilting competitive dynamics toward asset-light platform vendors that bypass heavy on-premise infrastructure commitments. Epic Systems Corporation leverages deep integration with academic medical centers to sustain long-term contract retention. Cerner Corporation anchors its position through extensive federal health IT deployments across US Veterans Affairs facilities. Teladoc Health competes via employer-sponsored virtual care networks that reduce per-episode costs.
North America and Europe ehealth encompasses digitally delivered healthcare services, remote patient monitoring infrastructure, and interoperable clinical data systems operating across HIPAA, GDPR, and ISO 27001 security parameters, with primary purpose of extending care access while reducing systemic cost burdens. Electronic health records occupy the most mature margin pool as consolidation among US health systems drives replacement cycles, while AI Analytics represents the fastest-expanding technology segment as diagnostic algorithms secure regulatory clearances. Cloud Computing underpins nearly all new platform deployments, though European data sovereignty requirements fragment vendor architectures.
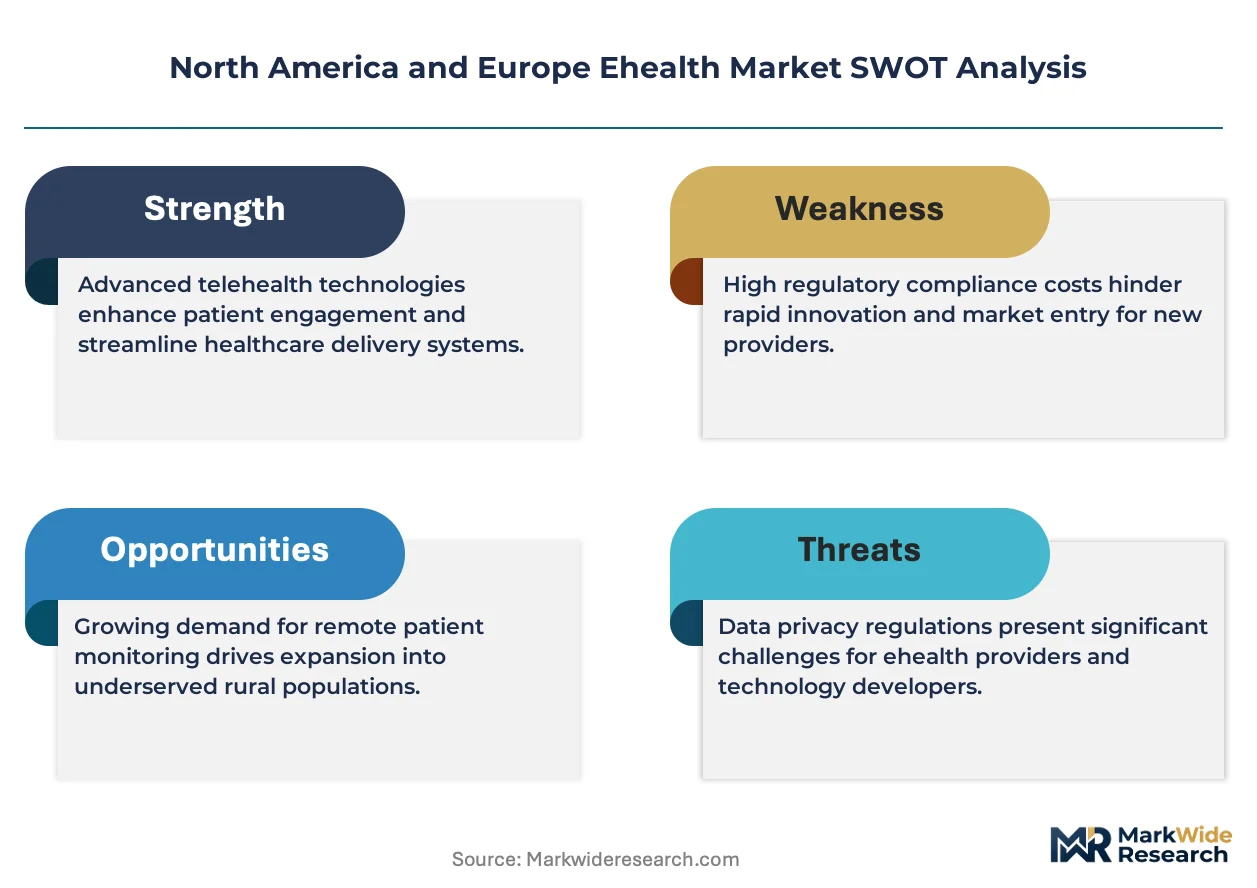
FDA software-as-medical-device guidance and EU AI Act risk-classification tiers are forcing vendors to restructure quality management systems before market entry. HIPAA in the US and GDPR across Europe impose divergent consent architectures that complicate cross-border data flows for multinational platforms. Stakeholders must monitor how FDA and EMA alignment on real-world evidence standards reshapes post-market surveillance obligations for algorithm-driven diagnostics.
Market Dynamics
Subscription-based SaaS financing is collapsing traditional infrastructure-heavy business models across North America and Europe, forcing vendors to abandon capital-intensive on-premise deployments in favor of asset-light platform architectures that scale through recurring revenue streams rather than perpetual license sales.
Growth Catalysts
- FDA software-as-medical-device pathways:Streamlined approval frameworks accelerate time-to-market for algorithm-driven diagnostics, reducing regulatory friction for AI-powered clinical tools seeking US commercialization.
- Rural hospital networks:Telemedicine adoption among underserved communities extends care access while generating volume for remote monitoring infrastructure vendors.
- EU AI Act risk-classification tiers:Clear regulatory boundaries enable vendors to structure quality management systems with predictable compliance costs before European market entry.
Market Restraints
- Cloud infrastructure concentration:European data sovereignty requirements fragment vendor architectures, forcing redundant regional deployments that inflate operational overhead.
- HIPAA-GDPR divergence:Incompatible consent architectures complicate cross-border data flows for multinational platforms operating across US and European jurisdictions.
- Legacy EHR replacement cycles:Consolidation among US health systems concentrates purchasing power among fewer buyers, extending sales cycles and pressuring vendor margins.
Strategic Opportunities
- German federal health IT infrastructure:Demand concentration in Europe's largest healthcare market creates anchor contracts for vendors establishing EU operational footholds.
- Real-world evidence standards alignment:FDA-EMA convergence on post-market surveillance obligations opens pathways for algorithm-driven diagnostics to leverage cross-Atlantic clinical data.
- AI Analytics-Cloud Computing convergence:Diagnostic algorithms paired with scalable compute infrastructure enable diagnostic-as-a-service models that bypass traditional capital equipment sales.
Industry Challenges
- Interoperability engineering talent:Scarcity of specialists capable of bridging HL7 FHIR, GDPR, and HIPAA compliance requirements simultaneously constrains platform development velocity.
- ISO 27001 certification timelines:Extended security audit cycles delay commercial launches for vendors targeting enterprise health system procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Ehealth Market |
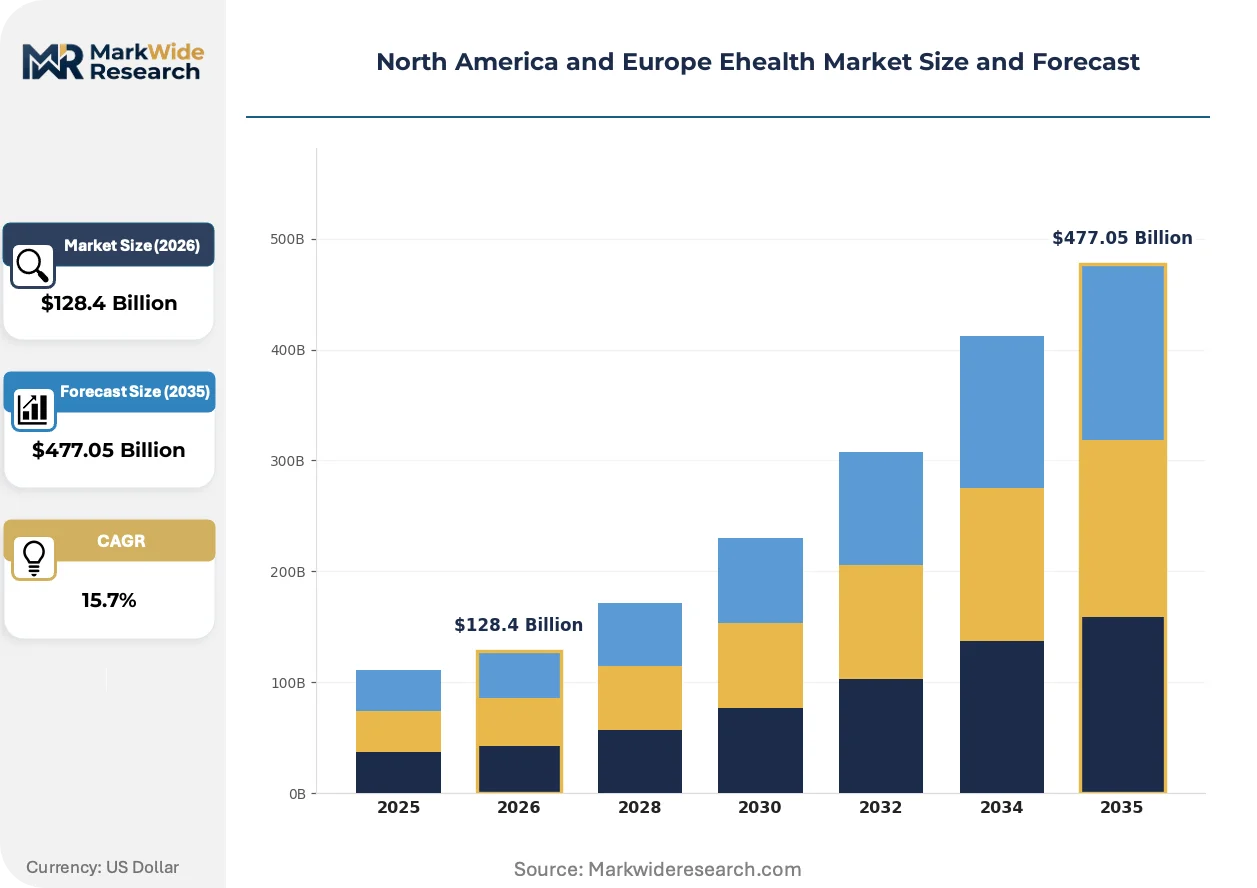
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $477.05 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine, Remote Monitoring, Electronic Health Records, mHealth Technology: Cloud Computing, AI Analytics, Blockchain, IoT Devices End User: Patients, Healthcare Providers, Insurers, Payers Service Type: Consulting, Software Development, Implementation, Maintenance |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare, Teladoc Health, Koninklijke Philips, Siemens Healthineers, GE Healthcare, Medtronic, Oracle Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Ehealth Market Strategic Shifts & Innovations
Platform economics are restructuring how clinical value is captured and delivered, with three distinct forces compressing traditional service models and creating new competitive terrain for digitally native health infrastructure vendors.
Generative AI clinical documentation tools are collapsing the administrative burden that has consumed 25-30% of physician time, enabling health systems in the US Northeast corridor to redeploy clinical labor toward direct patient interaction. Academic medical centers are piloting ambient listening technologies that auto-populate EHR fields, compressing documentation time from hours to minutes and reshaping workforce deployment models.
The EU AI Act's risk-based classification framework is forcing vendors to restructure quality management systems before European market entry, with high-risk diagnostic algorithms now requiring conformity assessments that parallel medical device pathways. German and French regulators are implementing the earliest enforcement protocols, creating a phased compliance landscape where early movers capture institutional reference contracts.
Employer-sponsored virtual care networks are displacing traditional payer-channel distribution for routine episodic care, with self-insured corporations in the US and UK directly contracting platform vendors to reduce per-episode costs. This bypasses traditional health system gatekeepers and concentrates purchasing authority among benefits administrators rather than clinical procurement officers.
North America and Europe Ehealth Market Segmentation
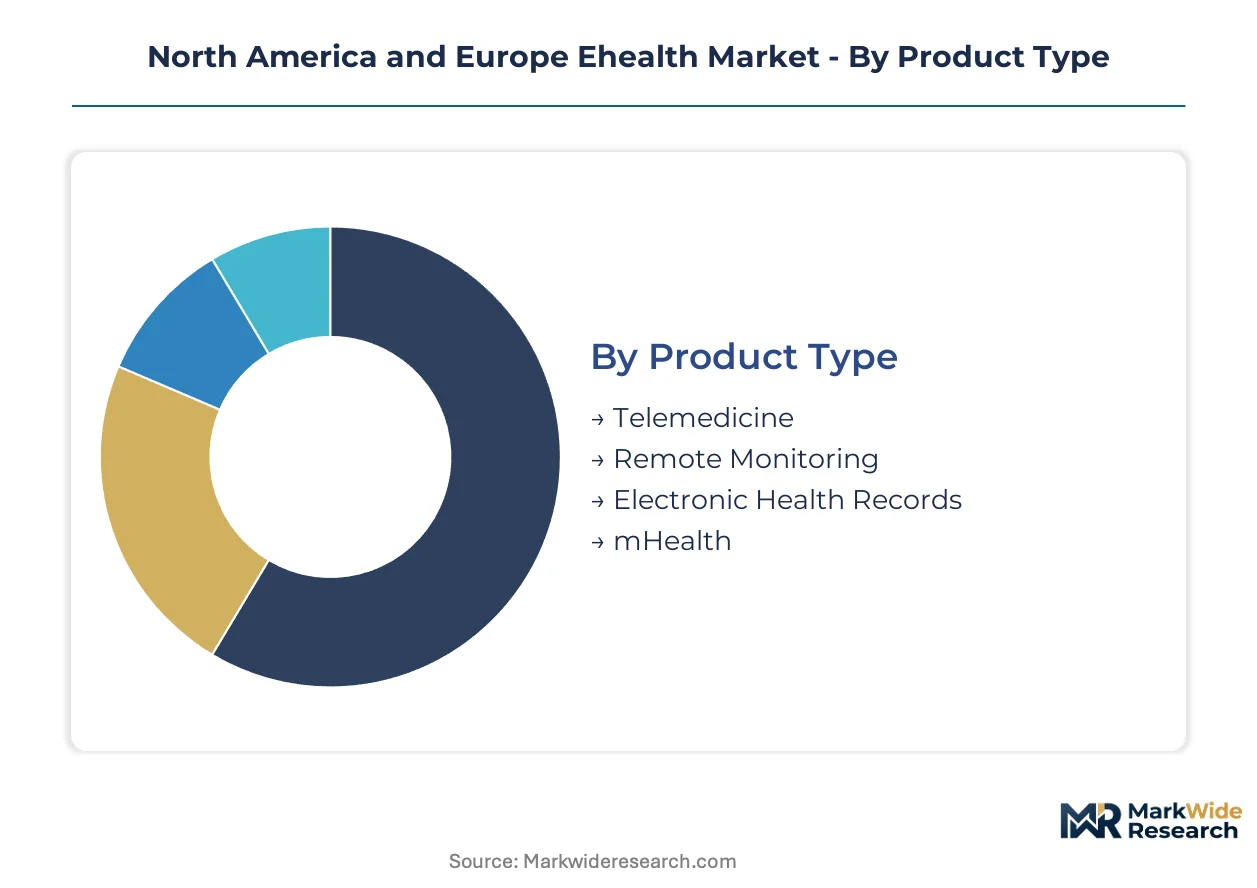
Segmentation across the North America and Europe Ehealth Market reveals how technology maturity, regulatory complexity, and buyer concentration reshape vendor strategies. Understanding these divisions exposes where infrastructure investments concentrate and which service models capture recurring revenue.
Product Type:
Mature platforms dominate procurement budgets while emerging modalities reshape care delivery economics.
- Electronic Health Records:Consolidated data repositories with HL7 FHIR interoperability protocols anchor health system IT architecture. US health system consolidation in the Northeast corridor and German hospital networks drive replacement cycles toward cloud-native deployments.
- Telemedicine:Synchronous virtual consultation platforms with embedded payment processing extend care access beyond physical infrastructure. Rural hospital networks across the US Midwest and Scottish Highlands generate volume for vendors with lightweight deployment models.
- Remote Monitoring:Continuous biometric data capture through connected peripherals enables chronic disease management outside acute settings.
- mHealth:Consumer-facing applications with limited clinical integration capture wellness engagement but face reimbursement uncertainty.
Electronic Health Records handles the majority of throughput; Telemedicine is expanding most quickly on share.
Technology:
Cost tier stratification separates enterprise-grade infrastructure from experimental deployments.
- Cloud Computing:Scalable compute and storage infrastructure with ISO 27001 certification underpins nearly all new platform deployments. European data sovereignty requirements fragment architectures between AWS, Azure, and regional providers like OVHcloud.
- AI Analytics:Diagnostic algorithms with FDA 510(k) or EU AI Act high-risk classification enable clinical decision support. Academic medical centers in Boston and Munich pilot ambient documentation tools that compress physician administrative burden.
- IoT Devices:Connected sensors and wearables with edge computing capabilities transmit patient data to centralized monitoring dashboards.
- Blockchain:Distributed ledger applications for credentialing and supply chain tracking remain confined to pilot programs with unproven ROI.
Cloud Computing absorbs the largest infrastructure spend; AI Analytics is climbing the fastest on commercial traction.
End User:
Customer type determines procurement authority and contract structure complexity.
- Healthcare Providers:Hospital systems and physician practices with Epic or Cerner deployments constitute the primary decision-makers for clinical workflow tools. Federal health IT mandates through US Veterans Affairs and NHS England frameworks standardize vendor selection criteria.
- Payers:Insurance carriers and self-insured employers with direct contracting authority seek per-episode cost reduction through virtual care networks. Large US corporations and UK benefits administrators displace traditional health system gatekeepers for routine care.
- Patients:Individual consumers with high-deductible plans drive direct-to-consumer mHealth adoption but limited enterprise value.
- Insurers:Traditional indemnity carriers with legacy claims systems lag in digital infrastructure investment.
Healthcare Providers command the longest contract durations; Payers are gaining procurement influence fastest.
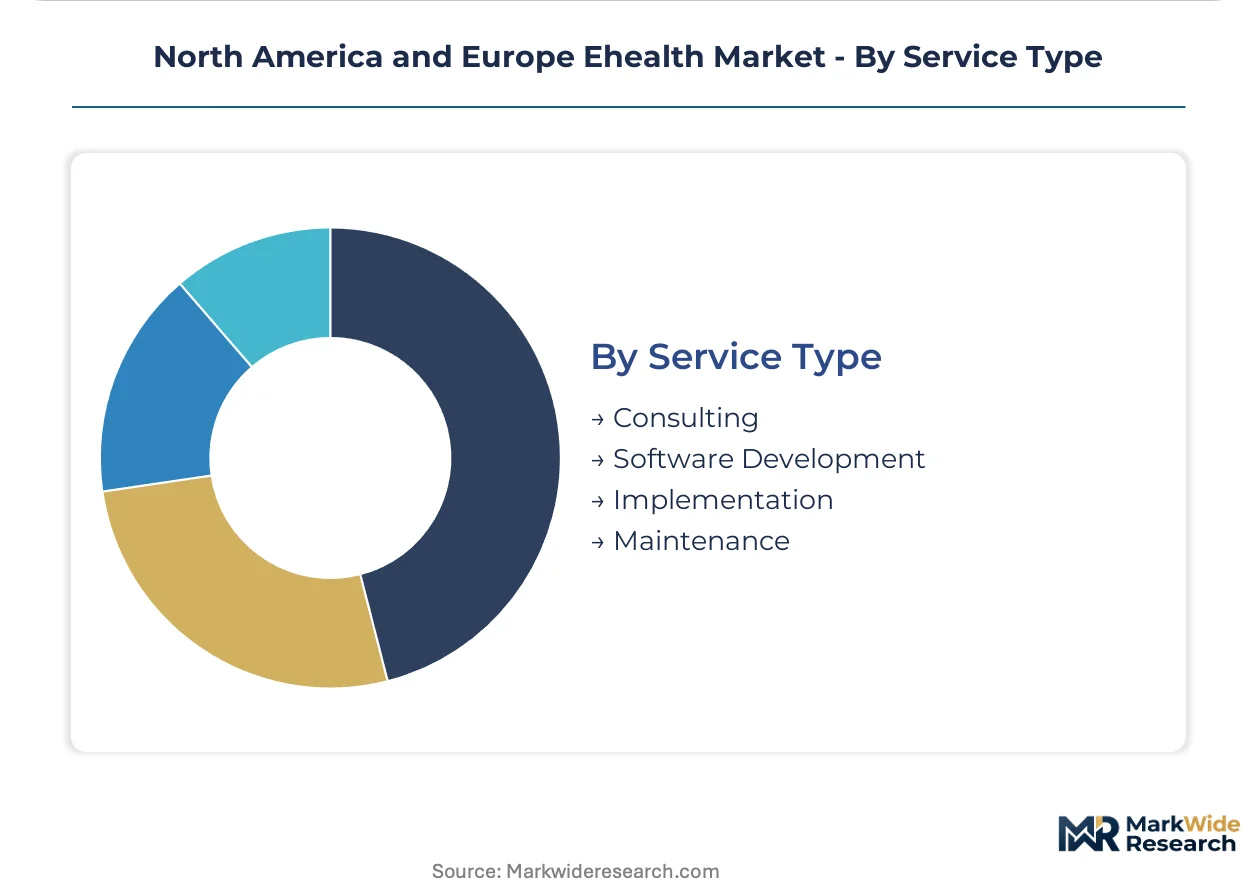
Service Type:
Margin concentration follows the transition from one-time implementation to recurring operational support.
- Software Development:Custom application engineering with HIPAA and GDPR compliance integration addresses health system-specific workflow requirements. German federal health IT infrastructure projects and US academic medical center Epic extensions sustain specialist vendor demand.
- Maintenance:Ongoing security patching, uptime guarantees, and regulatory update management generate predictable subscription revenue. ISO 27001 recertification cycles and FDA software-as-medical-device post-market surveillance obligations lock vendors into long-term relationships.
- Implementation:System integration and data migration services capture project-based fees with limited recurrence.
- Consulting:Strategic advisory on regulatory compliance and interoperability planning faces margin pressure from in-house health system teams.
Maintenance locks in the highest lifetime value; Software Development captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal health IT infrastructure investments and EU AI Act compliance deadlines are redistributing procurement authority across North America and Europe, concentrating vendor attention on jurisdictions with the clearest regulatory pathways and largest hospital system consolidation opportunities.
United States
Academic medical centers in the Northeast corridor drive replacement cycles toward cloud-native EHR platforms with embedded AI documentation tools. FDA software-as-medical-device pathways accelerate commercialization timelines for diagnostic algorithms seeking 510(k) clearance. Boston and New York Metro health systems pilot ambient listening technologies that auto-populate clinical records.
Germany
Federal health IT infrastructure projects anchor European demand for interoperable clinical data systems with HL7 FHIR compliance. EU AI Act high-risk classification requirements force vendors to restructure quality management systems before market entry. Munich and Berlin hospital networks implement the earliest conformity assessment protocols for algorithm-driven diagnostics.
United Kingdom
NHS England frameworks standardize vendor selection criteria for digital health procurement across integrated care systems. GDPR consent architectures complicate cross-border data flows for multinational platforms operating US-European footprints. London and Greater Manchester concentrate pilot deployments of employer-sponsored virtual care networks.
France
ANSM and CNIL implement phased enforcement of EU AI Act protocols for clinical decision support tools. French hospital networks prioritize ISO 27001-certified cloud infrastructure to satisfy data sovereignty requirements. Paris and Lyon academic centers anchor reference contracts for vendors establishing EU operational footholds.
Canada
Health Canada aligns software-as-medical-device guidance with FDA pathways to streamline cross-border commercialization for diagnostic algorithms. Provincial health authorities in Ontario and Quebec consolidate purchasing power for enterprise EHR replacements. Toronto-Waterloo corridor clusters health IT engineering talent for interoperability protocol development.
North America and Europe Ehealth Market Key Industry Players
On the supply side, the industry is consolidating around platform vendors with deep health system integration and recurring revenue models that displace perpetual license sales. Three strategic archetypes dominate: academic medical center-anchored EHR specialists, federal deployment-focused infrastructure vendors, and employer-sponsored virtual care networks. Competitive moves concentrate on strategic partnerships with cloud infrastructure providers and portfolio diversification into AI-powered clinical documentation.
Within the academic medical center tier, Epic Systems Corporation exemplifies deep integration strategies that sustain long-term contract retention. Among federal deployment specialists, Cerner Corporation anchors positions through extensive US Veterans Affairs health IT infrastructure. Teladoc Health occupies a position within employer-sponsored virtual care networks that bypass traditional health system gatekeepers for routine episodic care.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare |
| Teladoc Health |
| Koninklijke Philips |
| Siemens Healthineers |
| GE Healthcare |
| Medtronic |
| Oracle Health |
| Others |
Cost & Logistics Intelligence
Boston's academic medical center cluster concentrates purchasing power for enterprise EHR platforms, translating cloud infrastructure scale into downstream pricing leverage for vendors serving US Northeast health systems. German hospital networks in Munich and Berlin anchor European procurement volumes, creating regional price benchmarks that ripple through EU vendor contract negotiations.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001 and FDA 510(k) clearance commanding premium subscription rates over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by interoperability depth and AI module inclusion. Pricing pressure stems from health system consolidation in the US Northeast corridor, where fewer buyers extract volume discounts. Self-insured employers show least price sensitivity for virtual care networks, while rural hospital networks face acute budget constraints.
Supply Chain Analysis
Tariff exposure between US and China dominates hardware component sourcing for connected monitoring devices and IoT peripherals. Cloud infrastructure concentrates in Ireland, Germany, and US Virginia data center clusters, with European data sovereignty requirements fragmenting vendor architectures. Raw material dependencies span semiconductor chips, lithium-ion batteries for wearables, and medical-grade polymers for device housings. Single-source vulnerability runs through Taiwan-based chip fabrication for edge computing modules. Distribution runs through health system GPO contracts and direct employer benefits administrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions and buyer archetypes creates niche entry points for specialized vendors. EU AI Act implementation timelines and divergent HIPAA-GDPR compliance requirements splinter demand into addressable segments.
For Market Incumbents: Build switching cost moats through deep Epic and Cerner workflow integration that embeds AI documentation tools into clinical routines. Federal health IT deployment expertise anchors US Veterans Affairs and NHS England contract renewals. Cloud infrastructure partnerships with AWS and Azure defend against regional sovereign cloud challengers. ISO 27001 recertification investments lock out uncertified competitors from enterprise procurement frameworks.
For New Entrants and Emerging Players: Pursue ambient clinical documentation pilots at academic medical centers in Boston and Munich where administrative burden reduction justifies premium pricing. Rural hospital networks in US Midwest and Scottish Highlands present underpenetrated telemedicine demand with lighter competitive density. Direct-to-employer virtual care contracts bypass health system procurement gatekeepers and concentrate purchasing authority among benefits administrators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-native documentation specialists with FDA software-as-medical-device clearances and EU AI Act conformity assessments underway. Long-term viability hinges on recurring revenue models that displace perpetual license sales. Acquisition targets should demonstrate health system reference contracts and interoperability engineering capabilities. Watch FDA-EMA alignment on real-world evidence standards as inflection signal for algorithm-driven diagnostic commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | High-risk diagnostic algorithms gain market access across German and French hospital networks. |
| FDA Software-as-Medical-Device Submission | Streamlined 510(k) pathways accelerate US commercialization for clinical decision support tools. |
| Academic Medical Center Partnership | Boston and Munich reference contracts validate ambient documentation technology for broader adoption. |
| Employer-Sponsored Virtual Care Network | Direct contracts with US and UK benefits administrators bypass traditional health system gatekeepers. |
| Cloud Infrastructure Sovereignty Compliance | OVHcloud and regional provider partnerships satisfy GDPR data residency requirements for EU deployments. |
Research Approach
Desk research of FDA 510(k) filings, EU AI Act implementation guidance, hospital procurement databases, and GPO contract repositories preceded structured interviews with health system CIOs, biomedical engineers, regulatory affairs leads, and benefits administrators. Primary fieldwork captured deployment timelines and vendor selection criteria across US Northeast corridor and German federal health IT projects. Secondary validation drew from CMS Medicare reimbursement data, NHS England framework documents, and hyperscaler healthcare cloud capex disclosures. Bottom-up health system spending estimates triangulated against top-down market sizing from subscription revenue disclosures.
Assumptions held regulatory pathway timelines and health system consolidation rates within observed patterns across the analysis window. Segmentation modeling covered product type, technology tier, end-user archetype, and service model dimensions. CAGRs derived from recurring revenue growth trajectories and replacement cycle frequencies. Forecast inputs included FDA software-as-medical-device approval velocity and EU AI Act enforcement phase timing.
The forecast holds incumbent behavior within observed patterns; aggressive cloud infrastructure pricing moves by AWS, Azure, or sovereign European providers would shift vendor margin outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Video Telemedicine Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Remote Healthcare Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Telehealth Software Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
US Virtual Care Market
Telemedicine
US Telemedicine Market
Telemedicine
Tele-Care Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Global Telehealth Market