
 China Digital Radiology Market | 2026-2036
China Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Radiology Market Insights
GB 9706.1 medical electrical equipment certification is unwinding market access for imported and domestic manufacturers alike. United Imaging Healthcare leverages its captive flat-panel detector production to control cost structures across CT and digital X-ray lines. Siemens Healthineers anchors its position through R&D partnerships with Shanghai-based clinical research hospitals. Mindray Medical competes on ultrasound portability and tier-two hospital penetration where service networks matter most.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic images using electronic detectors with spatial resolution typically exceeding 2.5 line pairs per millimeter, replacing analog film-screen combinations in clinical workflows. CT scanner demand leads product type revenue pools given stroke and trauma protocol volumes, while flat panel detector technology displaces computed radiography in hospital upgrade cycles due to faster throughput and lower dose profiles. Oncology application growth tracks China's expanding cancer center network, and diagnostic centers represent the fastest-growing end user channel as regional imaging alliances consolidate procurement.
NMPA device registration timelines and GB standards compliance shape product development cycles for domestic and multinational suppliers, while provincial health commission tender rules determine regional market access terms. SAMR pricing oversight and centralized procurement pilots compress margins on standardized digital X-ray systems. Stakeholders must monitor which imaging modalities provincial bulk purchasing programs absorb next and whether domestic detector supply chains achieve cost parity with imported alternatives.
Market Dynamics
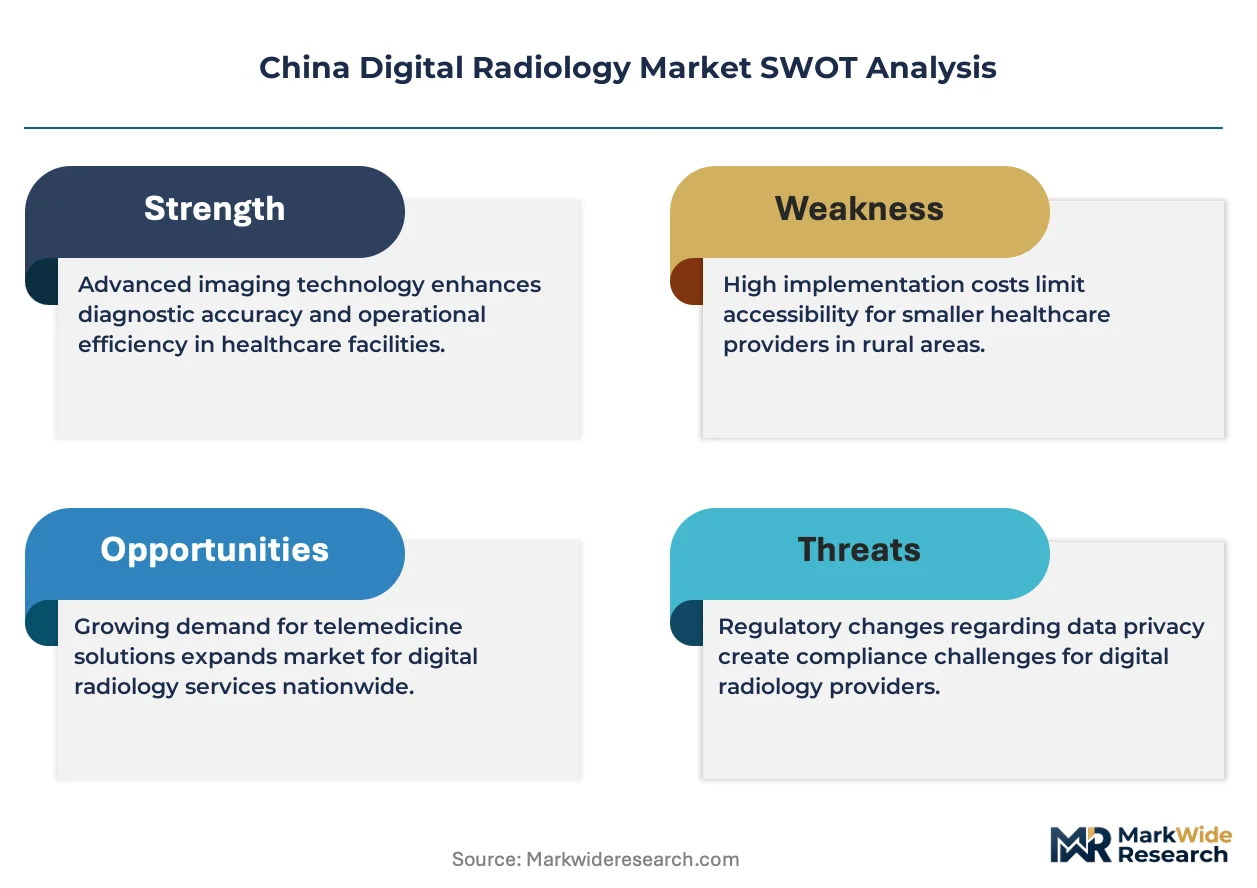
Centralized procurement pilots under SAMR are compressing margins on standardized digital X-ray systems while forcing manufacturers to restructure pricing and service bundling strategies across provincial health commission tenders.
Growth Catalysts
- GB 9706.1 certification streamlining:NMPA accelerated device registration timelines reduce product development cycles for domestic and imported manufacturers seeking hospital procurement eligibility.
- Oncology center expansion:China's growing cancer center network drives demand for high-resolution CT and digital radiology suites with advanced tumor imaging protocols.
- East China infrastructure modernization:Jiangsu and Zhejiang provincial health commissions prioritize imaging infrastructure upgrades, concentrating procurement volume in these coastal provinces.
Market Restraints
- Flat-panel detector supply concentration:Domestic detector supply chains have not yet achieved cost parity with imported alternatives, constraining margin flexibility for system integrators.
- SAMR pricing oversight:Centralized procurement pilots impose rigid price ceilings on standardized digital X-ray equipment, limiting premium positioning opportunities.
- Computed radiography substitution lag:Budget-constrained county hospitals delay upgrade cycles from computed radiography to flat-panel detector systems, extending replacement timelines.
Strategic Opportunities
- Tier-two hospital penetration:Service network density becomes a decisive competitive factor in tier-two and county hospital segments where maintenance response times determine vendor selection.
- Diagnostic center channel expansion:Regional imaging alliances consolidate procurement through independent diagnostic centers, creating volume aggregation opportunities outside traditional hospital sales channels.
- Dual carbon goals alignment:Lower-dose flat-panel detector protocols align with MEE energy efficiency mandates, positioning equipment upgrades as sustainability compliance investments.
Industry Challenges
- GB standards compliance complexity:Manufacturers must navigate evolving GB 9706.1 medical electrical equipment requirements alongside NMPA registration processes, extending time-to-market for new product introductions.
- Legacy system integration friction:Hospital IT departments face interoperability challenges when connecting new digital radiology suites to existing PACS infrastructure and hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Radiology Market |
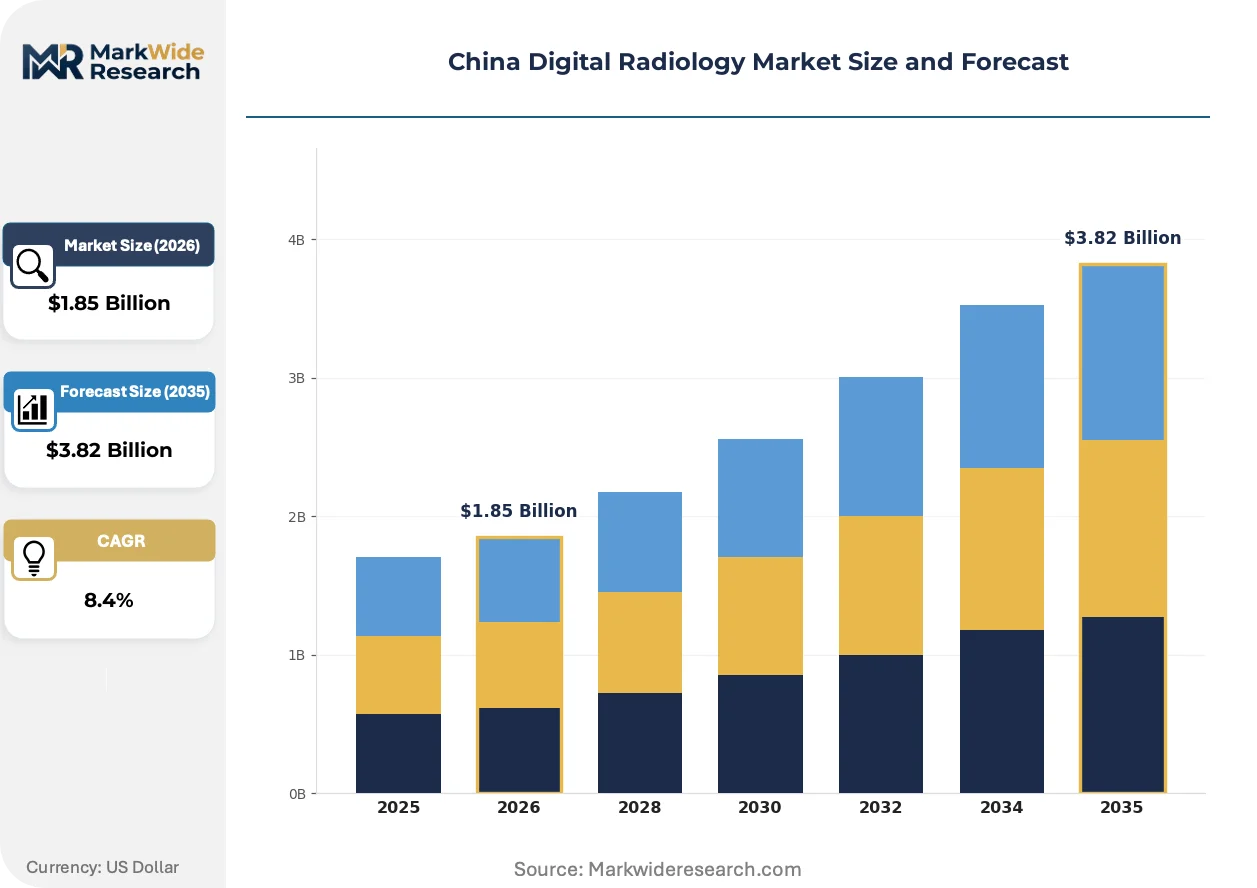
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, CT Scanner, MRI Scanner, Ultrasound Application: Oncology, Orthopedics, Cardiology, Neurology End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Institutes Technology: Flat Panel Detectors, Computed Radiography, Digital Sensors, Imaging Software |
| Companies Covered | United Imaging Healthcare, Mindray Medical, Orich Medical Equipment, Neusoft Medical, Wandong Medical, Jiahong, Siemens Healthineers, GE Healthcare, FUJIFILM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Radiology Market Trends and Innovations
Artificial intelligence integration and detector technology evolution are restructuring competitive differentiation while procurement centralization alters vendor-customer relationships across China's hospital tiers.
Flat-panel detector technology is fragmenting the installed base between premium direct-conversion systems and cost-optimized indirect-conversion alternatives. Tertiary hospitals in Beijing and Shanghai prioritize direct-conversion detectors for high-throughput stroke and trauma protocols. This technical stratification is fragmenting vendor portfolios into distinct performance tiers with diverging service and pricing models.
NMPA regulatory streamlining under harmonized GB standards is compressing approval timelines for both domestic and imported device registrations. Manufacturers now face synchronized compliance requirements across electrical safety and electromagnetic compatibility benchmarks. Domestic suppliers leverage proximity to certification bodies to accelerate iterative design approvals relative to multinational competitors.
Regional imaging alliances are consolidating procurement decisions through centralized tender platforms administered by provincial health commissions. Independent diagnostic centers and multi-hospital groups now negotiate volume contracts that displace traditional single-site purchasing. This aggregation is most visible in Jiangsu and Zhejiang, where provincial bulk purchasing programs absorb standardized digital X-ray systems before expanding to higher-end modalities.
China Digital Radiology Market Segmentation
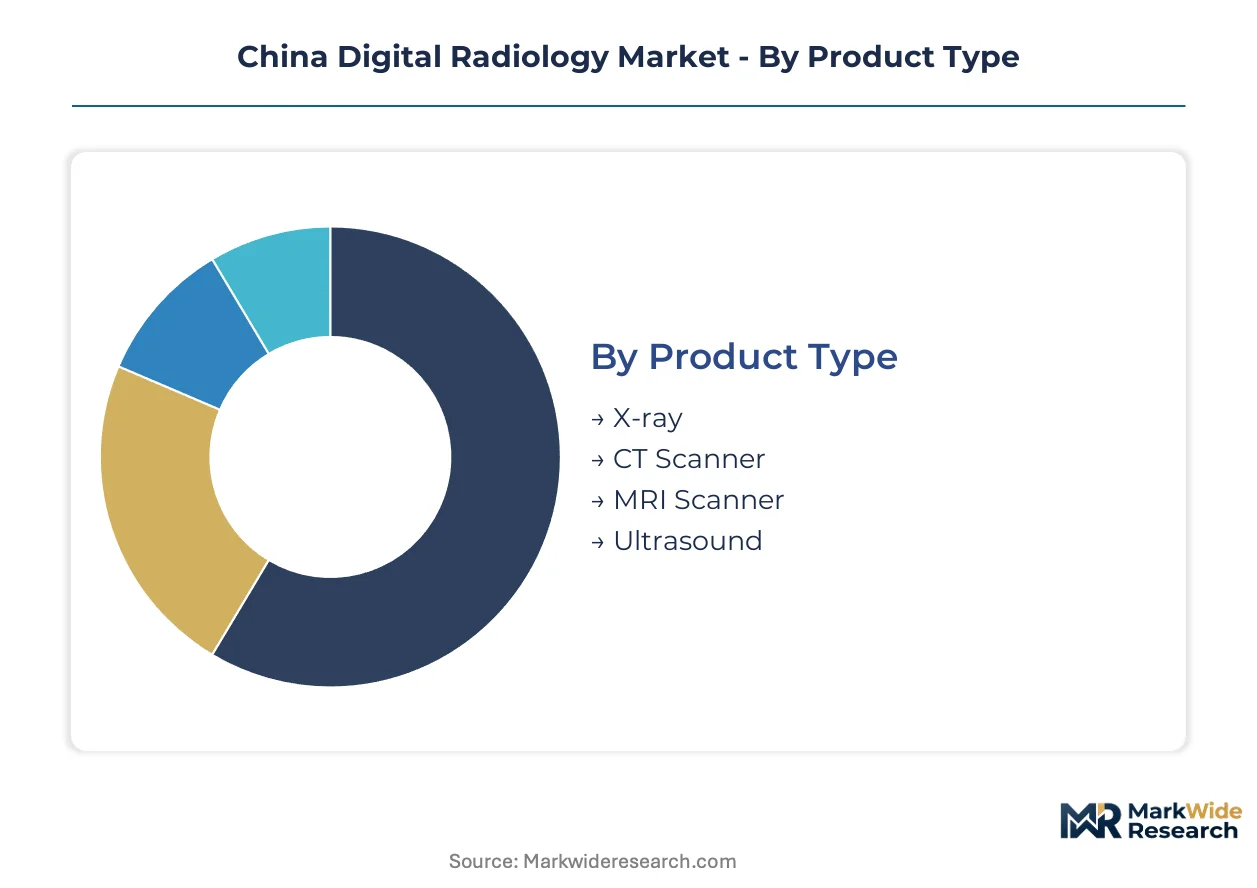
Segmentation in China's digital radiology market reveals how procurement centralization and technology substitution reshape competitive positioning across product tiers and customer channels. NMPA regulatory harmonization and provincial bulk purchasing programs create divergent growth trajectories depending on segment alignment with GB standards compliance and cost structures.
Product Type:
Computed radiography substitution pressure varies sharply across modalities, with flat-panel detector economics forcing accelerated upgrade cycles in some categories while legacy systems persist in others.
- CT Scanner:Multi-slice systems with detector arrays exceeding 64 rows dominate stroke and trauma protocol volumes in Beijing and Shanghai tertiary hospitals. Jiangsu and Zhejiang provincial health commissions concentrate procurement of premium CT suites through centralized tender platforms, compressing margins on standardized configurations while preserving premium pricing for spectral and dual-source variants.
- X-ray:Digital radiography systems with direct-conversion flat-panel detectors achieve spatial resolution above 3.5 line pairs per millimeter, displacing computed radiography in county hospital upgrade cycles. SAMR pricing oversight imposes rigid ceilings on standardized digital X-ray equipment, limiting premium positioning opportunities for imported systems.
- MRI Scanner:High-field systems at 1.5T and 3.0T field strengths serve oncology and neurology applications with superior soft-tissue contrast resolution.
- Ultrasound:Portable systems with phased-array transducers penetrate tier-two hospitals and outpatient clinics where service network density determines vendor selection.
CT Scanner anchors the volume base while X-ray gains share at the steepest rate.
Application:
Cost tier differentiation separates high-margin specialized protocols from commoditized screening applications across China's hospital tiers.
- Oncology:High-resolution CT and MRI protocols with contrast-enhanced staging sequences track China's expanding cancer center network. Provincial bulk purchasing programs in East China prioritize oncology imaging infrastructure, aggregating demand through regional diagnostic alliances.
- Orthopedics:Digital radiography with weight-bearing capability and metal artifact reduction serves trauma and joint replacement volumes. County hospitals delay computed radiography substitution due to budget constraints, extending replacement timelines for orthopedic imaging suites.
- Cardiology:ECG-gated CT angiography and echocardiography systems address coronary artery disease screening volumes.
- Neurology:Diffusion-weighted MRI and CT perfusion protocols support acute stroke intervention workflows.
Oncology commands premium pricing tiers while Orthopedics expands most quickly through county hospital penetration.
End User:
Customer type concentration shifts procurement authority from individual hospitals toward consolidated purchasing entities.
- Diagnostic Centers:Independent imaging facilities with multi-modality configurations aggregate procurement through regional alliances in Jiangsu and Zhejiang. Provincial health commission tender platforms absorb standardized digital X-ray systems before expanding to higher-end modalities, creating volume aggregation outside traditional hospital channels.
- Hospitals:Tertiary institutions in Beijing and Shanghai anchor demand for premium direct-conversion detector systems with advanced tumor imaging protocols. GB 9706.1 certification requirements and NMPA registration timelines shape vendor eligibility for hospital procurement.
- Outpatient Clinics:Limited-service facilities prioritize portable ultrasound and basic digital radiography with rapid turnaround requirements.
- Research Institutes:Academic medical centers with clinical research hospital status drive pre-commercial technology validation.
Hospitals retain the largest installed base while Diagnostic Centers climb the fastest through regional consolidation.
Technology:
Supply concentration in detector manufacturing constrains margin flexibility for system integrators across conversion technologies.
- Flat Panel Detectors:Direct-conversion amorphous selenium and indirect-conversion cesium iodide variants fragment between premium and cost-optimized tiers. United Imaging Healthcare leverages captive flat-panel detector production to control cost structures, while domestic supply chains have not yet achieved cost parity with imported alternatives.
- Computed Radiography:Photostimulable phosphor plate systems persist in budget-constrained county hospitals despite slower throughput and higher dose profiles. MEE energy efficiency mandates position flat-panel detector upgrades as sustainability compliance investments, accelerating substitution pressure.
- Digital Sensors:CMOS and CCD intraoral sensors serve dental and small-field applications with compact form factors.
- Imaging Software:AI-integrated reconstruction and PACS connectivity modules address interoperability challenges with legacy hospital information systems.
Flat Panel Detectors dominate new system revenue while Imaging Software shows the steepest expansion trajectory through AI integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial health commissions in East China concentrate procurement authority through centralized tender platforms. Beijing and Shanghai tertiary hospitals anchor premium-tier demand for advanced imaging protocols.
Beijing-Tianjin-Hebei
Tertiary hospitals in Beijing drive demand for spectral CT and direct-conversion flat-panel detector systems. NMPA registration streamlining under harmonized GB 9706.1 standards accelerates device approvals for both domestic and imported manufacturers. The Beijing clinical research hospital cluster validates pre-commercial imaging technologies before national deployment.
Yangtze River Delta
Jiangsu and Zhejiang provincial health commissions aggregate procurement through regional diagnostic alliances and bulk purchasing programs. SAMR centralized procurement pilots impose price ceilings on standardized digital X-ray equipment across these coastal provinces. Shanghai anchors the premium-tier segment while Suzhou and Hangzhou concentrate manufacturing supply chains for detector components.
Pearl River Delta
Guangdong province prioritizes imaging infrastructure modernization through provincial health commission tenders focused on county hospital upgrades. MEE dual carbon goals align with flat-panel detector adoption as energy efficiency compliance investments. Shenzhen and Guangzhou cluster independent diagnostic centers that consolidate procurement outside traditional hospital channels.
Sichuan-Chongqing
Western China expansion programs channel infrastructure investment toward tier-two hospital imaging suites in Chengdu and Chongqing. Budget constraints delay computed radiography substitution in county hospitals, extending replacement timelines. Provincial health commissions here pilot service-network-dependent vendor selection criteria where maintenance response times determine contract awards.
China Digital Radiology Market Competitive Landscape
Player mix skews toward vertically integrated domestic specialists competing against multinational system integrators with R&D partnerships. Market structure tiers into three clusters: captive-detector manufacturers controlling cost structures, premium-tier multinationals leveraging clinical research collaborations, and service-network-focused competitors penetrating county hospital segments. Consolidation pressure intensifies as provincial bulk purchasing programs aggregate procurement authority and compress margins on standardized configurations.
Among domestic specialists, United Imaging Healthcare leverages captive flat-panel detector production to control cost structures across CT and digital X-ray lines. Siemens Healthineers anchors multinational positioning through R&D partnerships with Shanghai-based clinical research hospitals. Mindray Medical occupies the tier-two penetration archetype where service network density determines vendor selection in county hospital segments.
| Leading Market Players |
|---|
| United Imaging Healthcare |
| Mindray Medical |
| Orich Medical Equipment |
| Neusoft Medical |
| Wandong Medical |
| Jiahong |
| Siemens Healthineers |
| GE Healthcare |
| FUJIFILM |
| Others |
Pricing and Supply Chain Analysis
Ninety-day component lead times for flat-panel detector substrates compress margin flexibility for system integrators while amplifying pricing power for captive producers. SAMR centralized procurement pilots and NMPA GB 9706.1 certification requirements together reshape how procurement committees weigh upfront equipment costs against total lifecycle service commitments.
Pricing Analysis
Cost-plus contracts with rare-earth element indexation dominate detector supply agreements between system integrators and substrate vendors. Three-tier pricing structure across premium direct-conversion, standard indirect-conversion, and economy computed radiography levels separates Beijing-Shanghai tertiary hospitals from county-level facilities. Pricing pressure stems from SAMR bulk purchasing pilots imposing rigid ceilings on standardized digital X-ray configurations. County hospital procurement committees exhibit highest price sensitivity due to budget constraints delaying computed radiography substitution.
Supply Chain Analysis
Strategic stockpiling of amorphous selenium and cesium iodide substrates prevails over just-in-time approaches given NMPA certification batch requirements and six-month requalification windows. China, Japan, and South Korea concentrate flat-panel detector manufacturing, with Jiangsu and Zhejiang provinces hosting downstream system assembly. Rare-earth phosphor materials and high-purity semiconductor substrates constitute critical input dependencies. Single-source vulnerability concentrates in direct-conversion selenium deposition equipment. Distribution runs through provincial health commission tender platforms aggregating multi-hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: NMPA GB 9706.1 certification timelines and provincial tender prequalification create switching costs that lock hospital procurement committees into validated vendor relationships.
For Market Incumbents: Secure captive flat-panel detector supply through backward integration or long-term offtake agreements with Jiangsu-based substrate vendors. Deepen service network density in Sichuan-Chongqing tier-two corridors where maintenance response times determine contract awards. Emerging domestic detector suppliers threaten cost parity within three to five years.
For New Entrants and Emerging Players: Anchor in independent diagnostic center channels where regional imaging alliances consolidate procurement outside traditional hospital sales structures. Target Pearl River Delta county hospital upgrade cycles delayed by computed radiography substitution lag. Lead with AI-integrated imaging software modules addressing legacy PACS interoperability friction.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flat-panel detector manufacturing as domestic supply chains achieve scale. Five-to-ten year viability favors vertically integrated specialists with captive detector production and established NMPA certification track records. Monitor provincial bulk purchasing program expansion into CT and MRI modalities as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA GB 9706.1 Certification Investment | Accelerates device registration timelines and unlocks provincial health commission tender eligibility. |
| Flat-Panel Detector Backward Integration | Captive selenium substrate production controls cost structures against imported alternative pricing. |
| Regional Diagnostic Alliance Partnership | Aggregates procurement volume through Jiangsu-Zhejiang independent diagnostic center channels. |
| AI-Integrated Imaging Software Development | Addresses hospital IT interoperability challenges with legacy PACS infrastructure. |
| Tier-Two Service Network Expansion | Maintenance response time density determines vendor selection in county hospital segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committee members, biomedical engineering directors, provincial health commission tender administrators, flat-panel detector manufacturing executives, and independent diagnostic center operators. Secondary validation drew from NMPA device registration databases, SAMR centralized procurement pilot disclosures, provincial health commission tender platforms, hospital procurement records, and GB standards compliance filings. Bottom-up equipment shipment estimates and top-down healthcare infrastructure investment flows were triangulated to constrain forecast variance.
Across the analysis window, projections incorporate product type segmentation by CT scanner, digital X-ray, MRI, and ultrasound modalities; application segmentation across oncology, orthopedics, cardiology, and neurology protocols; end-user segmentation spanning hospitals, diagnostic centers, outpatient clinics, and research institutes; and technology segmentation covering flat-panel detector conversion architectures. CAGRs were derived from equipment replacement cycle modeling, provincial infrastructure budget allocations, and cancer center network expansion trajectories. Detector technology substitution curves and SAMR pricing oversight intensity served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued NMPA regulatory streamlining and provincial bulk purchasing program expansion; material deviation would warrant model refresh. Revision becomes warranted when domestic flat-panel detector supply chains achieve cost parity with imported alternatives or when centralized procurement pilots absorb higher-end modalities beyond digital X-ray systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market