
 Neurotech Devices Market | 2026-2036
Neurotech Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurotech Devices Market Analysis
Software-defined programming for implantable neurostimulators is recalibrating what manufacturers actually sell, shifting revenue from hardware placement to recurring algorithm updates and remote parameter tuning. Medtronic plc leverages its integrated care management platform to sustain long-term patient relationships beyond the initial surgical procedure. Abbott Laboratories anchors its competitive position through proprietary directional lead technology that differentiates its deep brain stimulation portfolio. Neuralink Corp. competes on surgical automation, positioning its robotic implantation system as a gateway to scalable brain-computer interface adoption.
Neurotech devices encompass implantable and non-invasive systems that modulate, monitor, or restore neural function through electrical, magnetic, or computational interfaces, typically operating at signal frequencies between 1–200 Hz and requiring biocompatible electrode materials such as platinum-iridium alloys. These systems serve therapeutic restoration in Parkinson's disease, epilepsy, and sensorineural hearing loss, alongside emerging cognitive augmentation applications. Neurostimulation devices occupy the largest installed base due to decades of clinical validation in pain and movement disorders, while brain monitoring systems represent the fastest-expanding category as closed-loop algorithms enable real-time seizure prediction and adaptive therapy delivery. Neuroprosthetics command premium pricing tied to custom surgical fitting and regulatory exclusivity, particularly in cochlear and retinal implant segments where manufacturing complexity limits competitive entry.
FDA breakthrough device designation and CE marking under the EU Medical Device Regulation shape product development timelines, with the former accelerating market access for novel neuromodulation therapies and the latter imposing stricter post-market surveillance requirements on European commercialization. The FDA's evolving guidance on brain-computer interfaces and the EU AI Act's risk classification framework for adaptive algorithms are creating dual compliance pathways that favor companies with parallel regulatory capabilities. Stakeholders must monitor how reimbursement authorities in Germany, the United Kingdom, and Japan classify software-upgradable implants versus static devices, as this determination will dictate pricing power and contract structures across the next product generation.
Market Dynamics
Software-defined neurostimulators are compressing hardware refresh cycles and recalibring manufacturer revenue toward recurring algorithm subscriptions, fundamentally altering capital deployment patterns across the value chain.
Growth Catalysts
- FDA breakthrough device designation:The pathway accelerates commercialization timelines for novel neuromodulation therapies, reducing time-to-revenue for adaptive brain-computer interfaces.
- German university hospital networks:These clinical validation clusters anchor next-generation BCI development, creating concentrated demand for closed-loop seizure prediction systems.
- Platinum-iridium electrode alloys:Advances in biocompatible materials extend implant longevity and reduce revision surgery rates, improving lifetime value calculations for payers.
Market Restraints
- Custom surgical fitting costs:Neuroprosthetics require patient-specific manufacturing that limits scale economies and maintains premium pricing barriers to mass adoption.
- EU MDR post-market surveillance:Stricter reporting requirements for software-upgradable implants extend compliance timelines and inflate European commercialization costs.
- Neurostimulator battery replacement:Finite power lifespans necessitate revision procedures that create patient attrition and reimbursement friction.
Strategic Opportunities
- Japan's aging demographic:Parkinson's disease prevalence creates concentrated demand for deep brain stimulation systems in metropolitan hospital networks.
- Remote parameter tuning channels:Telemedicine integration enables real-time algorithm optimization without clinic visits, opening rural and home-care segments.
- EU AI Act risk classification:Adaptive therapy algorithms face favorable regulatory treatment relative to diagnostic AI, creating compliance arbitrage for closed-loop devices.
Industry Challenges
- Neural signal processing expertise:Scarcity of engineers fluent in both electrophysiology and machine learning constrains product development velocity.
- CE marking timeline compression:Parallel FDA and EU regulatory submissions require duplicative clinical evidence generation that strains R&D budgets.
- Legacy hospital IT integration:Proprietary neurostimulator data formats create interoperability friction with existing electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurotech Devices Market |
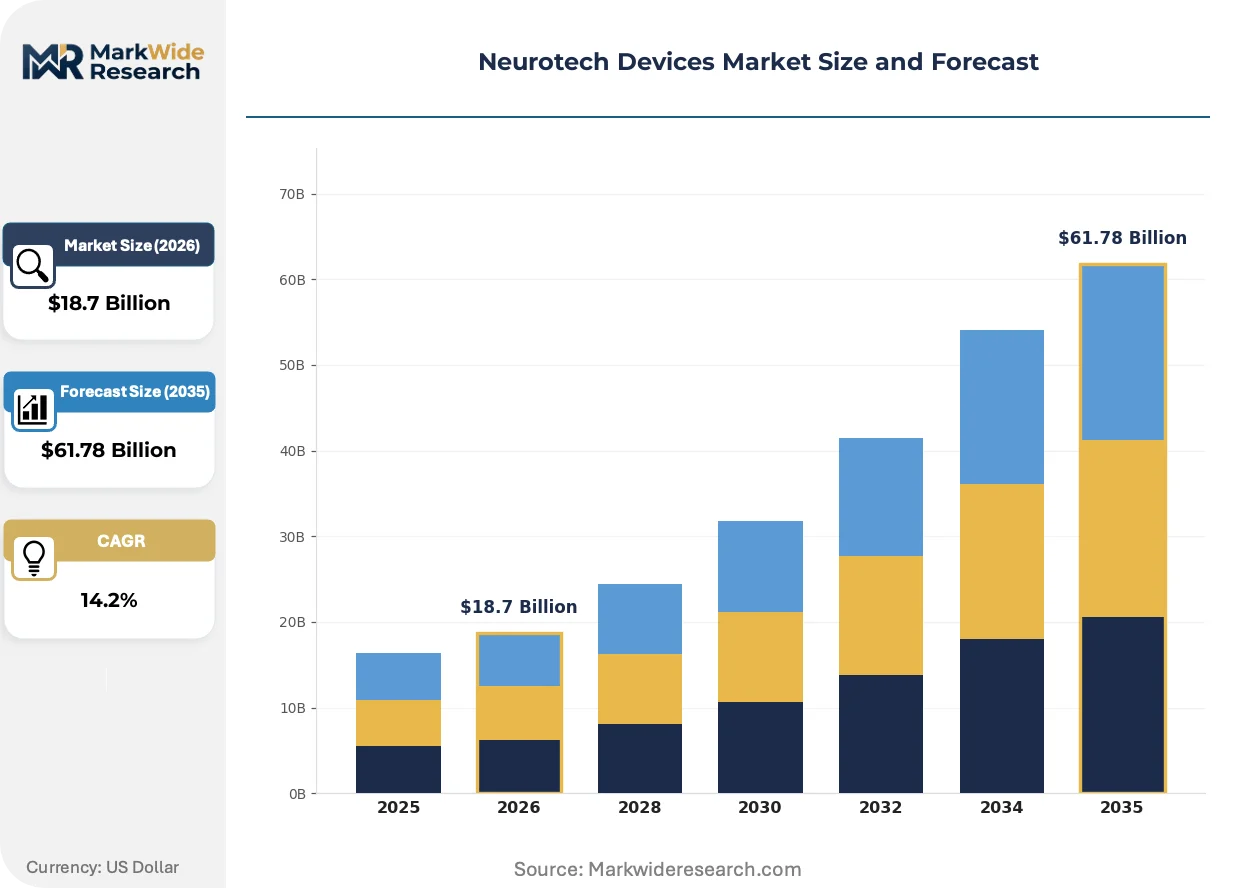
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Neuroprosthetics, Brain Monitoring Systems, Cognitive Enhancement Devices Application: Neurological Disorders, Pain Management, Rehabilitation, cognitive Development End User: Hospitals, Research Institutions, Clinics, Home Care Settings Technology: Transcranial Magnetic Stimulation, Electroencephalography, Deep Brain Stimulation, Functional MRI |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Nihon Kohden Corporation, Cochlear Limited, NeuroPace, Inc., Nevro Corp., Neuralink Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurotech Devices Market Emerging Trajectories
Closed-loop algorithms are displacing open-loop stimulation paradigms, enabling real-time therapeutic adaptation that responds to patient-specific neural biomarkers rather than fixed parameter sets.
Directional lead technology is electrifying deep brain stimulation precision by steering current toward targeted neural populations while avoiding adjacent structures. Movement disorder centers in the United States are adopting these systems at accelerated pace to reduce side-effect profiles. This capability is electrifying competitive differentiation in the premium neurostimulator tier and compressing market share for legacy ring-electrode configurations.
The EU AI Act's risk classification framework for adaptive algorithms is creating dual compliance obligations for manufacturers pursuing transatlantic commercialization. European notified bodies are interpreting machine-learning-enabled parameter adjustment as higher-risk functionality than static programming. Neurostimulation systems with autonomous adaptation features face extended conformity assessment timelines in Germany and France relative to conventional devices.
Hospital procurement departments are unbundling hardware placement from long-term algorithm management, creating separate contract vehicles for initial implantation and ongoing software subscriptions. Academic medical centers in the United Kingdom are piloting per-patient-per-month pricing models that align vendor incentives with therapeutic outcomes. This restructuring is most visible in chronic pain management programs where remote monitoring capabilities enable outcome verification.
Neurotech Devices Market Segmentation
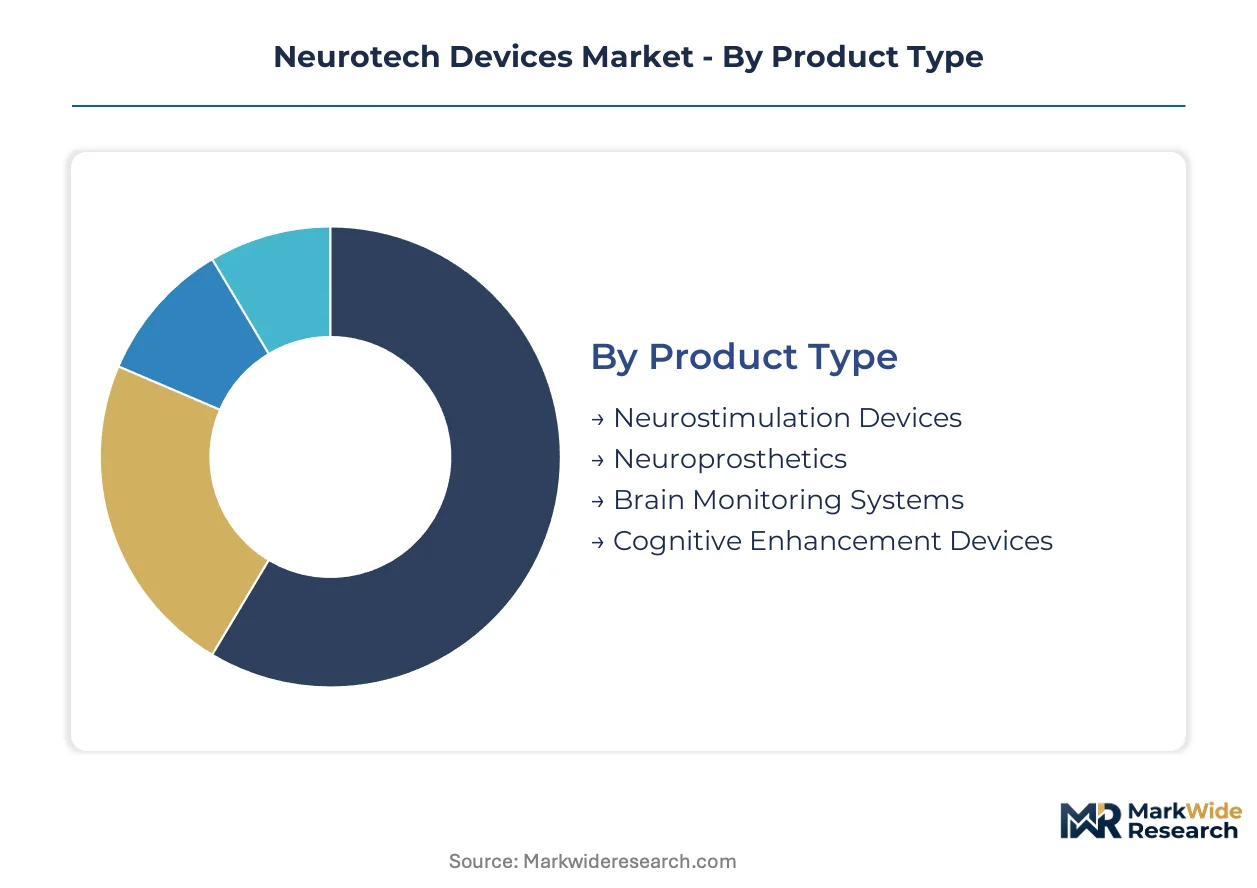
Neurotech device segmentation reveals how supply concentration, clinical validation requirements, and reimbursement pathways fragment commercial opportunity across distinct technical and customer categories. Manufacturers must align R&D investment with segment-specific regulatory timelines and purchasing authority structures.
Product Type:
Supply concentration in neurostimulation hardware has shifted manufacturing scale toward closed-loop platforms while neuroprosthetics remain captive to custom surgical workflows.
- Neurostimulation Devices:Implantable systems delivering electrical pulses at 1–200 Hz through platinum-iridium electrodes dominate therapeutic restoration for movement disorders. Demand concentrates in German university hospital networks validating adaptive parameter adjustment algorithms.
- Neuroprosthetics:Patient-specific cochlear and retinal implants require custom surgical fitting that limits batch production economies. Japanese metropolitan hospitals anchor premium pricing through concentrated procurement of auditory restoration systems.
- Brain Monitoring Systems:Closed-loop seizure prediction platforms represent the steepest expansion trajectory as real-time biomarker processing enables therapeutic adaptation.
- Cognitive Enhancement Devices:Non-invasive transcranial systems face reimbursement uncertainty outside research protocols.
Neurostimulation Devices absorb the bulk of installed capacity; Brain Monitoring Systems are expanding most quickly.
Application:
Cost tier stratification separates premium-priced movement disorder therapies from commoditized pain management protocols.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease commands premium pricing tied to surgical precision and battery longevity. Japanese aging demographics concentrate demand in Tokyo and Osaka hospital networks.
- Pain Management:Spinal cord stimulation for chronic back pain faces reimbursement compression as remote monitoring enables outcome verification.
- Rehabilitation:Stroke recovery neuroprosthetics require extended clinical validation timelines that strain smaller manufacturer balance sheets.
- Cognitive Development:Pediatric attention deficit applications remain experimental with limited payer coverage outside research institutions.
Neurological Disorders capture the largest revenue pool; Rehabilitation applications are climbing the fastest as stroke incidence rises in aging populations.
End User:
Customer type determines purchasing authority complexity, with hospital procurement departments unbundling hardware from algorithm subscriptions.
- Hospitals:Academic medical centers in the United Kingdom pilot per-patient-per-month pricing models that align vendor incentives with therapeutic outcomes.
- Research Institutions:Brain-computer interface development concentrates in German university hospital networks anchoring FDA breakthrough device validation.
- Clinics:Outpatient pain management programs adopt remote parameter tuning to extend geographic reach without physical expansion.
- Home Care Settings:Telemedicine-integrated neurostimulators enable rural patient monitoring but face connectivity infrastructure gaps.
Hospitals retain dominant purchasing volume; Home Care Settings are gaining share fastest as remote monitoring matures.
Technology:
Volume concentration favors implantable platforms with decades of clinical validation over diagnostic imaging modalities.
- Transcranial Magnetic Stimulation:Non-invasive magnetic field induction treats depression and migraine without surgical risk. Outpatient clinics in the United States deploy these systems to extend service lines without operating room investment.
- Deep Brain Stimulation:Directional lead technology steers current toward targeted neural populations while avoiding adjacent structures. Movement disorder centers adopt these systems to reduce side-effect profiles and justify premium pricing.
- Electroencephalography:Surface electrode arrays enable seizure prediction algorithms but face signal fidelity constraints relative to implanted alternatives.
- Functional MRI:Research-grade neural mapping remains concentrated in academic medical centers with limited therapeutic application.
Deep Brain Stimulation holds the largest installed base; Transcranial Magnetic Stimulation is expanding most quickly as depression reimbursement pathways stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mannheim anchors European neurotech validation networks through university hospital clusters that stress-test adaptive brain-computer interfaces before FDA breakthrough designation submissions. Demand concentrates where aging demographics intersect with reimbursement stability for movement disorder therapies.
United States
Movement disorder centers in Minnesota and Massachusetts deploy directional lead systems at accelerated pace to reduce side-effect profiles. FDA breakthrough device designation compresses commercialization timelines for novel neuromodulation therapies. The Twin Cities corridor anchors deep brain stimulation surgical volume through concentrated academic medical center procurement.
Germany
University hospitals in Heidelberg and Tübingen validate next-generation closed-loop seizure prediction algorithms for European CE marking. The EU MDR imposes stricter post-market surveillance requirements on software-upgradable implants than static devices. Bavarian precision engineering clusters supply platinum-iridium electrode alloys that extend implant longevity.
Japan
Metropolitan hospital networks in Tokyo and Osaka concentrate demand for deep brain stimulation systems as Parkinson's disease prevalence rises. PMDA regulatory pathways favor hardware platforms with decades of domestic clinical validation. The Kansai region anchors cochlear implant manufacturing through captive audiological research infrastructure.
United Kingdom
Academic medical centers in London and Manchester pilot per-patient-per-month pricing models that align vendor incentives with chronic pain management outcomes. MHRA post-Brexit regulatory autonomy enables faster adaptive algorithm approvals than EU notified body timelines. The Oxford-Cambridge arc concentrates brain-computer interface research through cross-institutional validation consortia.
Australia
TGA regulatory frameworks for neurostimulators emphasize biocompatibility testing that extends lead times for novel electrode materials. Sydney and Melbourne hospital networks anchor demand for spinal cord stimulation in chronic back pain management. The Melbourne biomedical precinct concentrates cochlear implant research through sustained government research funding.
Neurotech Devices Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the neurotech value chain, with implantable hardware manufacturers bearing biocompatibility certification costs that software-centric entrants avoid. The vendor base fragments across three tiers: diversified medical technology conglomerates with integrated care platforms, mid-cap neuromodulation specialists with proprietary lead geometries, and venture-backed brain-computer interface developers competing on surgical automation. Strategic moves concentrate on algorithm licensing partnerships and remote monitoring infrastructure rather than manufacturing scale expansion.
Among diversified medical technology conglomerates, Medtronic plc and Abbott Laboratories exemplify integrated platform strategies that bundle hardware placement with recurring software subscription revenue. Boston Scientific Corporation occupies a position within the neuromodulation specialist tier, anchoring competitive differentiation through directional current steering capabilities. Neuralink Corp. represents the surgical automation archetype, competing on robotic implantation scalability rather than established clinical validation networks.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Nihon Kohden Corporation |
| Cochlear Limited |
| NeuroPace, Inc. |
| Nevro Corp. |
| Neuralink Corp. |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility certification gates qualified supply of platinum-iridium electrodes while simultaneously stratifying pricing access across implantable neurostimulator tiers, as manufacturers without notified body relationships face exclusion from premium reimbursement bands in German and French hospital networks.
Pricing Analysis
Value-based pricing anchors on therapeutic outcome verification through remote monitoring platforms that document seizure reduction rates and pain score improvements. Three-tier pricing structure across premium adaptive systems, standard programmable devices, and economy fixed-parameter models reflects algorithm sophistication and battery longevity differentials. Cost compression in the standard tier intensifies because hospital procurement departments unbundle hardware from software subscriptions. Research institutions exhibit lowest price sensitivity due to grant-funded validation budgets, while outpatient pain clinics face highest sensitivity tied to capitated reimbursement contracts.
Supply Chain Analysis
Freight costs for temperature-sensitive biocompatible alloys from Bavarian precision engineering clusters to FDA-registered cleanroom facilities in Minnesota and Massachusetts add 12-15% to landed electrode material costs. Manufacturing concentrates in Germany, the United States, and Japan, with platinum-iridium alloys, ceramic feedthroughs, and lithium-ion cells anchoring component dependencies. Single-source vulnerability for medical-grade platinum concentrates supply risk given South African mining concentration. Distribution runs through specialized medical device distributors with GPO contracts rather than direct hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop algorithms are displacing open-loop stimulation paradigms, creating a technology-transition phase where adaptive therapy platforms render legacy fixed-parameter systems obsolete across movement disorder and pain management applications.
For Market Incumbents: To counter surgical automation entrants competing on implantation scalability, deepen backward integration into platinum-iridium electrode manufacturing to secure biocompatibility certification advantages. Anchor channel control through exclusive GPO contracts with academic medical centers in the United Kingdom piloting per-patient-per-month pricing models.
For New Entrants and Emerging Players: Telemedicine infrastructure partners offer the fastest channel to rural and home-care segments underserved by incumbent field clinical specialist networks. Target stroke rehabilitation neuroprosthetics in Japanese metropolitan hospitals where aging demographics concentrate demand but custom surgical fitting costs limit incumbent scale economies. Pursue algorithm licensing partnerships with mid-tier neuromodulation specialists lacking in-house machine learning capabilities.
For Investors and Strategic Acquirers: FDA breakthrough device designation announcements are the leading indicator that valuation multiples will expand for pre-revenue brain-computer interface developers. Five-to-ten year viability favors platforms with parallel FDA and CE marking capabilities given divergent AI Act and evolving BCI guidance timelines. Acquisition target archetype: venture-backed closed-loop seizure prediction systems with German university hospital validation networks. Watch for MHRA post-Brexit regulatory autonomy enabling faster adaptive algorithm approvals than EU notified body timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR software-upgradable implant requirements compress conformity assessment timelines for adaptive algorithms in Germany. |
| Hospital System Partnership | Academic medical center alliances in London and Manchester enable per-patient-per-month pricing pilot programs. |
| Software Companion Development | Remote parameter tuning applications extend geographic reach without physical clinic expansion into rural segments. |
| Reimbursement Strategy | German diagnosis-related group classification for algorithm-upgradable implants versus static devices dictates pricing power. |
| FDASubmission | Breakthrough device designation accelerates commercialization timelines for novel neuromodulation therapies in Minnesota corridors. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance trajectories, CE marking database entries, and hospital procurement contract awards anchored the trend analysis, supplemented by interviews with deep brain stimulation surgical directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA filings, EUDAMED post-market surveillance records, CMS Medicare reimbursement databases, and hospital procurement system extracts. Bottom-up installed base modeling triangulated against top-down neuromodulation therapy penetration estimates.
Input-output matrices mapped electrode material costs, surgical procedure volumes, and algorithm subscription attach rates across product type, application, end user, and technology segmentation dimensions over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in movement disorder and pain management indications. Forecast inputs incorporated PMDA regulatory pathway timelines for Japanese aging demographic demand concentration and MHRA post-Brexit autonomous approval velocity.
Caveats apply where EU AI Act risk classification revisions for adaptive therapy algorithms or reimbursement authority reclassification of software-upgradable implants could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hormonal Implants Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Global Spirometers Market
Medical Devices
Occlusion Microcatheter Market