
 US Virtual Visits Market | 2026-2036
US Virtual Visits Market Size, Share, and Industry Trends Forecast 2026-2036
US Virtual Visits Market Intelligence
DEA registration requirements for controlled substance prescribing via telehealth is bifurcating the competitive landscape between compliant platforms and limited-service entrants. Teladoc Health leverages its multi-specialty physician network to sustain nationwide coverage depth. American Well anchors enterprise contracts with large hospital systems seeking white-label infrastructure. MDLIVE competes on speed-to-appointment metrics in urgent care verticals.
Virtual visits encompass real-time, synchronous clinical encounters delivered through digital interfaces connecting patients with licensed providers, typically requiring HIPAA-compliant encryption, minimum bandwidth thresholds of 1.5 Mbps, and integration with electronic health record systems for care continuity. The primary commercial purpose centers on expanding healthcare access while reducing per-encounter costs relative to traditional facility-based delivery. Video conferencing technology leads current deployment volumes but mobile app delivery is expanding fastest among younger demographics seeking asynchronous touchpoints. Telehealth as a service type captures the broadest reimbursement coverage, while behavioral health remote therapy commands premium pricing due to specialist scarcity and persistent demand-supply imbalances.
FDA oversight of Software as a Medical Device intersects with CMS reimbursement policy and state-level medical board licensure requirements to create a fragmented compliance environment that shapes platform architecture decisions. HIPAA security rule enforcement by the Office for Civil Rights directly constrains how patient data flows between virtual visit platforms and third-party analytics vendors. State telehealth parity laws vary in scope, forcing multi-state operators to maintain configurable compliance engines rather than uniform national deployments. Stakeholders must monitor evolving DEA flexibilities for controlled substances and state-level scope-of-practice expansions for nurse practitioners as decisive variables shaping addressable market boundaries.
Market Dynamics
Medicare reimbursement parity rules under CMS are compressing traditional fee-for-service margins while forcing health systems to reconfigure care delivery around virtual-first encounter models. Rural provider shortages accelerate platform consolidation as networks seek geographic coverage density.
Growth Catalysts
- CMS Reimbursement Parity:Federal mandates requiring equivalent payment for virtual and in-person visits eliminate historical price disincentives. Hospital systems now embed telehealth into standard care protocols.
- Rural Health Access Gaps:Provider shortages across Midwest and Southeast states drive health system investment in asynchronous triage platforms. Federally qualified health centers deploy virtual infrastructure to retain patient panels.
- Behavioral Health Integration:Specialist scarcity in psychiatry and addiction medicine creates structural demand for remote therapy modalities. Employer-sponsored programs expand coverage for digital mental health encounters.
Market Restraints
- DEA Registration Barriers:Controlled substance prescribing restrictions fragment platform capabilities and limit service breadth for pain management and ADHD treatment.
- State Licensure Fragmentation:Medical board requirements vary across jurisdictions, forcing multi-state operators to maintain redundant compliance infrastructure and physician credentialing systems.
- Bandwidth Infrastructure Inequality:Minimum 1.5 Mbps thresholds exclude patient populations in broadband deserts, constraining addressable market penetration in rural geographies.
Strategic Opportunities
- Asynchronous Care Models:Store-and-forward dermatology and radiology applications expand beyond real-time video into lower-cost encounter formats. Health systems capture margin through automated triage workflows.
- Nurse Practitioner Scope Expansion:State-level legislative changes in Texas and Florida authorize independent virtual prescribing authority. Platforms reconfigure staffing models to leverage mid-level provider capacity.
- Remote Patient Monitoring Convergence:Integration of continuous glucose monitors and blood pressure cuffs with virtual visit platforms creates chronic care subscription revenue streams.
Industry Challenges
- EHR Integration Complexity:Proprietary data formats from Epic and Cerner impose middleware development costs on platform vendors seeking health system contracts.
- Cybersecurity Certification Burden:HIPAA security rule enforcement by OCR requires continuous penetration testing and business associate agreement renegotiation with analytics partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Virtual Visits Market |
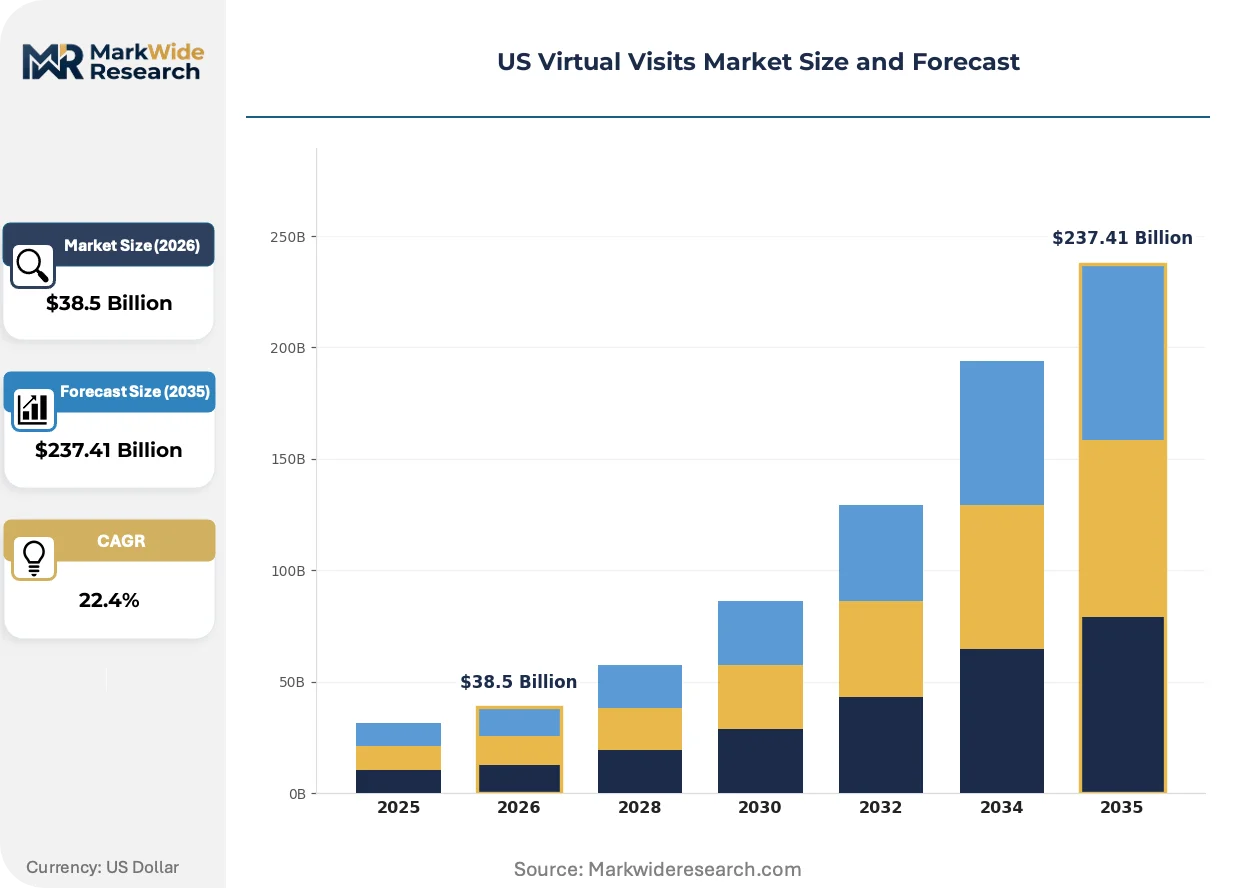
| Market Size in 2026 | $38.5 Billion |
| Market Size in 2035 | $237.41 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Live Chat, Remote Monitoring, Mobile App Service Type: Telehealth, Online Consultation, Remote Therapy, Behavioral Health End User: Patients, Healthcare Providers, Insurance Companies, Employers Delivery Mode: Desktop Application, Mobile Application, Web-Based, Integrated Platform |
| Companies Covered | Teladoc Health, American Well, MDLIVE, Doctor On Demand, CVS Health, HealthTap, PlushCare, SOC Telemed, 98point6, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Virtual Visits Market Strategic Shifts & Innovations
Platform architectures are pivoting from standalone video tools toward embedded care coordination systems that synchronize patient data across encounter types. This shift compresses development timelines for new market entrants.
AI-powered clinical decision support is displacing traditional nurse triage protocols in urgent care verticals. Large health systems in California and New York deploy symptom-checker algorithms to route patients before human provider contact. The technology compresses per-encounter labor costs while redirecting low-acuity cases away from emergency departments.
DEA flexibilities for controlled substance prescribing via telehealth face permanent legislative uncertainty. The Ryan Haight Online Pharmacy Consumer Protection Act amendments create compliance volatility for platforms treating ADHD and opioid use disorder. Behavioral health specialists in Pennsylvania and Ohio are diversifying service portfolios to reduce dependence on scheduled medication management.
Employer-sponsored plan designs now embed virtual-first requirements that steer employees toward digital encounters before facility-based care. Fortune 500 procurement teams in Michigan and Georgia negotiate per-member-per-month contracts that displace traditional visit fee structures. This procurement compression is most visible in self-insured manufacturing and logistics sectors seeking predictable healthcare expenditure.
US Virtual Visits Market Segmentation
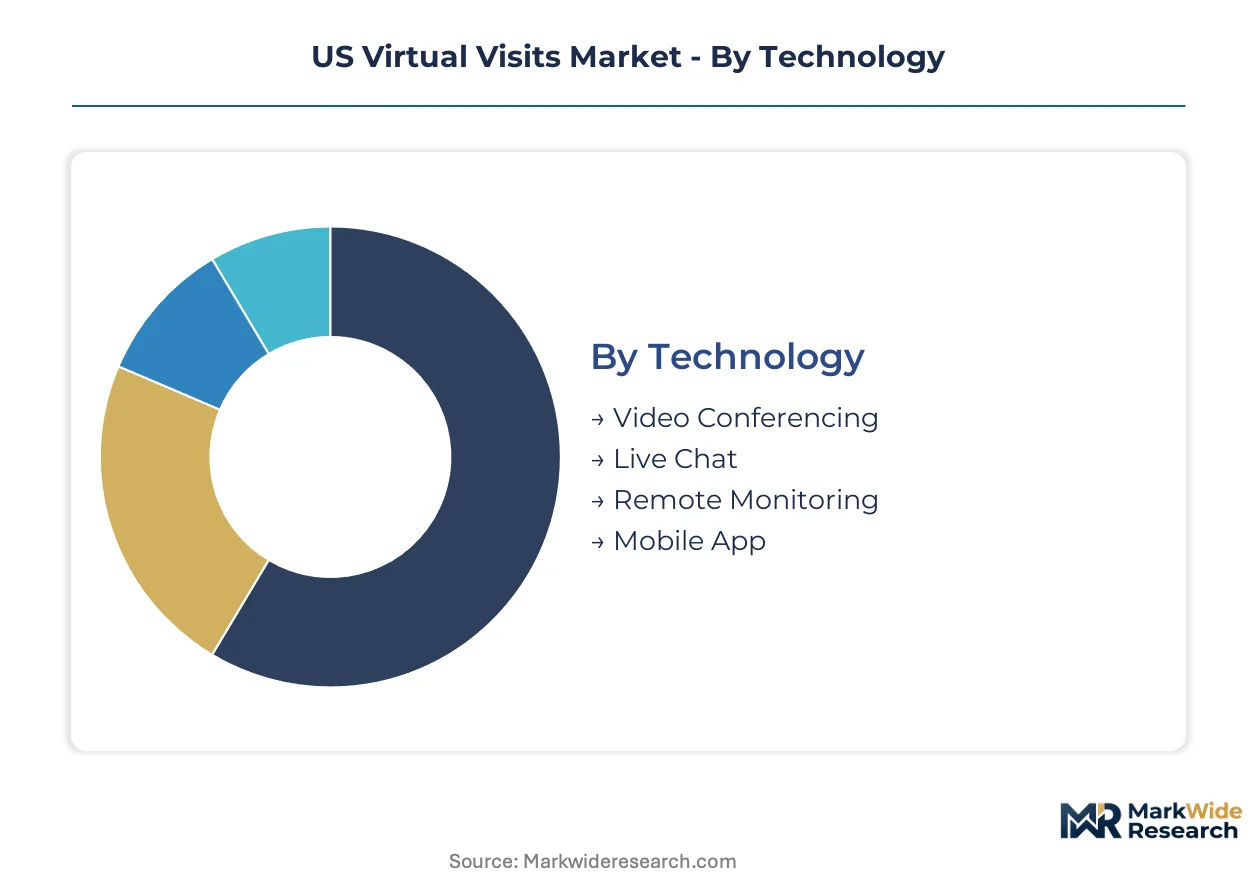
Virtual visit platforms route patient encounters through distinct technology stacks and service modalities that determine reimbursement pathways, compliance burdens, and margin structures. Segment boundaries shift as CMS rules redefine billable encounter types and employer plan designs steer utilization toward preferred channels.
Technology:
Channel mix varies sharply by bandwidth availability and encounter acuity, with synchronous modalities dominating fee-for-service billing while asynchronous tools capture subscription revenue.
- Video Conferencing:Real-time audiovisual encounters requiring 1.5 Mbps minimum bandwidth and HIPAA-compliant encryption. Hospital systems in the Southeast deploy this for specialist consultations where visual assessment is clinically necessary, though rural broadband gaps constrain penetration in Appalachian counties.
- Mobile App:Native smartphone applications enabling asynchronous messaging and photo-based triage. Younger demographics in Texas and Florida drive fastest adoption here, with platforms capturing recurring subscription fees rather than per-visit charges.
- Live Chat:Text-based synchronous encounters for low-acuity symptom assessment. Federally qualified health centers integrate this into patient portals to deflect unnecessary emergency department visits.
- Remote Monitoring:Continuous biometric data transmission from connected devices. Chronic care programs in the Midwest bundle this with virtual visits for diabetes and hypertension management.
Video conferencing dominates installed base. Mobile app is where expansion concentrates.
Service Type:
Margin profiles diverge by clinical complexity, with behavioral health commanding premium pricing due to specialist scarcity and regulatory barriers limiting prescriptive authority.
- Telehealth:Broad category encompassing synchronous clinical encounters across all specialties. Medicare reimbursement parity under CMS rules has embedded this into standard care protocols across hospital systems in Michigan and Georgia.
- Behavioral Health:Remote psychiatric and addiction medicine services. DEA registration requirements for controlled substances fragment platform capabilities, with Pennsylvania and Ohio specialists diversifying into therapy-only models to reduce compliance exposure.
- Online Consultation:General medical advice for non-urgent conditions. Employer-sponsored programs in the Midwest steer employees here before facility-based care to capture predictable per-member-per-month expenditure.
- Remote Therapy:Counseling and psychotherapy delivered via video or audio. State-level scope-of-practice expansions for nurse practitioners in Texas and Florida are reconfiguring staffing models for this segment.
Telehealth captures the broadest reimbursement coverage. Behavioral health shows the steepest expansion trajectory.
End User:
Procurement authority and payment responsibility determine platform feature requirements, with employers and insurers driving standardization while providers prioritize EHR integration.
- Patients:Individual consumers accessing direct-to-pay services. Out-of-pocket payment concentration in urgent care verticals creates price sensitivity that platforms address through transparent visit fees.
- Healthcare Providers:Hospitals and physician groups deploying white-label infrastructure. Epic and Cerner integration requirements impose middleware development costs that favor established vendors.
- Employers:Self-insured corporations negotiating population health contracts. Manufacturing and logistics sectors in Michigan and Georgia procure per-member-per-month arrangements that displace traditional fee-for-service structures.
- Insurance Companies:Payers embedding virtual-first requirements into plan designs. Prior authorization protocols increasingly mandate digital encounter attempts before facility-based care approval.
Healthcare providers dominate current deployment volumes. Employers represent the fastest-climbing procurement channel.
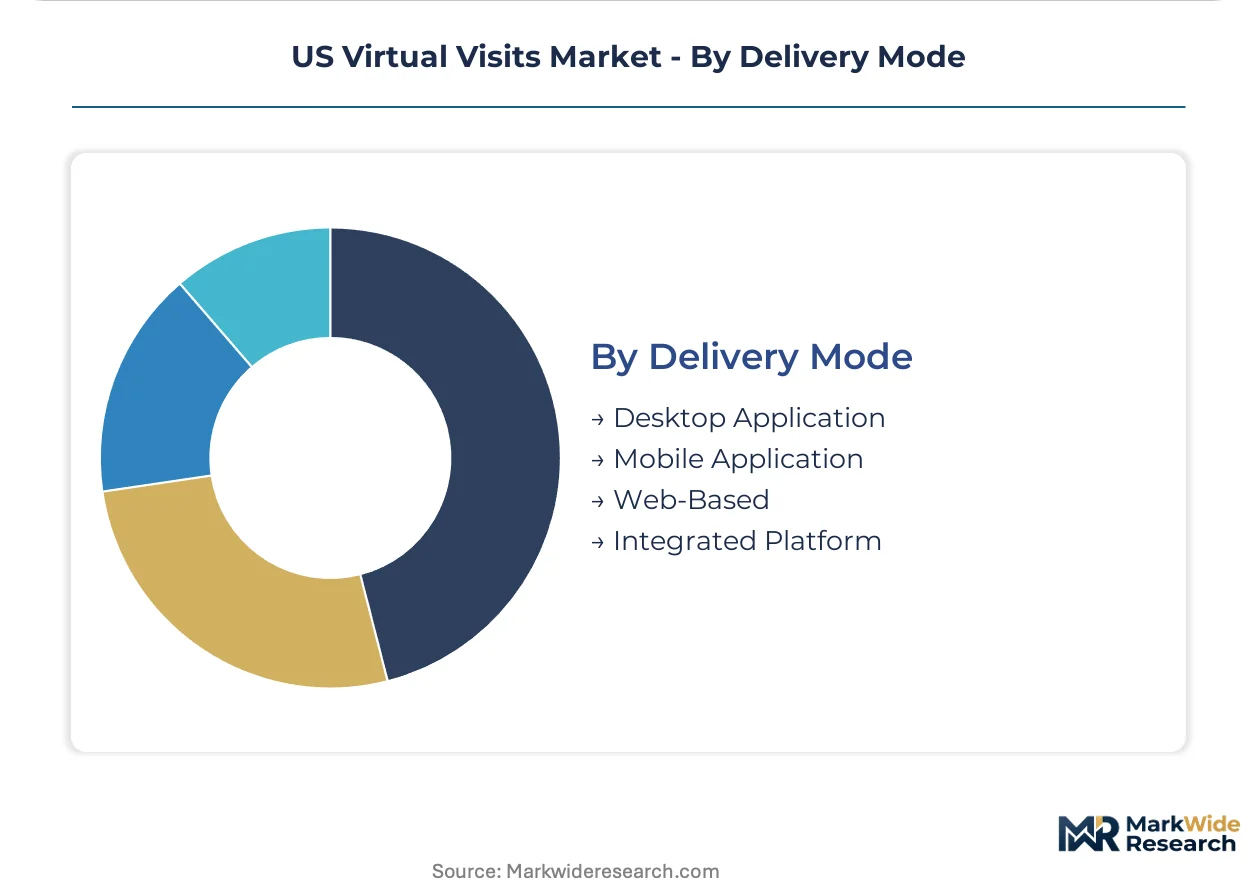
Delivery Mode:
Architecture choices reflect IT governance standards and user experience priorities, with integrated platforms capturing enterprise contracts while single-purpose apps serve niche use cases.
- Web-Based:Browser-accessible encounters requiring no local installation. Rural health systems favor this for patient populations with device diversity and limited technical support capacity.
- Integrated Platform:Embedded care coordination systems synchronizing data across encounter types. Large hospital networks in California and New York deploy this to compress development timelines and unify patient records.
- Desktop Application:Installed software for high-security environments. Federal qualified health centers maintain this option for compliance with stringent HIPAA security rule enforcement by OCR.
- Mobile Application:Native iOS and Android deployments. Asynchronous touchpoint demand among younger users drives fastest feature iteration cycles here.
Web-based access holds the largest addressable reach. Integrated platform is where enterprise contract value concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and fiber-optic backbone density across the Midwest and Southeast underwrite the geographic concentration of virtual visit adoption. Rural broadband expansion programs from the FCC's Rural Digital Opportunity Fund reshape addressable market boundaries state by state.
California
Silicon Valley health tech clusters and Kaiser Permanente's integrated delivery networks drive platform innovation cycles. The California Department of Public Health enforces stringent telehealth privacy standards that exceed federal HIPAA baselines. Los Angeles and San Francisco anchor enterprise contract procurement for white-label virtual infrastructure.
Texas
Employer-sponsored programs in Dallas-Fort Worth and Houston energy corridors generate concentrated demand for occupational health virtual visits. The Texas Medical Board expanded nurse practitioner independent prescribing authority through 2023 legislative amendments. Austin's startup ecosystem incubates asynchronous care model developers targeting younger demographics.
Michigan
Self-insured manufacturing employers in Detroit and Grand Rapids negotiate per-member-per-month virtual-first health plan designs. CMS reimbursement parity enforcement through the Detroit Medicare Administrative Contractor standardizes billing protocols across hospital systems. The University of Michigan Health System deploys integrated platform architecture for rural specialty consultation networks.
Pennsylvania
Behavioral health specialist scarcity in Pittsburgh and Philadelphia metropolitan areas sustains premium pricing for remote psychiatric services. DEA registration requirements for controlled substance prescribing create compliance complexity for platforms treating ADHD and opioid use disorder. Philadelphia's health system consolidation trend favors vendors with Epic EHR integration capabilities.
Florida
Snowbird population mobility between Northeast and Southeast drives demand for multi-state licensure platform coverage. The Florida Board of Medicine maintains reciprocal telehealth licensing agreements that reduce credentialing friction for out-of-state providers. Miami and Tampa hospital systems invest in Spanish-language virtual visit interfaces to capture Hispanic patient panels.
US Virtual Visits Market Key Industry Players
Listed leaders compete with private specialists across enterprise contract channels, creating a tiered structure where scale advantages separate national platforms from regional operators. The vendor base fragments across technology delivery modes, with video conferencing incumbents defending installed base against mobile-native challengers. Three archetypes dominate: multi-specialty physician networks, white-label infrastructure providers, and urgent care speed specialists. Consolidation through health system M&A and strategic partnerships with EHR vendors constitute the primary competitive vectors reshaping market share distribution.
Within the multi-specialty network tier, Teladoc Health and American Well occupy positions exemplifying divergent strategic postures toward enterprise versus direct-to-consumer channels. MDLIVE anchors the urgent care speed archetype. These three entities collectively represent the competitive reference points against which newer entrants benchmark platform capabilities and contract terms.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| MDLIVE |
| Doctor On Demand |
| CVS Health |
| HealthTap |
| PlushCare |
| SOC Telemed |
| 98point6 |
| Others |
Cost & Logistics Intelligence
Per-member-per-month contracts lock in multi-year revenue visibility for virtual visit platforms while compressing price flexibility for health systems seeking predictable expenditure. This contract structure binds employer-sponsored programs in Michigan and Georgia to fixed-rate arrangements that shield vendors from visit-volume volatility.
Pricing Analysis
HIPAA certification tier creates the primary spread between enterprise-grade platforms and limited-service entrants. Three-tier pricing structure across premium, standard, and economy levels segments the market by EHR integration depth and DEA registration status. Cost compression in the urgent care vertical intensifies because MDLIVE and similar speed-focused competitors race to zero-margin acquisition. Self-insured employers show highest price sensitivity due to procurement team mandates, while integrated delivery networks demonstrate lowest sensitivity given care continuity requirements.
Supply Chain Analysis
Just-in-time cloud infrastructure provisioning dominates platform architecture decisions, though strategic stockpiling of physician licenses in high-demand states buffers regulatory volatility. Software development concentrates in California, Texas, and New York, with clinical staffing networks anchored in Florida and Pennsylvania for licensure reciprocity advantages. Raw material dependencies include AWS and Azure compute capacity, Epic and Cerner API access, and DEA-registered prescriber pools. Single-source vulnerability in EHR integration middleware threatens margin stability. Distribution runs through health system procurement committees and employer benefits consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in virtual care hinge on Epic and Cerner interoperability consolidation, which is compressing standalone vendor margins while rewarding embedded infrastructure providers.
For Market Incumbents: Secure exclusive EHR integration partnerships with hospital systems in Pennsylvania and Ohio before mid-level platform competitors replicate American Well's white-label architecture. Deepen clinical network density in behavioral health to offset DEA registration barriers threatening ADHD and opioid use disorder service lines. Lock in multi-state nurse practitioner staffing models in Texas and Florida to exploit scope-of-practice expansions. For New Entrants and Emerging Players: Differentiate on asynchronous care models targeting rural broadband-constrained geographies in Appalachian counties where video bandwidth thresholds exclude incumbent platforms. Penetrate the store-and-forward dermatology segment where automated triage workflows capture margin through lower labor intensity. Deploy Spanish-language interfaces in Florida to capture Hispanic patient panels underserved by national competitors. For Investors and Strategic Acquirers: Mobile-native platforms with asynchronous-first architectures represent the highest-conviction acquisition archetype for portfolio exposure to younger demographic adoption curves. Long-term viability rests on CMS reimbursement parity permanence and DEA flexibility continuity rather than technology differentiation alone. Monitor state-level scope-of-practice legislation in Texas and Florida as the decisive signal for mid-level provider capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Epic EHR Integration Partnership | Epic's closed ecosystem in Pennsylvania health systems creates defensive moats for embedded platforms. |
| DEA Registration Expansion | Controlled substance prescribing authority unlocks behavioral health premium pricing in ADHD and addiction medicine. |
| Asynchronous Care Model Launch | Store-and-forward dermatology in rural Midwest captures margin through automated triage workflows. |
| Nurse Practitioner Staffing Scale-Up | Texas and Florida scope expansions reconfigure labor models for remote therapy delivery. |
| Multi-State Licensure Aggregation | Florida reciprocal agreements reduce credentialing friction for snowbird population coverage. |
Research Approach
Cross-validation between CMS Medicare reimbursement databases and employer benefits procurement records anchors the qualitative findings on virtual visit adoption patterns. Primary interviews with health system CIOs, GPO contracts managers, telehealth platform product directors, and DEA-registered behavioral health specialists informed service line prioritization. Secondary validation drew from FDA Software as a Medical Device guidance documents, CMS telehealth parity rulemakings, state medical board licensure databases, and FCC Rural Digital Opportunity Fund disbursement records. Bottom-up encounter volume modeling and top-down employer expenditure analysis triangulate market sizing.
Sensitivity analysis on CMS reimbursement permanence assumptions and DEA flexibility sunset provisions shapes the projection framework. Segmentation dimensions modeled include technology delivery mode, clinical service type, end-user procurement authority, and geographic broadband infrastructure tier. CAGRs derive from encounter volume growth rates applied to per-visit reimbursement benchmarks across the analysis window. Forecast inputs incorporate FCC broadband deployment timelines and state-level nurse practitioner scope legislative tracking.
The analysis sits within stated boundaries; outcomes outside sustained CMS parity enforcement or permanent DEA telehealth flexibilities would require recalibration. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory continuity. DEA registration volatility and state licensure fragmentation constitute primary risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
US Telehealth Market
Telemedicine
Telepathology Service Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Global Telehealth Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Tele-ICU Services Market
Telemedicine
North America Telemedicine Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Video Telemedicine Market