
 US EMS Billing Services Market | 2026-2036
US EMS Billing Services Market Size, Share, and Industry Trends Forecast 2026-2036
US EMS Billing Services Market Insights
US-based revenue cycle specialists is pivoting toward cloud-native platforms that automate prior authorization and real-time eligibility verification. Change Healthcare leverages its clearinghouse infrastructure to anchor large ambulance network contracts. ESO sustains competitive positioning through deep integration with electronic patient care reporting systems. Digitech differentiates via specialized compliance engines tailored to Medicare Part B ambulance fee schedules.
EMS billing services encompass the technical processes of coding emergency medical transports, submitting claims to Medicare, Medicaid, and commercial payers, and managing denials through appeals workflows requiring ICD-10 and HCPCS Level II specificity. These services reduce revenue leakage from downcoded trips and unpaid accounts receivable while ensuring documentation supports medical necessity determinations. Cloud-Based Solutions leads technology adoption as fire departments and private ambulance operators abandon server-dependent legacy systems. Fee-for-Service retains structural dominance in revenue terms though Bundled Payments is gaining traction within integrated healthcare systems seeking episode-based accountability. Claims Management captures disproportionate margin pools relative to transaction volume due to specialized expertise requirements in federal and state appeals procedures.
CMS, HIPAA, and the No Surprises Act collectively shape compliance architecture, with CMS ambulance fee schedule updates directly altering reimbursement coding requirements and the No Surprises Act mandating transparent patient cost estimates before transport. State Medicaid agencies impose supplemental prior authorization rules that vary across jurisdictions, fragmenting standardization efforts. Stakeholders must monitor CMS proposed rules on ground ambulance data collection while evaluating platform investments against evolving interoperability mandates under the Trusted Exchange Framework.
Market Dynamics
Cloud-native revenue cycle platforms are consolidating billing operations across fragmented ambulance networks, compressing the competitive window for server-dependent legacy vendors. HIPAA enforcement actions and the No Surprises Act's cost transparency mandates are accelerating this infrastructure replacement cycle.
Growth Catalysts
- Medicare Part B ambulance fee schedule complexity:Specialized coding requirements for HCPCS Level II modifiers create demand for outsourced expertise that reduces claim denials from documentation errors.
- Municipal privatization waves:Texas, Florida, and California fire departments are outsourcing billing to private operators, expanding the addressable market for third-party revenue cycle management.
- Real-time eligibility verification APIs:Cloud-based prior authorization automation reduces transport-to-payment cycles, improving cash flow for ambulance providers operating on thin margins.
Market Restraints
- State Medicaid fragmentation:Prior authorization rules vary across jurisdictions, preventing standardized workflow deployment and increasing compliance overhead.
- Technical debt in legacy EMS agencies:Rural and municipal operators lack capital reserves for platform migration, slowing aggregate adoption velocity.
- Substitution by in-house billing departments:Large integrated health systems are building captive revenue cycle teams, reducing outsourcing penetration in consolidated markets.
Strategic Opportunities
- Rural ambulance district underpenetration:Volunteer and hybrid fire-EMS departments in the Mountain West and Great Plains lack billing infrastructure, representing greenfield deployment potential.
- Interoperability mandates under TEFCA:Trusted Exchange Framework compliance requirements create pull for platforms with embedded health information exchange connectivity.
- AI-assisted denial prediction:Machine learning models trained on historical CMS rejection patterns are converging with robotic process automation to preempt appeals workflows.
Industry Challenges
- Certified EMS coder scarcity:ICD-10-PCS and ambulance-specific HCPCS expertise requires specialized training pipelines that community colleges and workforce programs have not scaled.
- Legacy ePCR integration friction:Electronic patient care reporting systems from the 2010s lack modern API architectures, forcing expensive middleware development for data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US EMS Billing Services Market |
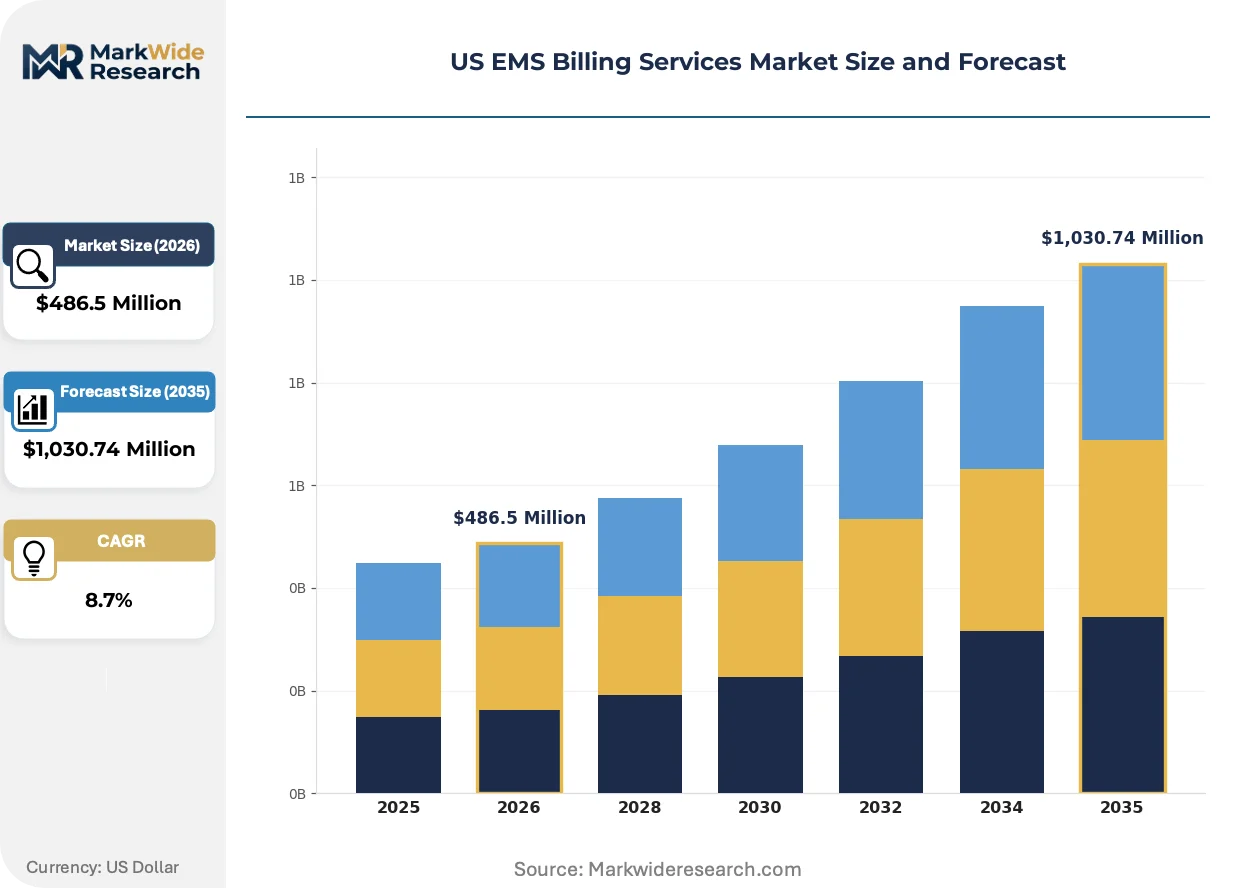
| Market Size in 2026 | $486.5 Million |
| Market Size in 2035 | $1,030.74 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Billing Model: Fee-for-Service, Capitation, Bundled Payments, Direct Billing End User: Ambulance Providers, Healthcare Systems, Private Practices, Government Agencies Service Type: Primary Billing, Secondary Billing, Claims Management, Payment Processing Technology: Cloud-Based Solutions, On-Premise Solutions, Mobile Apps, Integrated Platforms |
| Companies Covered | Change Healthcare, AIM EMS Software & Services, EMS Management & Consultants, Inc., Intermedix, Digitech, ESO, MP Cloud Technologies, Cvikota EMS, PCC Ambulance Billing Service, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US EMS Billing Services Market Trends and Innovations
Automation is penetrating claims management at the workflow layer, with predictive analytics replacing manual denial triage. Regulatory pressure on price transparency and data interoperability is synchronizing technology investment cycles across previously siloed ambulance operators.
Artificial intelligence applied to documentation completeness is rewriting how ambulance providers approach medical necessity justification. Fire departments and private operators in Texas and California are deploying natural language processing tools that flag insufficient run reports before submission, compressing denial rates and reducing appeals labor. This capability is enabling smaller agencies to achieve revenue cycle performance parity with large networked operators.
The No Surprises Act's good faith estimate requirements are mandating patient cost disclosures before emergency transport, altering operational workflows for ambulance dispatch and billing coordination. CMS enforcement of these transparency obligations is forcing platform upgrades that integrate real-time deductible tracking and out-of-network rate calculations. Urban and suburban ambulance providers in Florida are responding fastest, driven by higher volumes of commercially insured patients subject to balance billing protections.
Consolidated purchasing by regional ambulance networks is displacing fragmented vendor relationships that dominated the 2010s. Multi-county emergency service districts in California and Texas are issuing joint RFPs for end-to-end revenue cycle management, favoring platforms with unified coding, claims submission, and patient responsibility collection. This concentration is most visible in integrated healthcare systems where episode-based accountability is aligning ambulance billing with hospital revenue cycle timelines.
US EMS Billing Services Market Segmentation
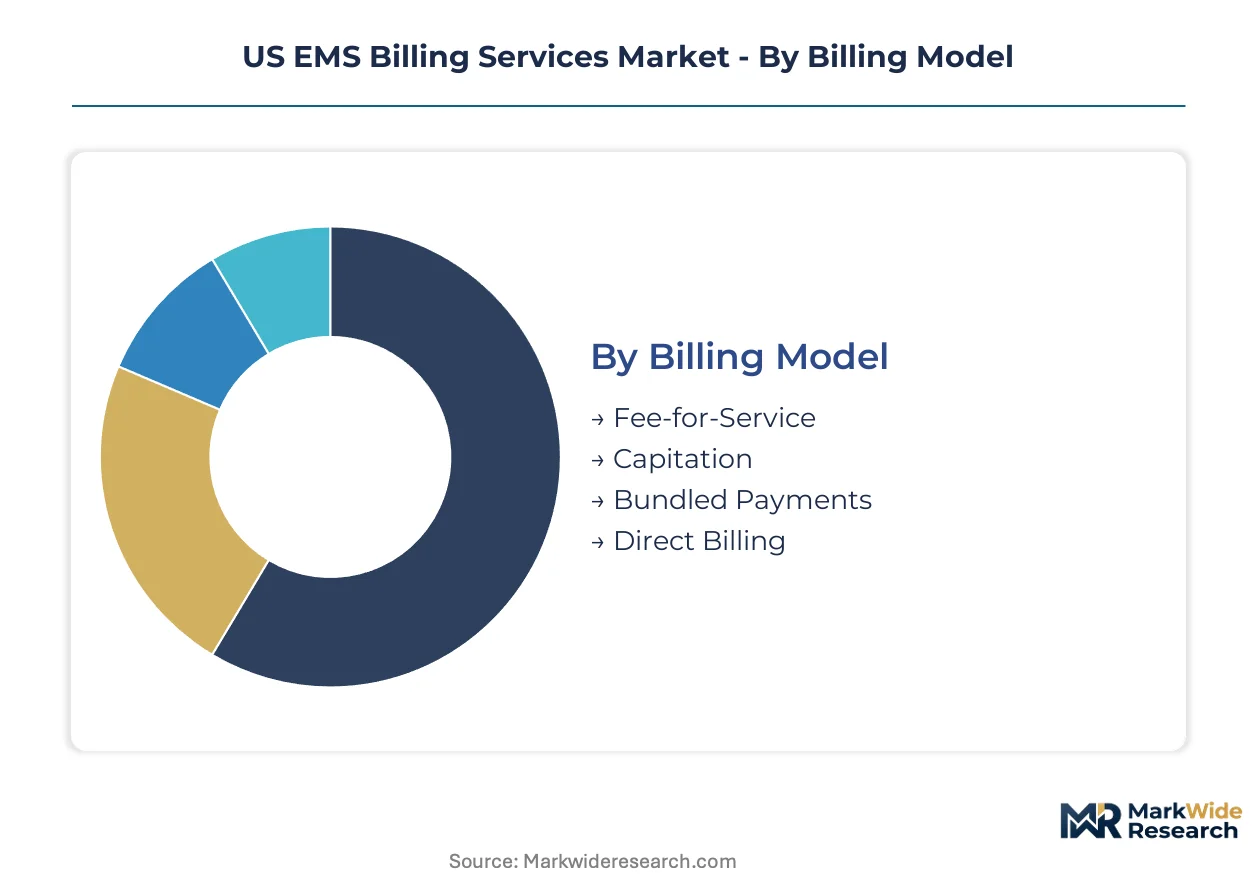
EMS billing services fragment across four structural dimensions that determine technology requirements, margin profiles, and regulatory exposure. Understanding these partitions clarifies where platform investments concentrate and which customer configurations drive sustainable revenue.
Billing Model:
Migration from legacy reimbursement structures toward episode-based accountability is compressing the competitive window for vendors lacking multi-model flexibility.
- Fee-for-Service:Dominant revenue mechanism where ambulance providers bill per transport using HCPCS Level II modifiers tied to CMS ambulance fee schedules. Texas and Florida municipal fire departments rely heavily on this model, though denial rates from documentation gaps erode net collections.
- Bundled Payments:Episode-based reimbursement aggregating ambulance transport with hospital admission costs. Integrated healthcare systems in California deploy this structure to align ambulance revenue cycle timelines with inpatient accountability metrics.
- Capitation:Fixed per-member-per-month payments requiring risk-adjusted coding sophistication. Medicare Advantage penetration in urban markets pulls demand for predictive utilization analytics.
- Direct Billing:Patient-responsible balance collection bypassing payer intermediaries. No Surprises Act transparency mandates force upfront cost estimate integration into dispatch workflows.
Volume placements concentrate in Fee-for-Service; the faster expansion belongs to Bundled Payments.
End User:
Customer-type stratification reveals divergent procurement authority and technical debt tolerance across the provider landscape.
- Ambulance Providers:Independent operators and networked private ambulance companies generating the core transaction volume. Rural districts in the Mountain West lack capital reserves for platform migration, constraining aggregate adoption velocity.
- Healthcare Systems:Hospital-owned ambulance services and integrated delivery networks consolidating revenue cycle functions. Large systems in California and Texas increasingly build captive billing teams, reducing outsourcing penetration.
- Private Practices:Physician-owned urgent care and occupational medicine clinics with occasional emergency transport billing needs. Lower transaction volumes favor lightweight, API-connected solutions over comprehensive platforms.
- Government Agencies:Municipal fire departments and county emergency service districts subject to public procurement cycles. Multi-county joint RFPs in Texas favor vendors with unified coding and patient responsibility collection modules.
Transaction density peaks with Ambulance Providers; margin expansion is steepest among Healthcare Systems.
Service Type:
Workflow decomposition shows disproportionate value capture in specialized functions requiring federal and state appeals expertise.
- Claims Management:End-to-end denial prevention and appeals navigation consuming specialized labor pools. Certified EMS coder scarcity—particularly ICD-10-PCS and ambulance-specific HCPCS expertise—elevates pricing power for vendors with trained staffing pipelines.
- Primary Billing:Initial claim submission and real-time eligibility verification forming the operational baseline. Cloud-native platforms automate prior authorization to compress transport-to-payment cycles for thin-margin operators.
- Secondary Billing:Coordination of benefits and supplemental payer pursuit after primary adjudication. Complex Medicaid fragmentation across state jurisdictions increases compliance overhead.
- Payment Processing:Patient responsibility collection and merchant services integration. No Surprises Act good faith estimate requirements mandate deductible tracking and out-of-network rate calculations before transport.
Revenue concentration sits with Claims Management; automation penetration is climbing fastest in Primary Billing.
Technology:
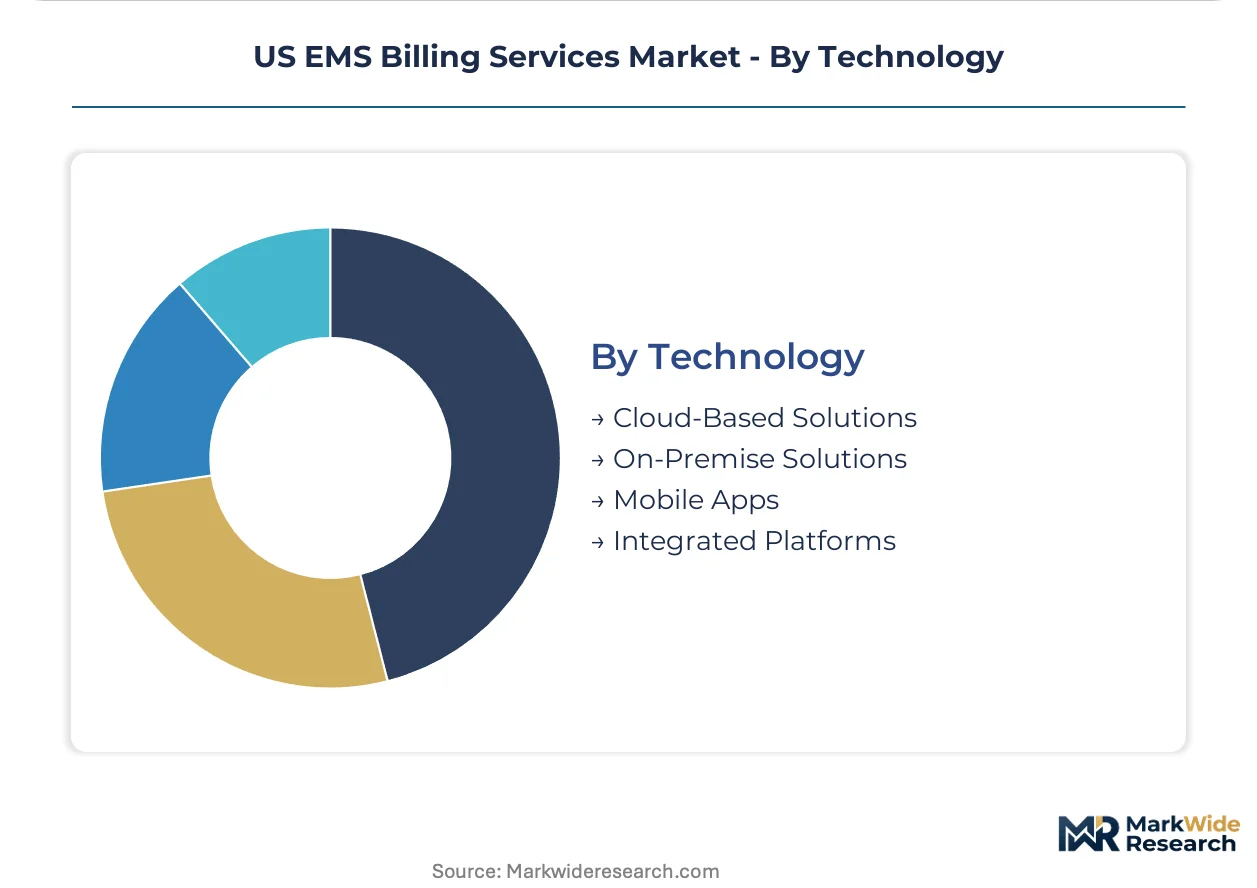
Infrastructure replacement cycles favor cloud architectures that synchronize with electronic patient care reporting and health information exchange mandates.
- Cloud-Based Solutions:Browser-accessible platforms with automatic CMS fee schedule updates and API-first interoperability. Fire departments abandon server-dependent legacy systems as HIPAA enforcement actions accelerate infrastructure replacement.
- Integrated Platforms:Unified revenue cycle modules embedding coding, claims submission, and patient collection. Legacy ePCR systems from the 2010s force expensive middleware development for data synchronization.
- On-Premise Solutions:Server-dependent installations retained by rural agencies with connectivity constraints. Capital requirements and maintenance burdens drive gradual displacement.
- Mobile Apps:Field-accessible documentation tools and real-time eligibility lookup. Natural language processing capabilities flag insufficient run reports before submission, compressing denial rates.
Deployment share tilts toward Cloud-Based Solutions; Integrated Platforms are gaining share fastest among multi-county emergency service districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas municipal fire departments anchor the US EMS billing services geography, where privatization waves and high call volumes concentrate vendor deployment. California and Florida follow as secondary demand poles, driven by integrated healthcare system consolidation and commercial payer density.
Texas
Multi-county emergency service districts in Texas generate outsized billing transaction volumes through municipal privatization contracts. State Medicaid prior authorization rules here remain less fragmented than coastal jurisdictions, reducing compliance overhead for platform vendors. Dallas-Fort Worth and Houston metro corridors host the densest ambulance operator clusters, where fire departments issue joint RFPs for unified revenue cycle management.
California
Integrated healthcare systems in California deploy bundled payment structures that align ambulance billing with hospital revenue cycle timelines. HIPAA enforcement actions from the Office for Civil Rights accelerate cloud platform migrations among Los Angeles and San Francisco Bay Area operators. Medicare Advantage penetration in urban markets pulls demand for risk-adjusted coding analytics and predictive utilization tools.
Florida
Commercial payer density in Florida drives rapid adoption of No Surprises Act compliance workflows, particularly around good faith estimate generation. Miami-Dade and Tampa Bay ambulance providers field higher volumes of commercially insured patients subject to balance billing protections. State Medicaid prior authorization requirements here create specialized appeals expertise demand that vendors capture through certified coder staffing.
New York
Volunteer and hybrid fire-EMS departments across upstate New York present greenfield deployment potential for cloud-native billing platforms. Municipal budget constraints in the Hudson Valley and Western New York slow capital migration from server-dependent legacy systems. New York City hospital-owned ambulance services increasingly build captive revenue cycle teams, reducing outsourcing penetration in the consolidated metro core.
Mountain West
Rural ambulance districts across Colorado, Utah, and Idaho lack billing infrastructure due to thin margins and connectivity constraints. Federal rural health clinic programs provide limited capital access for platform migration, constraining aggregate adoption velocity. Denver and Salt Lake City serve as regional hubs where vendors establish satellite operations to serve dispersed mountain and plains departments.
US EMS Billing Services Market Competitive Landscape
Global majors compete with regional champions across clearinghouse infrastructure and specialized compliance engine dimensions. The US EMS billing services market structures around three tiers: clearinghouse-anchored platforms with national reach, ePCR-integrated specialists with workflow depth, and compliance-focused boutiques with Medicare Part B expertise. Consolidation pressure favors vendors with unified coding, claims submission, and patient responsibility collection modules. M&A activity targets regional billing services with established municipal fire department relationships, while technology licensing deals embed prior authorization automation into legacy dispatch systems.
Within the clearinghouse-anchored tier, Change Healthcare occupies a position exemplifying infrastructure scale advantages. ESO and Digitech represent contrasting specialization archetypes—ESO anchoring ePCR integration depth, Digitech occupying Medicare fee schedule compliance expertise. These three companies collectively illustrate how vendor positioning fragments across workflow layer versus regulatory layer competitive advantages.
| Leading Market Players |
|---|
| Change Healthcare |
| AIM EMS Software & Services |
| EMS Management & Consultants, Inc. |
| Intermedix |
| Digitech |
| ESO |
| MP Cloud Technologies |
| Cvikota EMS |
| PCC Ambulance Billing Service |
| Others |
Pricing and Supply Chain Analysis
HIPAA compliance mandates and the No Surprises Act's transparency obligations gate qualified supply access and premium-tier pricing power for EMS billing vendors, forcing municipal fire departments and private ambulance operators toward certified platforms while marginalizing uncertified competitors.
Pricing Analysis
Warranty and service-bundling structures differentiate EMS billing vendor tiers, with premium subscriptions embedding dedicated appeals support and real-time eligibility APIs while economy tiers unbundle compliance updates and patient collection modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and coding specialist staffing, with Change Healthcare and ESO commanding brand premiums for clearinghouse infrastructure and ePCR integration. Cost compression in the standard tier intensifies as cloud-native entrants automate prior authorization workflows, squeezing legacy server-dependent vendors. Rural ambulance districts and volunteer fire departments in the Mountain West exhibit highest price sensitivity, while integrated California healthcare systems prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Certified EMS coder supply rests on fragmented US community college training pipelines and specialized workforce development programs that have failed to scale ICD-10-PCS and ambulance-specific HCPCS expertise. Cloud infrastructure draws from hyperscaler data centers concentrated in Virginia, Texas, and California, while legacy ePCR system maintenance hinges on aging middleware vendors in the Midwest and Southeast. Single-source vulnerability permeates the certified coder labor pool, where specialized expertise concentrates among a handful of billing services with established training academies. Distribution runs through direct enterprise sales to municipal procurement departments and multi-county joint RFPs, with regional implementation partners serving dispersed rural districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US EMS billing services market functions as a cost-of-compliance story where the No Surprises Act's good faith estimate mandates erect barrier-to-entry moats favoring vendors with embedded transparency automation and certified coding pipelines.
For Market Incumbents: Cement clearinghouse infrastructure advantages by acquiring regional billing services with established municipal fire department relationships in Texas and Florida, while embedding AI-assisted denial prediction to preempt appeals workflows. Cloud-native entrants automating prior authorization pose substitution threats; defend through vertical integration into ePCR systems and real-time eligibility APIs that compress transport-to-payment cycles for thin-margin operators. For New Entrants and Emerging Players: Capture greenfield deployment potential among rural ambulance districts across the Mountain West and Great Plains, where volunteer and hybrid fire-EMS departments lack billing infrastructure and capital reserves for platform migration. Municipal privatization waves in secondary Texas metros and upstate New York counties represent the most penetrable geography. A compliance-first go-to-market angle emphasizing No Surprises Act workflow automation differentiates against legacy vendors burdened by technical debt. For Investors and Strategic Acquirers: CMS proposed rules on ground ambulance data collection is the leading indicator that regulatory complexity will deepen competitive moats for compliant platforms over the next decade. Target acquisition archetypes include regional billing services with certified coder staffing pipelines and established municipal relationships in high-call-volume states. Watch HIPAA enforcement actions from the Office for Civil Rights as the inflection signal accelerating cloud platform migrations and infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies coding, claims submission, and patient collection modules for multi-county emergency service districts. |
| Acquisition of Specialist Firm | Captures certified EMS coder pipelines and municipal fire department relationships in Texas and Florida corridors. |
| Product Launch | Deploys AI-assisted denial prediction trained on historical CMS rejection patterns to preempt appeals workflows. |
| Strategic Partnership | Embeds prior authorization automation into legacy dispatch systems through technology licensing arrangements. |
| Geographic Expansion | Establishes satellite operations in Denver and Salt Lake City to serve dispersed Mountain West rural districts. |
Research Methodology
Document review covered CMS Medicare claims data, HIPAA enforcement action records, and state Medicaid prior authorization rule filings, complemented by interviews with revenue cycle executives at ambulance providers, municipal fire department procurement officers, and certified EMS coding specialists. Secondary validation drew from SEC filings of publicly traded healthcare IT vendors, GPO contract databases, and hospital procurement records. Bottom-up transaction modeling triangulated against top-down market sizing from payer enrollment and ambulance transport volume data.
Cross-referencing historical Medicare fee schedule updates against panel input from billing service operators informed the analytical framework across the projection horizon. Segmentation dimensions modeled include billing model type, end-user configuration, service type workflow, and technology deployment architecture. CAGRs were derived from trend extrapolation of municipal privatization rates, cloud platform adoption curves, and regulatory compliance investment cycles. Forecast inputs incorporated ambulance call volume projections and Medicare Advantage penetration patterns by metropolitan statistical area.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS rulemaking on ground ambulance data collection, state Medicaid prior authorization fragmentation, and certified coder workforce expansion. Assumptions underlying projections reflect documented regulatory trajectories and technology adoption patterns rather than speculative discontinuities. A small set of named triggers—HIPAA enforcement intensity, No Surprises Act implementation guidance, and TEFCA interoperability mandate timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Global Ambulance Market