
 India Telehealth Services Market | 2026-2036
India Telehealth Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Telehealth Services Market Insights
The capital-intensity divergence between well-funded hospital-linked platforms and standalone app operators is collapsing as cloud infrastructure costs drop and API-based telehealth stacks commoditize. Apollo TeleHealth Services leverages its captive hospital network to sustain end-to-end care continuity across tier-2 cities. Tata 1mg Healthcare Solutions anchors consumer trust through integrated pharmacy fulfillment and diagnostic booking. Practo Technologies competes on SaaS penetration into clinic management systems.
Telehealth services encompass real-time clinical consultation, asynchronous store-and-forward diagnostics, and remote physiological monitoring delivered through encrypted digital channels, typically requiring HL7 FHIR interoperability and sub-200ms latency for synchronous video. These systems extend primary care access to underserved populations while reducing facility congestion. Consultation services dominate current transaction volumes, yet AI Diagnostics within mobile-based delivery captures expanding margin pools as algorithmic triage reduces physician time per case. Remote monitoring is maturing fastest among post-operative cardiac and diabetes cohorts, though emergency services remain structurally constrained by ambulance integration gaps.
CDSCO governs software-as-medical-device classifications for AI diagnostic outputs, while the Ministry of Health and Family Welfare operationalizes telemedicine practice guidelines that standardize consent protocols and prescription validity. BIS certification requirements for connected health devices further shape hardware-linked service deployment. Stakeholders must monitor whether the Digital Information Security in Healthcare Act tightens data-localization obligations enough to force infrastructure reinvestment.
Market Dynamics
The Ayushman Bharat Digital Mission is collapsing the urban-rural care divide by mandating interoperable health records and subsidizing last-mile connectivity for virtual consultations.
Growth Catalysts
- CDSCO software-as-medical-device pathway:Streamlined classification for AI diagnostic algorithms accelerates deployment of mobile-based triage tools in outpatient settings.
- Rural outpatient demand:Government-subsidized internet infrastructure and Jan Aushadhi pharmacy networks extend telehealth reach into tier-3 towns and village clusters.
- Cloud API commoditization:Open-source telehealth stacks reduce platform development costs, enabling standalone operators to match hospital-linked service quality.
Market Restraints
- Data-localization hardware costs:Proposed Digital Information Security in Healthcare Act obligations would force server infrastructure reinvestment, compressing margins for cash-constrained operators.
- Diagnostic device certification lag:BIS testing timelines for connected glucose monitors and ECG wearables delay remote monitoring rollouts by 8-14 months.
- Physician supply concentration:Specialist density remains skewed toward Maharashtra, Karnataka, and Tamil Nadu, limiting synchronous consultation quality in eastern and northeastern states.
Strategic Opportunities
- Post-operative cardiac monitoring:Remote physiological monitoring protocols for bypass and stent patients create recurring revenue streams outside acute hospital stays.
- PLI scheme for medical electronics:Production-linked incentives for domestic wearable manufacturing reduce import dependency and enable cost-competitive subscription pricing.
- Asynchronous store-and-forward dermatology:Image-based consultation models bypass real-time physician constraints, unlocking demand in skin-care and chronic wound management.
Industry Challenges
- HL7 FHIR interoperability talent:Shortage of engineers capable of implementing health data exchange standards slows platform integration with public hospital systems.
- Ambulance-dispatch protocol gaps:Emergency telehealth services remain structurally constrained by absent real-time coordination with 108 emergency response networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Telehealth Services Market |
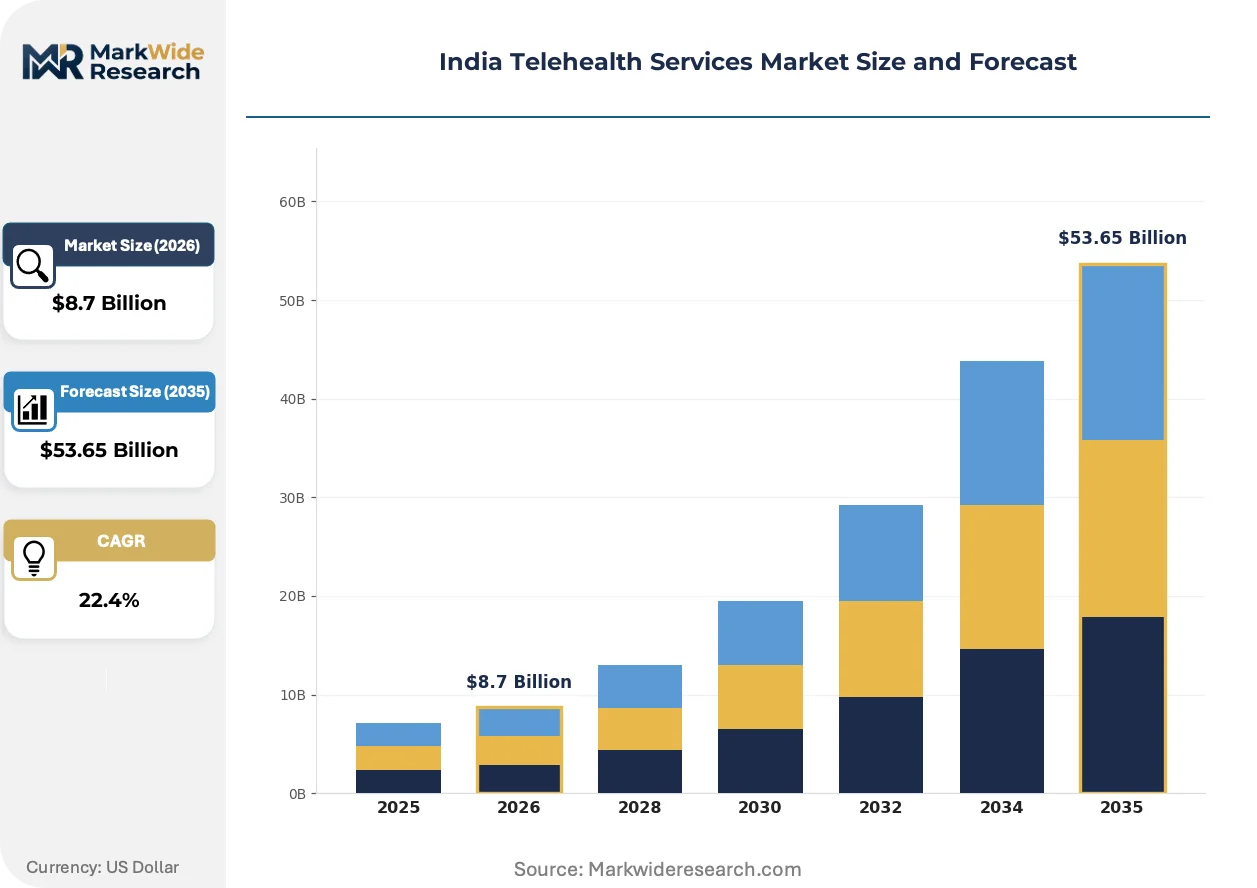
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation Services, Remote Monitoring, Emergency Services, Follow-up Care Technology: Video Conferencing, Mobile Apps, Chatbots, AI Diagnostics End User: Patients, Healthcare Providers, Insurance Companies, Corporates Delivery Mode: Web-Based, Mobile-Based, Offline Support, Hybrid Model |
| Companies Covered | Practo Technologies, Apollo TeleHealth Services, Tata 1mg Healthcare Solutions, MediBuddy, MFine, Portea Medical, Netmeds Marketplace, Lybrate India, CallHealth Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Telehealth Services Market Trends and Innovations
Algorithmic triage and edge-computing diagnostics are compressing physician time per case while expanding serviceable patient volumes beyond traditional clinic capacity constraints.
Portable ECG and pulse-oximetry sensors integrated with smartphone cameras are miniaturizing diagnostic hardware into sub-50-gram form factors. Cardiology and diabetology clinics in tier-2 cities are adopting these kits for home-visit extensions. The technology is miniaturizing the physical footprint required for credible remote monitoring, enabling subscription models that bypass capital-intensive clinic buildouts.
CDSCO's 2023 software-as-medical-device notification requires algorithmic transparency documentation for AI diagnostic outputs. Diagnostic platform operators must now submit training dataset provenance and bias audit reports. Maharashtra and Karnataka-based developers are responding by establishing captive clinical validation partnerships with medical colleges to preempt regulatory rejection.
Patients in tier-2 and tier-3 cities are bypassing general practitioner referrals entirely, booking direct specialist consultations through mobile apps. This channel disintermediation fragments traditional primary care gatekeeping and concentrates demand on cardiology, dermatology, and endocrinology verticals. The pattern is most visible in Gujarat and Rajasthan, where pharmacy-anchored platforms bundle diagnostic booking with medication delivery.
India Telehealth Services Market Segmentation
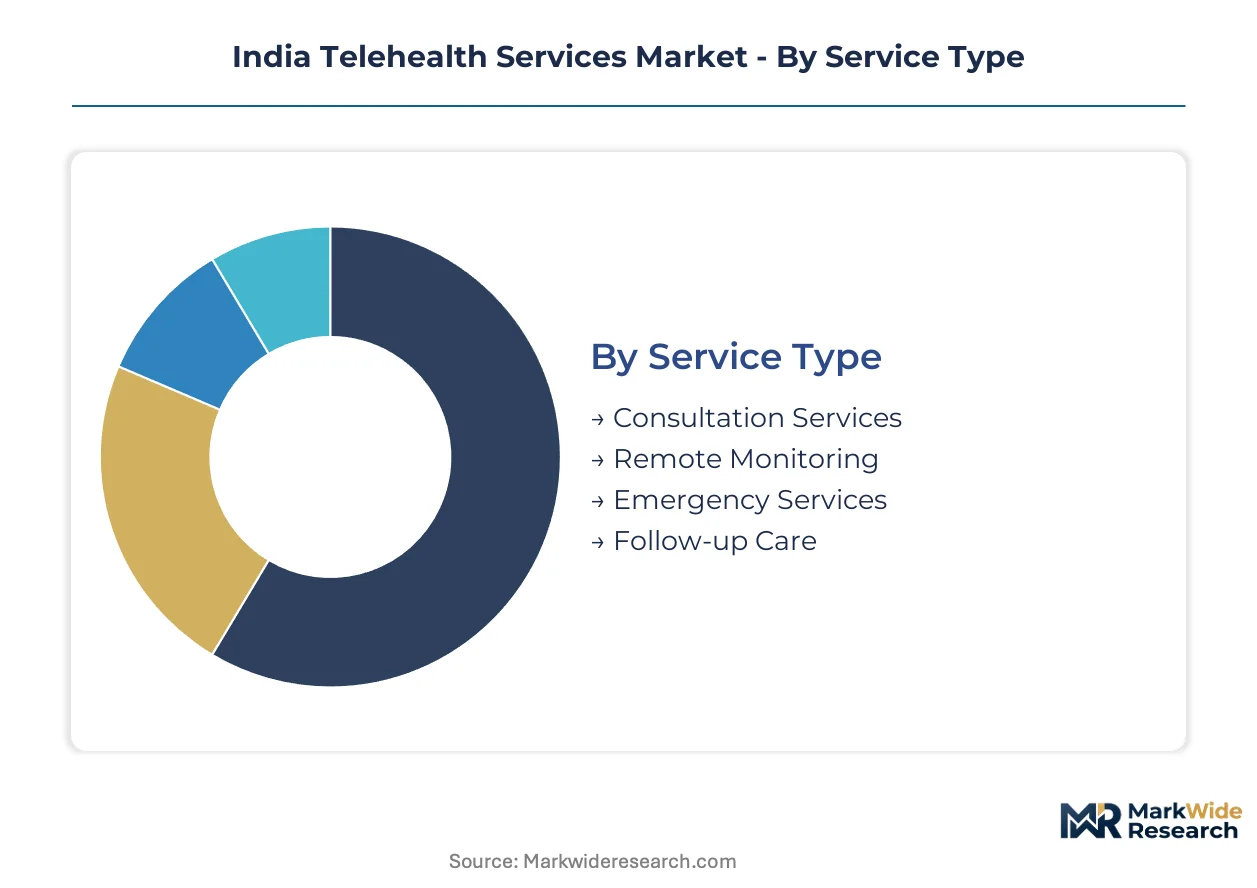
Segmentation in Indian telehealth reveals how regulatory pathways, infrastructure maturity, and payment flows concentrate value across distinct service configurations. Understanding these divisions exposes where CDSCO classifications, BIS hardware mandates, and Ayushman Bharat interoperability requirements create divergent margin structures and competitive barriers.
Service Type:
CDSCO's software-as-medical-device pathway applies unevenly across service categories, with diagnostic-adjacent offerings facing stricter algorithmic transparency requirements than pure consultation models.
- Consultation Services:Real-time synchronous video and audio encounters between physicians and patients, typically requiring sub-200ms latency for clinical credibility. Maharashtra and Karnataka dominate transaction volumes due to specialist physician concentration, though tier-3 town penetration accelerates through government-subsidized connectivity.
- Remote Monitoring:Continuous physiological data transmission from wearable devices for post-operative cardiac and diabetes cohorts, generating recurring subscription revenue outside acute care episodes. CDSCO's 2023 notification demands training dataset documentation for AI-interpreted outputs, extending BIS certification timelines for connected glucose monitors and ECG wearables by 8-14 months.
- Emergency Services:Real-time triage and coordination for acute episodes, structurally constrained by absent integration with 108 ambulance dispatch networks.
- Follow-up Care:Scheduled post-discharge check-ins and medication adherence monitoring, predominantly asynchronous to optimize physician time allocation.
Established volume favors Consultation Services; emerging adoption favors Remote Monitoring.
Technology:
Cost tier differentiation separates capital-intensive video infrastructure from lightweight mobile deployments, with API commoditization collapsing development cost gaps between enterprise and standalone operators.
- Video Conferencing:HIPAA-grade encrypted synchronous platforms requiring dedicated bandwidth provisioning and HL7 FHIR interoperability for hospital system integration. Tier-2 city clinics favor this mode for specialist access, though engineer scarcity for health data exchange standards slows public hospital deployment.
- Mobile Apps:Smartphone-native delivery concentrating demand in Gujarat and Rajasthan through pharmacy-anchored platforms bundling diagnostic booking with Jan Aushadhi medication fulfillment. Algorithmic triage capabilities embedded here capture expanding margin pools as physician time per case compresses.
- Chatbots:NLP-based preliminary symptom collection and appointment routing, operating below CDSCO medical device thresholds.
- AI Diagnostics:Algorithmic image interpretation and risk stratification, requiring CDSCO software-as-medical-device registration with bias audit submission.
Volume leadership sits with Mobile Apps; steepest expansion trajectory belongs to AI Diagnostics.
End User:
Payment source fragmentation creates distinct service specifications, with corporate and insurance channels demanding outcome documentation that patient-direct models often bypass.
- Patients:Direct-to-consumer bookings bypassing traditional primary care gatekeeping, channeling demand toward cardiology, dermatology, and endocrinology verticals through tier-2 and tier-3 city smartphone penetration.
- Healthcare Providers:Clinic management system integration and SaaS-based practice tools, competing on physician workflow efficiency rather than patient acquisition.
- Insurance Companies:Utilization management and pre-authorization platforms requiring claims data interoperability with Ayushman Bharat Digital Mission health records.
- Corporates:Occupational health screening and employee wellness programs, typically bundled with annual health checkup mandates.
Transaction density concentrates in Patients; contract value expansion favors Insurance Companies.
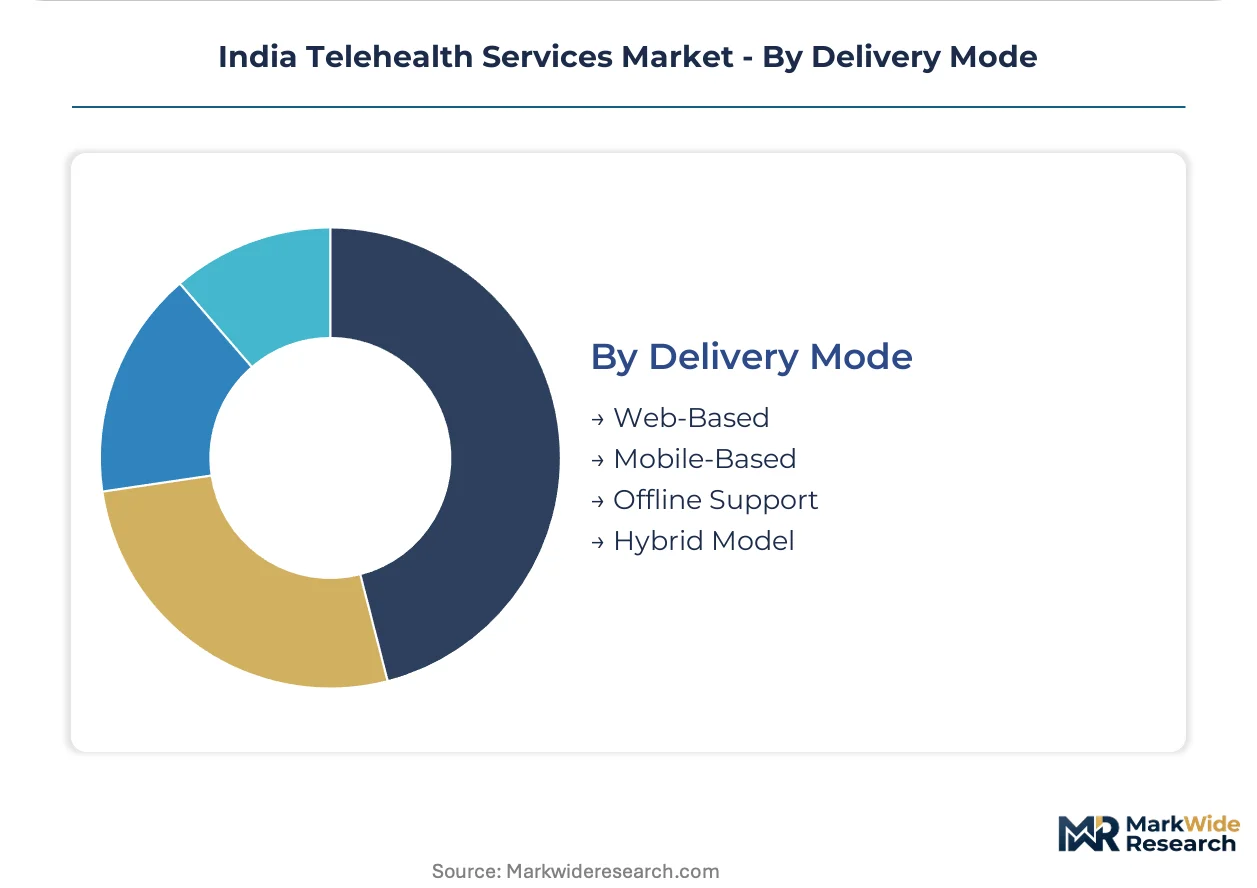
Delivery Mode:
Geography determines infrastructure feasibility, with last-mile connectivity gaps in eastern and northeastern states preserving offline dependencies that hybrid architectures must accommodate.
- Web-Based:Browser-accessible platforms optimized for desktop clinic environments and formal healthcare settings requiring EMR integration. Urban hospital-linked operators sustain this channel for care continuity across their captive networks.
- Mobile-Based:Smartphone-first delivery capturing rural outpatient demand through the Ayushman Bharat Digital Mission's subsidized connectivity mandates, with AI Diagnostics modules concentrating developer activity in Maharashtra and Karnataka.
- Offline Support:Telephone-based and assisted-digital services for populations with limited smartphone penetration or digital literacy.
- Hybrid Model:Synchronous-digital combined with physical diagnostic collection through home visits or pharmacy partnerships, miniaturizing into sub-50-gram portable ECG and pulse-oximetry kits for tier-2 city cardiology extensions.
Current penetration peaks with Mobile-Based; infrastructure resilience drives Hybrid Model investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telehealth consumption patterns diverge sharply across Indian states, with western and southern regions leveraging mobile-first specialist access while eastern and northeastern markets remain tethered to assisted-digital and hybrid delivery models due to connectivity gaps.
Maharashtra
Specialist physician density and venture capital concentration make Maharashtra the epicenter of AI diagnostic development. CDSCO's software-as-medical-device notification drives Mumbai and Pune-based developers to establish captive clinical validation partnerships with medical colleges. The state's tier-2 cities witness rapid adoption of portable ECG and pulse-oximetry kits for cardiology home visits.
Karnataka
Bengaluru's technology ecosystem anchors algorithmic triage innovation, with developers concentrating on mobile-based dermatology and endocrinology verticals. The state's engineering talent pool enables HL7 FHIR interoperability implementations for hospital-linked platforms. Karnataka's Jan Aushadhi pharmacy network density supports diagnostic-booking bundling in tier-3 towns.
Gujarat
Pharmacy-anchored platform penetration runs deepest here, with patients bypassing general practitioner referrals for direct specialist bookings. The state's pharmaceutical distribution infrastructure enables cost-competitive subscription pricing for chronic disease management. Ahmedabad and Surat emerge as testing grounds for asynchronous store-and-forward consultation models.
Tamil Nadu
Public hospital system integration advances fastest in this state, with the Ayushman Bharat Digital Mission driving interoperable health record deployment. Chennai's medical college network supplies clinical validation partnerships for CDSCO-bound algorithmic transparency documentation. Post-operative cardiac monitoring protocols gain traction among bypass and stent patient cohorts.
West Bengal
Eastern market constraints preserve hybrid delivery dependencies, with telephone-based assisted-digital services filling smartphone penetration gaps. Kolkata's specialist concentration cannot offset physician supply shortages in surrounding districts. The state illustrates the structural limits of synchronous consultation quality where infrastructure lags behind platform availability.
India Telehealth Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital-linked platforms leveraging captive networks for care continuity while standalone operators compete on SaaS penetration and pharmacy fulfillment integration. The market structure stratifies across three archetypes: integrated hospital systems, pharmacy-anchored consumer platforms, and clinic management SaaS specialists. Dominant competitive moves include cloud API commoditization collapsing development cost gaps, and strategic partnerships with Jan Aushadhi networks for last-mile medication delivery.
Among hospital-linked integrated operators, Apollo TeleHealth Services exemplifies the captive network archetype through end-to-end care continuity across tier-2 cities. Tata 1mg Healthcare Solutions anchors the pharmacy-fulfillment tier, occupying a position where diagnostic booking bundling generates consumer trust. Practo Technologies sits within the SaaS specialist segment, representing clinic management system penetration rather than patient acquisition competition.
| Leading Market Players |
|---|
| Practo Technologies |
| Apollo TeleHealth Services |
| Tata 1mg Healthcare Solutions |
| MediBuddy |
| MFine |
| Portea Medical |
| Netmeds Marketplace |
| Lybrate India |
| CallHealth Services |
| Others |
Pricing and Supply Chain Analysis
CDSCO software-as-medical-device classification gates both platform qualification and subscription tier differentiation, forcing developers to absorb clinical validation costs that stratify market entry barriers and price positioning simultaneously.
Pricing Analysis
Long-term subscription contracts dominate enterprise hospital-linked platforms while per-consultation transactional pricing prevails among standalone mobile operators. Three-tier pricing structure across premium, standard, and economy levels separates Apollo TeleHealth's captive network bundles from Tata 1mg's pharmacy-integrated diagnostics and Practo's SaaS clinic tools. Cost compression in standalone app tiers is intensifying because cloud API commoditization collapses development cost gaps. Tier-3 rural patients exhibit highest price sensitivity; corporate occupational health buyers demonstrate lowest.
Supply Chain Analysis
India anchors domestic telehealth platform development while China and Taiwan supply semiconductor components for connected diagnostic hardware. Cloud infrastructure draws from AWS, Azure, and domestic data center operators; portable ECG sensors and pulse-oximetry modules source from Shenzhen manufacturing clusters. Single-source vulnerability concentrates in AI training chip procurement for algorithmic triage tools. Distribution runs through Jan Aushadhi pharmacy networks for medication fulfillment and hospital system EMR integrations for care continuity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India Telehealth Services Market sits in early-cycle expansion as Ayushman Bharat Digital Mission subsidies collapse urban-rural connectivity barriers and accelerate virtual consultation penetration into tier-3 towns.
For Market Incumbents: Compound defensive moats by deepening captive hospital network integrations to lock in care continuity workflows against standalone app disintermediation. Accelerate CDSCO software-as-medical-device certification pipelines for AI diagnostic modules to preempt regulatory rejection and sustain margin pools from algorithmic triage. Prioritize backward integration into Jan Aushadhi pharmacy fulfillment networks to control last-mile medication delivery costs. For New Entrants and Emerging Players: CDSCO's streamlined software-as-medical-device fast-track unlocks white-space entry through asynchronous store-and-forward dermatology and chronic wound management verticals. Target eastern and northeastern states where physician supply concentration gaps limit synchronous consultation quality and hybrid assisted-digital models retain necessity. Pursue pharmacy-anchored go-to-market partnerships bundling diagnostic booking with Jan Aushadhi medication delivery. For Investors and Strategic Acquirers: Digital Information Security in Healthcare Act passage reshapes the acquisition landscape by forcing server infrastructure reinvestment that will consolidate cash-constrained operators. Favor targets with established clinical validation partnerships and captive health data repositories over pure technology plays. Watch BIS certification timeline compression for connected glucose monitors and ECG wearables as inflection signal for remote monitoring subscription scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Software-as-Medical-Device Registration | Algorithmic transparency documentation unlocks AI diagnostic revenue pools in Maharashtra and Karnataka. |
| Jan Aushadhi Pharmacy Network Partnership | Last-mile medication fulfillment integration anchors consumer trust in Gujarat and Rajasthan markets. |
| HL7 FHIR Interoperability Implementation | Hospital system data exchange capability secures enterprise contracts with public health infrastructure. |
| Portable Diagnostic Hardware Miniaturization | Sub-50-gram ECG and pulse-oximetry kits enable tier-2 city cardiology home-visit extensions. |
| Post-Operative Cardiac Monitoring Protocol | Bypass and stent patient cohorts generate recurring subscription revenue outside acute hospital stays. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with telehealth platform executives, hospital CIOs, CDSCO regulatory affairs leads, and Jan Aushadhi network coordinators; and secondary validation against BIS certification databases, CDSCO software-as-medical-device filings, Ayushman Bharat Digital Mission interoperability documentation, and hospital procurement records. Bottom-up triangulation cross-checked platform transaction volumes against top-down addressable population estimates.
Across the analysis window, forecasting modeled service type segmentation, technology deployment modes, end-user payment sources, and delivery mode geography. CAGRs derived from penetration rate trajectories in tier-2 and tier-3 towns, physician supply concentration patterns, and cloud infrastructure cost curves. Industry-specific inputs incorporated CDSCO regulatory pathway velocity and BIS hardware certification timelines.
Underlying assumptions cover Ayushman Bharat subsidy continuity, CDSCO algorithmic transparency enforcement consistency, and rural connectivity infrastructure buildout pace, with deviation risk concentrated in Digital Information Security in Healthcare Act data-localization obligations and eastern state physician supply constraints. Recalibration cycles align with material shifts in regulatory enforcement intensity and public health record interoperability deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Tele-ICU Services Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
US Virtual Care Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Remote Healthcare Market
Telemedicine
Teledermatology Market