
 Telehealth Kiosk Market | 2026-2036
Telehealth Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Telehealth Kiosk Market Outlook
A shortage of certified telehealth technicians is rotating deployment priorities toward vendors with integrated training ecosystems. Advantech Co., Ltd. leverages its industrial computing heritage to dominate embedded hardware supply for kiosk OEMs. Olea Kiosks specializes in ADA-compliant enclosure design, a capability that sustains its position in municipal health contracts. Clinics On Cloud navigates software-hardware integration challenges that constrain smaller competitors.
Telehealth kiosks are self-service terminal systems integrating biometric sensors, video consultation modules, and diagnostic peripherals for remote clinical encounters, typically housed in weatherized enclosures with antimicrobial surfaces. These units process patient intake, capture vital signs, and facilitate real-time physician interaction in settings lacking full-time medical staff. Standalone kiosks lead volume deployment due to their minimal infrastructure requirements and rapid site activation. Integrated kiosks command premium positioning where health systems seek unified EHR connectivity and payment processing. Portable kiosks represent the fastest-expanding configuration as mobile health units and disaster response agencies prioritize field-deployable diagnostic capacity.
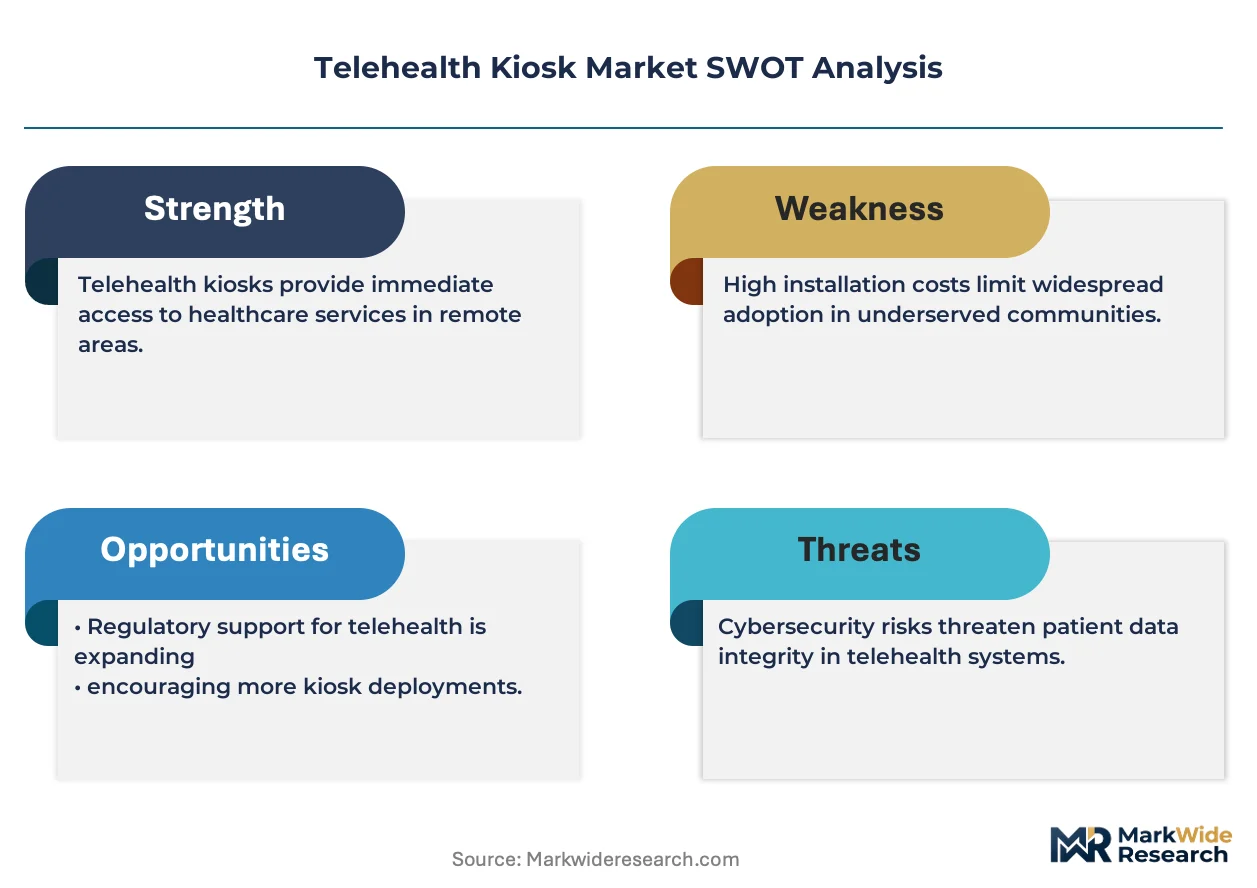
FDA 510(k) clearance pathways and HIPAA security standards shape hardware design mandates and software architecture decisions for kiosk manufacturers seeking hospital procurement channels. CMS remote patient monitoring reimbursement codes influence end-user willingness to invest in biometric-enabled units over basic video terminals. Stakeholders must weigh FDA compliance timelines against state-level telehealth parity laws that expand addressable clinic footprints without uniform reimbursement guarantees.
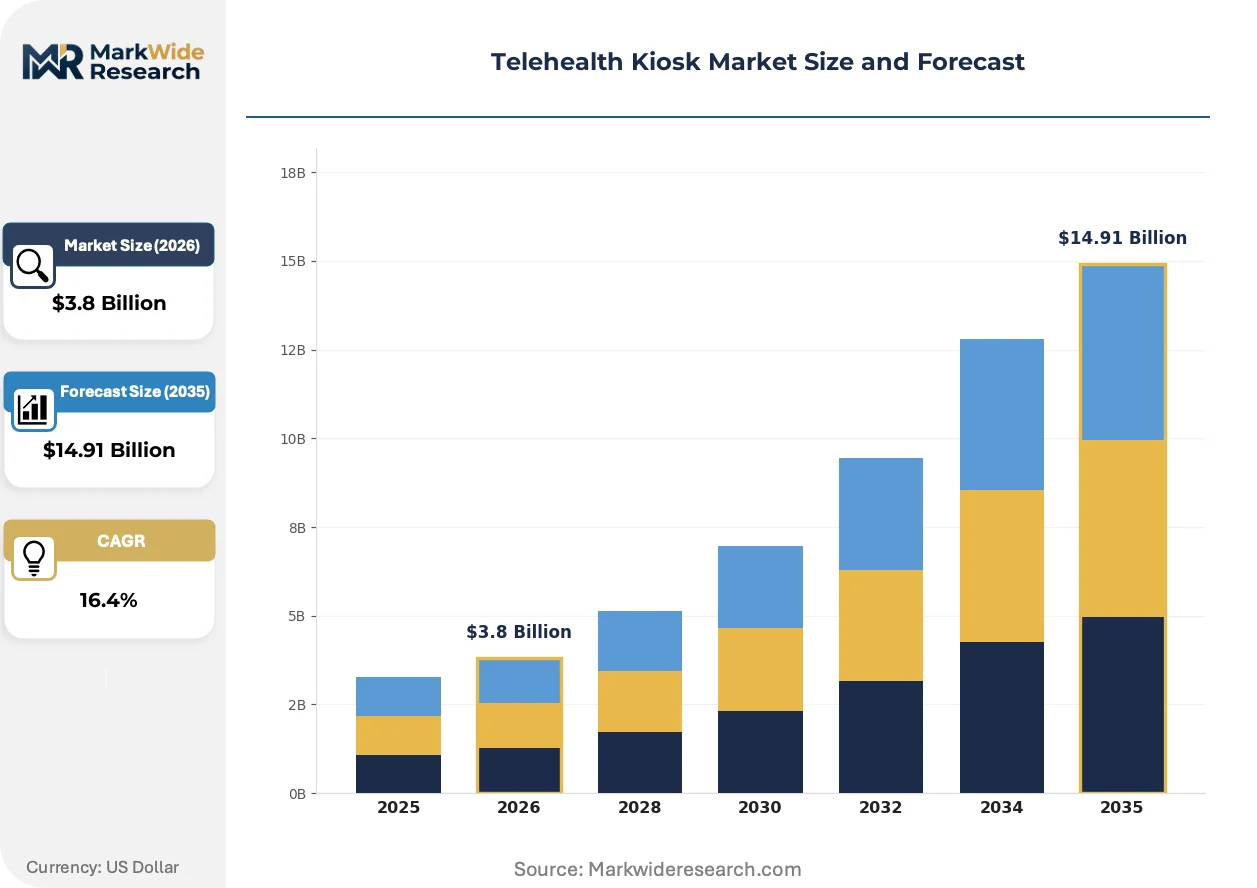
Market Dynamics
CMS remote patient monitoring reimbursement codes are restructuring hospital procurement priorities, tilting capital allocation toward biometric-enabled units over basic video terminals and compressing vendor qualification timelines.
Growth Catalysts
- Rural health system expansion:Community health centers in underserved counties are deploying self-service diagnostic access to offset physician shortages. Federal rural health clinic funding accelerates site activation.
- FDA 510(k) pathway maturation:Clearance precedents for integrated vital sign capture modules reduce regulatory uncertainty for kiosk OEMs. Hardware design mandates now embed HIPAA security standards by default.
- Biometric sensor convergence:Multi-parameter patient intake systems process blood pressure, pulse oximetry, and temperature in single encounters. Real-time data streams enable synchronous physician decision-making.
Market Restraints
- Certified technician scarcity:Deployment velocity constrains to vendors with integrated training ecosystems. Health systems face onboarding bottlenecks for field maintenance staff.
- Component supply concentration:Embedded computing boards and medical-grade displays cluster among East Asian contract manufacturers. Geopolitical friction elevates lead time volatility.
- Reimbursement fragmentation:State-level telehealth parity laws expand addressable clinic footprints without uniform payment guarantees. Buyers confront variable ROI calculations across jurisdictions.
Strategic Opportunities
- Disaster response procurement:Mobile health units and emergency management agencies prioritize field-deployable diagnostic capacity. Portable configurations command premium positioning in federal contingency contracts.
- Pharmacy chain anchor tenancy:Retail health networks seek rapid site activation with minimal infrastructure requirements. Standalone kiosks enable patient intake without construction permits.
- ADA-compliant municipal contracts:Accessible enclosure design capabilities unlock public sector procurement channels. Weatherized antimicrobial surfaces meet durability specifications for outdoor placement.
Industry Challenges
- EHR integration complexity:Unified connectivity and payment processing requirements strain smaller software-hardware integrators. Health systems demand seamless data exchange with existing clinical workflows.
- Antimicrobial surface certification:Medical-grade material validation timelines extend hardware development cycles. Manufacturers must balance durability claims against EPA registration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehealth Kiosk Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Kiosk, Integrated Kiosk, Portable Kiosk, Wall-mounted Kiosk End User: Hospitals, Clinics, Ambulance Services, Retail Pharmacies Technology: Video Conferencing, Remote Monitoring, AI Diagnostics, Biometric Access Service Type: Consultation Services, Health Screening, Prescription Services, Chronic Care Management |
| Companies Covered | RedyRef Interactive Kiosks, Advantech Co., Ltd., Clinics On Cloud, Fabcon, Clearwave Corporation, Olea Kiosks, KIOSK Information Systems, Frank Mayer and Associates, Meridian Kiosks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehealth Kiosk Market Strategic Shifts
Deployment economics are pivoting toward integrated training ecosystems and rapid site activation models, compressing traditional vendor qualification cycles and elevating hardware-software convergence as a procurement differentiator.
Edge computing architectures are fragmenting traditional kiosk data processing models. Biometric sensor arrays now execute initial vital sign analysis locally before cloud transmission. Rural health systems and mobile health units adopt these distributed systems to reduce bandwidth dependency. The shift compresses reliance on continuous connectivity and enables diagnostic functionality in network-constrained environments.
CMS reimbursement code expansions for remote patient monitoring are restructuring capital allocation priorities. Hospital procurement committees now weight biometric-enabled units against basic video terminals in budget cycles. Integrated kiosk configurations capture premium positioning where health systems seek unified EHR connectivity. FDA 510(k) clearance timelines increasingly determine vendor shortlist composition.
Self-service diagnostic access is displacing traditional scheduled appointment models in pharmacy and retail health settings. Pharmacy chains anchor kiosk rollout programs with minimal infrastructure requirements and rapid deployment timelines. Community health centers in underserved areas replicate this procurement pattern. The United States concentrates this demand rotation, with municipal health contracts following retail channel precedent.
Telehealth Kiosk Market Segmentation
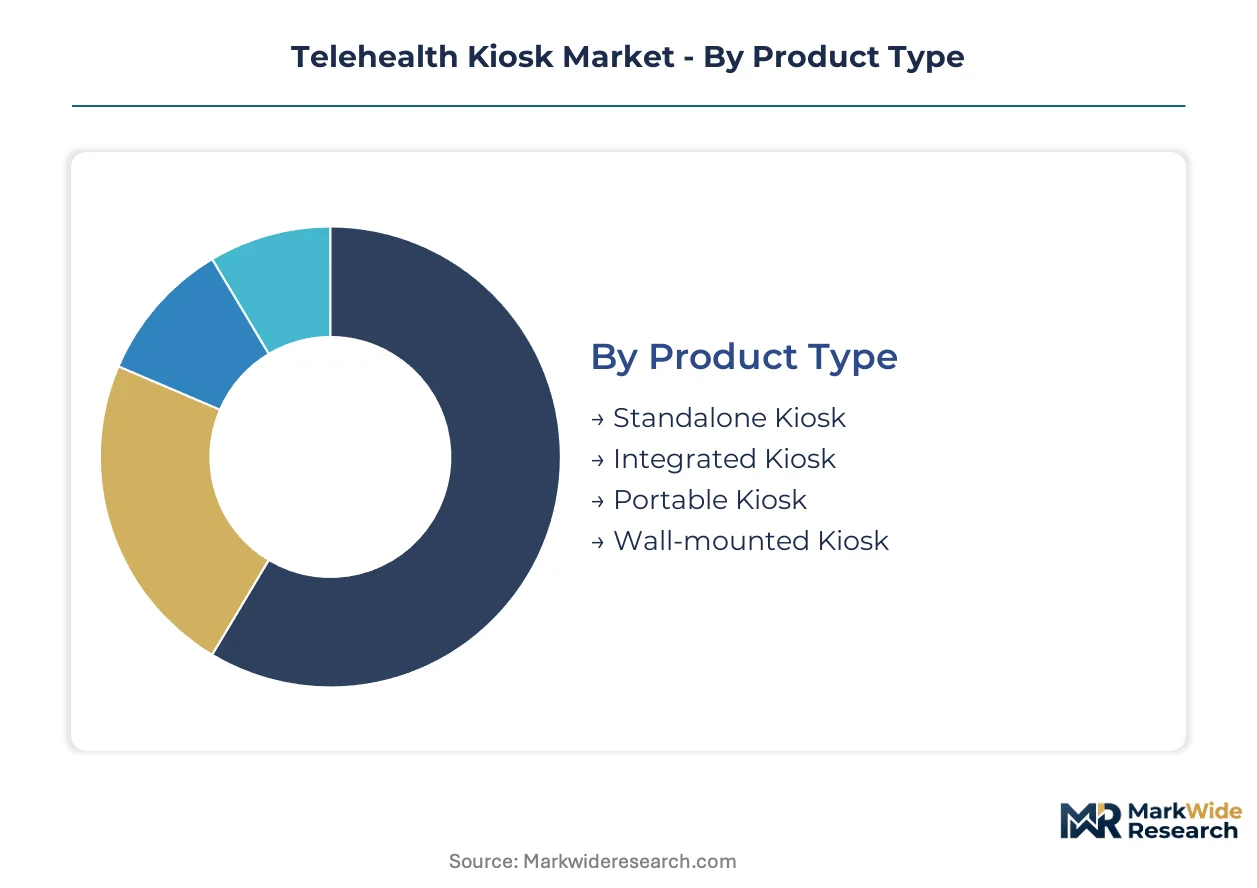
Telehealth kiosk deployment economics vary sharply across product configurations and service models. Procurement committees weight capital intensity against reimbursement eligibility when segmenting vendor shortlists. Understanding channel flow through each dimension reveals where margin pools concentrate.
Product Type:
Standalone units flow through pharmacy chain anchor tenancy programs. Integrated configurations require health system capital committees. Portable variants channel through federal emergency procurement. Wall-mounted options concentrate in municipal public health contracts.
- Standalone Kiosk:Self-contained terminal systems with minimal infrastructure requirements enable rapid site activation in retail settings. Pharmacy chains in the United States deploy these units without construction permits, driven by CMS reimbursement code expansions for remote patient monitoring.
- Integrated Kiosk:Unified EHR connectivity and payment processing modules embed directly into hospital clinical workflows. Health systems prioritize these configurations where FDA 510(k) clearance for vital sign capture reduces regulatory uncertainty.
- Portable Kiosk:Field-deployable diagnostic capacity serves mobile health units and disaster response agencies. Federal contingency contracts channel demand through vendors with weatherized antimicrobial enclosures.
- Wall-mounted Kiosk:Space-constrained installations in community health centers and municipal facilities. ADA-compliant design capabilities unlock public sector procurement channels.
Standalone kiosks dominate installed base. Portable configurations are where expansion concentrates.
End User:
Hospital procurement operates through capital budget cycles with EHR integration requirements. Clinic deployment accelerates through federal rural health funding. Ambulance service adoption hinges on field connectivity specifications. Retail pharmacy rollout follows rapid site activation models.
- Hospitals:Capital committees allocate toward biometric-enabled units over basic video terminals. CMS reimbursement codes reshape budget priorities toward diagnostic peripherals with real-time data streams.
- Clinics:Community health centers in underserved counties offset physician shortages through self-service diagnostic access. Federal rural health clinic funding accelerates site activation timelines.
- Ambulance Services:Emergency medical transport requires portable configurations with edge computing architectures. Bandwidth-independent diagnostic functionality enables network-constrained environments.
- Retail Pharmacies:Minimal infrastructure requirements and rapid deployment timelines anchor kiosk rollout programs. Patient intake without scheduled appointments displaces traditional clinic models.
Hospital systems concentrate procurement volume. Retail pharmacies are climbing the fastest.
Technology:
Video conferencing modules serve basic consultation demand. Remote monitoring platforms capture CMS reimbursement eligibility. AI diagnostics require FDA clearance pathways. Biometric access systems embed HIPAA security standards by default.
- Video Conferencing:Real-time physician interaction modules form the baseline capability across all kiosk configurations. Retail health networks deploy these for patient intake in settings lacking full-time medical staff.
- Remote Monitoring:Multi-parameter vital sign capture systems process blood pressure, pulse oximetry, and temperature in single encounters. CMS reimbursement codes for remote patient monitoring restructure capital allocation priorities.
- AI Diagnostics:Edge computing architectures execute initial analysis locally before cloud transmission. FDA 510(k) clearance timelines determine vendor qualification for hospital procurement shortlists.
- Biometric Access:Patient identification and authentication systems embed HIPAA security standards into hardware design mandates. Health systems demand seamless data exchange with existing clinical workflows.
Video conferencing dominates installed base. Remote monitoring is where expansion concentrates.
Service Type:
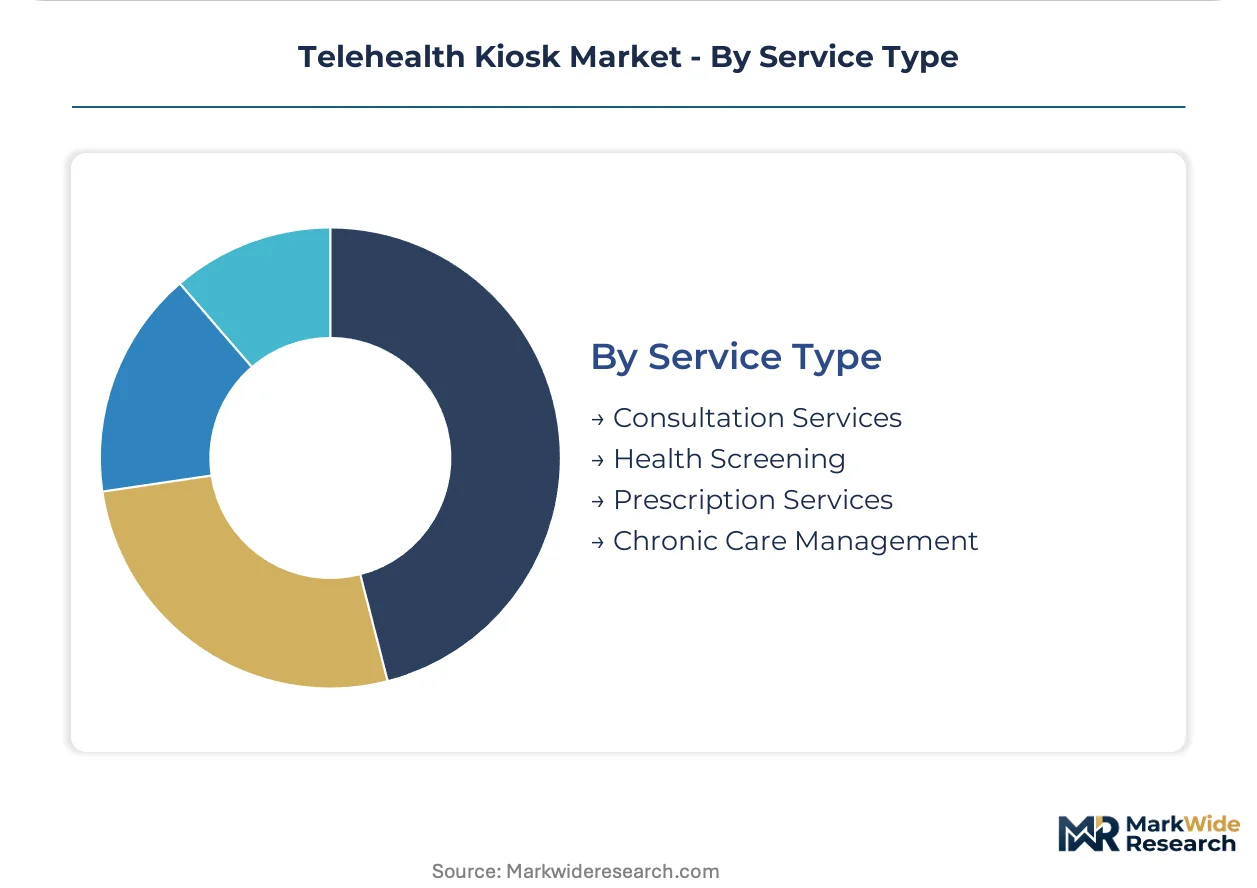
Consultation services flow through basic video terminal deployments. Health screening requires biometric sensor convergence. Prescription services demand integrated payment processing. Chronic care management captures recurring reimbursement codes.
- Consultation Services:Synchronous physician encounters via self-service terminals address physician shortage gaps. Community health centers in rural United States counties deploy these for primary care access.
- Health Screening:Multi-parameter patient intake systems capture vital signs for preventive care protocols. Federal rural health clinic funding accelerates deployment in underserved areas.
- Prescription Services:Integrated payment processing and e-prescribing modules require unified EHR connectivity. Pharmacy chains prioritize rapid site activation with minimal infrastructure.
- Chronic Care Management:Recurring remote patient monitoring encounters qualify for CMS reimbursement codes. Health systems weight these service models in capital budget cycles.
Consultation services dominate installed base. Chronic care management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telehealth kiosk deployment patterns diverge sharply between mature reimbursement environments and emerging health infrastructure markets. The United States concentrates premium integrated configurations where CMS codes justify capital investment. Developing markets prioritize standalone units with minimal site preparation requirements.
United States
Federal rural health clinic funding accelerates kiosk deployment in physician-shortage counties across the Midwest and Southeast. FDA 510(k) clearance pathways for vital sign capture modules reduce procurement uncertainty for hospital capital committees. Texas and Florida anchor pharmacy chain rollout programs where rapid site activation displaces traditional clinic models.
Germany
Community health centers in Bavaria and North Rhine-Westphalia adopt self-service diagnostic terminals to manage aging-population care demand. EMA medical device regulations and GDPR data protection standards shape hardware architecture decisions for kiosk OEMs seeking hospital procurement channels. Berlin-Brandenburg clusters telehealth infrastructure vendors serving municipal health contracts.
India
Community health centers in Maharashtra and Karnataka deploy portable configurations to extend diagnostic access in rural talukas. CDSCO medical device regulations and the PLI scheme for electronics manufacturing influence component sourcing strategies for domestic kiosk assembly. Telangana anchors software-hardware integration capabilities serving health-tech procurement.
Japan
Metropolitan health systems in Tokyo and Osaka integrate biometric-enabled units to address nursing staff shortages. PMDA medical device approval timelines and JIS standards for antimicrobial materials extend hardware development cycles. Nagoya industrial clusters supply embedded computing components for kiosk OEMs.
Australia
Remote community health services in Queensland and Western Australia prioritize field-deployable diagnostic capacity for Indigenous health outreach. TGA medical device registration requirements and federal rural health funding programs structure procurement timelines. New South Wales anchors retail pharmacy pilot programs testing rapid site activation models.
Telehealth Kiosk Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with industrial computing heritage and ADA-compliant enclosure capabilities determining vendor qualification for premium contracts. The market structure rewards players combining embedded hardware supply with software-hardware integration expertise. Three archetypes dominate: industrial computing conglomerates with captive component supply, specialized enclosure fabricators with municipal certification track records, and health-tech integrators navigating EHR connectivity requirements. Competitive moves concentrate on strategic partnerships for rapid deployment scaling and portfolio diversification into portable configurations for federal emergency procurement.
Within the industrial computing tier, Advantech Co., Ltd. anchors embedded hardware supply relationships with kiosk OEMs. Olea Kiosks exemplifies the enclosure-specialist archetype through ADA-compliant design capabilities that unlock municipal health contracts. Clinics On Cloud occupies a position representing software-hardware integration expertise that constrains smaller competitors in health system procurement cycles.
| Leading Market Players |
|---|
| RedyRef Interactive Kiosks |
| Advantech Co., Ltd. |
| Clinics On Cloud |
| Fabcon |
| Clearwave Corporation |
| Olea Kiosks |
| KIOSK Information Systems |
| Frank Mayer and Associates |
| Meridian Kiosks |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for medical-grade embedded computing boards concentrate pricing power among East Asian contract manufacturers, while hospital procurement committees absorb cost volatility through multi-year service contracts rather than spot purchasing.
Pricing Analysis
Long-term offtake agreements dominate hospital system procurement, with subscription-based SaaS tiers for software-hardware integration commanding premiums over per-unit transactional models for standalone pharmacy deployments. Price differentiation separates FDA 510(k)-cleared biometric configurations from basic video terminals, with certification level and after-sales service bundling as primary tiering mechanisms. Pricing pressure stems from reimbursement fragmentation across state-level telehealth parity laws, compressing margins for vendors without integrated training ecosystems. Retail pharmacy chains exhibit highest price sensitivity due to rapid site activation volume requirements, while municipal health contracts prove least sensitive given ADA compliance mandates.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan port corridors elevate landed costs for embedded computing components and medical-grade displays, with container availability constraints feeding into procurement committee timelines. Manufacturing concentrates in Taiwan, South Korea, and coastal China for semiconductor boards and sensor arrays, while antimicrobial enclosure fabrication clusters in domestic U.S. and Mexican facilities. Raw material dependencies include medical-grade aluminum alloys, EPA-registered antimicrobial coatings, and HIPAA-compliant encryption chipsets. Single-source vulnerability in East Asian contract manufacturing represents the dominant structural risk. Distribution runs through direct OEM relationships with health systems and pharmacy chain anchor tenancy programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth kiosk economics are approaching a platform-economics inflection where EHR interoperability ecosystems determine vendor survival, with CMS reimbursement code convergence accelerating winner-take-most dynamics.
For Market Incumbents: Fortify embedded hardware supply relationships through backward integration into sensor module production, while deepening certification investment in FDA 510(k) pathways to defend against software-native entrants. Prioritize captive training ecosystem development to offset certified technician scarcity threatening deployment velocity. Channel control through exclusive pharmacy chain partnerships represents the critical defensive lever against retail-health disintermediation. For New Entrants and Emerging Players: Chronic care management service-layer gaps in rural health clinic networks offer white-space expansion where incumbents under-serve reimbursement complexity. Target community health centers in physician-shortage counties with portable configuration offerings and rapid federal funding qualification support. Go-to-market positioning through disaster response procurement channels bypasses entrenched hospital system vendor lists. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable kiosk sub-segments as edge computing architectures reduce cloud infrastructure dependency. Long-term viability favors acquiring software-hardware integrators with municipal certification track records rather than pure hardware fabricators. Monitor FDA 510(k) clearance velocity as the primary inflection signal for vendor shortlist composition shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Investment | Reduces procurement uncertainty for hospital capital committees evaluating biometric-enabled configurations. |
| Integrated Training Ecosystem Development | Addresses certified technician scarcity constraining deployment velocity for health system buyers. |
| EHR Platform Partnership | Enables unified connectivity requirements that strain smaller software-hardware integrators. |
| Portable Configuration Scale-Up | Captures federal emergency procurement demand from disaster response agencies. |
| ADA-Compliant Enclosure Certification | Unlocks municipal public health contracts requiring weatherized antimicrobial surface specifications. |
Study Parameters
Desk research of FDA 510(k) clearance databases, CMS reimbursement code filings, and hospital procurement contract disclosures preceded structured interviews with biomedical engineers, GPO contracts managers, kiosk OEM product directors, and rural health clinic administrators. Primary fieldwork combined with secondary validation against SEC filings of embedded computing suppliers and trade data for medical-grade display imports. Bottom-up unit deployment estimates triangulated against top-down health system capital expenditure surveys.
Variance decomposition across product configuration, end-user segment, technology tier, and regional reimbursement environment shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to early-adopter deployment trajectories in pharmacy chain and community health center channels. Forecast inputs included federal rural health clinic funding authorization timelines and state-level telehealth parity law adoption rates.
Underlying assumptions cover sustained CMS remote patient monitoring reimbursement eligibility and stable East Asian component supply corridors, with deviation risk concentrated in FDA clearance timeline extensions and geopolitical friction affecting embedded computing board availability. Recalibration cycles align with material shifts in federal rural health appropriations and state reimbursement parity expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telehealth Software Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Telepathology Service Market
Telemedicine
Tele-Care Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
US Telemedicine Market
Telemedicine
Telemedicine Service Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Europe Telemedicine Market
Telemedicine
India Telehealth Services Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
North America and Europe Ehealth Market