
 Cattle Health Market | 2026-2036
Cattle Health Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Health Market Analysis
Precision livestock monitoring through wearable biosensors and AI-driven diagnostic platforms is reshaping how cattle health interventions are timed and delivered. Zoetis Inc. leverages its diagnostics-to-therapeutics pipeline to anchor premium positions in reproductive health segments. Boehringer Ingelheim International GmbH sustains manufacturing scale across vaccine portfolios for bovine respiratory disease. Elanco Animal Health Incorporated differentiates through channel control in North American beef feedlot systems.
Cattle health encompasses the prevention, diagnosis, and treatment of infectious, metabolic, and reproductive disorders in bovine populations, typically involving biologics with specified antigen concentrations, antimicrobial formulations with defined withdrawal periods, and mineral supplements balanced to NRC nutritional requirements. Vaccines dominate product type revenue pools given mandatory protocols for brucellosis and clostridial diseases across commercial operations. Disease prevention leads application-level demand due to regulatory compliance requirements, while reproductive health segments capture expanding margin pools as dairy operations intensify artificial insemination programs. Dairy farms represent the most concentrated end user category for nutritional support products, particularly in regions with large-scale confinement operations.
The FDA Veterinary Feed Directive restricts over-the-counter antibiotic access, compelling producers to establish veterinary-client-patient relationships and reshaping procurement patterns. USDA Animal and Plant Health Inspection Service traceability mandates for interstate cattle movement create compliance-driven demand for electronic identification and health certification systems. State-level brand inspection programs in Texas, Kansas, and Nebraska add layered documentation requirements that influence health product distribution logistics. Stakeholders must monitor evolving antimicrobial resistance policy frameworks and assess how diagnostic technology investments reshape operational workflows before regulatory deadlines tighten further.
Market Dynamics
The FDA's Veterinary Feed Directive and parallel antimicrobial stewardship mandates across Brazil and the European Union are compressing antibiotic-dependent workflows while accelerating veterinary-client-patient relationship formation as a structural prerequisite for product access.
Growth Catalysts
- Precision Monitoring Hardware:Wearable biosensors tracking rumination patterns and core body temperature enable subclinical mastitis detection 48-72 hours before visible symptoms appear, driving replacement of scheduled veterinary visits with event-triggered interventions.
- USDA Traceability Mandates:Interstate cattle movement documentation requirements under APHIS rules create compliance-driven procurement of electronic identification systems and integrated health certification databases across feedlot and dairy operations.
- Intensification in Mato Grosso:Brazil's integrated beef operations scaling beyond 50,000 head deploy automated processing facilities that bundle health monitoring with nutritional optimization, creating concentrated demand for reproductive health biologics.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for tetracycline and macrolide classes concentrates in Chinese and Indian chemical clusters, exposing formulators to shipping disruption and currency volatility without short-term substitution options.
- Veterinary Labor Scarcity:Rural practitioner density in the US Great Plains and Australian outback falls below thresholds needed to satisfy VFD-mandated prescription relationships, forcing producers to absorb travel costs or delay treatment initiation.
- Withdrawal Period Complexity:Extended meat and milk withholding requirements for newer antimicrobial classes complicate treatment timing in continuous-flow dairy operations, reducing therapeutic flexibility and elevating culling rates for refractory infections.
Strategic Opportunities
- Sub-Saharan Africa Pastoral Systems:Mobile veterinary diagnostic platforms using solar-powered cold chain storage address infrastructure gaps in Kenya and Ethiopia's extensive grazing zones, opening volume pools currently served by informal medicine traders.
- CRISPR-Based Vaccine Platforms:Gene-edited antigen delivery systems reduce development timelines for emerging pathogen responses, with regulatory pathways under evaluation by EMA and Brazil's ANVISA creating first-mover positioning for platform licensors.
- Blockchain Health Certification:Immutable record systems for antibiotic use and vaccination history align with EU Green Deal farm-to-fork traceability requirements, enabling premium market access for verified low-residue beef exports.
Industry Challenges
- Interoperability Deficits:Proprietary data formats from competing sensor manufacturers prevent integration of rumination monitors, milk composition analyzers, and herd management software into unified decision-support dashboards.
- Diagnostic Validation Bottlenecks:Field-deployable PCR and ELISA platforms for bovine viral diarrhea and infectious bovine rhinotracheitis require state-by-state laboratory certification in the US, extending commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Health Market |
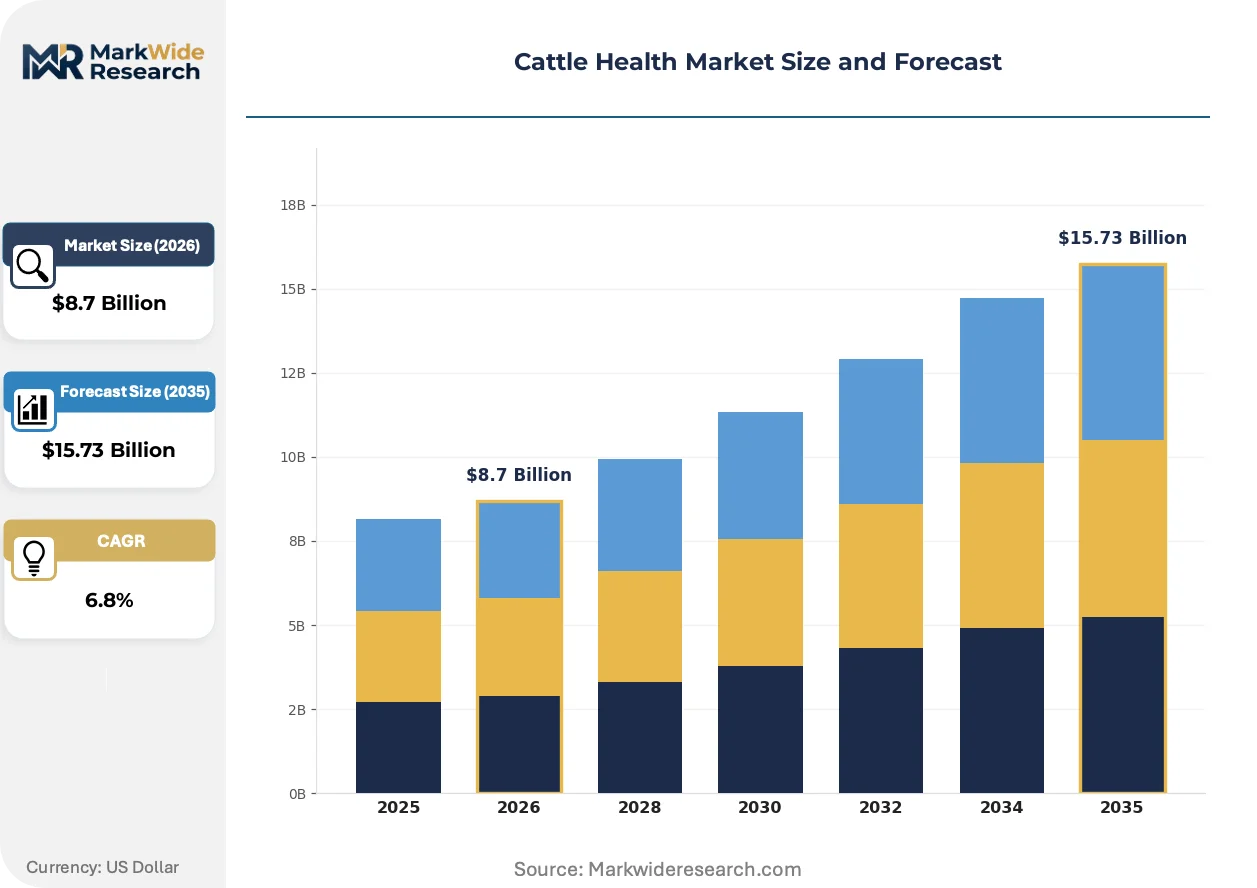
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Hormones, Minerals Application: Disease Prevention, Pain Management, Reproductive Health, Nutritional Support End User: Dairy Farms, Beef Farms, Veterinary Clinics, Research Institutions Delivery Mode: Injectable, Oral, Topical, Inhalation |
| Companies Covered | Elanco Animal Health Incorporated, Ceva Santé Animale S.A., Zoetis Inc., Virbac S.A., Vetoquinol S.A., Merck & Co., Inc., Phibro Animal Health Corporation, Dechra Pharmaceuticals PLC, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Health Market Emerging Trajectories
Artificial intelligence inference at the edge and cloud-based epidemiological modeling are converging to transform how health interventions are timed, shifting competitive advantage toward data-integrated service architectures rather than standalone pharmaceutical formulations.
Machine learning algorithms processing accelerometer and acoustic data from neck-mounted sensors is digitizing estrus detection accuracy in large-scale dairy confinement operations. Wisconsin and California herds exceeding 5,000 milking head deploy these systems to compress artificial insemination windows from 12-hour observation cycles to real-time alerts. The technology is digitizing reproductive labor allocation, reducing skilled herdsperson headcount per thousand animals while improving conception rate consistency.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are accelerating veterinary pharmaceutical cold chain reconfiguration across member states. Bulk vaccine storage and transport systems face refrigerant replacement costs and equipment retrofit requirements that compress distributor margins. Northern European dairy cooperatives respond by consolidating regional distribution hubs to amortize infrastructure investment across larger volume pools.
Consolidated beef packer procurement specifications now mandate third-party verified health protocols as a condition for forward contract eligibility. JBS, Tyson, and Cargill feedlot procurement teams in the US High Plains require documentation of bovine respiratory disease vaccination timing and antimicrobial use records. This specification cascade forces independent backgrounding operations to adopt certified veterinary oversight programs previously optional for cash market sales.
Cattle Health Market Segmentation
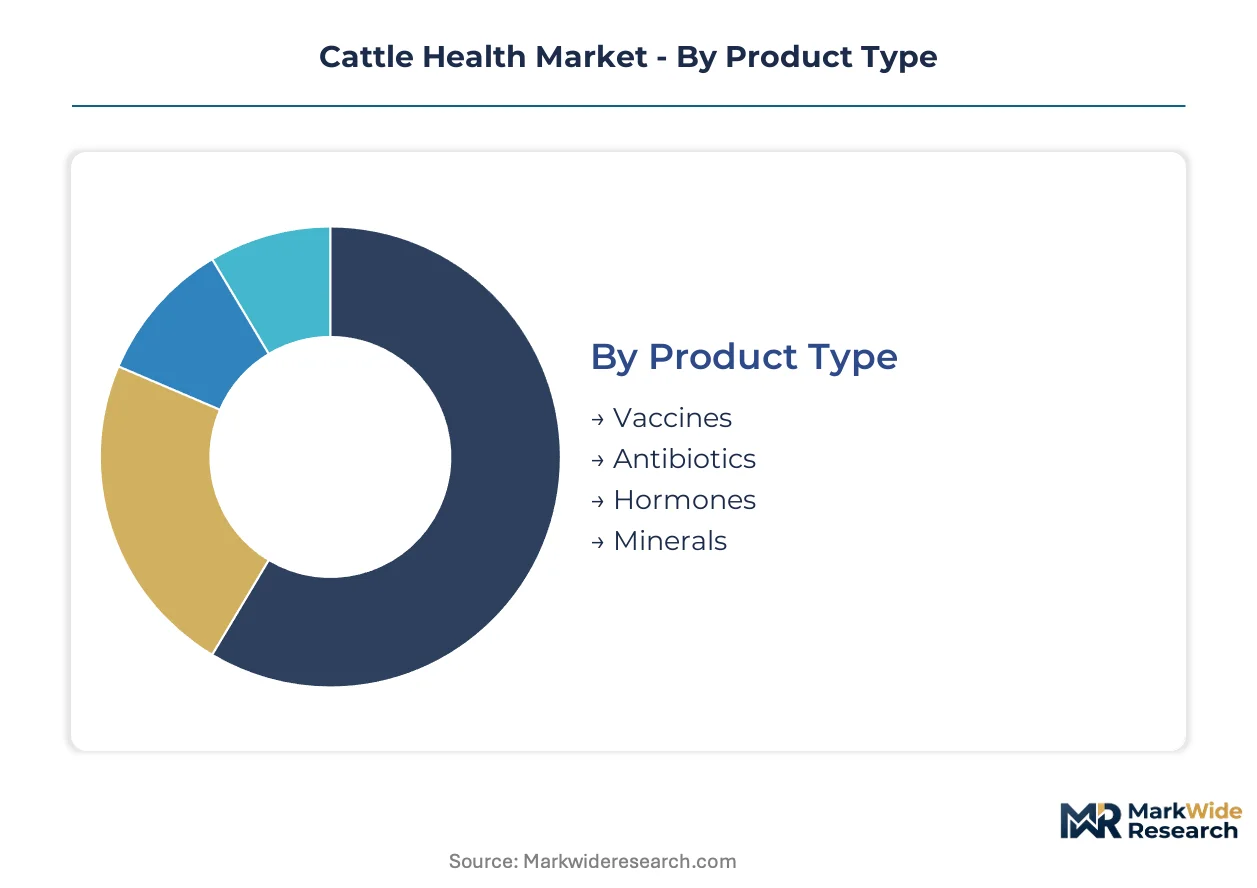
Cattle health procurement patterns diverge sharply across operational contexts. Dairy confinement systems prioritize metabolic monitoring products, while extensive beef grazing operations emphasize portable delivery formats. Understanding these segment boundaries clarifies where formulation investments yield differential returns.
Product Type:
Cost tier structures in this category separate premium biologics from commodity chemical formulations, with margin concentration tracking regulatory complexity and manufacturing scale.
- Vaccines:These biologics contain specified antigen concentrations requiring cold chain integrity from production through administration. Demand clusters in commercial feedlots across the US High Plains and integrated operations in Brazil's Mato Grosso, driven by mandatory brucellosis protocols and packer procurement specifications.
- Antibiotics:Antimicrobial formulations carry defined withdrawal periods that constrain treatment timing in continuous-flow operations. FDA Veterinary Feed Directive restrictions compress over-the-counter access, forcing veterinary-client-patient relationship formation as a prerequisite for procurement in Wisconsin and California dairy systems.
- Hormones:Reproductive biologics including prostaglandins and gonadotropins support estrus synchronization programs.
- Minerals:Nutritional supplements balanced to NRC requirements address trace element deficiencies in forage-based systems.
Vaccines command the established base. The steepest expansion runs through reproductive health hormones as dairy intensification accelerates artificial insemination programs.
Application:
Volume concentration in this dimension follows the regulatory compliance burden, with mandatory protocols generating baseline demand and discretionary interventions creating margin upside.
- Disease Prevention:Prophylactic protocols encompass clostridial and respiratory disease vaccination schedules. USDA Animal and Plant Health Inspection Service traceability mandates for interstate movement amplify documentation requirements, concentrating procurement in large-scale backgrounding operations.
- Reproductive Health:Estrus synchronization and fertility management products capture expanding margin pools. Wisconsin herds exceeding 5,000 head deploy AI programs with timed breeding protocols, generating concentrated demand for prostaglandin and GnRH analogues.
- Pain Management:Analgesic formulations address dehorning, castration, and lameness interventions.
- Nutritional Support:Metabolic correction products target transition cow management and subclinical ketosis.
Disease prevention anchors volume throughput. Reproductive health applications are climbing the fastest as labor scarcity drives automation of estrus detection.
End User:
Customer type in this segmentation separates concentrated capital-intensive operations from dispersed service-dependent channels, with procurement authority residing at distinct organizational levels.
- Dairy Farms:Confinement operations with large milking herds drive nutritional support and metabolic health product demand. California's Central Valley and Wisconsin's Fox River Valley host the most concentrated purchasing power for precision monitoring-integrated health systems.
- Beef Farms:Backgrounding and feedlot operations prioritize respiratory disease prevention and growth promotion protocols.
- Veterinary Clinics:Rural practitioner networks serve as gatekeepers for prescription-required products under antimicrobial stewardship frameworks.
- Research Institutions:Academic and government veterinary laboratories validate diagnostic platforms and field trial novel formulations.
Dairy farms represent the most concentrated channel. Veterinary clinics are gaining share fastest as regulatory frameworks mandate professional oversight for antimicrobial access.
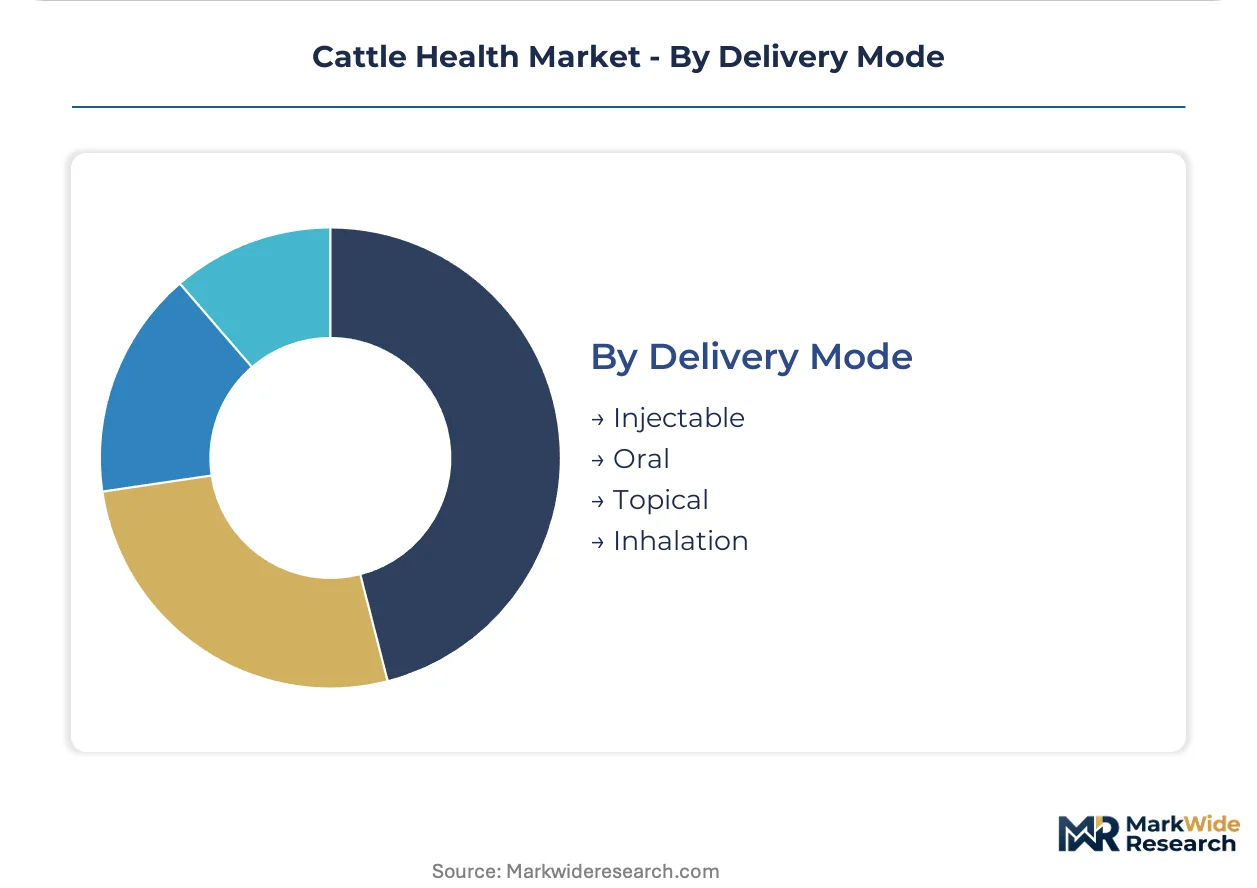
Delivery Mode:
Supply concentration in manufacturing infrastructure shapes availability and cost structures across administration formats, with formulation complexity determining competitive moats.
- Injectable:Parenteral formulations dominate biologic delivery, requiring sterile manufacturing capacity and skilled administration technique. Brazil's integrated beef processors deploy automated processing facilities that standardize injection protocols across 50,000-head operations.
- Oral:Feed and water medication formats face reformulation pressures as the EU F-Gas Regulation and parallel mandates restrict certain excipient classes.
- Topical:Pour-on antiparasitics and wound treatments suit extensive grazing systems with limited handling infrastructure.
- Inhalation:Intranasal vaccine delivery reduces needle-associated tissue reactions and improves operator safety.
Injectable formats retain volume dominance. Oral delivery is expanding most quickly as feed medication automation spreads in large-scale confinement systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated beef operations export premium cattle genetics and health protocols to Middle Eastern and Asian processors, while the United States ships pharmaceutical formulations to Canadian feedlots under harmonized USDA-CFIA veterinary oversight frameworks.
United States
Wisconsin's Fox River Valley and California's Central Valley dairy herds drive precision monitoring hardware procurement. The FDA's Veterinary Feed Directive compels veterinary-client-patient relationship formation for antibiotic access. Texas Panhandle feedlots bundle respiratory disease vaccination with packer procurement specifications.
Brazil
Mato Grosso's 50,000-head integrated beef processors deploy automated health certification systems for export eligibility. ANVISA evaluates CRISPR-based vaccine regulatory pathways alongside EMA alignment. São Paulo state distributors consolidate cold chain infrastructure to serve the southeastern dairy belt.
Germany
Bavarian dairy cooperatives absorb EU F-Gas Regulation refrigerant retrofit costs through regional distribution hub consolidation. The country's national pharmaceutical regulator enforces withdrawal period documentation for antimicrobial use. Lower Saxony's intensive livestock zones pilot blockchain health certification for EU Green Deal farm-to-fork compliance.
China
Inner Mongolia and Xinjiang pastoral regions scale mobile veterinary diagnostic platforms with solar-powered cold chain storage. The national medical products administration tightens import registration for bovine biologics. Shandong Peninsula feedlots adopt automated processing facilities modeled on Brazilian integrated operations.
Australia
Queensland and New South Wales extensive grazing operations face veterinary labor scarcity below rural practitioner density thresholds. The national agricultural department mandates electronic identification for interstate cattle movement traceability. Victorian dairy confinement systems import precision estrus detection algorithms from Wisconsin technology licensors.
Cattle Health Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates manufacturing scale among diversified animal health portfolios, while mid-tier specialists defend margin positions through reproductive health segment focus. Three archetypes dominate: integrated pharmaceutical-diagnostics platforms, vaccine-centric biologics manufacturers, and precision monitoring-integrated service providers. Competitive moves center on diagnostic-to-therapeutic pipeline integration and regional distribution hub consolidation.
Within the integrated pharmaceutical tier, Zoetis Inc. and Boehringer Ingelheim International GmbH exemplify scale-driven platform strategies, while Elanco Animal Health Incorporated occupies a position emphasizing North American channel control. These entities represent divergent approaches to veterinary-client-patient relationship formation under antimicrobial stewardship mandates.
| Leading Market Players |
|---|
| Elanco Animal Health Incorporated |
| Ceva Santé Animale S.A. |
| Zoetis Inc. |
| Virbac S.A. |
| Vetoquinol S.A. |
| Merck & Co., Inc. |
| Phibro Animal Health Corporation |
| Dechra Pharmaceuticals PLC |
| Boehringer Ingelheim International GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity in sterile injectable manufacturing across the European Union and North America is driving contract manufacturers toward multi-year offtake commitments with cattle health formulators, compressing spot-market availability while elevating price floors for parenteral vaccine and antibiotic delivery systems. This utilization squeeze feeds directly into procurement posture, with large-scale feedlot operators locking in volume guarantees to secure cold-chain capacity ahead of seasonal disease pressure windows.
Pricing Analysis
Cost-plus contracts indexed to tetracycline and macrolide active pharmaceutical ingredient spot markets dominate antimicrobial procurement between Brazilian integrated processors and Asian chemical manufacturers. Pricing stratifies across premium cold-chain biologics, standard ambient-stable formulations, and economy generic antibiotics, with differentiation anchored in ANVISA certification tiers and withdrawal-period documentation depth. Cost compression in the generic antibiotic tier is intensifying due to Indian API oversupply, while vaccine margins hold firm. Dairy confinement operations above 5,000 head show lowest price sensitivity given regulatory compliance imperatives, whereas extensive grazing operations in Australia's outback exhibit acute sensitivity to freight-included delivered costs.
Supply Chain Analysis
Export control regimes restricting CRISPR-based platform technology transfer from United States and European Union research institutions are constraining vaccine development pipeline access for Brazilian and Chinese formulators. Active pharmaceutical ingredient manufacturing concentrates in China and India, sterile fill-finish capacity clusters in Germany and the United States, and distribution logistics hinge on regional cold-chain hubs in São Paulo and Wisconsin. Single-source vulnerability runs through H1N1 and BVD vaccine strain seed stock repositories held by USDA and OIE reference laboratories. Distribution runs through veterinary clinic gatekeepers in North America, direct-to-processor arrangements in Brazil's Mato Grosso, and cooperative buying groups in Germany's Bavarian dairy belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
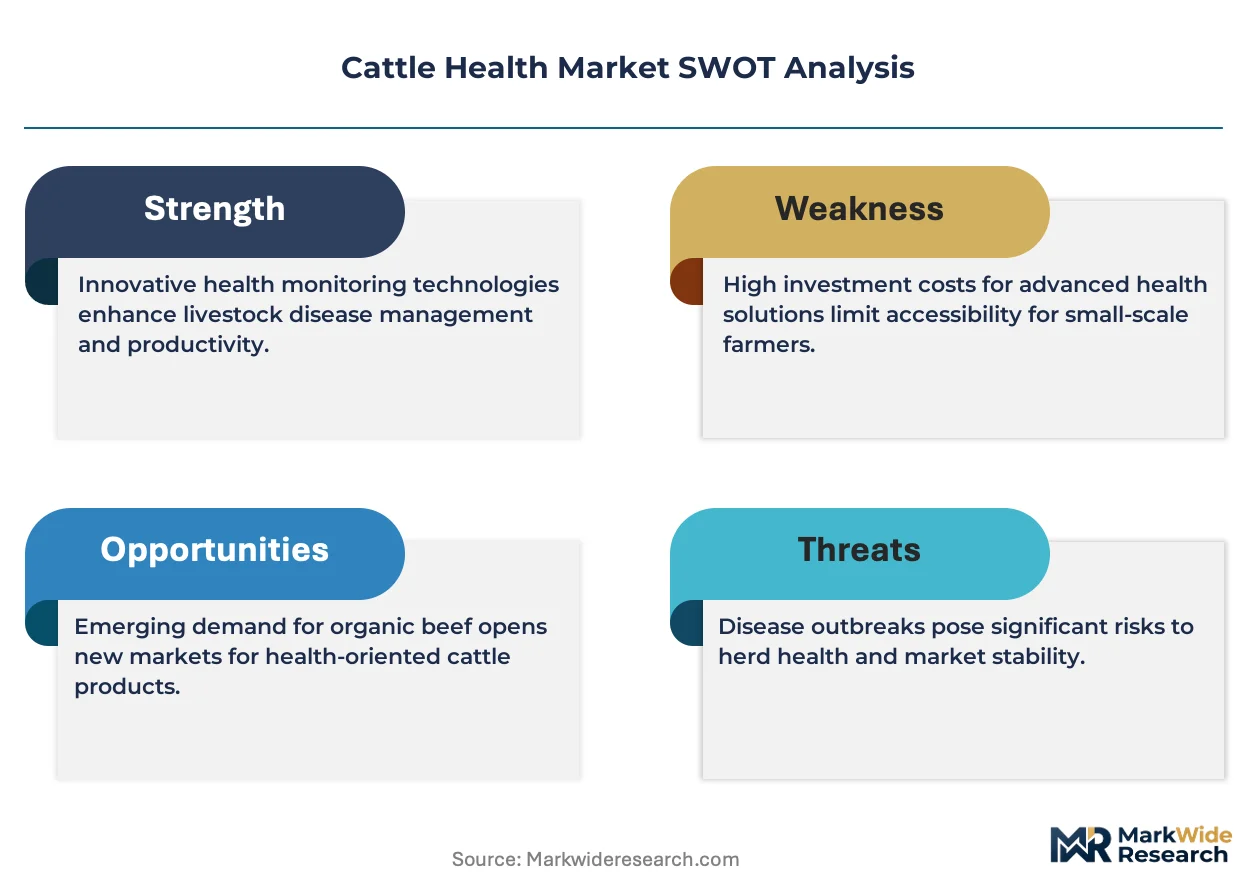
Precision livestock monitoring penetration remains below 15% in extensive grazing systems despite proven subclinical mastitis detection capabilities, positioning the market for an early-cycle expansion as solar-powered hardware costs decline and veterinary labor scarcity intensifies.
For Market Incumbents: Build diagnostic-to-therapeutic pipeline integration as the primary competitive moat. Acquire edge-computing sensor specialists to unify rumination monitoring with automated treatment triggering, defending against software-native entrants. Anchor manufacturing scale in Brazil through ANVISA-aligned cold-chain infrastructure, locking out regional challengers facing regulatory validation bottlenecks.
For New Entrants and Emerging Players: Mobile veterinary diagnostic platforms serving Kenya and Ethiopia's pastoral corridors represent the most penetrable entry point, bypassing incumbent channel control in saturated North American and European markets. Solar-powered cold chain hardware bundled with pay-per-test PCR services offers a capital-light go-to-market angle against asset-heavy integrated pharmaceutical platforms.
For Investors and Strategic Acquirers: Capital is best deployed toward precision monitoring-integrated service providers with established veterinary-client-patient relationship networks, as antimicrobial stewardship mandates elevate prescription gatekeeper value. The five-to-ten-year viability window favors platform licensors over standalone formulation plays. Watch for FDA Veterinary Feed Directive enforcement intensity as the signal for antibiotic-dependent workflow displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | Unifies sensor data with treatment protocols, compressing intervention windows for Wisconsin dairy herds. |
| CRISPR Vaccine Regulatory Pathway | ANVISA and EMA alignment on gene-edited antigen delivery accelerates pandemic response capabilities. |
| Cold Chain Infrastructure Consolidation | São Paulo distributors amortize EU F-Gas retrofit costs across larger volume pools serving southeastern dairy. |
| Blockchain Health Certification | Immutable antibiotic use records unlock EU Green Deal premium market access for verified low-residue beef. |
| Veterinary Channel Control | Clinic network ownership secures prescription gatekeeper position under FDA antimicrobial stewardship mandates. |
Methodological Framework
A spread of perspectives from feedlot operations managers, veterinary clinic principals, pharmaceutical regulatory affairs leads, and cooperative procurement directors converged on the working assumptions shaping demand forecasts. Primary interviews across Wisconsin, California, Mato Grosso, and Bavaria were cross-referenced with secondary validation from FDA Veterinary Feed Directive implementation reports, ANVISA biologic registration databases, USDA APHIS traceability compliance filings, and EU F-Gas Regulation phase-down schedules. Bottom-up volume modeling from herd-level product consumption patterns was triangulated against top-down manufacturer shipment data.
Demand-supply balance dynamics across the projection horizon were assessed through capacity utilization analysis at sterile manufacturing facilities and veterinary labor density mapping in rural service territories. Segmentation dimensions included product type biologics versus chemical formulations, application disease prevention versus reproductive health, end user dairy confinement versus extensive beef grazing, and delivery mode injectable versus oral versus topical. CAGRs were derived from regression analysis against historical adoption curves for comparable precision agriculture technologies. Forecast inputs incorporated packer procurement specification evolution and antimicrobial resistance policy trajectory.
Practitioners should monitor API shipping disruption frequency, veterinary practitioner graduation rates, and packer blockchain certification mandate rollout for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Global Companion Animal Health Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Animal Health Software Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Rat Model Market
Animal Health
US Companion Animal Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
US Military Animals Market
Animal Health
Animal Healthcare Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Animal Health Market
Animal Health
Cattle Healthcare Market
Animal Health
African Horse Sickness Treatment Market