
 North America Renewable Energy Market | 2026-2036
North America Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Renewable Energy Market Outlook
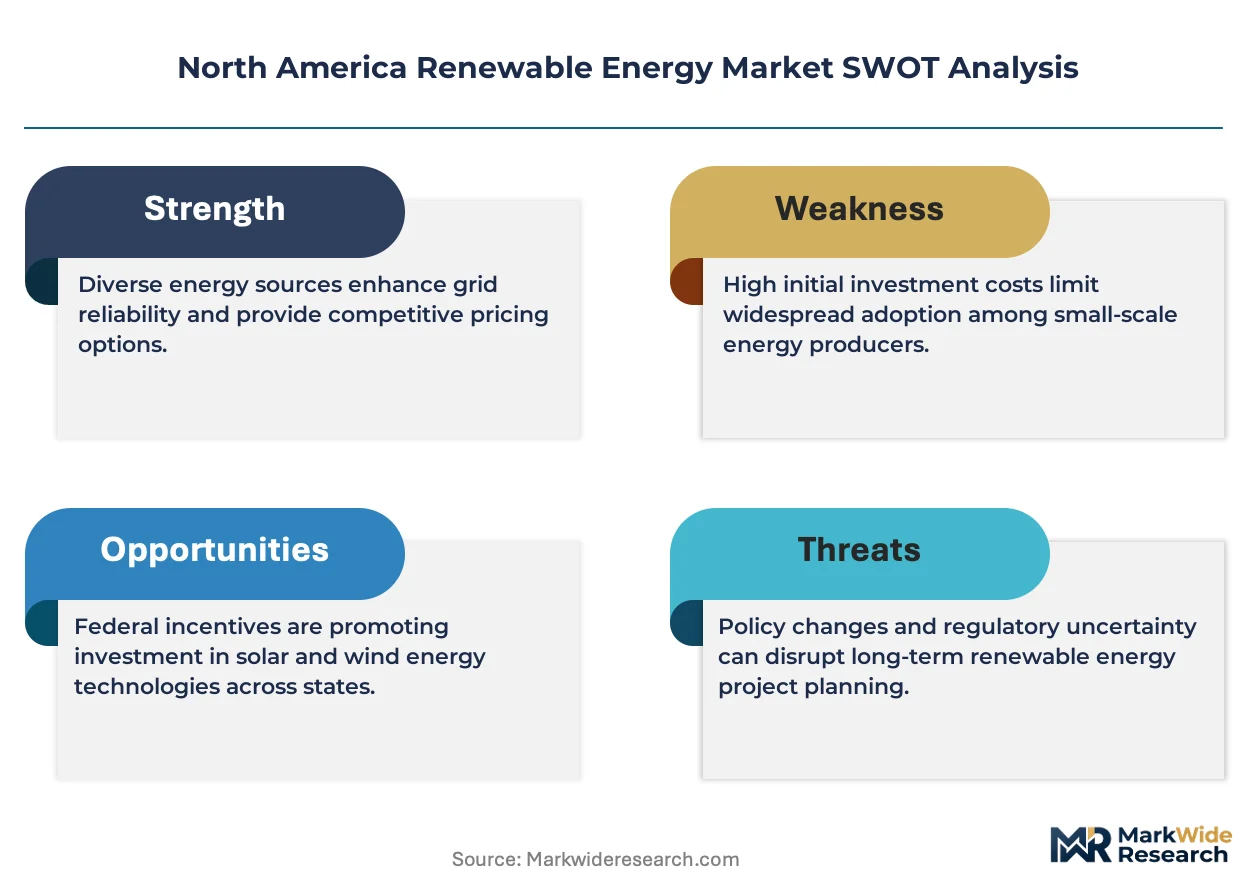
The US Inflation Reduction Act is restructuring capital flows across the North America renewable energy landscape, extending tax credit eligibility to standalone storage and green hydrogen co-located assets. NextEra Energy leverages its vertically integrated development platform to control project timelines from origination through grid interconnection. Constellation Energy anchors its competitive position through nuclear-to-renewable hybrid fleet optimization and wholesale power contracting expertise. Invenergy differentiates through proprietary wind turbine technology partnerships and large-scale battery co-location strategies.
North America renewable energy encompasses electricity generation systems that harness solar irradiance, wind kinetic energy, organic biomass combustion, and hydrological flow to produce grid-connected or distributed power with near-zero operational emissions, typically operating at capacity factors ranging from 25% for solar PV to 90% for run-of-river hydroelectric installations. Solar technology dominates new capacity additions across utility-scale procurement channels, while distributed generation applications are gaining structural share behind commercial and industrial meters as net metering policies evolve. Wind technology maintains mature cost competitiveness across the Great Plains corridor, and biomass retains niche relevance in combined heat and power configurations for pulp and paper industrial end users.
The Federal Energy Regulatory Commission shapes market access through interconnection queue reforms and transmission planning mandates, while the Environmental Protection Agency enforces emissions standards that accelerate coal displacement. State-level renewable portfolio standards in California, New York, and Illinois create demand floors that complement federal tax incentives. Stakeholders must monitor interconnection backlog resolution timelines and evolving domestic content requirements as determinants of project returns.
Market Dynamics
The US Inflation Reduction Act's production tax credit extensions and standalone storage eligibility are restructuring capital deployment timelines across project finance structures. Federal and state policy layering creates divergent development velocities across interconnection queues.
Growth Catalysts
- ITC/PTC Stackability:The IRA's enhanced tax credits for domestic content and energy communities reduce levelized cost of energy for utility-scale solar developers in Texas and California interconnection zones.
- Corporate PPA Procurement:Technology and data center operators are signing 10-20 year virtual power purchase agreements that provide revenue certainty for merchant renewable projects.
- Battery Cost Curves:Lithium iron phosphate cell prices have compressed co-located storage economics, enabling four-hour duration systems to capture peak price spreads in ERCOT and CAISO markets.
Market Restraints
- Interconnection Backlog:FERC Order 2023 reforms address queue reform but regional transmission organizations still face 3-5 year study timelines for grid-scale projects in PJM and SPP territories.
- Domestic Content Requirements:The IRA's phased domestic content bonus credit creates supply chain constraints as crystalline silicon wafer and cell manufacturing capacity lags module assembly in the United States.
- Copper and Rare Earth Concentration:Wind turbine permanent magnet supply chains concentrate processing capacity in China, exposing project developers to tariff and logistics volatility.
Strategic Opportunities
- Green Hydrogen Hub Development:The DOE's hydrogen hub program creates offtake anchors for renewable projects in Texas, California, and the Midwest with dedicated production tax credits under Section 45V.
- Behind-the-Meter C&I:Commercial and industrial distributed solar with battery backup is penetrating manufacturing facilities seeking resilience against escalating utility demand charges.
- Offshore Wind Lease Areas:BOEM lease auctions in the Gulf of Mexico and Pacific Northwest open new development frontiers with higher capacity factors than onshore resources.
Industry Challenges
- Electrical Engineer and Technician Shortage:Grid interconnection studies, substation design, and high-voltage commissioning expertise pools are insufficient for current project pipelines.
- Environmental Permitting Variability:Endangered species reviews under the Endangered Species Act and NEPA timelines create 12-24 month delays for projects in the Southwest and Great Plains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Renewable Energy Market |
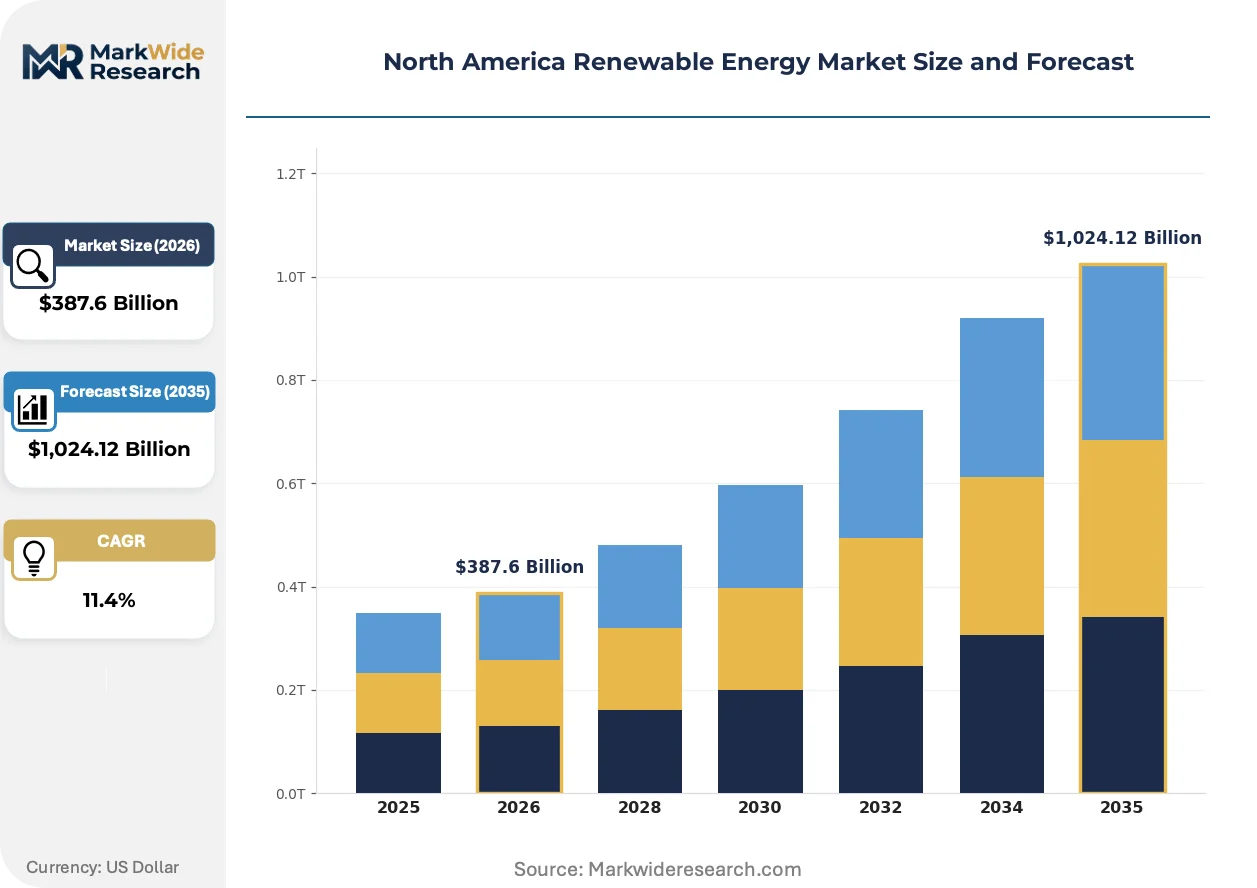
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro Application: Utility Scale, Distributed Generation, Off-grid, Combined Heat and Power End User: Residential, Commercial, Industrial, Government Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | NextEra Energy, Constellation Energy, Invenergy, EDF Renewables North America, EDP Renewables North America, Brookfield Renewable Partners, Pattern Energy, First Solar, Clearway Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Renewable Energy Market Strategic Shifts
Technology convergence between solar PV, battery storage, and electrolyzer systems is redefining project configuration economics. Regulatory pressure on fossil fuel retirement timelines accelerates clean capacity procurement.
Bifacial solar modules with tracking systems are expanding into utility-scale procurement channels as the default technology choice. Independent power producers and utility affiliates are specifying these configurations for new-build projects. The technology is expanding into markets previously dominated by fixed-tilt mono-facial installations by reducing land use intensity and improving capacity factors.
The EPA's power plant greenhouse gas standards under Section 111 of the Clean Air Act are forcing coal and natural gas fleet retirement decisions. State environmental regulators are aligning implementation timelines with renewable build-out schedules. Baseload replacement procurement in the Midwest and Southeast is accelerating combined solar-storage hybrid project development.
Virtual power purchase agreements are displacing traditional utility green tariff programs as the preferred corporate procurement mechanism. Large technology and consumer goods companies are executing synthetic PPAs that provide price hedges without physical delivery obligations. This structure concentrates creditworthy offtake demand in ERCOT, CAISO, and PJM markets where merchant price exposure remains material.
North America Renewable Energy Market Segmentation
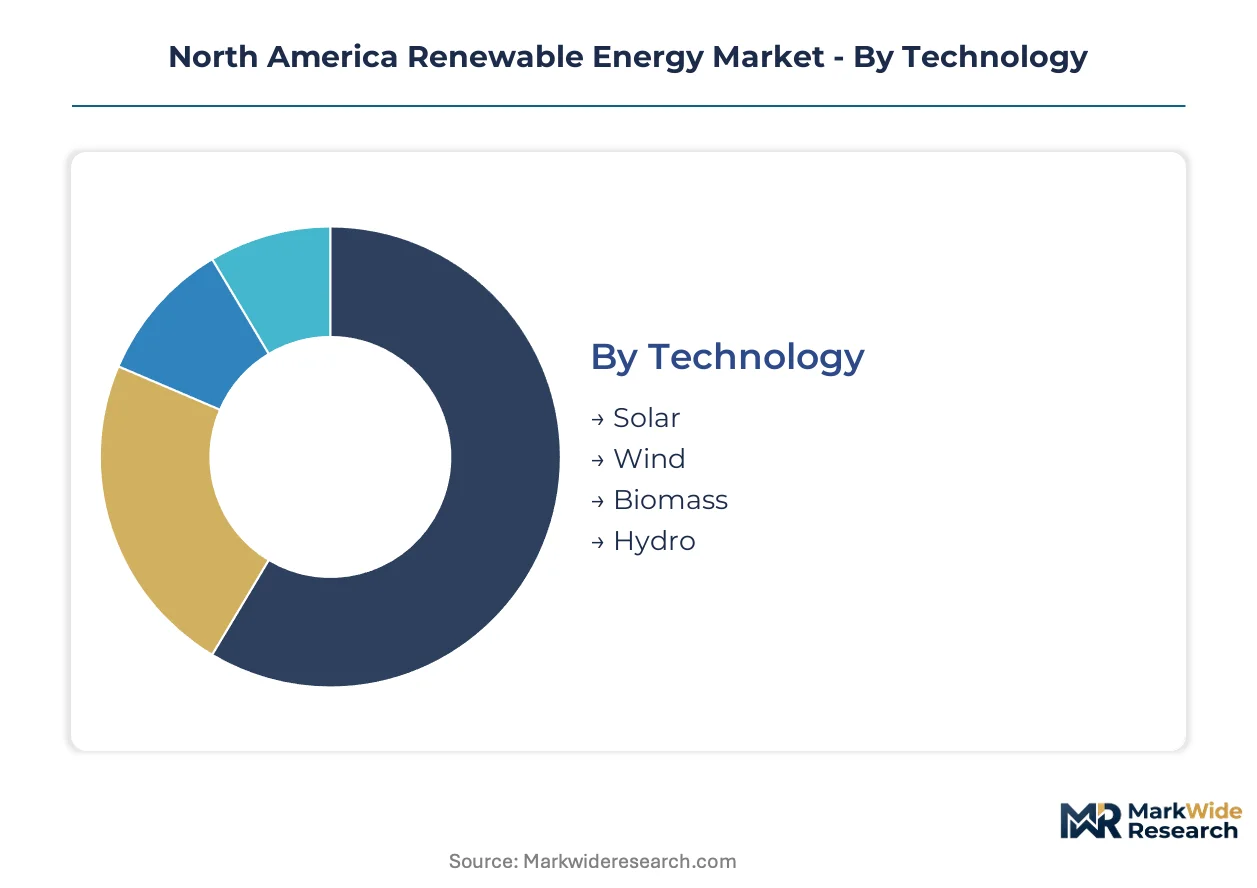
Technology mix and deployment scale determine capital intensity and revenue durability for developers across North American renewable energy markets. Application context shapes interconnection requirements and offtake structures that differentiate project returns.
Technology:
Project developers select technology based on resource availability, land constraints, and IRA tax credit stackability rather than uniform cost curves.
- Solar:Crystalline silicon PV with bifacial modules and single-axis tracking dominates new capacity additions across ERCOT and CAISO interconnection queues. Utility-scale procurement in Texas and California concentrates demand as corporate buyers execute virtual PPAs seeking price hedges against volatile wholesale markets.
- Wind:Horizontal-axis turbines with hub heights exceeding 150 meters access higher wind speeds across the Great Plains corridor. Iowa, Oklahoma, and Kansas anchor onshore deployment where capacity factors exceed 45 percent and transmission access to load centers determines site selection.
- Biomass:Combustion and anaerobic digestion systems serve pulp and paper facilities with combined heat and power configurations in the Southeast and Pacific Northwest.
- Hydro:Run-of-river and small-scale installations retain relevance in the Pacific Northwest and New York where existing dam infrastructure supports modernization rather than greenfield development.
Volume sits with solar; growth tilts toward wind as turbine technology improves capacity factors in marginal resource zones.
Application:
Scale of deployment determines interconnection voltage level, permitting pathway, and offtake contract structure available to developers.
- Utility Scale:Grid-connected projects exceeding 100 MW capacity interconnect at transmission voltage levels and secure long-term PPAs with utilities or corporate offtakers. FERC interconnection queue reforms and regional transmission planning mandates in PJM and SPP territories shape development timelines for these assets.
- Distributed Generation:Behind-the-meter solar PV systems at commercial and industrial facilities reduce demand charge exposure and provide resilience against grid instability. Net metering policy evolution in California, New York, and Illinois creates divergent value propositions for host customers.
- Off-grid:Remote microgrids with solar-battery hybrid configurations serve mining operations, military installations, and rural communities where transmission extension proves uneconomical.
- Combined Heat and Power:Biomass-fueled cogeneration systems integrate with industrial process heat requirements in pulp, paper, and food processing facilities.
Utility scale captures investment volume; distributed generation climbs fastest as commercial electricity rates escalate and battery costs compress.
End User:
Customer creditworthiness and load predictability determine financing terms and contract tenors that developers can secure.
- Residential:Rooftop solar installations with third-party ownership or loan structures depend on state-level net metering policies and utility rate design. California's NEM 3.0 reforms have shifted economics toward battery pairing and self-consumption optimization.
- Commercial:Retail, hospitality, and office building owners pursue distributed solar to manage escalating utility demand charges and demonstrate sustainability commitments to tenants.
- Industrial:Manufacturing facilities with 24/7 load profiles value renewable PPAs for price stability and execute direct procurement through virtual structures. Data center operators in Virginia, Texas, and Arizona anchor gigawatt-scale demand for clean energy matching.
- Government:Federal agencies and state municipalities leverage power purchase agreements to meet clean electricity mandates under executive orders and renewable portfolio standards.
Industrial offtakers dominate contracted capacity; commercial segment expands most quickly as behind-the-meter economics improve.
Service Type:
Value chain positioning determines margin capture and capital intensity for market participants serving project developers and asset owners.
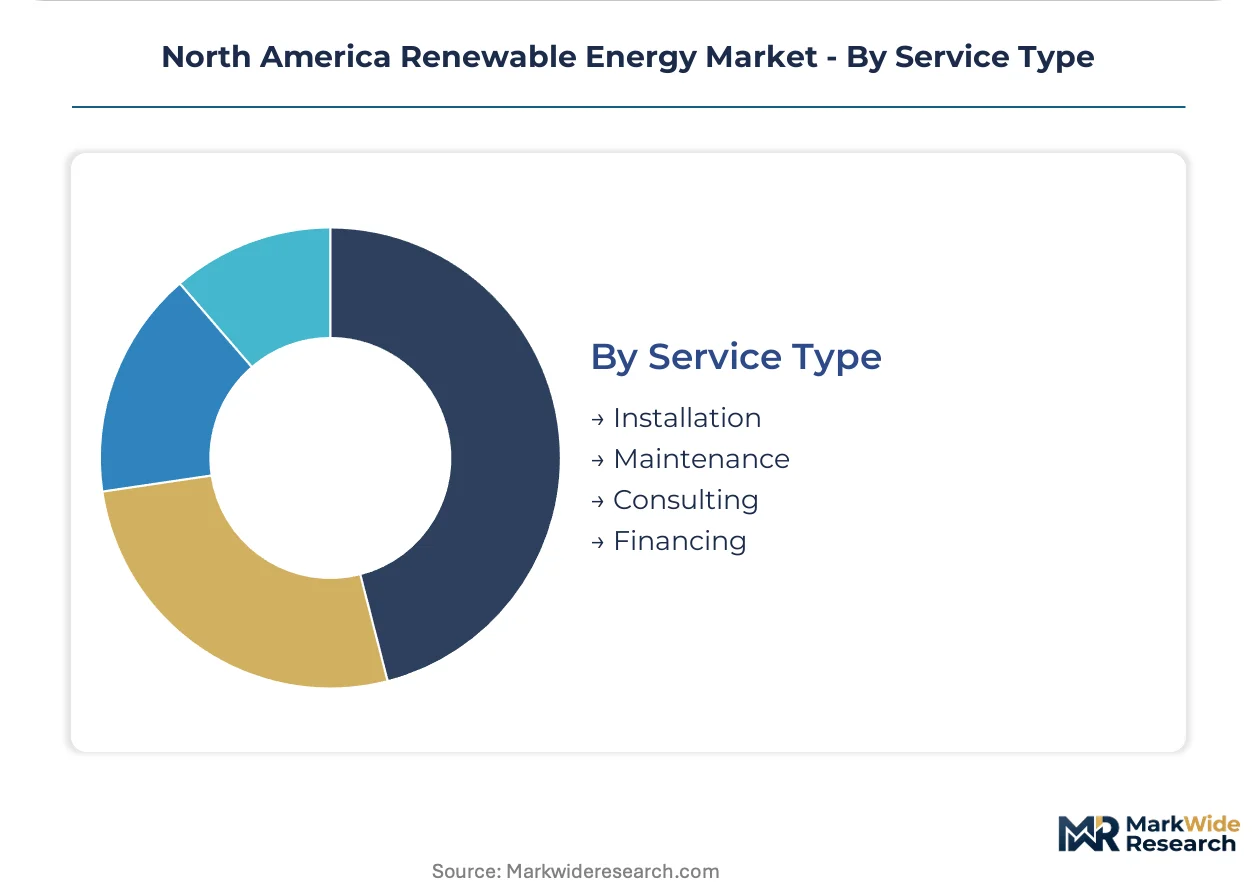
- Installation:Engineering, procurement, and construction contractors manage civil works, electrical installation, and grid interconnection for utility-scale projects. Electrical engineer and technician shortages constrain execution capacity across active development pipelines.
- Maintenance:Operations and maintenance providers optimize energy production through predictive analytics and component replacement scheduling. Long-term service agreements with original equipment manufacturers dominate wind turbine maintenance.
- Consulting:Technical advisory and owner's engineering services support project financing due diligence and interconnection study management.
- Financing:Tax equity investors, green bond issuers, and construction lenders structure capital stacks around IRA production and investment tax credits.
Installation commands revenue scale; financing services gain share fastest as tax credit monetization complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American renewable energy finance and project development activity, with the Texas Gulf Coast corridor concentrating corporate headquarters, engineering talent pools, and capital markets infrastructure that funds deployment across the continent.
United States
Corporate data center load growth in Virginia and Texas drives utility-scale solar procurement, while the EPA's power plant emissions standards under Section 111 accelerate coal retirement timelines. The ERCOT and CAISO interconnection queues concentrate grid-scale battery co-location projects in the Houston-Austin corridor and California's Central Valley.
Canada
Hydropower modernization and offshore wind lease development in Nova Scotia attract capital seeking baseload-clean energy hybrids, with the Canadian Environmental Assessment Agency streamlining federal permitting for transmission-linked projects. Alberta's industrial heartland hosts solar-wind hybrid installations serving oil sands decarbonization commitments.
Mexico
Nearshoring manufacturing investment in Nuevo León and Baja California escalates demand for clean electricity matching, with the Energy Regulatory Commission reforming market rules for private renewable procurement. The Sonora desert corridor concentrates solar export potential toward southwestern US load centers.
North America Renewable Energy Market Competitive Environment
Premium-margin players sit above commodity-margin players across development platform sophistication and balance sheet capacity. The vendor base stratifies between vertically integrated utilities with captive project pipelines and independent power producers competing for interconnection queue positions. Three archetypes dominate: utility-affiliated developers with regulated rate base advantages, pure-play renewables specialists with tax equity structuring expertise, and technology-integrated manufacturers with module supply security. Capacity expansion into battery co-location and strategic partnerships for offtake origination represent the dominant competitive vectors.
Within the utility-affiliated tier, NextEra Energy exemplifies balance sheet-driven platform scale, while Constellation Energy occupies a position bridging nuclear baseload and renewable procurement optimization. Invenergy anchors the independent developer archetype with project origination capabilities across multiple ISO territories.
| Leading Market Players |
|---|
| NextEra Energy |
| Constellation Energy |
| Invenergy |
| EDF Renewables North America |
| EDP Renewables North America |
| Brookfield Renewable Partners |
| Pattern Energy |
| First Solar |
| Clearway Energy |
| Others |
Value Chain & Pricing Dynamics
Electrical engineer and technician concentration in the Houston-Austin corridor drives labor-cost differentials that widen pricing-tier spreads between premium integrated EPC providers and commodity installation contractors bidding on utility-scale solar projects.
Pricing Analysis
Capacity-factor guarantees anchor value-based pricing for utility-scale wind and solar assets, with developers structuring long-term offtake contracts around energy yield commitments rather than capital cost recovery alone. Price differentiation rests on domestic content certification levels and bankability of interconnection queue positions, with IRA bonus credit eligibility commanding material premiums. Cost compression in standard-tier crystalline silicon modules is intensifying because Chinese manufacturing overcapacity floods global spot markets. Industrial offtakers with 24/7 load profiles exhibit lowest price sensitivity, while distributed commercial hosts behind utility rate structures face highest sensitivity to upfront capital requirements.
Supply Chain Analysis
The IRA's phased domestic content bonus credit is reshaping sourcing decisions, forcing developers to weigh bonus credit value against higher crystalline silicon wafer and cell costs from nascent U.S. manufacturing capacity. Polysilicon refining concentrates in China, Malaysia, and Germany, while lithium iron phosphate cathode active material draws from Chinese and South Korean chemical processors. Rare earth permanent magnet supply chains for wind turbines concentrate processing in China, exposing project developers to tariff volatility and export licensing risk. Distribution runs through vertically integrated original equipment manufacturers with captive module assembly and direct EPC contracting arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with balance sheet capacity and upstream manufacturing control emerging as the decisive competitive lever separating premium-margin platform players from commodity developers.
For Market Incumbents: To counter interconnection queue position erosion from independent power producers with tax equity structuring expertise, incumbent utilities should deepen backward integration into battery storage system assembly and secure captive manufacturing partnerships for bifacial module supply. Balance sheet deployment into green hydrogen hub development creates defensible offtake anchors that lock in renewable production volumes before competitors secure queue positions.
For New Entrants and Emerging Players: Proprietary grid interconnection study management software offers a technology-first wedge for entrants lacking legacy queue positions, enabling faster study timeline compression than incumbent EPC relationships permit. White-space targets concentrate in behind-the-meter commercial and industrial solar-battery hybrid installations in states with escalating utility demand charges, particularly manufacturing facilities seeking resilience against grid instability. Direct sales to facility energy managers bypasses utility green tariff program complexity.
For Investors and Strategic Acquirers: The window for entry favors independent power producers with contracted development pipelines and established tax equity investor relationships rather than greenfield development platforms. Long-term viability hinges on securing interconnection queue positions in ERCOT and CAISO territories where transmission expansion timelines align with project completion schedules. The signal to watch is FERC Order 2023 implementation velocity across regional transmission organizations, as faster study timelines unlock trapped development value.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Virtual PPAs with technology sector offtakers anchor revenue certainty for merchant solar projects in Texas and California. |
| Backward Integration into Storage | In-house lithium iron phosphate system assembly captures IRA domestic content bonus credits and reduces EPC margin leakage. |
| Green Hydrogen Hub Development | DOE Section 45V production tax credits create dedicated offtake anchors for renewable projects in the Midwest and Gulf Coast. |
| Interconnection Queue Position Acquisition | Purchased study positions in PJM and SPP territories accelerate project timelines versus greenfield queue entry. |
| Technology Licensing Partnership | Proprietary wind turbine design agreements with European OEMs differentiate capacity factors in marginal Great Plains resource zones. |
Study Parameters
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings, with secondary validation drawing from EIA generation capacity databases, IEA renewable energy market reports, FERC interconnection queue filings, and project finance transaction databases. Primary fieldwork combined structured interviews with tax equity investors and original equipment manufacturer commercial leads. Bottom-up project pipeline aggregation and top-down regulatory impact modeling were cross-referenced for triangulation.
Historical capacity deployment patterns across the analysis window anchored forward projections, with the forecast framework modeling technology mix, generation capacity tier, project scale, regulatory framework, and regional grid type as core segmentation dimensions. CAGRs were derived from installed capacity build-out trajectories and capital cost curve assumptions, incorporating IRA tax credit phase-down schedules and domestic content bonus credit eligibility timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unanticipated NEPA timeline extensions, endangered species act litigation outcomes, and raw material tariff escalations beyond current policy trajectories. Forecasts reflect documented assumptions regarding interconnection queue reform implementation and transmission expansion permitting velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Marine Energy Market
Renewable Energy
South Asia Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
South America Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
Solar Autoclave Market