
 Africa Renewable Energy Market | 2026-2036
Africa Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Renewable Energy Market Analysis
Utility-scale power purchasers is reorganizing procurement priorities away from diesel backup toward hybrid renewable installations. ACWA Power anchors its position through captive supply of desalination-linked solar in Morocco and South Africa. Vestas Wind Systems A/S dominates turbine installation capacity across Egypt's Gulf of Suez corridor. JinkoSolar leverages polycrystalline module cost leadership to compete for East African distributed generation tenders.
Africa renewable energy encompasses solar photovoltaic, wind turbine, biomass combustion, and run-of-river hydropower systems engineered for grid-connected, mini-grid, or off-grid deployment, typically operating at 11-33 kV distribution voltage with battery storage integration for frequency regulation. Its primary purpose displaces fossil-fuel baseload with dispatchable clean capacity across transmission-constrained economies. Solar technology occupies the largest share of installed capacity, though wind commands premium margins in North African trade-wind zones. The application split reveals power generation as the mature revenue pool while electrification of rural settlements represents the fastest-growing addressable segment. Government end users sustain the deepest project pipelines through sovereign-guaranteed offtake structures.
Egypt's New and Renewable Energy Authority, South Africa's National Energy Regulator, and Kenya's Energy and Petroleum Regulatory Authority collectively shape licensing timelines, local-content thresholds, and tariff benchmarks that determine developer returns. South Africa's Integrated Resource Plan and Egypt's feed-in tariff decree establish binding capacity allocation schedules that de-risk long-dated equity commitments. Stakeholders must monitor currency convertibility regimes and sovereign offtake creditworthiness as primary variables in capital allocation decisions.
Market Dynamics
Utility-scale developers across Egypt, South Africa, and Morocco are pivoting procurement toward hybrid solar-plus-storage configurations as grid instability and diesel price volatility erode conventional backup economics. This structural reconfiguration is compressing project development timelines and reshaping capital allocation priorities across the continent.
Growth Catalysts
- South Africa's Renewable Energy Independent Power Producer Procurement Programme:Binding capacity schedules de-risk long-dated equity commitments and redirect institutional capital toward utility-scale solar and wind installations.
- Mining sector off-takers:Energy-intensive extractive operations in the Northern Cape and Limpopo are scaling captive renewable procurement to displace diesel-fired backup generation.
- East Africa's decentralized solar-home-system corridor:Kenya, Tanzania, and Ethiopia concentrate demand for pay-as-you-go electrification models reaching rural settlements beyond grid extension.
Market Restraints
- Currency convertibility regimes:Local-currency revenue exposure in Egyptian pounds and South African rand creates hedging costs that inflate developer hurdle rates.
- Polycrystalline module supply concentration:East African distributed generation tenders remain vulnerable to Chinese manufacturing output fluctuations and shipping cost spikes.
- Grid interconnection queues:Egypt's New and Renewable Energy Authority licensing timelines stretch 18-24 months for utility-scale projects, locking working capital in pre-construction phases.
Strategic Opportunities
- Desalination-linked solar in Morocco:ACWA Power's captive supply model demonstrates scalable integration of water-energy nexus projects along coastal industrial zones.
- Feed-in tariff reforms:Egypt's revised tariff decree creates price certainty for bilateral power purchase agreements with state-owned offtakers.
- Biomass combustion mini-grids:Agricultural residue-to-power systems in Ethiopia's sugar belt offer dispatchable baseload alternatives to intermittent solar.
Industry Challenges
- Local-content threshold compliance:South Africa's National Energy Regulator mandates domestic manufacturing participation that strains developer procurement flexibility.
- Battery storage integration complexity:Frequency regulation and ramp-rate control specifications vary across Kenya's Energy and Petroleum Regulatory Authority jurisdictions, fragmenting engineering standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Renewable Energy Market |
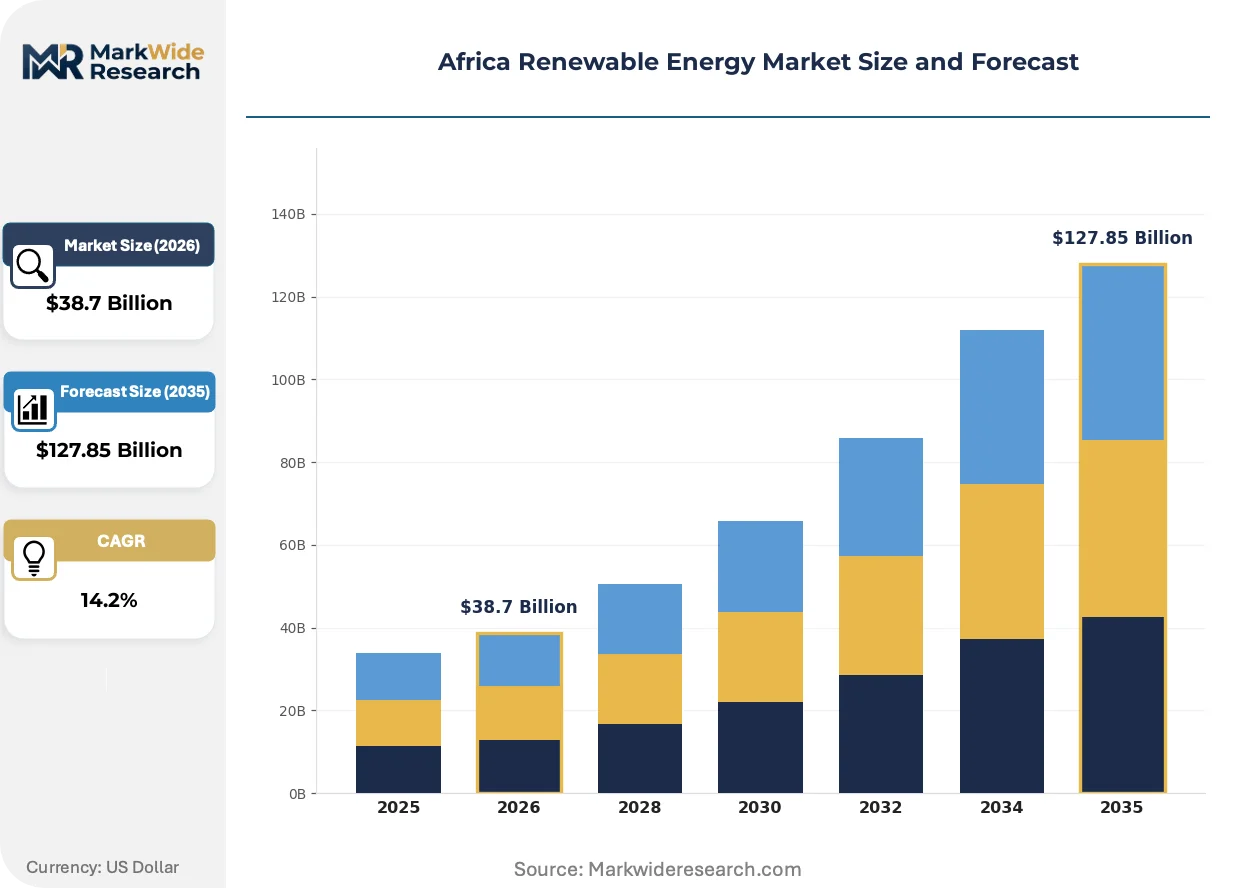
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Power Generation, Electrification, Heating, Transportation End User: Residential, Commercial, Industrial, Government Investment Stage: Early-Stage, Growth, Maturity, Expansion |
| Companies Covered | EDF Renewables, Acciona SA, Vestas Wind Systems A/S, ENGIE Africa, Juwi Holding AG, ACWA Power, JinkoSolar, Sun King, Enel Green Power S.p.A., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Renewable Energy Market Emerging Trajectories
Technology convergence and procurement model evolution are compressing project economics while regulatory frameworks accelerate standardization. These forces collectively reshape competitive positioning across generation, storage, and distribution layers.
Solar photovoltaic module technology is miniaturizing through higher-efficiency monocrystalline PERC and TOPCon cell architectures. Mining and industrial off-takers in South Africa's platinum and manganese belts are adopting these denser panels to maximize generation per hectare of constrained land. This density improvement is miniaturizing the physical footprint of utility-scale installations, reducing land acquisition costs and environmental permitting friction.
Egypt's feed-in tariff decree and South Africa's Integrated Resource Plan establish binding capacity allocation schedules that standardize offtake risk pricing. These frameworks compress developer equity return requirements by substituting sovereign creditworthiness for merchant price exposure. North African trade-wind zones and East African decentralized corridors respond with divergent technology mixes—utility-scale wind in Egypt versus solar-home-systems in Kenya.
Power purchasers are consolidating procurement functions under centralized energy management offices that negotiate multi-site renewable supply agreements. Industrial clusters in Morocco's Oujda region and South Africa's Richards Bay are displacing fragmented site-level diesel contracting with aggregated hybrid solar-storage tenders. This buyer concentration is most visible in mining verticals where energy costs constitute 15-30 percent of operating expenditure.
Africa Renewable Energy Market Segmentation
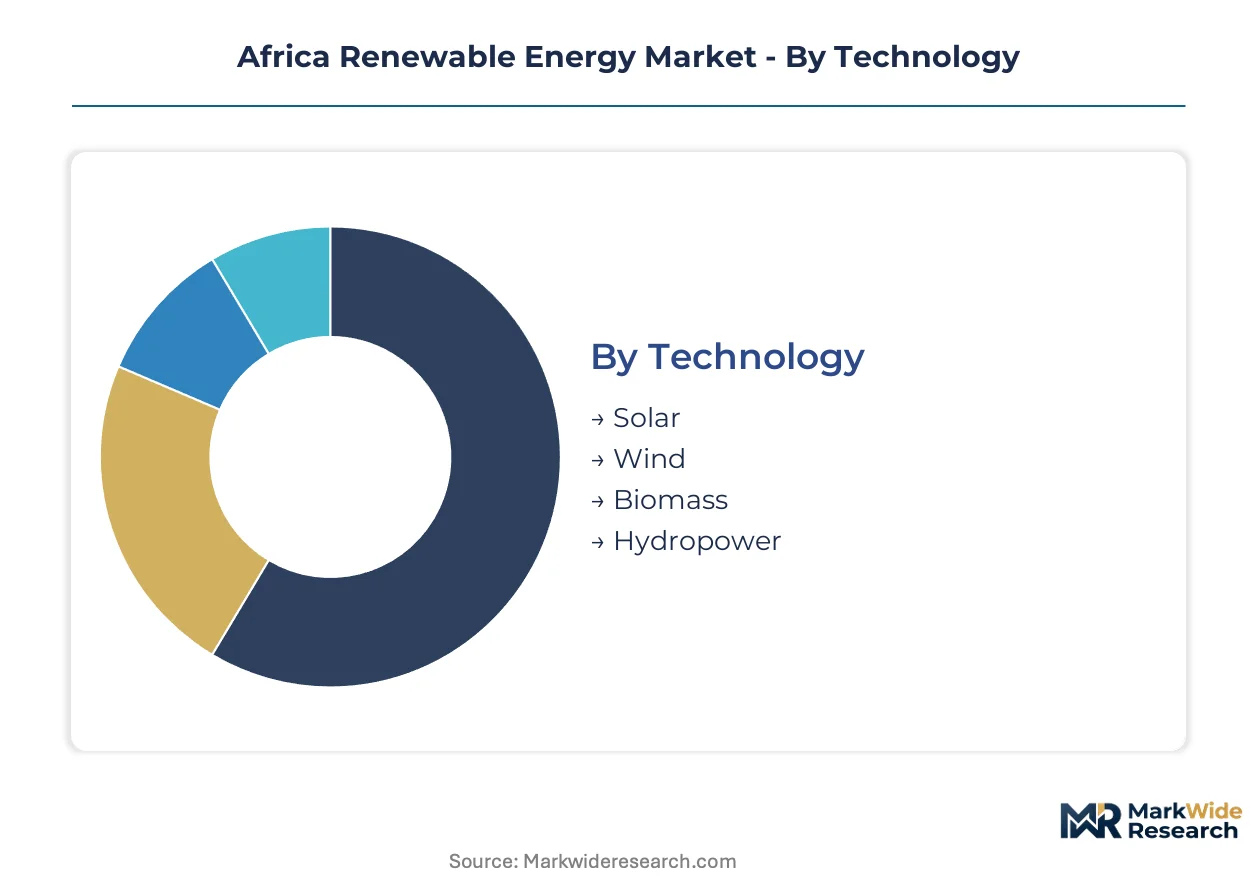
Technology and application splits across Africa's renewable energy market reveal divergent capital intensity profiles and regulatory exposure. Segment boundaries matter for procurement strategy, as solar photovoltaic systems face fundamentally different grid interconnection queues than run-of-river hydropower.
Technology:
Substitution pressure concentrates most intensely on biomass combustion systems, where agricultural residue supply chains compete with alternative fuel uses and direct land conversion.
- Solar:Photovoltaic modules utilizing monocrystalline PERC and TOPCon cell architectures dominate installed capacity. Mining sector off-takers in South Africa's Northern Cape and Limpopo provinces are scaling captive solar-plus-storage installations to displace diesel-fired backup generation, compressing project payback periods through land-constrained high-density panel deployment.
- Wind:Horizontal-axis turbines engineered for North African trade-wind zones command premium margins in Egypt's Gulf of Suez corridor. Vestas Wind Systems A/S anchors turbine installation capacity through utility-scale projects benefiting from feed-in tariff price certainty under Egypt's revised decree.
- Biomass:Agricultural residue-to-power systems in Ethiopia's sugar belt offer dispatchable baseload alternatives, though feedstock competition from alternative fuel uses constrains scaling.
- Hydropower:Run-of-river configurations bypass reservoir construction timelines but remain exposed to seasonal flow variability across East African river basins.
Solar retains volume leadership; wind holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive utility-scale installations from distributed generation models with minimal grid interconnection requirements.
- Power Generation:Grid-connected utility-scale projects operating at 11-33 kV distribution voltage represent the mature revenue pool. South Africa's Renewable Energy Independent Power Producer Procurement Programme and Egypt's feed-in tariff decree establish binding capacity schedules that de-risk long-dated equity commitments.
- Electrification:Off-grid and mini-grid deployment reaching rural settlements beyond transmission extension constitutes the fastest-climbing segment. Kenya, Tanzania, and Ethiopia concentrate demand for pay-as-you-go solar-home-systems with battery storage integration.
- Heating:Solar thermal collectors and biomass boilers serve industrial process heat requirements in Morocco's coastal industrial zones.
- Transportation:Electric vehicle charging infrastructure linked to renewable generation remains nascent, constrained by grid stability limitations and battery storage integration complexity.
Power generation commands current revenue concentration; electrification is gaining share fastest.
End User:
Customer type determines offtake risk pricing, with sovereign-guaranteed structures compressing equity return requirements relative to merchant exposure.
- Residential:Distributed solar-home-systems in East Africa's decentralized corridor rely on pay-as-you-go financing models. Currency convertibility regimes in Egyptian pounds and South African rand create hedging costs that inflate developer hurdle rates for local-currency revenue exposure.
- Commercial:Agricultural processing and cold-chain operators in Ethiopia and Kenya are consolidating procurement under centralized energy management offices.
- Industrial:Mining sector off-takers in South Africa's platinum and manganese belts displace fragmented site-level diesel contracting with aggregated hybrid solar-storage tenders, where energy costs constitute 15-30 percent of operating expenditure.
- Government:Sovereign-guaranteed offtake structures through Egypt's New and Renewable Energy Authority and South Africa's National Energy Regulator sustain the deepest project pipelines.
Government end users anchor project volume; industrial offtakers are expanding most quickly.
Investment Stage:
Supply concentration in Chinese polycrystalline module manufacturing creates vulnerability windows for early-stage projects exposed to shipping cost spikes and output fluctuations.
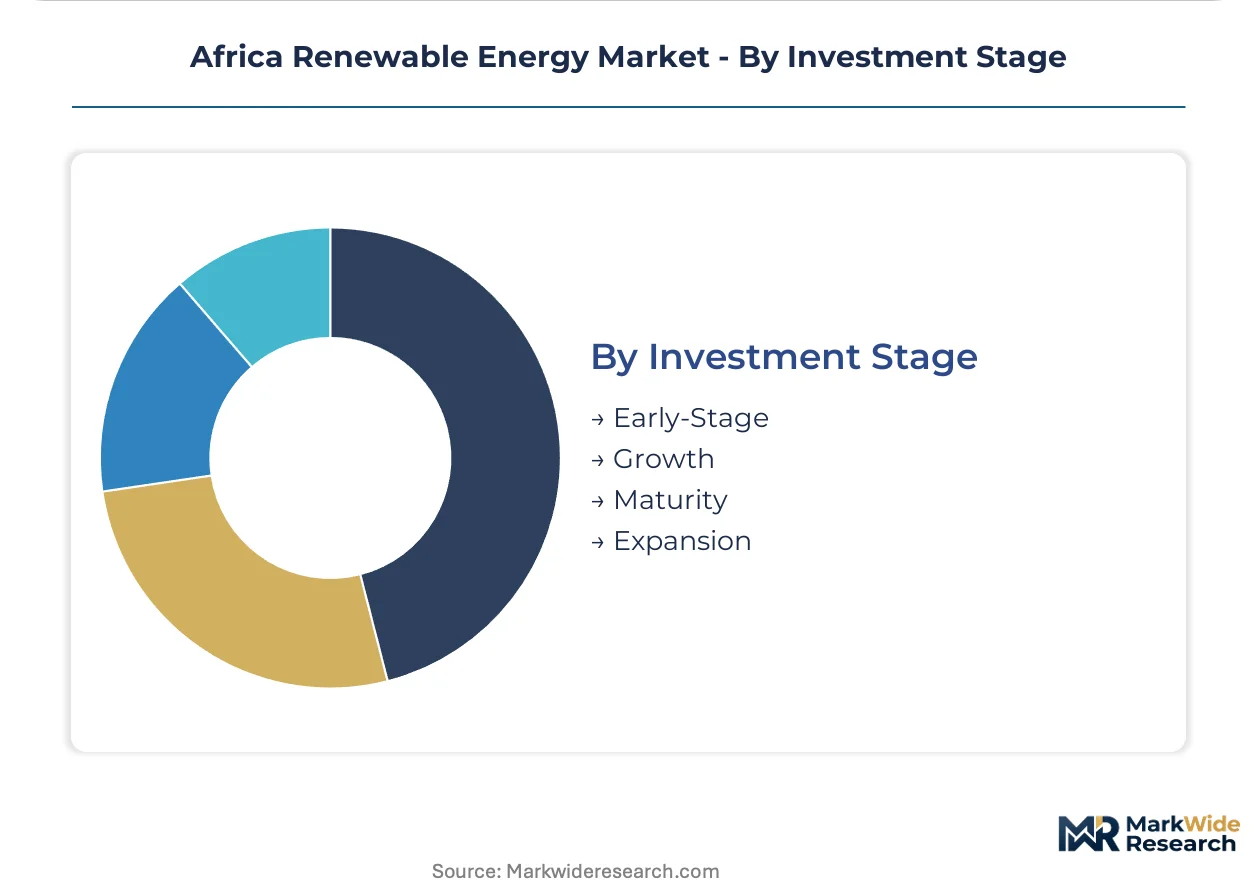
- Early-Stage:Pre-construction phases in Egypt face 18-24 month licensing timelines through the New and Renewable Energy Authority, locking working capital before revenue generation.
- Growth:Utility-scale solar and wind installations in Morocco and South Africa benefit from standardized offtake frameworks that compress development timelines.
- Maturity:Operational assets in Kenya's solar-home-system corridor face pay-as-you-go portfolio consolidation as customer acquisition costs rise.
- Expansion:Hybrid solar-plus-storage retrofits and capacity additions target grid instability and diesel price volatility across mining and industrial clusters.
Growth-stage projects absorb dominant capital flows; expansion-stage retrofits show the steepest acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
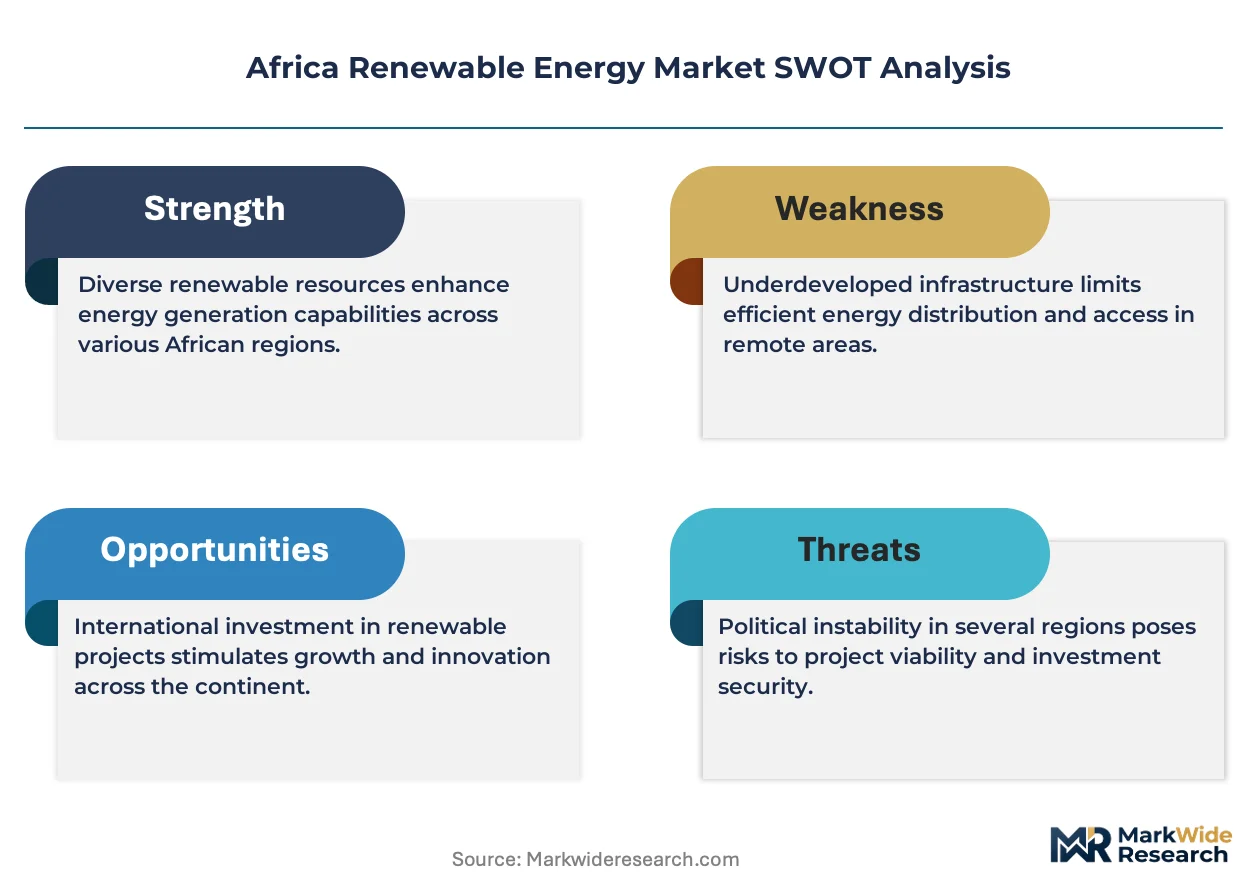
Module assembly and turbine manufacturing capacity concentrates in Chinese and European supply bases serving African project pipelines. Developer equity and construction finance flows through Dubai, London, and Johannesburg financial centers. Grid interconnection bottlenecks and currency volatility create divergent risk profiles across North, East, and Southern African markets.
South Africa
Mining houses in the Northern Cape and Limpopo provinces are aggregating captive solar-plus-storage procurement to displace diesel backup generation. The Renewable Energy Independent Power Producer Procurement Programme establishes binding capacity schedules that compress developer equity return requirements. Richards Bay industrial clusters are consolidating fragmented site-level energy contracting under centralized procurement offices.
Egypt
Utility-scale wind developers target Gulf of Suez trade-wind zones with horizontal-axis turbine installations. The New and Renewable Energy Authority revised feed-in tariff decree creates price certainty for bilateral power purchase agreements with state-owned offtakers. Licensing timelines stretching 18-24 months lock working capital in pre-construction phases before revenue generation begins.
Morocco
Desalination-linked solar projects along coastal industrial zones integrate water-energy nexus infrastructure. The national utility ONEE anchors offtake structures for utility-scale installations serving phosphate processing and chemical manufacturing clusters. Oujda region industrial parks are displacing conventional backup systems with hybrid renewable tenders aggregating multi-site demand.
Kenya
Pay-as-you-go solar-home-system providers reach rural settlements beyond grid extension in the decentralized electrification corridor. The Energy and Petroleum Regulatory Authority governs licensing timelines and local-content thresholds that determine developer returns. Agricultural processing and cold-chain operators in the Rift Valley are consolidating procurement under centralized energy management offices.
Ethiopia
Agricultural residue-to-power systems in the sugar belt offer dispatchable baseload alternatives to intermittent solar generation. The Ethiopian Electric Power utility channels sovereign-guaranteed offtake toward utility-scale installations. Biomass combustion mini-grids serving rural settlements face feedstock competition from alternative fuel uses and direct land conversion pressures.
Africa Renewable Energy Market Vendor Landscape
Concentration sits with integrated utility-scale developers possessing captive construction finance and sovereign offtake relationships. The competitive field stratifies across three archetypes: European turbine and module suppliers with technology licensing networks, Gulf-based independent power producers with desalination integration expertise, and Chinese panel manufacturers with cost leadership in distributed generation tenders. Dominant competitive moves include strategic partnerships anchoring multi-project development pipelines and backward integration into module assembly to control supply security.
Among European utility-scale specialists, EDF Renewables and ENGIE Africa exemplify the integrated developer archetype combining project finance access with construction execution capability. Vestas Wind Systems A/S anchors turbine supply positioning across North African wind corridors. ACWA Power represents the Gulf-based independent power producer model with demonstrated scale in desalination-linked solar integration.
| Leading Market Players |
|---|
| EDF Renewables |
| Acciona SA |
| Vestas Wind Systems A/S |
| ENGIE Africa |
| Juwi Holding AG |
| ACWA Power |
| JinkoSolar |
| Sun King |
| Enel Green Power S.p.A. |
| Others |
Supply Flow & Price Mechanics
South Africa's Renewable Energy Independent Power Producer Procurement Programme gates both developer qualification and tariff benchmarking, compressing equity return requirements for compliant bidders while excluding non-compliant projects from sovereign-guaranteed offtake structures. This regulatory anchor simultaneously shapes supply chain procurement decisions and price differentiation across utility-scale and distributed generation segments.
Pricing Analysis
Egypt's revised feed-in tariff decree dictates the pricing tier structure for bilateral power purchase agreements, with sovereign-backed tariffs compressing developer hurdle rates below merchant market exposure. Price differentiation rests on local-content compliance thresholds and grid interconnection voltage class, with 11-33 kV distribution projects commanding premium structuring. Cost compression in distributed solar tenders is intensifying because Chinese polycrystalline module output fluctuations expose East African developers to margin volatility. Mining sector off-takers in South Africa's Northern Cape exhibit the lowest price sensitivity due to diesel displacement economics, while residential pay-as-you-go customers in Kenya face acute affordability constraints.
Supply Chain Analysis
Red Sea transit corridors underwrite module delivery schedules to North African project sites, with Suez Canal congestion creating chokepoint exposure for just-in-time construction timelines. Manufacturing concentration centers on China for photovoltaic cells, Vietnam for module assembly, and Denmark for horizontal-axis turbine nacelles. Raw material dependencies span polysilicon feedstock, lithium-ion battery cells, and rare-earth magnet supply for permanent-magnet generators. Single-source vulnerability concentrates in Chinese ingot wafering capacity. Distribution runs through Dubai-based EPC contractors serving Gulf of Suez wind corridors and Johannesburg-financed developers targeting South African mining off-takers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's renewable energy market is recovering from sovereign offtake creditworthiness compression, with Egypt's feed-in tariff reforms and South Africa's procurement programme restarts providing cyclical momentum for capital deployment.
For Market Incumbents: Consolidate project development pipelines around captive construction finance relationships and sovereign-guaranteed offtake structures to defend against emerging Gulf-based IPPs with desalination integration expertise. Prioritize backward integration into battery storage system assembly to control supply security against Chinese lithium-ion cell export restrictions. Anchor multi-site hybrid solar-plus-storage tenders with mining sector off-takers in South Africa's platinum and manganese belts.
For New Entrants and Emerging Players: Kenya's Energy and Petroleum Regulatory Authority certification fast-track for solar-home-system providers opens white-space penetration in East Africa's decentralized electrification corridor. Target agricultural residue-to-power mini-grids in Ethiopia's sugar belt where feedstock supply chains remain underdeveloped. Pursue pay-as-you-go financing partnerships with mobile network operators to bypass traditional banking infrastructure gaps.
For Investors and Strategic Acquirers: Carve-out targets emerge from European utility-scale developers with stranded project pipelines in Egypt's 18-24 month licensing queues. Long-term viability hinges on currency hedging capability against Egyptian pound and South African rand convertibility regimes. Monitor feed-in tariff decree amendments as the inflection signal for bilateral power purchase agreement repricing windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Deployment | Mining sector off-takers in South Africa's Northern Cape displace diesel backup with integrated renewable baseload. |
| Desalination-Linked Solar Integration | Morocco's coastal industrial zones demonstrate scalable water-energy nexus projects under ONEE offtake structures. |
| Pay-as-You-Go Financing Expansion | Kenya's solar-home-system providers reach rural settlements beyond grid extension through mobile payment platforms. |
| Local-Content Threshold Compliance | South Africa's National Energy Regulator mandates domestic manufacturing participation that strains developer procurement flexibility. |
| Feed-in Tariff Reform Engagement | Egypt's New and Renewable Energy Authority revised decree creates price certainty for state-owned bilateral power purchase agreements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IEA renewable energy databases, EIA international energy statistics, and African Development Bank infrastructure financing disclosures. Interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators informed demand-side validation. Supply-side perspectives came from module manufacturers, turbine OEMs, and battery storage integrators. Secondary sources include FERC-equivalent filings from Egypt's New and Renewable Energy Authority and South Africa's National Energy Regulator. Bottom-up project pipeline aggregation triangulates against top-down macroeconomic capacity forecasts.
Segmentation dimensions modeled span technology type, application category, end-user archetype, and investment stage across the projection horizon. The analytical framework incorporates fuel source substitution dynamics, regulatory framework evolution, and regional grid interconnection constraints. CAGRs derive from capacity deployment trajectories, tariff reform implementation schedules, and mining sector procurement cycle timing. Industry-specific inputs include solar resource irradiance mapping, wind speed measurement campaigns, and biomass feedstock availability assessments.
Decision-makers should treat outputs as directional under assumptions of sustained sovereign offtake creditworthiness and stable currency convertibility regimes; material deviation would warrant model refresh. Forecasts reflect base-case capacity allocation schedules, licensing timeline normalization, and module cost trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Global Green Energy Market