
 Seawater Cooling System Market | 2026-2036
Seawater Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Seawater Cooling System Market Analytics
Data center cooling is broadening the addressable base for seawater cooling systems beyond traditional marine and power applications. Alfa Laval leverages its plate heat exchanger expertise to dominate coastal hyperscale projects. Wärtsilä anchors its position through integrated marine power and thermal management packages. GEA Group differentiates via corrosion-resistant alloy portfolios suited to high-salinity environments.
A seawater cooling system extracts thermal energy from industrial processes by circulating ocean water through heat transfer equipment, typically employing titanium or super-duplex stainless steel components to withstand chloride-induced corrosion at salinities near 35 parts per thousand. Open-cycle configurations remain the installed base majority, though closed-cycle systems are capturing margin pools where thermal discharge regulations restrict direct seawater return. Heat exchangers command the largest product category share, while piping systems face substitution pressure from modular skid-mounted designs that reduce on-site welding and commissioning duration.
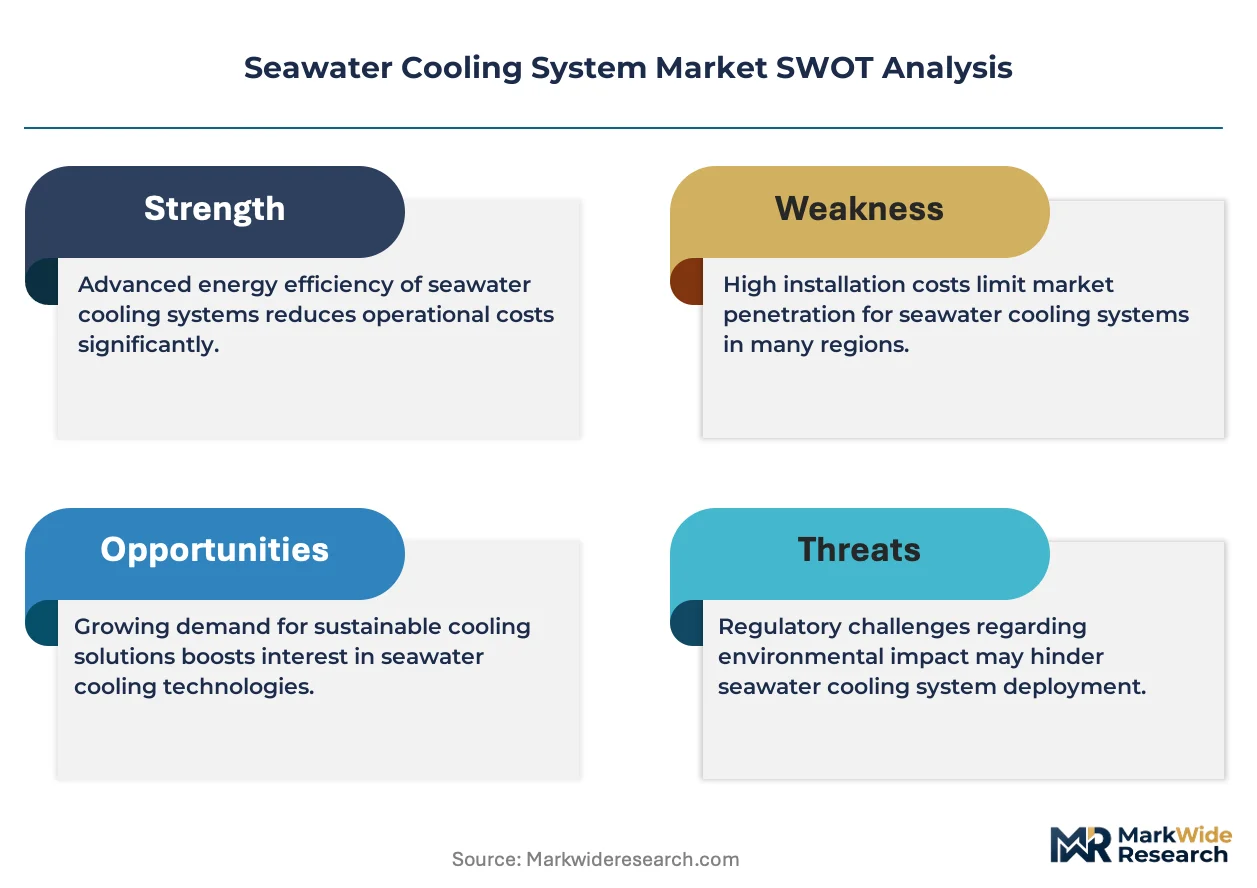
The EPA's Clean Water Act Section 316(b) rules on cooling water intake structures shape US product standards, while the EU F-Gas Regulation accelerates displacement of synthetic refrigerant-based alternatives in coastal European industry. China's MEE enforces stricter thermal discharge limits near marine protected zones. Stakeholders must weigh capital intensity against operational savings as regulatory baselines tighten and coastal siting permits grow more contested.
Market Dynamics
Data center operators along coastlines are accelerating seawater cooling adoption to slash energy intensity, while tightening thermal discharge rules under the EU Green Deal and China's MEE reshape system design requirements and site permitting timelines.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Tightening thermal discharge rules are forcing coastal facilities to upgrade or install closed-cycle seawater cooling systems to maintain operating licenses.
- Hyperscale data center clustering:China's eastern seaboard facilities are concentrating near tidal resources to exploit natural cooling capacity and reduce mechanical refrigeration loads.
- Titanium heat exchanger advances:Improved fabrication techniques for corrosion-resistant alloys are extending equipment lifespans in high-salinity environments above 35 parts per thousand.
Market Restraints
- Titanium and super-duplex steel price volatility:Raw material cost swings for chloride-resistant alloys compress margins on large-capacity heat exchanger contracts.
- Coastal permitting congestion:Contested siting approvals in marine protected zones delay project commissioning and concentrate execution risk with specialized EPC contractors.
- EPA Section 316(b) compliance burden:Cooling water intake structure rules impose expensive fish protection technologies that inflate capital intensity for open-cycle installations.
Strategic Opportunities
- Modular skid-mounted system penetration:Pre-fabricated designs reduce on-site welding duration and open the market to buyers lacking specialized marine construction capabilities.
- Closed-cycle displacement of open-cycle base:Regulatory restrictions on direct seawater return create upgrade demand among existing coastal power and industrial facilities.
- EU F-Gas Regulation tailwind:Synthetic refrigerant phase-down mandates accelerate displacement of compressor-based alternatives with seawater heat rejection in coastal European industry.
Industry Challenges
- Marine corrosion engineering talent scarcity:Specialized expertise in chloride-induced degradation mechanisms remains concentrated among aging technical specialists at equipment OEMs.
- Legacy system integration complexity:Retrofitting seawater circuits into existing industrial plants requires custom piping configurations that extend commissioning timelines.
- ISO 15156/NACE MR0175 certification bottlenecks:Sour service material qualification delays for super-duplex components constrain supplier throughput during project surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seawater Cooling System Market |
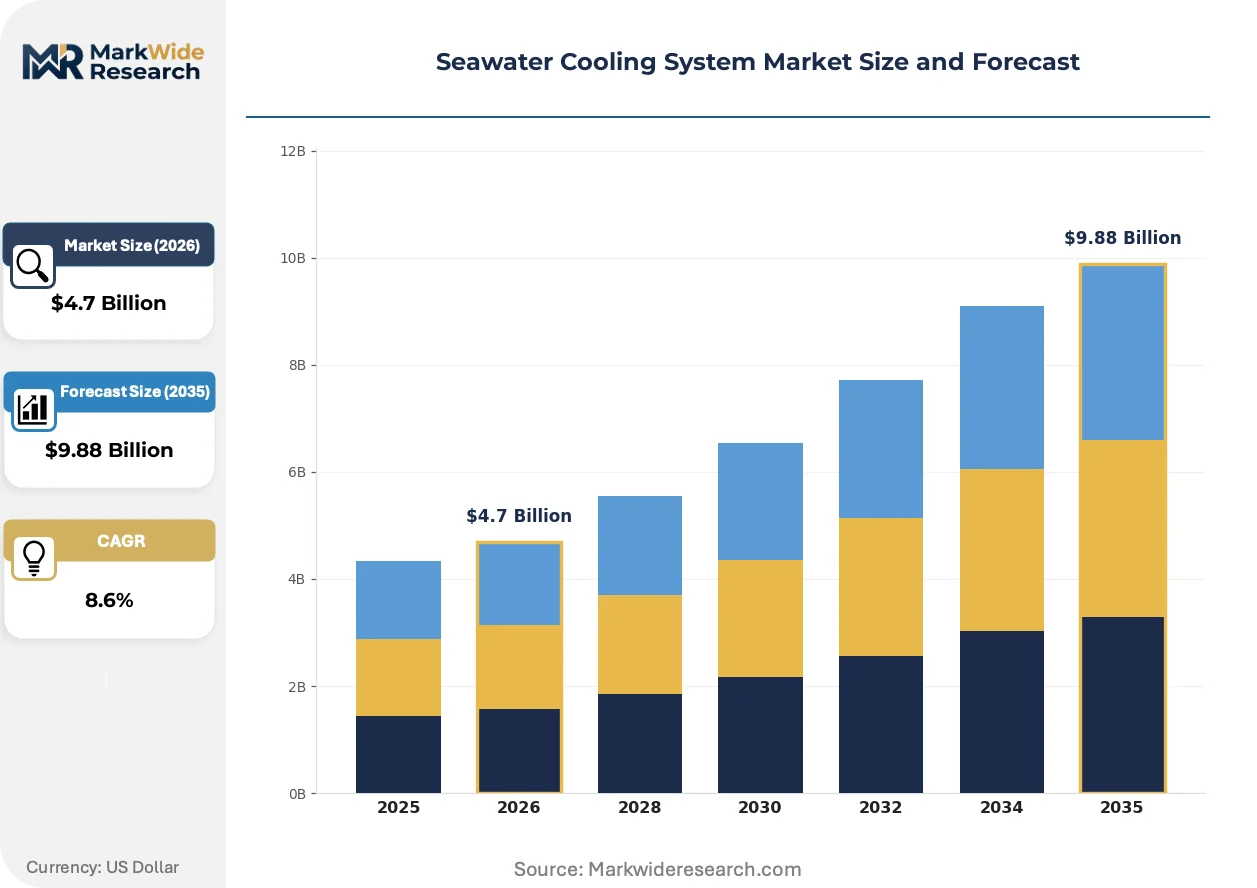
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Pumps, Piping Systems, Valves Application: Power Generation, Marine Cooling, Industrial Processes, HVAC End User: Power Plants, Marine Vessels, Industrial Facilities, Data Centers Technology: Open-Cycle Systems, Closed-Cycle Systems, Direct Cooling, Indirect Cooling |
| Companies Covered | Alfa Laval, Wärtsilä, GEA Group, SPX Flow, TRAC Ecological, Orion Machinery, VIRIDIS Engineering, EJ Bowman, Kelvion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seawater Cooling System Market Evolving Landscape
Equipment suppliers are converging on modular architectures and corrosion-resistant material platforms that compress deployment timelines while regulatory pressure on thermal discharge reshapes competitive positioning between open and closed-cycle configurations.
Super-duplex stainless steel heat exchanger bundles are expanding into hyperscale data center applications as facility operators prioritize 25-year service intervals in salt-air environments. Coastal operators in Northern Europe and East Asia are specifying these alloys for primary cooling circuits to eliminate mid-life replacement cycles. The technology is expanding into markets previously served by coated carbon steel systems, compressing the addressable base for conventional marine-grade equipment.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is redirecting coastal industrial investment toward seawater-based heat rejection systems. Chemical processors and cold storage operators in Spain, Italy, and Greece are abandoning synthetic refrigerant loops in favor of direct ocean cooling or secondary glycol circuits. Heat exchanger manufacturers with EU-wide service networks are capturing this displacement demand through turnkey thermal management packages.
Buyer preference for performance-guaranteed service contracts is displacing traditional equipment-only procurement in large coastal installations. Data center operators and marine terminal developers are transferring operational risk to OEMs through decade-long thermal performance agreements. This contracting evolution is most visible in the North Sea corridor and China's Bohai Economic Rim, where project finance requirements favor predictable opex structures over capital-heavy balance sheet entries.
Seawater Cooling System Market Segmentation
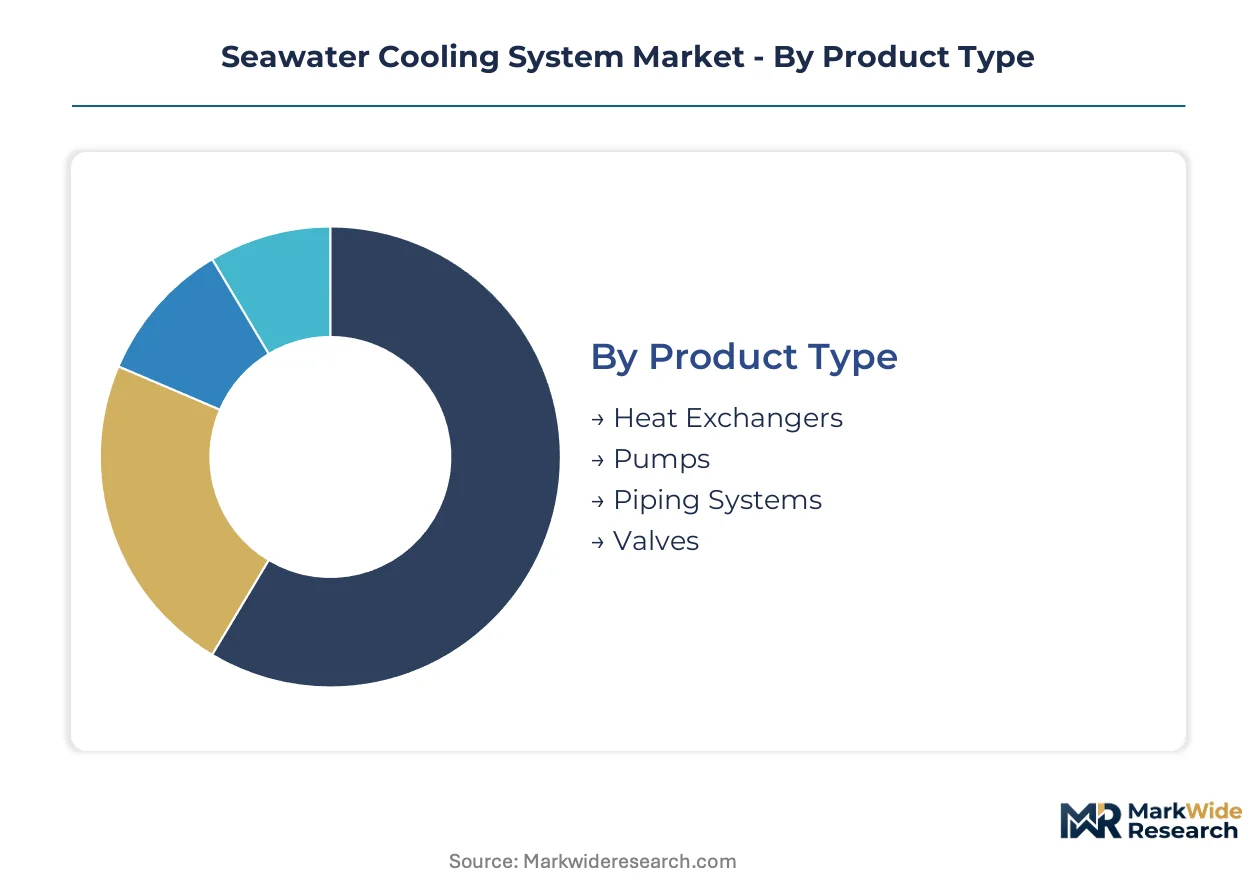
Seawater cooling system architecture fragments across hardware layers, thermal cycles, and deployment contexts. Each dimension carries distinct margin profiles and regulatory exposure. Understanding integration depth across these categories clarifies where capital concentrates versus where upgrade cycles accelerate.
Product Type:
Standalone hardware commands replacement demand, while skid-mounted assemblies embed multiple product classes into single procurement decisions.
- Heat Exchangers:Titanium and super-duplex stainless steel bundles transfer thermal energy between process fluids and seawater circuits. Data center operators in China's Bohai Economic Rim specify these for 25-year service intervals in salt-air environments, prioritizing corrosion resistance over first-cost savings.
- Pumps:Centrifugal and axial flow designs circulate high-salinity water at flow rates exceeding 50,000 cubic meters per hour in coastal power installations. Demand clusters along Spain's Mediterranean coast where EU F-Gas Regulation compliance is forcing synthetic refrigerant displacement toward ocean-based heat rejection.
- Piping Systems:Modular carbon steel and alloy distribution networks face substitution pressure from pre-fabricated skids.
- Valves:Titanium-bodied isolation and control components regulate flow in chloride-rich environments.
Volume placements concentrate in heat exchangers; the faster expansion belongs to pumps as closed-cycle retrofits multiply circulation requirements.
Application:
Cost-tier stratification separates mission-critical thermal management from commodity comfort cooling, with regulatory intensity rising toward the top.
- Power Generation:Baseload and peaking plants deploy massive once-through or recirculating systems to condense turbine exhaust steam. US facilities face EPA Section 316(b) compliance costs for fish protection technologies at cooling water intakes, inflating capital intensity for open-cycle configurations.
- Marine Cooling:Propulsion and auxiliary systems aboard cargo vessels and cruise ships reject engine heat to surrounding ocean. Shipyards in South Korea and Japan specify compact plate heat exchangers to meet IMO energy efficiency mandates while minimizing machinery space claims.
- Industrial Processes:Refineries, petrochemical complexes, and desalination plants integrate seawater circuits into multi-stage thermal operations.
- HVAC:District cooling networks in coastal cities leverage ocean thermal mass to reduce compressor-based refrigeration loads.
Power generation retains the largest installed base; industrial processes are climbing the fastest as chemical processors abandon synthetic refrigerant loops.
End User:
Customer-type differentiation separates asset owners with captive engineering capabilities from operators dependent on turnkey service contracts.
- Power Plants:Utility and independent power producers operate the most mature seawater cooling infrastructure, now facing upgrade cycles driven by thermal discharge rule tightening.
- Marine Vessels:Ship operators prioritize weight reduction and redundancy in propulsion cooling circuits.
- Industrial Facilities:Chemical processors and cold storage operators in Italy and Greece are redirecting investment toward seawater heat rejection as EU F-Gas phasedown accelerates.
- Data Centers:Hyperscale operators along China's eastern seaboard and Northern Europe's North Sea corridor are transferring operational risk to OEMs through decade-long thermal performance agreements.
Industrial facilities dominate current procurement volume; data centers are gaining share fastest as coastal clustering intensifies.
Technology:
Maturity curves separate legacy open-cycle dominance from emerging closed-cycle and indirect configurations reshaping competitive positioning.
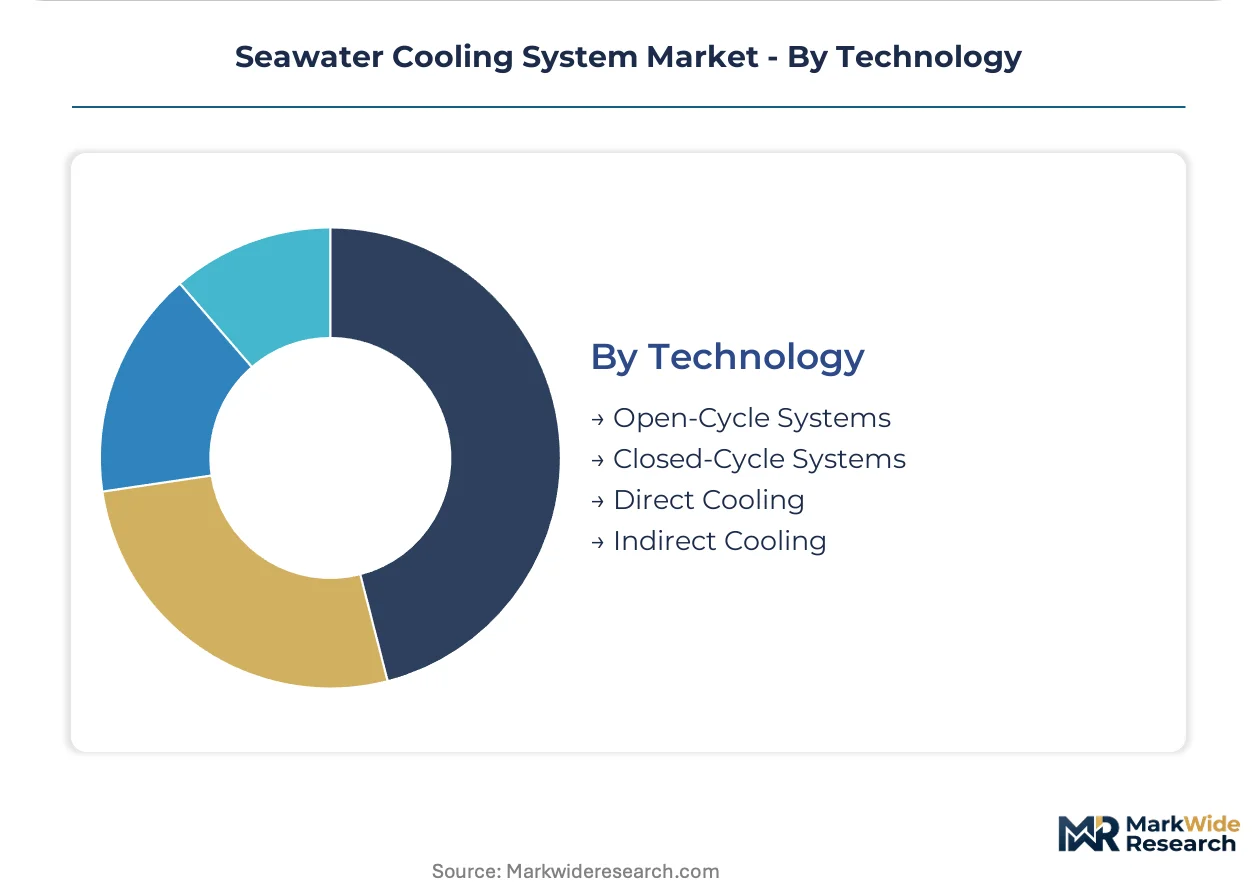
- Open-Cycle Systems:Direct once-through seawater circulation remains the installed base majority, though thermal discharge restrictions are constraining new permits in marine protected zones.
- Closed-Cycle Systems:Recirculating loops with cooling towers or surface condensers capture margin pools where regulators restrict direct ocean return. China's MEE enforces stricter limits near sensitive marine ecosystems, forcing facility upgrades.
- Direct Cooling:Raw seawater contacts process equipment in the simplest, most capital-efficient configuration.
- Indirect Cooling:Intermediate freshwater or glycol circuits isolate process fluids from corrosive chloride exposure, extending equipment life in high-salinity environments above 35 parts per thousand.
Open-cycle systems retain volume leadership; closed-cycle configurations are expanding most quickly as permitting constraints tighten across coastal jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Bohai Economic Rim and Yangtze River Delta special economic zones concentrate hyperscale data center investment, while EU Green Deal implementation and EPA thermal discharge rules reshape coastal infrastructure economics across three continents.
United States
Hyperscale data center operators in Virginia Beach and Los Angeles County deploy seawater cooling to bypass mechanical refrigeration loads. EPA Section 316(b) rules on cooling water intake structures inflate capital costs for open-cycle installations, forcing closed-cycle adoption. The Pacific Northwest corridor clusters marine-grade titanium fabrication capacity serving West Coast thermal management projects.
China
MEE thermal discharge limits near marine protected zones accelerate closed-cycle retrofits at Bohai Bay petrochemical complexes. Yangtze River Delta hyperscale facilities exploit tidal resources to reduce energy intensity. Qingdao and Tianjin port zones concentrate super-duplex heat exchanger manufacturing serving domestic coastal power upgrades.
Germany
North Sea offshore wind converter platforms specify indirect seawater cooling to isolate electronics from chloride exposure. EU F-Gas Regulation phasedown redirects Hamburg and Bremerhaven chemical processors toward ocean-based heat rejection. Coastal shipyards in Lower Saxony integrate compact plate heat exchangers into IMO-compliant propulsion systems.
Japan
Tokyo Bay data center operators transfer operational risk through decade-long thermal performance contracts with OEMs. METI efficiency mandates compress machinery space claims in Kansai-region shipbuilding. Osaka-based industrial clusters adopt closed-cycle configurations where thermal discharge restrictions protect Seto Inland Sea ecosystems.
South Korea
Ulsan petrochemical complexes face MEE-equivalent discharge standards as coastal environmental rules tighten. Busan shipyards specify corrosion-resistant alloys for 25-year service intervals in high-salinity environments. Gwangyang steelworks integrate seawater circuits into multi-stage thermal operations under national industrial decarbonization targets.
Seawater Cooling System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated marine power houses commanding premium pricing in vessel applications while modular fabricators capture data center retrofit demand. Market structure tilts toward consolidation at the heat exchanger layer, where chloride-resistant alloy expertise creates defendable positions. Three archetypes dominate: full-system integrators with captive metallurgy capabilities, component specialists focused on titanium fabrication scale, and regional EPC contractors bundling installation with long-term service agreements. Competitive moves concentrate on strategic partnerships for coastal permitting expertise and backward integration into super-duplex steel supply.
Within the full-system integrator tier, Alfa Laval and Wärtsilä exemplify contrasting geographic anchoring strategies, with the Swedish-Finnish complex leveraging Nordic marine engineering heritage while the Finnish-German group ties marine power and thermal management into unified procurement packages. GEA Group occupies a position among corrosion-resistant alloy specialists, its German engineering base supporting high-salinity environment portfolios. These three represent distinct archetypes: plate heat exchanger dominance, integrated power-thermal bundling, and materials-science differentiation.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| GEA Group |
| SPX Flow |
| TRAC Ecological |
| Orion Machinery |
| VIRIDIS Engineering |
| EJ Bowman |
| Kelvion |
| Others |
Value Network & Pricing Analysis
Marine corrosion engineering specialists concentrated in Nordic shipbuilding regions and Japan's Kansai industrial belt command wage premiums that compress margins at the premium tier while widening spreads to economy-grade titanium fabrication sourced from emerging manufacturing zones.
Pricing Analysis
Lead-time premiums separate procurement tiers, with spot inventory of super-duplex heat exchanger bundles trading at discounts to engineered-to-order systems requiring ISO 15156/NACE MR0175 certification. Project-based contract structures dominate large coastal installations, where price differentiation hinges on alloy grade certification and bundled decade-long thermal performance guarantees. Cost compression in standard-grade titanium components is intensifying as Chinese fabricators expand Bohai Rim capacity. Data center operators demonstrate lowest price sensitivity, prioritizing 25-year service intervals over first-cost savings.
Supply Chain Analysis
Freight costs for oversized heat exchanger bundles constrain sourcing radius, anchoring supply concentration in Germany, South Korea, and coastal China where heavy-lift port infrastructure supports project cargo. Raw material flows draw from Finnish titanium sponge producers, Swedish super-duplex steel mills, and Japanese precision casting foundries. Single-source vulnerability concentrates in chloride-resistant alloy metallurgy expertise held by aging technical specialists at established OEMs. Distribution runs through specialized marine EPC contractors bundling installation with long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as EPA Section 316(b) compliance costs and EU F-Gas Regulation mandates force sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Hedge titanium price exposure through long-term offtake agreements with Nordic sponge producers while building captive super-duplex steel capabilities to offset raw material volatility threatening large-contract margins. Secure coastal permitting expertise through strategic partnerships with specialized marine EPC contractors facing execution risk concentration. For New Entrants and Emerging Players: Begin with modular skid-mounted system fabrication for data center retrofits, where buyers lack specialized marine construction capabilities and procurement is shifting toward turnkey thermal performance contracts. Target China's Yangtze River Delta hyperscale cluster through partnerships with local port zone fabricators holding MEE discharge compliance experience. For Investors and Strategic Acquirers: The window for entry favors corrosion-resistant alloy specialists with ISO 15156/NACE MR0175 certification capabilities and established EU-wide service networks capturing F-Gas Regulation displacement demand. Watch for inflection when China's MEE extends thermal discharge limits beyond current marine protected zones to broader coastal jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Super-Duplex Steel Supply | Captive metallurgy capabilities defend margins against raw material volatility in high-salinity equipment contracts. |
| Modular Skid-Mounted System Expansion | Pre-fabricated designs reduce on-site welding duration and open coastal data center retrofit demand. |
| Long-Term Thermal Performance Contracting | Decade-long service agreements transfer operational risk from Bohai Rim hyperscale operators to OEMs. |
| Coastal Permitting Expertise Partnership | Specialized marine EPC relationships compress project commissioning timelines in contested siting jurisdictions. |
| Closed-Cycle Configuration Portfolio Buildout | Regulatory restrictions on direct seawater return create upgrade demand among existing coastal power facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with heat exchanger procurement directors at hyperscale data center operators, marine EPC project managers, super-duplex steel mill technical sales leads, and MEE regional compliance officers. Bottom-up equipment shipment tallies triangulated against top-down coastal power and industrial capacity investment tracking across the analysis window.
Data-stream reconciliation connected hardware layer volumes to end-use application spend through product-type, thermal cycle configuration, and deployment context segmentation. CAGRs were derived from installed base replacement cycles and regulatory-driven upgrade demand modeling. Forecast inputs incorporated EPA Section 316(b) compliance cost trajectories and EU F-Gas Regulation phasedown schedules.
Underlying measurement precision varies by segment; heat exchanger product-type data carries tighter precision than aftermarket service contract value attribution. Forecasts reflect assumptions about regulatory enforcement intensity and titanium price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Global Chiller Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Solar Fan Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Solar Powered Cold Storage Market