
 United States Subsea Pumps Market | 2026-2036
United States Subsea Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
United States Subsea Pumps Market Intelligence
Subsea pump engineering talent is rotating from conventional platform roles into deepwater specialty teams as Gulf of Mexico projects demand tighter pressure tolerance and longer tieback distances. Baker Hughes leverages its artificial lift portfolio to dominate electric submersible system integration. Schlumberger anchors its position through permanent monitoring capabilities bundled with pump deployment. TechnipFMC competes on integrated subsea production systems that compress project cycle times.
Subsea pumps are pressure-rated centrifugal or positive displacement units designed to operate at seabed depths exceeding 1,000 meters, typically constructed from duplex stainless steel or nickel-aluminum bronze to resist chloride-induced corrosion while maintaining hydraulic efficiency across variable crude viscosities. Centrifugal pumps occupy the largest installed base due to their compatibility with high-volume crude lift operations, while positive displacement configurations capture margin in heavy-oil applications where viscosity challenges standard impeller designs. Electric submersible pump technology leads capital deployment because subsea power distribution infrastructure now supports higher horsepower ratings at deeper water depths.
The Bureau of Safety and Environmental Enforcement enforces mechanical integrity rules that mandate redundant barrier systems and real-time leak detection on all subsea pumping installations in federal waters. The Environmental Protection Agency coordinates with the Coast Guard on spill response preparedness requirements that shape equipment specification and emergency shutdown architecture. Stakeholders must monitor how evolving methane performance standards and electrification mandates for offshore platforms reshape pump specification criteria and supplier qualification pathways.
Market Dynamics
Deepwater tieback economics in the Gulf of Mexico are compressing project breakeven thresholds, forcing pump manufacturers to engineer higher-pressure systems that operate reliably at 2,500+ meter depths without platform support infrastructure.
Growth Catalysts
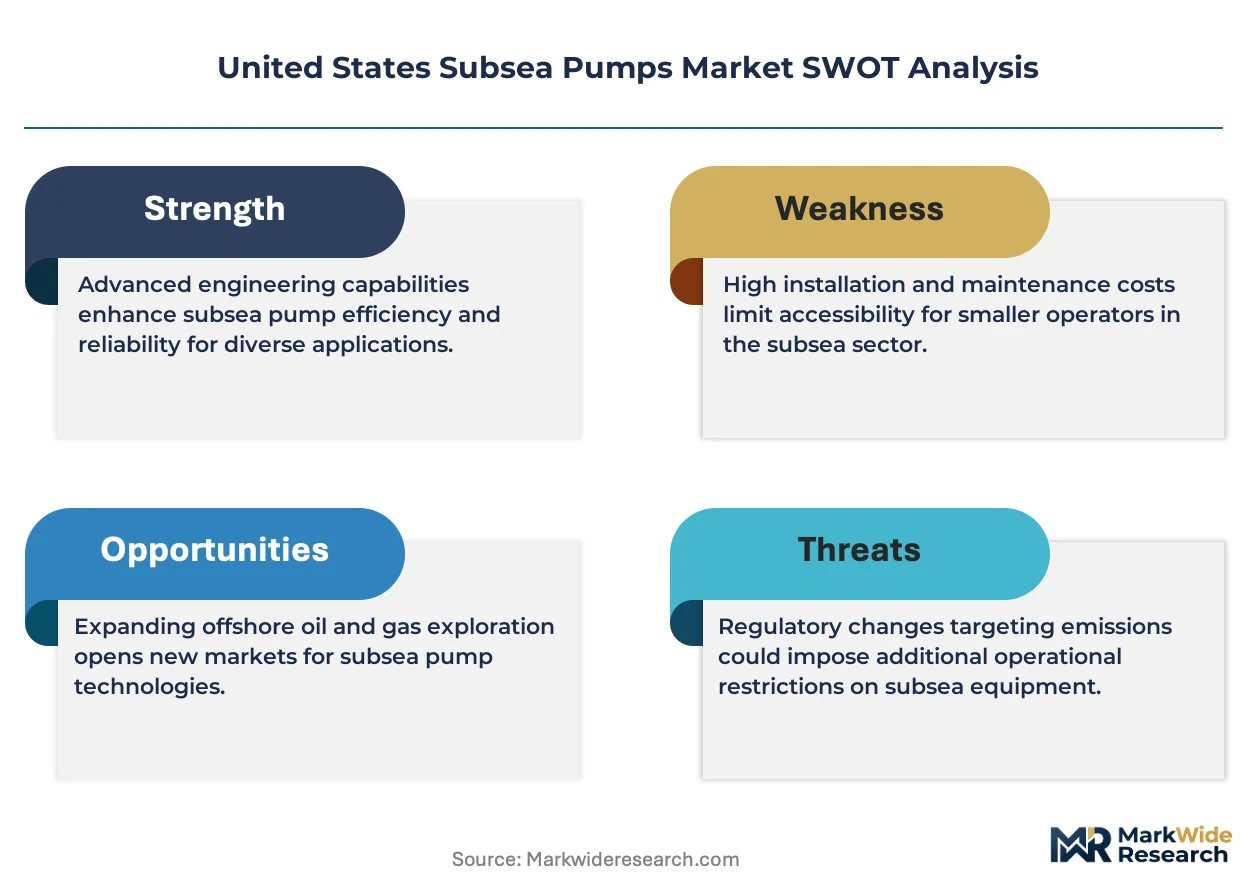
- Equipment Reliability Mandates:The Bureau of Safety and Environmental Enforcement requires redundant barrier systems on all subsea pumping installations, accelerating replacement cycles for legacy units in federal waters.
- Heavy-Oil Reservoir Development:Positive displacement pump configurations capture demand from viscosity-challenged crudes in the Lower Tertiary formations where standard centrifugal designs underperform.
- Texas-Louisiana Infrastructure Clustering:Concentrated offshore service yards in Port Fourchon and Houston reduce logistics friction for subsea pump deployment and maintenance turnaround.
Market Restraints
- Nickel-Aluminum Bronze Supply Concentration:Foundry capacity for corrosion-resistant pump housings concentrates among a handful of Gulf Coast suppliers, creating lead time vulnerability for large-diameter castings.
- Deepwater Capex Intensity:Subsea pump packages requiring 5,000+ horsepower ratings demand specialized power distribution infrastructure that extends project sanctioning timelines.
- Substitution from Gas-Lift Systems:Mature Gulf of Mexico fields with declining reservoir pressure increasingly favor gas-lift retrofit over subsea pump installation for marginal production gains.
Strategic Opportunities
- Electrification Tailwinds:The Inflation Reduction Act's offshore platform electrification incentives reshape pump specification criteria toward all-electric submersible systems.
- Permanent Monitoring Convergence:Integration of fiber-optic distributed temperature sensing with pump control systems enables predictive maintenance contracts that extend supplier revenue streams.
- California Offshore Revival:Deferred Pacific Coast projects face renewed operator interest as permitting pathways clarify for tieback developments requiring subsea boosting.
Industry Challenges
- Specialized Welding Certification Bottlenecks:Duplex stainless steel fabrication for high-pressure pump housings requires ASME Section IX-qualified welders in short supply along the Gulf Coast.
- Legacy Control System Integration:Brownfield installations demand custom interface engineering to marry modern variable frequency drives with aging platform SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Subsea Pumps Market |
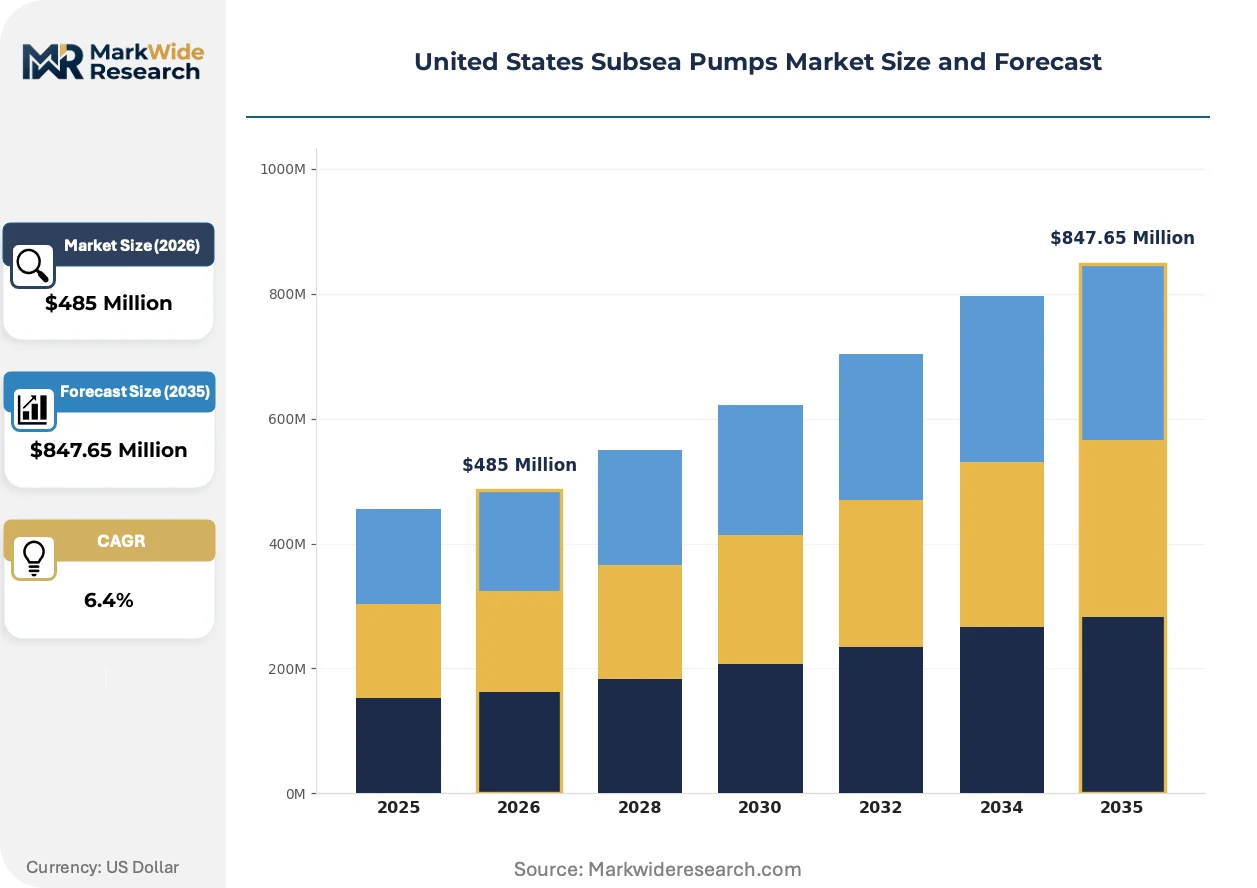
| Market Size in 2026 | $485 Million |
| Market Size in 2035 | $847.65 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Reciprocating Pumps, Submersible Pumps Technology: Electric Submersible Pumps, Hydraulic Pumps, Mechanical Pumps, Pneumatic Pumps End User: Oil & Gas, Marine, Water Management, Renewables Application: Decommissioning, Exploration, Production, Transmission |
| Companies Covered | Flowserve Corporation, Baker Hughes, TechnipFMC, Aker Solutions, OneSubsea, Schlumberger, Sulzer, Halliburton, National Oilwell Varco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Subsea Pumps Market Strategic Shifts & Innovations
Subsea pump engineering is pivoting toward integrated production systems where boosting, separation, and compression functions merge into single seabed packages, compressing project cycle times and reducing topside footprint requirements.
Permanent magnet motor technology is supplanting conventional induction designs in electric submersible pump applications. Operators in the Gulf of Mexico's deepwater Wilcox and Norphlet plays are specifying these motors for their superior efficiency at variable speeds. This shift is supplanting the historical dominance of fixed-speed pump configurations and enabling longer step-out distances from host platforms.
The Environmental Protection Agency coordinates with the Coast Guard on spill response preparedness requirements that now mandate real-time leak detection integration with subsea pump control systems. This regulatory layering forces pump OEMs to embed sensor networks directly into pressure barrier designs. Heavy-oil developments in federal waters face the steepest compliance cost escalation as they require redundant monitoring architectures.
Service contract unbundling is fragmenting traditional procurement relationships. Independent operators in the Gulf of Mexico now separate pump hardware acquisition from installation and maintenance services, creating openings for specialized subsea contractors. This pattern is most pronounced among private-equity-backed producers in the Gulf who prioritize capital flexibility over single-source accountability.
United States Subsea Pumps Market Segmentation
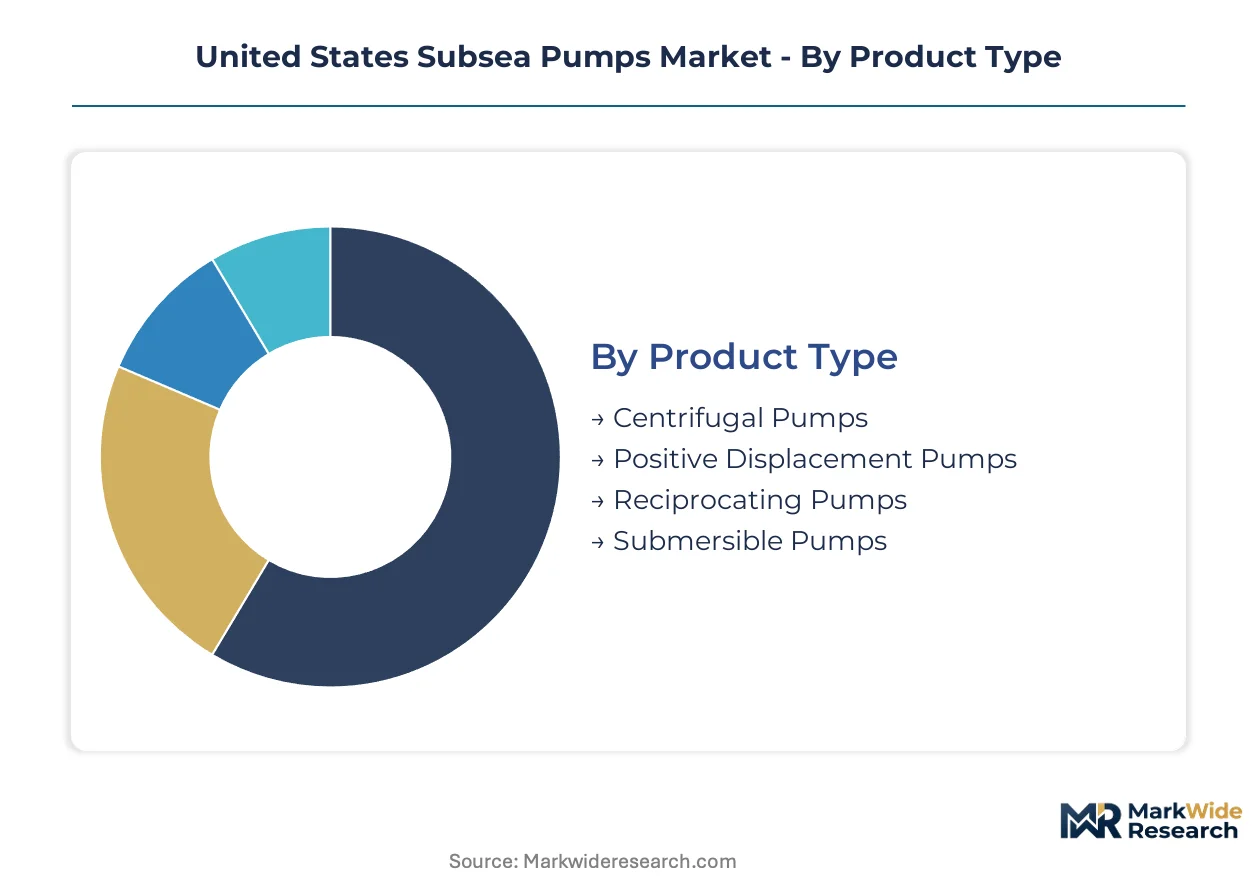
Subsea pump procurement in the United States fragments across equipment architecture, power delivery systems, and operational deployment modes. Understanding these segment boundaries clarifies where suppliers compete on specification depth versus where standardization drives price compression.
Product Type:
Margin pools concentrate in corrosion-resistant alloy fabrications and high-pressure sealing systems that differentiate premium pump architectures from commodity alternatives.
- Centrifugal Pumps:Impeller-driven designs constructed from duplex stainless steel or nickel-aluminum bronze dominate high-volume crude lift operations across the Gulf of Mexico's deepwater tiebacks. Texas and Louisiana offshore clusters specify these units for their hydraulic efficiency across variable crude viscosities at depths exceeding 1,500 meters.
- Positive Displacement Pumps:Screw or progressing cavity configurations engineered for heavy-oil applications in the Lower Tertiary formations where standard centrifugal impellers face viscosity-induced performance degradation. Operators in federal waters increasingly specify these units as reservoir characteristics shift toward heavier crudes.
- Reciprocating Pumps:Plunger-based positive displacement systems deployed for high-pressure injection duties and chemical service in subsea processing trains.
- Submersible Pumps:Compact sealed units integrated into seabed boosting stations for artificial lift in marginal field developments.
The dominant share belongs to Centrifugal Pumps, while Positive Displacement Pumps is closing the gap fastest as heavy-oil reservoir development accelerates.
Technology:
Power delivery architecture determines capital intensity and operational flexibility across the technology spectrum.
- Electric Submersible Pumps:Permanent magnet motor designs are supplanting conventional induction configurations in the Wilcox and Norphlet plays for superior efficiency at variable speeds. The Inflation Reduction Act's offshore platform electrification incentives reshape procurement criteria toward these all-electric systems.
- Hydraulic Pumps:Fluid-power units leveraging subsea hydraulic distribution networks for applications requiring rapid torque response in intervention-heavy developments.
- Mechanical Pumps:Direct-drive systems with minimal electrical infrastructure dependence, specified for ultra-deepwater installations where power distribution complexity escalates project risk.
- Pneumatic Pumps:Compressed-gas-driven units confined to niche subsea chemical injection and low-pressure utility services.
Electric Submersible Pumps commands the largest installed base, though Mechanical Pumps is expanding most quickly in ultra-deepwater sanctioning pipelines.
End User:
Customer concentration patterns reflect federal leasing activity and infrastructure access economics.
- Oil & Gas:Integrated majors and independent operators in the Gulf of Mexico drive specification standards through deepwater field development programs. The Bureau of Safety and Environmental Enforcement mandates redundant barrier systems and real-time leak detection for all subsea pumping installations in federal waters.
- Marine:Offshore vessel operators and subsea construction contractors specifying pumps for ballast, bilge, and auxiliary systems on dynamically positioned rigs and support vessels.
- Water Management:Coastal municipalities and industrial facilities deploying subsea intake and discharge systems for desalination and cooling water applications.
- Renewables:Offshore wind developers evaluating subsea pump integration for foundation installation, cable burial, and future green hydrogen production infrastructure.
Oil & Gas retains the dominant procurement volume, while Renewables is gaining share fastest as Atlantic Coast offshore wind lease rounds mature into construction phases.
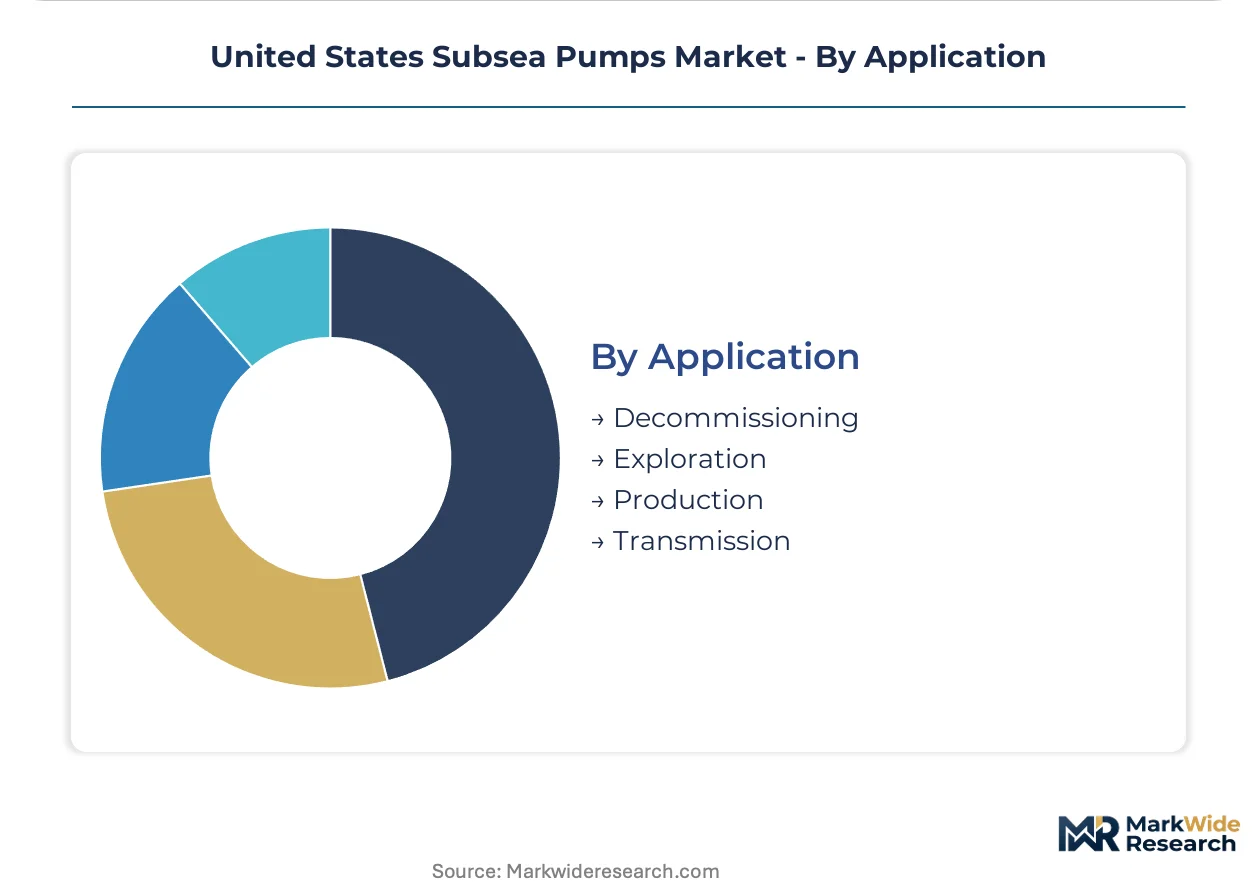
Application:
Lifecycle stage determines equipment reliability requirements and service contract structures.
- Production:Artificial lift and boosting systems operating continuously at seabed depths exceeding 2,000 meters without platform support infrastructure. Deepwater tieback economics in the Gulf of Mexico compress breakeven thresholds and force higher-pressure system specifications.
- Exploration:Temporary subsea pump packages deployed for extended well testing and early production systems in frontier basins.
- Transmission:Pipeline booster stations maintaining flow assurance across long-distance subsea export routes from marginal fields to host facilities.
- Decommissioning:Dewatering and hydrocarbon recovery pumps for end-of-life field abandonment operations in mature Gulf of Mexico provinces.
Production holds the dominant share, while Decommissioning is climbing the fastest as the Gulf of Mexico's installed base ages toward regulatory abandonment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast procurement patterns diverge sharply from Pacific and Atlantic approaches, with Texas and Louisiana operators specifying higher-pressure systems for deepwater tiebacks while California and Atlantic developments prioritize modular configurations for permitting flexibility.
Texas
Deepwater Wilcox and Norphlet plays drive demand for permanent magnet electric submersible systems rated above 5,000 horsepower. The Bureau of Safety and Environmental Enforcement enforces redundant barrier mandates on all federal installations off the Texas coast. Houston anchors the national supply chain, with engineering clusters in the Energy Corridor specifying corrosion-resistant alloys for ultra-deepwater deployments.
Louisiana
Lower Tertiary heavy-oil formations require positive displacement configurations that centrifugal designs cannot service effectively. EPA coordination with the Coast Guard on spill response preparedness shapes emergency shutdown architecture for installations in federal waters. Port Fourchon functions as the primary logistics hub, with service yards executing turnaround maintenance on subsea boosting systems for Gulf of Mexico producers.
California
Pacific Coast tieback developments favor lower-pressure electric submersible packages suited to shallower reservoir depths and stricter environmental review timelines. The California Environmental Quality Act and Coastal Commission permitting pathways influence equipment specification toward modular, removable configurations. Long Beach and Ventura industrial zones host fabrication capacity for subsea hardware serving deferred offshore projects awaiting regulatory clarity.
Alaska
Arctic and sub-Arctic offshore prospects specify mechanical pump systems minimizing electrical infrastructure dependence in extreme cold environments. The Department of the Interior's Bureau of Ocean Energy Management oversees leasing and equipment standards for federal waters off the North Slope. Anchorage engineering offices coordinate procurement for frontier basin exploration where power distribution complexity escalates project risk thresholds.
Atlantic Coast
Emerging offshore wind lease rounds evaluate subsea pump integration for foundation installation and future green hydrogen production infrastructure. The Bureau of Ocean Energy Management's Atlantic planning areas face distinct regulatory layering compared to Gulf of Mexico conventions. Norfolk and New Bedford port clusters position for construction support roles as lease maturation transitions toward development phases.
United States Subsea Pumps Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding system integration contracts while mid-tier fabricators compete on component supply and aftermarket service. The structure reflects consolidation around subsea production system bundling, where pump procurement merges with separation and compression packages. Three archetypes dominate: integrated oilfield service conglomerates with artificial lift portfolios, pure-play subsea equipment specialists focused on seabed production systems, and diversified industrial pump manufacturers leveraging corrosion-resistant alloy expertise. Competitive moves center on permanent monitoring convergence and electrification-ready product line transitions.
Within the integrated service tier, Baker Hughes and Schlumberger occupy positions shaped by artificial lift heritage and permanent monitoring capabilities respectively. Baker Hughes leverages electric submersible system integration strengths across Gulf of Mexico deepwater programs. Schlumberger anchors its market presence through bundled deployment of pump hardware with real-time reservoir monitoring. TechnipFMC sits within the subsea production system specialist archetype, competing on integrated packages that compress project cycle times for offshore operators. These three represent the competitive core around which procurement relationships and specification standards coalesce.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Baker Hughes |
| TechnipFMC |
| Aker Solutions |
| OneSubsea |
| Schlumberger |
| Sulzer |
| Halliburton |
| National Oilwell Varco |
| Others |
Cost & Logistics Intelligence
Permanent magnet motor substitution for conventional induction designs is redrawing supplier geography toward Asian magnet processing centers while compressing margin structures for legacy motor OEMs serving Gulf of Mexico deepwater programs. This displacement simultaneously concentrates rare earth sourcing leverage and intensifies price competition in the electric submersible pump tier.
Pricing Analysis
Long-term offtake agreements dominate capital equipment procurement, with integrated majors locking in five-to-seven-year supply contracts for high-horsepower subsea pump packages. Price differentiation separates API-certified units for federal water installations from non-certified alternatives serving state-regulated developments, with certification premiums widening as BSEE tightens mechanical integrity enforcement. Cost compression in the standard centrifugal tier reflects foundry overcapacity for duplex stainless steel castings, while positive displacement configurations command pricing resilience due to heavy-oil application specialization. Private-equity-backed independents exhibit the sharpest price sensitivity, unbundling hardware from installation services to preserve capital flexibility.
Supply Chain Analysis
Inbound logistics costs from Asian rare earth processing hubs through West Coast ports create vulnerability for permanent magnet motor supply chains serving Gulf Coast assembly operations. Manufacturing concentration in China, Japan, and the United States shapes component availability for electric submersible systems, with neodymium magnet supply drawing from Chinese separation facilities and Japanese alloy production. Nickel-aluminum bronze foundry capacity concentrates among Gulf Coast suppliers, creating single-source exposure for large-diameter pump housings. Distribution runs through Port Fourchon and Houston service yards that execute final assembly and subsea deployment logistics for federal water installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States subsea pumps market functions as a service-attach opportunity where predictive maintenance contracts and permanent monitoring subscriptions expand faster than hardware shipments, rewarding suppliers who embed sensor networks into pressure barrier designs.
For Market Incumbents: Compound defensive positioning through backward integration into nickel-aluminum bronze foundry capacity and captive supply of permanent magnet motor assemblies, neutralizing lead time vulnerability as rare earth sourcing concentrates. Lock in long-term offtake relationships with integrated majors before electrification mandates reshape procurement criteria, while investing in ASME Section IX welding certification programs to capture scarce fabrication talent. For New Entrants and Emerging Players: Lead with modular electric submersible packages sized for California offshore tieback developments, where permitting flexibility favors lower-pressure configurations over Gulf of Mexico deepwater specifications. Target Atlantic Coast offshore wind construction support as the most penetrable adjacent vertical, offering subsea pump integration for foundation installation and cable burial services. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors suppliers with permanent monitoring convergence capabilities and electrification-ready product architectures. Acquisition targets should demonstrate fiber-optic distributed temperature sensing integration and variable-speed drive compatibility. Watch BSEE methane performance standard evolution as the inflection signal that would accelerate replacement cycles for legacy gas-lift-dependent installations.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Sensor-embedded pump systems enable recurring revenue streams through condition-based service contracts. |
| Permanent Magnet Motor Manufacturing Scale-Up | Captive production of high-efficiency motors reduces dependence on Asian rare earth supply chains. |
| ASME Section IX Welding Certification Investment | Qualified fabrication capacity addresses Gulf Coast talent scarcity for duplex stainless steel housings. |
| Integrated Subsea Production System Bundling | Combined pump-separation-compression packages compress project cycle times for deepwater operators. |
| California Offshore Market Entry | Modular system configurations align with CEQA-driven permitting requirements for Pacific Coast tiebacks. |
Research Approach
A standing panel of subsea project engineers, offshore procurement directors, and BSEE compliance officers provided ongoing calibration for demand assumptions and regulatory interpretation. Primary fieldwork with pump OEM product managers, Gulf Coast foundry operations heads, and electric submersible system integration specialists was cross-referenced against BSEE incident databases, EPA spill response filings, and Bureau of Ocean Energy Management leasing records. Bottom-up unit demand modeling triangulated against top-down capital expenditure forecasts from integrated major public disclosures.
Consistency checks validated volume and value outputs against external benchmarks including EIA offshore production data, IHS Markit subsea equipment tracking, and FERC pipeline flow statistics. The analytical framework segmented demand across pump architecture, power delivery technology, end-user category, and application lifecycle stage throughout the projection horizon. CAGR derivation incorporated subsea tieback sanctioning timelines, electrification incentive phase-ins from the Inflation Reduction Act, and heavy-oil reservoir development curves from Lower Tertiary formations.
Forecasts assume regulatory continuity in BSEE mechanical integrity enforcement and EPA spill response coordination; material policy shifts in methane performance standards or offshore platform electrification mandates would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Electric Oil Pump Market
Pumps and Control Devices
Dosing Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Package Pumping Station Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market