
 North America Ocean Power Market | 2026-2036
North America Ocean Power Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ocean Power Market Analytics
Utility procurement in the North America ocean power sector is consolidating around long-term power purchase agreements with coastal municipalities and independent system operators. Ocean Power Technologies leverages its autonomous PowerBuoy platform to anchor early-stage commercial deployments in US territorial waters. Verdant Power sustains technology leadership in tidal stream installations through its Roosevelt Island Tidal Energy project in New York's East River. Lockheed Martin Corporation competes via defense-adjacent engineering capabilities applied to deep-water energy infrastructure.
North America ocean power encompasses the capture and conversion of marine kinetic energy from tides, waves, and thermal gradients into grid-ready electricity using turbine arrays, oscillating water columns, or closed-cycle heat engines operating across temperature differentials exceeding 20°C. Tidal Stream technology dominates near-term deployment pipelines due to predictable resource availability and established turbine supply chains. Wave Energy occupies the fastest-growing structural position as point absorber and attenuator designs achieve higher capacity factors in Pacific Coast testbeds. Grid Integration applications command premium margins where synchronous condensers and subsea cables resolve intermittency challenges for islanded coastal communities.
The US Federal Energy Regulatory Commission licenses marine hydrokinetic projects under streamlined pilot and commercial permits, while the Department of Energy's Water Power Technologies Office funds demonstration arrays through national laboratory partnerships. Canada's Ocean Renewable Energy Group coordinates provincial permitting with Fisheries and Oceans Canada to mitigate environmental review timelines. Stakeholders must monitor how evolving interconnection queue reforms and coastal zone management plans determine which project pipelines secure offtake certainty.
Market Dynamics
Utility procurement consolidation around long-term power purchase agreements is compressing developer risk premiums and reshaping capital allocation across Pacific Coast project pipelines. This structural force accelerates the shift from demonstration arrays to commercial-scale deployments.
Growth Catalysts
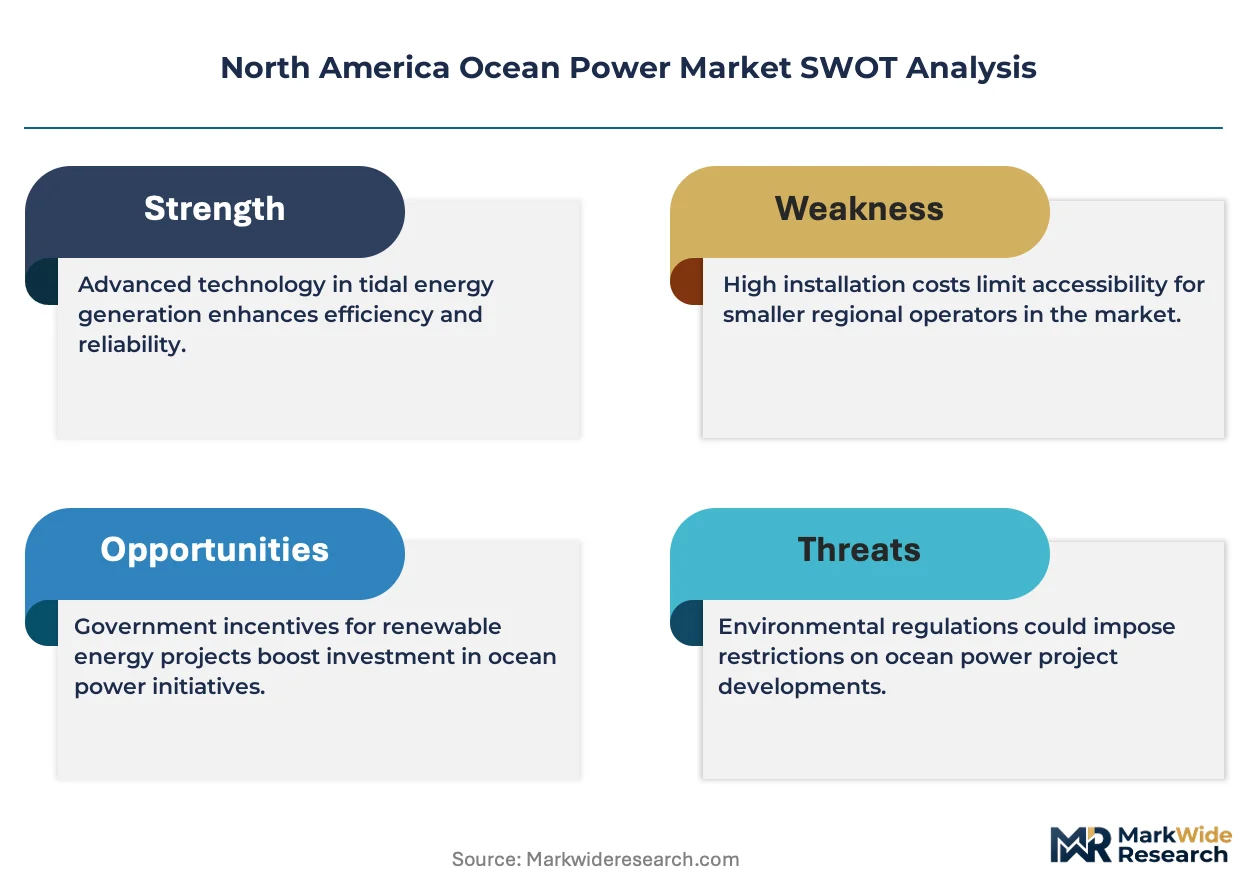
- US Inflation Reduction Act Tax Credits:Federal investment credits for marine energy projects reduce levelized cost of energy and accelerate developer timelines from permitting to grid interconnection.
- Predictable Tidal Stream Resources:Near-term deployment pipelines favor tidal turbine arrays due to forecastable output profiles and established supply chains for horizontal-axis designs.
- Coastal Municipality Demand:Islanded communities in Washington, Oregon, and California seek synchronous condensers and subsea cable infrastructure to resolve intermittency challenges.
Market Restraints
- Subsea Cable Input Costs:High-voltage DC transmission cable manufacturing concentrates among European and Asian suppliers, exposing project budgets to commodity volatility and extended lead times.
- FERC Permitting Friction:Federal Energy Regulatory Commission pilot-to-commercial license transitions create timeline uncertainty for projects advancing beyond demonstration phase.
- Wave Energy Technical Limitation:Point absorber survivability in extreme sea states remains unproven at multi-megawatt scale, constraining insurer appetite and debt financing availability.
Strategic Opportunities
- Underpenetrated Canadian Coastlines:British Columbia and Nova Scotia tidal resources lack grid interconnection infrastructure, creating first-mover advantage for developers securing provincial permits through Fisheries and Oceans Canada coordination.
- Autonomous Platform Convergence:Integration of PowerBuoy-type platforms with offshore aquaculture and surveillance applications diversifies revenue streams beyond electricity sales.
- Department of Energy Demonstration Funding:Water Power Technologies Office national laboratory partnerships de-risk technology validation for emerging attenuator designs.
Industry Challenges
- Marine Hydrokinetic Skill Gap:Specialized turbine installation and subsea maintenance expertise remains concentrated among offshore oil service contractors, limiting workforce scalability.
- Environmental Certification Timelines:National Marine Fisheries Service consultations for endangered species impacts extend pre-construction monitoring periods by multiple seasons.
- Legacy Grid Integration Complexity:Synchronous condenser deployment for frequency stability requires coordination with independent system operators holding divergent interconnection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ocean Power Market |
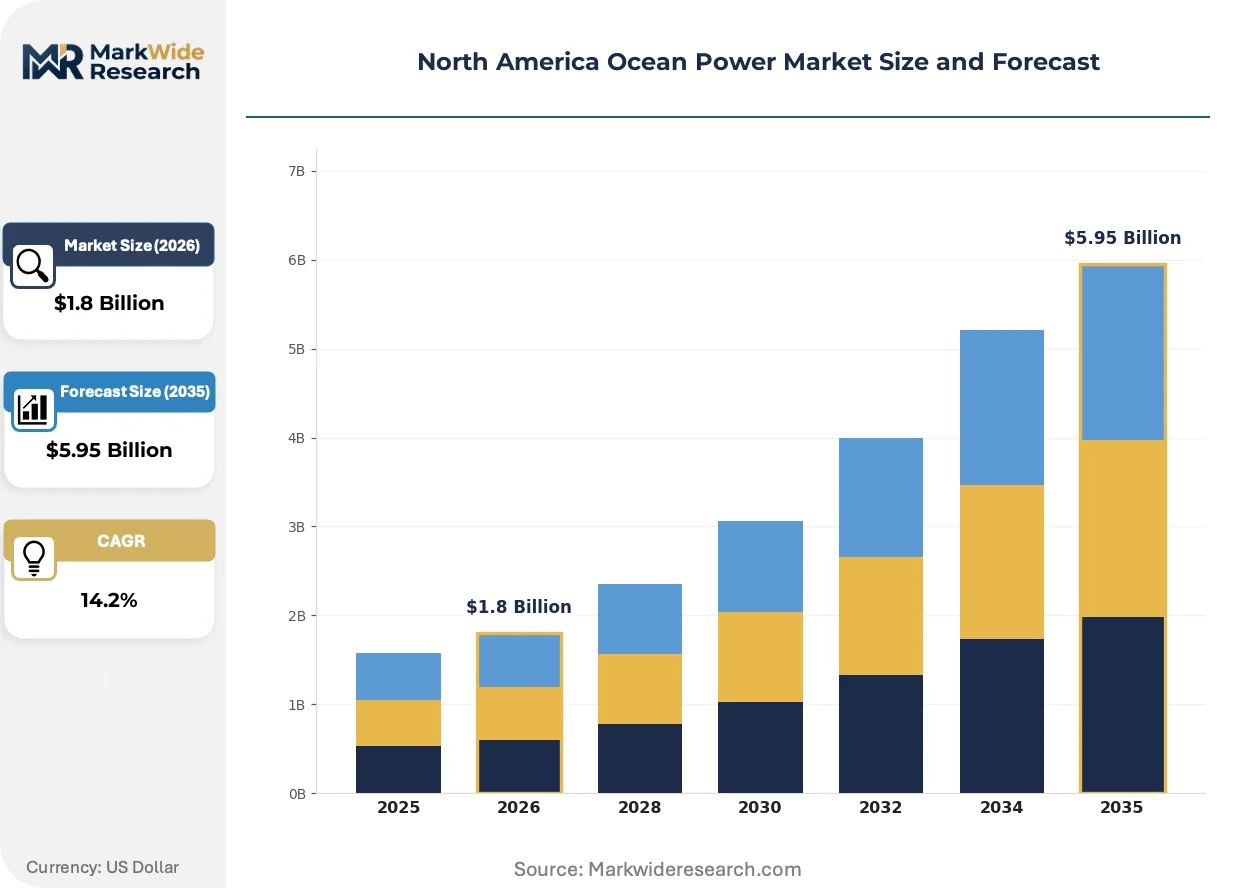
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tidal Stream, Wave Energy, Ocean Thermal, Salinity Gradient End User: Utilities, Marine Industries, Research Institutions, Energy Providers Application: Power Generation, Desalination, Energy Storage, Grid Integration Deployment: Onshore, Offshore, Pilot Projects, Commercial Projects |
| Companies Covered | Ocean Power Technologies, Verdant Power, Lockheed Martin Corporation, GE Vernova, CalWave, Aqua-Magnetics, Atargis Energy Corporation, Able Technologies, Ocean Renewable Power Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ocean Power Market Evolving Landscape
Technology convergence between offshore energy and autonomous maritime systems is compressing operational expenditure models while regulatory streamlining accelerates project velocity. These forces reshape competitive positioning around platform versatility and permitting efficiency.
Attenuator wave energy converters are absorbing oscillating water column market share as articulated multi-segment designs achieve higher capacity factors in Pacific Coast testbeds. California and Oregon utilities are piloting these systems for baseload supplementation. This technology is absorbing capital that previously flowed to fixed-bottom tidal installations.
FERC's streamlined pilot permit pathway is compressing demonstration-to-commercial timelines for marine hydrokinetic projects in US territorial waters. The policy reduces environmental review redundancy while maintaining stakeholder consultation requirements. Developers in Washington state are responding by clustering projects near existing transmission infrastructure.
Power purchase agreement tenor extension is displacing merchant revenue exposure for ocean power developers. Coastal municipalities and community choice aggregators are signing 20-25 year contracts that transfer offtake risk to ratepayers. This pattern concentrates most visibly in California where renewable portfolio standards mandate marine energy carve-outs.
North America Ocean Power Market Segmentation
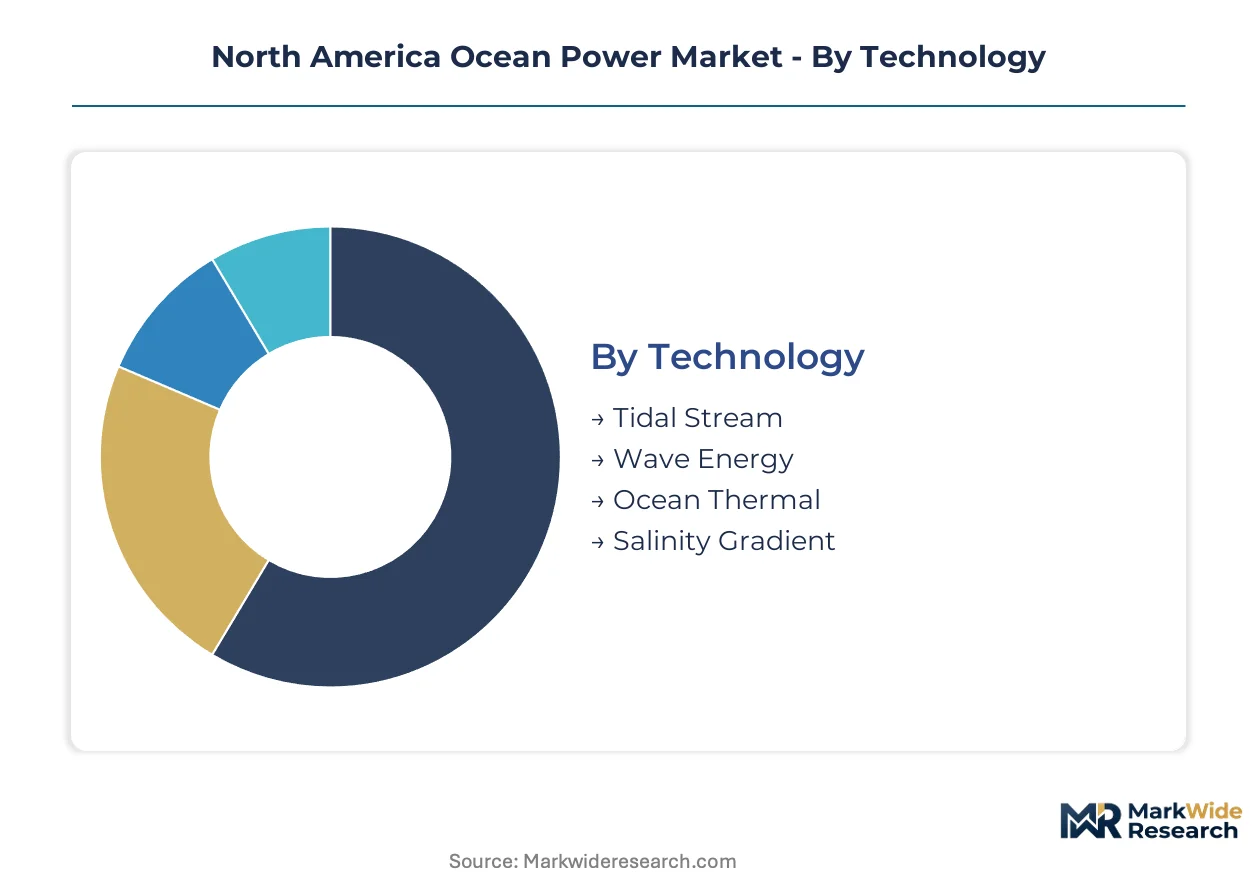
Technology differentiation in ocean power determines project economics, permitting complexity, and grid interconnection requirements. End user procurement patterns and deployment scale further stratify capital allocation across the North American pipeline.
Technology:
Resource predictability and turbine maturity separate developers seeking bankable cash flows from those pursuing frontier designs.
- Tidal Stream:Horizontal-axis turbines extract kinetic energy from predictable tidal currents. Demand clusters in Nova Scotia's Bay of Fundy and Washington's Puget Sound where velocity profiles support capacity factors exceeding 40%. Established supply chains for subsea foundations reduce installation risk premiums.
- Wave Energy:Point absorbers and attenuators convert oscillating surface motion into electricity. California and Oregon testbeds favor articulated multi-segment designs achieving higher capacity factors than oscillating water columns. Survivability in extreme sea states remains the binding constraint for multi-megawatt scaling.
- Ocean Thermal:Closed-cycle heat engines exploit temperature differentials exceeding 20°C between surface and deep water. Hawaii and Florida coastal zones host the only viable US resources for this technology.
- Salinity Gradient:Pressure-retarded osmosis and reverse electrodialysis generate power from freshwater-saltwater mixing. No commercial deployments exist in North America due to membrane durability challenges and site-specificity constraints.
Volume sits with Tidal Stream; growth tilts toward Wave Energy.
End User:
Contract structure and offtake duration distinguish procurement behavior across buyer categories.
- Utilities:Investor-owned and public power entities dominate procurement through 20-25 year power purchase agreements. Pacific Coast utilities in California, Oregon, and Washington leverage renewable portfolio standards with marine energy carve-outs to justify premium pricing for tidal and wave resources.
- Marine Industries:Offshore aquaculture, desalination plants, and remote port operations seek autonomous power solutions. PowerBuoy-type platforms serving these users diversify revenue streams beyond grid-connected electricity sales.
- Research Institutions:National laboratories and university consortia validate emerging attenuator designs through Department of Energy Water Power Technologies Office partnerships. Funding de-risks technology validation but does not scale to commercial deployment.
- Energy Providers:Community choice aggregators and independent power producers aggregate distributed generation for coastal municipalities. These entities concentrate in California where direct access statutes enable bypass of incumbent utility procurement.
Contract volume concentrates with Utilities; project velocity accelerates fastest among Marine Industries.
Application:
Value capture mechanism—electricity sales versus co-product revenue—determines technology-platform pairing.
- Power Generation:Grid-ready electricity from turbine arrays and oscillating water columns constitutes the core revenue model. Synchronous condensers resolve frequency stability challenges for islanded coastal communities in Washington and Alaska.
- Desalination:Co-located reverse osmosis plants leverage consistent tidal or wave power for water production. Southern California municipalities pilot these configurations to reduce dependence on imported Colorado River supplies.
- Energy Storage:Subsea pumped hydro and compressed air systems buffer intermittency from wave resources. No commercial installations operate in North America due to geological siting constraints.
- Grid Integration:Subsea cable infrastructure and reactive power compensation enable remote resource connection. High-voltage DC transmission manufacturing concentrates among European and Asian suppliers, exposing project budgets to extended lead times.
Revenue concentration rests with Power Generation; technology integration advances fastest in Grid Integration.
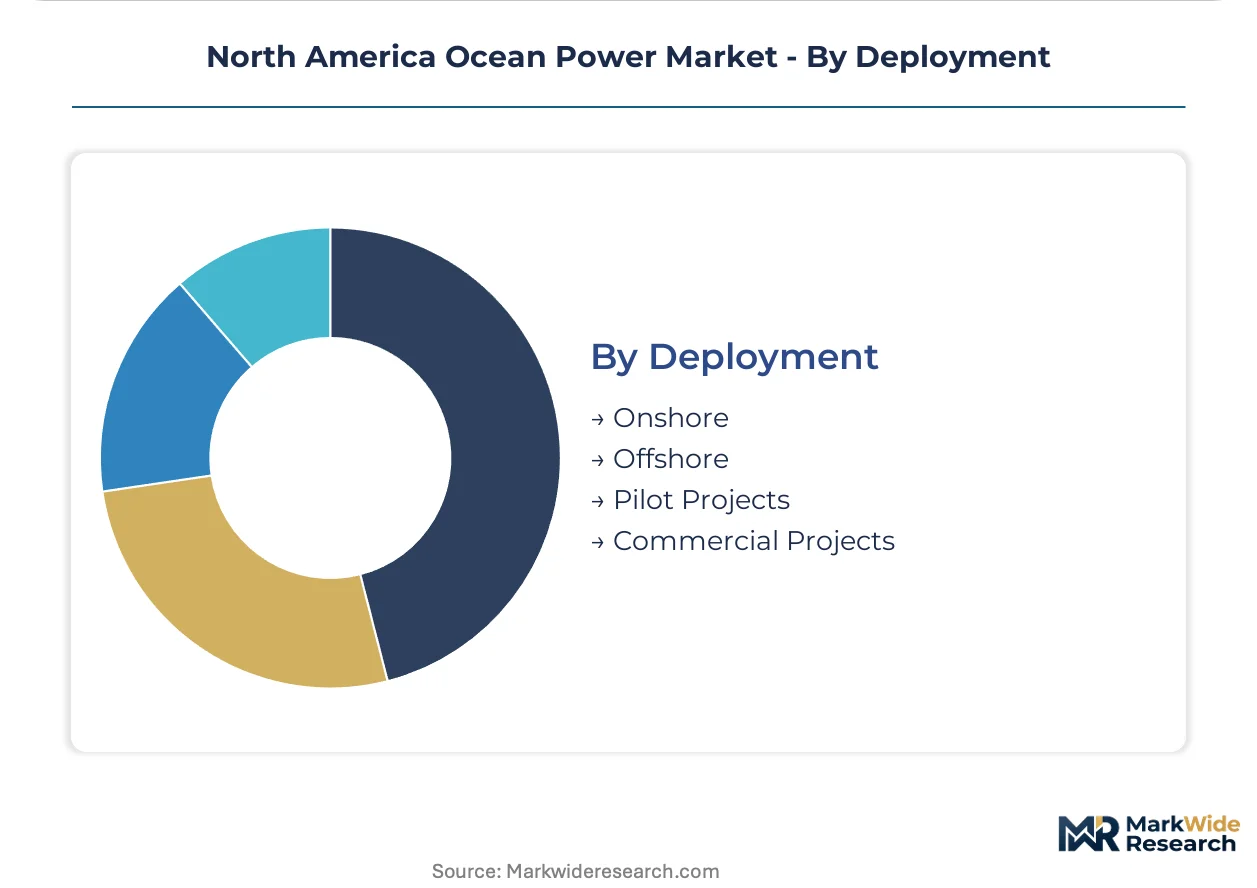
Deployment:
Regulatory pathway and capital intensity separate demonstration-phase projects from bankable commercial assets.
- Onshore:Shore-based oscillating water columns and tidal barrages integrate with existing transmission infrastructure. Limited viable sites in North America constrain deployment scale.
- Offshore:Floating platforms and subsea turbine arrays access higher-energy resources. Installation and maintenance costs concentrate among offshore oil service contractors, limiting workforce scalability.
- Pilot Projects:FERC streamlined permits compress demonstration timelines for marine hydrokinetic projects in US territorial waters. Washington state developers cluster these near existing transmission to reduce interconnection queue risk.
- Commercial Projects:Full-scale arrays require transition from pilot-to-commercial FERC licensing and long-term power purchase agreements. Environmental certification timelines through National Marine Fisheries Service consultations extend pre-construction monitoring by multiple seasons.
Project count concentrates in Pilot Projects; capital deployment shifts toward Commercial Projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for ocean power concentrates along the Pacific Coast where wave and tidal resources intersect with aggressive decarbonization mandates. State-level renewable portfolio standards with marine energy carve-outs drive procurement velocity in coastal jurisdictions.
United States
California utilities execute 20-25 year power purchase agreements for wave energy pilot projects while Oregon developers cluster near existing transmission infrastructure. FERC's streamlined pilot-to-commercial permit pathway compresses demonstration timelines for marine hydrokinetic arrays. Washington state's Puget Sound hosts tidal stream installations leveraging predictable velocity profiles exceeding 40% capacity factors.
Canada
British Columbia's coastline offers underpenetrated tidal resources awaiting grid interconnection infrastructure investment. Fisheries and Oceans Canada coordinates provincial permitting with the Ocean Renewable Energy Group to mitigate environmental review timelines. Nova Scotia's Bay of Fundy anchors the country's highest-velocity tidal sites where horizontal-axis turbine arrays achieve bankable output predictability.
Mexico
Baja California's Pacific coastline presents wave energy potential for isolated coastal communities lacking centralized grid access. The country's national energy regulator oversees interconnection standards for distributed renewable generation. Sonora and Sinaloa states host preliminary resource assessments for oscillating water column installations serving desalination co-location.
North America Ocean Power Market Competitive Landscape
United States developers anchor the technology demonstration tier; Canadian specialists hold project development positions along underpenetrated coastlines. The participant base stratifies across defense-adjacent engineering conglomerates, autonomous platform specialists, and pure-play tidal stream operators. Three archetypes dominate: integrated engineering firms leveraging submarine infrastructure expertise, point absorber technology developers targeting utility-scale deployment, and tidal turbine manufacturers exploiting predictable resource geographies. Competitive moves concentrate on securing long-term power purchase agreements and navigating FERC licensing transitions.
Within the autonomous platform tier, Ocean Power Technologies occupies a position exemplifying early-stage commercial deployment in territorial waters. Verdant Power represents tidal stream technology leadership through sustained East River project operations. Lockheed Martin Corporation anchors the defense-adjacent engineering archetype applying deep-water infrastructure capabilities to marine energy applications.
| Leading Market Players |
|---|
| Ocean Power Technologies |
| Verdant Power |
| Lockheed Martin Corporation |
| GE Vernova |
| CalWave |
| Aqua-Magnetics |
| Atargis Energy Corporation |
| Able Technologies |
| Ocean Renewable Power Company |
| Others |
Value Network & Pricing Analysis
Utility procurement consolidation around 20-25 year power purchase agreements is forcing supply chains to absorb extended warranty obligations and performance guarantees that compress margins for turbine manufacturers and subsea cable suppliers.
Pricing Analysis
Volume sits with tidal stream arrays while margins concentrate in wave energy pilot projects. Project-based long-term offtake contracts dominate, with price differentiation driven by capacity factor guarantees and FERC licensing status. Cost compression in utility-scale deployments is intensifying because European and Asian cable suppliers command premium pricing for high-voltage DC transmission. Municipal utilities show highest price sensitivity; defense-adjacent engineering firms demonstrate lowest sensitivity due to captive project development capabilities.
Supply Chain Analysis
Specialized turbine installation expertise concentrates in Norway, the United Kingdom, and the United States Gulf Coast offshore oil service corridors. Horizontal-axis turbine arrays draw from forged steel drivetrain components, composite blade manufacturing, and subsea foundation casting. Single-source vulnerability runs through high-voltage DC cable manufacturing where European and Asian suppliers control capacity. Distribution runs through EPC contractors holding FERC licensing experience and utility interconnection relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ocean power sector is transitioning from oscillating water column designs to articulated multi-segment attenuator wave energy converters that achieve superior capacity factors in Pacific Coast testbeds.
For Market Incumbents: Cement technology leadership by securing exclusive supply agreements with Norwegian and UK offshore installation contractors before workforce scarcity intensifies. Pursue backward integration into subsea foundation manufacturing to defend margins against commodity volatility in forged steel components. The threat of emerging point absorber specialists with Department of Energy demonstration funding demands rapid certification investment.
For New Entrants and Emerging Players: The premium-to-economy price gap in grid integration infrastructure offers entry points for synchronous condenser and reactive power compensation specialists. Target British Columbia and Nova Scotia coastlines where Fisheries and Oceans Canada permitting coordination remains underdeveloped. A go-to-market angle through aquaculture co-location partnerships diversifies revenue beyond electricity sales.
For Investors and Strategic Acquirers: Re-rating potential sits with autonomous platform developers given convergence opportunities between offshore energy and maritime surveillance applications. Long-term viability favors entities with demonstrated FERC pilot-to-commercial license transitions and secured interconnection queue positions. Watch National Marine Fisheries Service consultation timelines as the inflection signal for project velocity acceleration or stagnation.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Extension | Twenty-five year contracts with California community choice aggregators transfer offtake risk to ratepayers. |
| FERC Licensing Transition | Pilot-to-commercial permit advancement unlocks project finance for Washington state tidal arrays. |
| Backward Integration into Foundations | In-house subsea foundation production reduces exposure to European steel casting lead times. |
| Autonomous Platform Diversification | PowerBuoy-type convergence with aquaculture and surveillance expands addressable market beyond utilities. |
| Provincial Permit Coordination | Fisheries and Oceans Canada alignment accelerates environmental review for Nova Scotia tidal sites. |
Research Methodology
Multi-period observation of FERC licensing timelines, interconnection queue positions, and power purchase agreement execution anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA generation data, FERC project filings, IEA marine energy reports, and national laboratory demonstration databases. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling provided triangulation.
Segment-weighting across technology type, deployment scale, and end-user procurement structure informed the analytical framework across the projection horizon. CAGRs were derived from technology-specific learning curve assumptions and policy incentive trajectory modeling. Forecast inputs incorporated Inflation Reduction Act tax credit utilization rates and coastal municipality renewable portfolio standard compliance pathways.
Underlying measurement precision varies by segment; tidal stream deployments with established supply chains carry tighter precision than wave energy frontier designs. Forecasts reflect assumptions regarding FERC regulatory streamlining and cable manufacturing capacity expansion. Material deviation in National Marine Fisheries Service consultation timelines or high-voltage DC supply constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Solar Farm Market
Renewable Energy
Global Green Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Green Power Market