
 Ultra Low Temperature Lithium Battery Market | 2026-2036
Ultra Low Temperature Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Low Temperature Lithium Battery Market Insights
Asset-light leasing models for battery-as-a-service fleets is tilting competitive economics toward manufacturers with captive financing arms. CATL leverages its vertical integration into electrolyte chemistry to sustain margin control across cold-climate contracts. Samsung SDI anchors premium aerospace and medical device supply through its specialization in high-reliability cell architectures. BYD competes on manufacturing scale, using in-house vehicle integration to dominate captive demand from its own electric truck and bus platforms.
Ultra low temperature lithium batteries are electrochemical storage cells engineered to maintain discharge capacity and cycle stability at temperatures below minus twenty degrees Celsius, typically achieved through fluorinated electrolyte formulations, silicon-doped anodes, and active thermal management subsystems. Their primary purpose is to power equipment in polar logistics, high-altitude aerospace, and cold-chain medical transport where standard lithium-ion cells experience catastrophic capacity fade. The LiFePO4 chemistry segment leads in military and stationary cold-climate deployments due to its inherent thermal stability and extended cycle life, while solid state architectures represent the fastest-growing technology category as electrode engineering breakthroughs promise wider operating windows without auxiliary heating. Electric vehicles constitute the most contested application battleground, with aerospace manufacturers and healthcare providers representing higher-margin but lower-volume end user pools.
The US FAA and EPA jointly shape market access through airworthiness certification requirements for aircraft auxiliary power units and emissions-linked procurement rules for federal fleet electrification. China's NMPA and GB standards enforce mandatory cold-start performance testing, effectively filtering out suppliers lacking sub-zero validation infrastructure. The EU Green Deal and F-Gas Regulation are accelerating demand for fluorinated electrolyte alternatives, creating compliance complexity for European automotive producers. Stakeholders must monitor how solid state thermal management patents and evolving cold-climate certification protocols in multiple jurisdictions will redistribute competitive advantage across the supplier base.
Market Dynamics
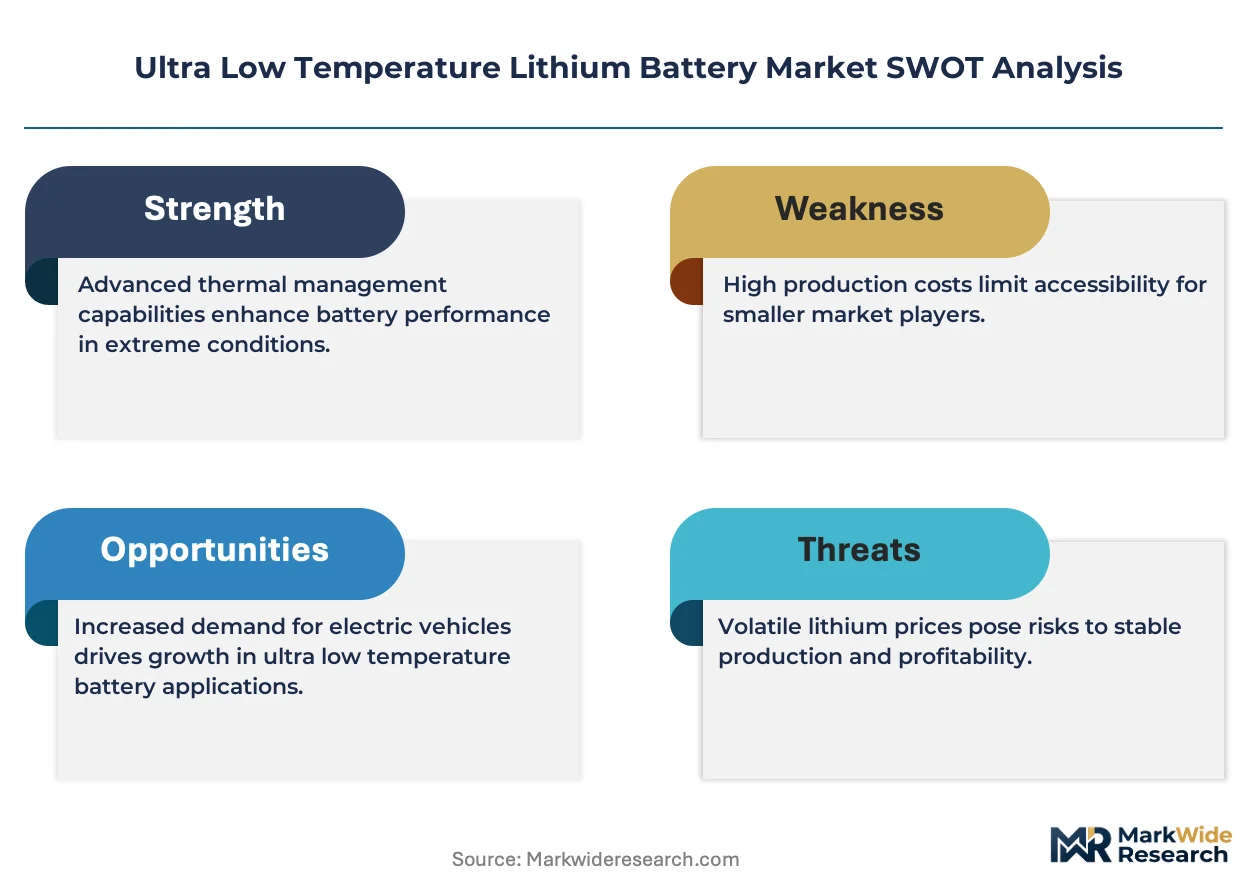
Fluorinated electrolyte formulations are compressing the performance gap between conventional lithium-ion systems and purpose-built cold-climate architectures, forcing incumbent manufacturers to accelerate chemistry roadmaps or surrender premium positioning in polar logistics contracts.
Growth Catalysts
- China's NMPA Cold-Start Mandates:Mandatory sub-zero performance testing under GB standards is filtering out unqualified suppliers and concentrating procurement among validated domestic and foreign cell producers.
- Polar Logistics Fleet Electrification:Arctic shipping operators and Nordic mining contractors are specifying minus-forty-degree capable packs for heavy equipment replacement cycles.
- Solid-State Electrode Engineering:Breakthroughs in silicon-doped anode architectures are widening operating temperature windows without auxiliary thermal management subsystems.
Market Restraints
- Fluorinated Salt Input Concentration:Lithium hexafluorophosphate and specialized electrolyte additives depend on concentrated Chinese chemical processing capacity, exposing cell manufacturers to supply disruption risk.
- EU F-Gas Regulatory Friction:The F-Gas Regulation is accelerating phase-down timelines for fluorinated greenhouse gases used in electrolyte formulations, forcing European automotive producers to reformulate or source externally.
- Active Thermal Management Cost Burden:Auxiliary heating subsystems add fifteen to twenty-five percent to pack bill-of-materials, compressing margins in price-sensitive electric truck segments.
Strategic Opportunities
- Underpenetrated High-Altitude Aerospace:Unmanned aerial systems operating above six thousand meters in the Himalayas and Andes represent unserved demand for ultra-low-temperature cells without ground support infrastructure.
- Battery-as-a-Service Leasing Models:Asset-light fleet financing structures are opening procurement access for mid-sized cold-chain logistics operators previously blocked by upfront capital requirements.
- US IRA Clean Vehicle Tax Credits:Domestic content requirements for federal fleet electrification are creating procurement preference for North American-assembled cold-climate packs.
Industry Challenges
- Sub-Zero Validation Infrastructure Scarcity:Environmental test chambers capable of sustained minus-forty-degree cycling with controlled humidity remain concentrated in China, Germany, and the United States, creating certification bottlenecks for emerging suppliers.
- Solid-State Patent Thickets:Licensing complexity around ceramic electrolyte interfaces and lithium-metal anode stabilization is delaying commercialization timelines for second-tier manufacturers.
- Electrolyte Formulation Talent Gap:Fluorine chemistry specialists with battery-specific experience command premium compensation, constraining R&D expansion at mid-cap cell producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Low Temperature Lithium Battery Market |
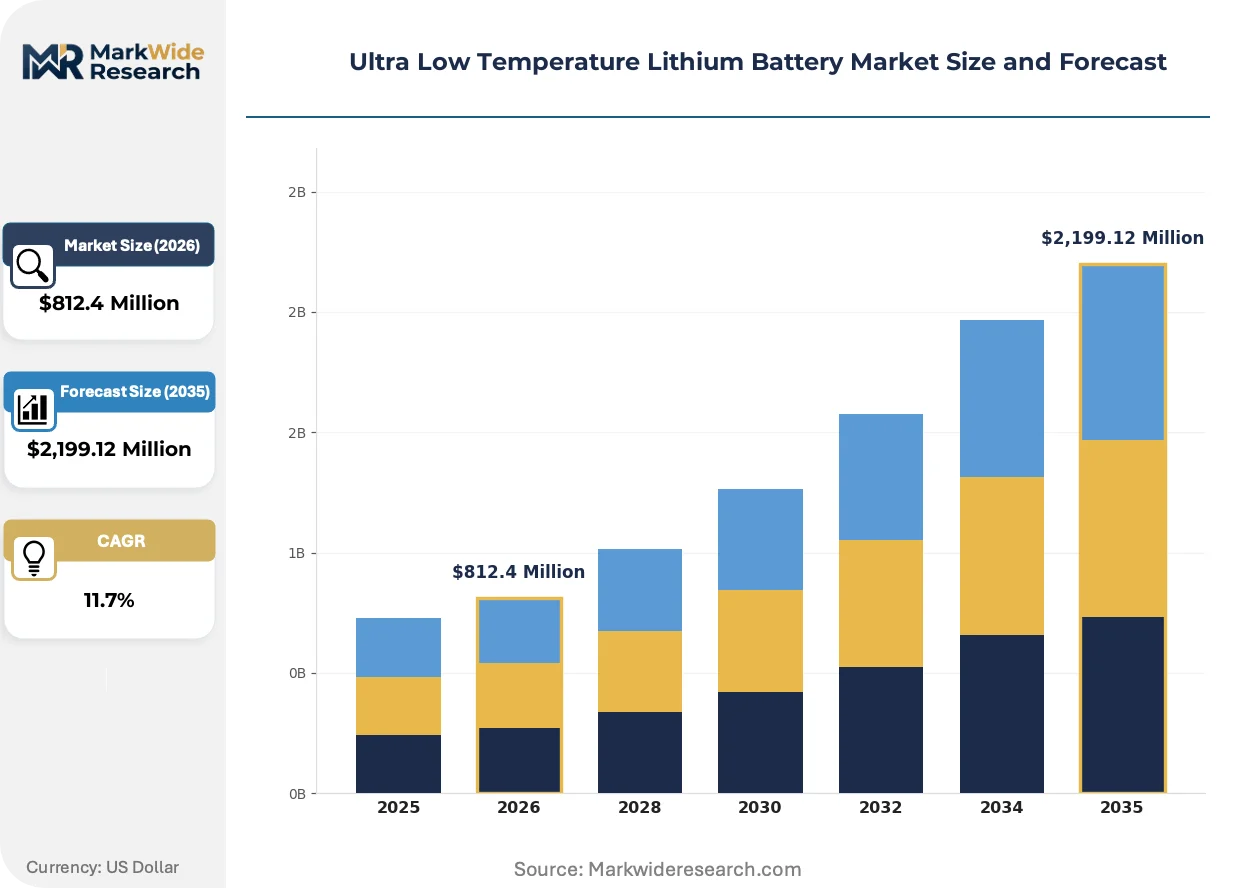
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $2,199.12 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, LiFePO4, Solid State, Nickel-Manganese-Cobalt Application: Aerospace, Military, Medical Devices, Electric Vehicles End User: Healthcare Providers, Aerospace Manufacturers, Automotive Producers, Research Institutions Technology: Thermal Management, Electrolyte Optimization, Electrode Engineering, Battery Management Systems |
| Companies Covered | Samsung SDI, CATL, BYD, Shenzhen Grepow, Lishen, CALB Technology, Maxell, Soundon New Energy, EJEVE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Low Temperature Lithium Battery Market Trends and Innovations
Silicon-doped anode architectures and ceramic electrolyte interfaces are converging to eliminate auxiliary heating subsystems, compressing pack cost structures and unlocking deployment in weight-constrained aerospace applications previously blocked by thermal management mass penalties.
Solid-state lithium-metal cells with sulfide-based ceramic electrolytes are collapsing the temperature-performance tradeoff that has constrained conventional liquid-electrolyte systems. Arctic research stations and high-altitude telecommunications relay platforms are piloting these architectures for unattended multi-year deployments. The elimination of freeze-vulnerable liquid components is enabling form factors and energy densities previously unattainable in sub-zero environments.
The EU F-Gas Regulation is accelerating demand for hydrofluoroether electrolyte alternatives and non-fluorinated lithium salts. European automotive producers are reformulating cell chemistries to maintain cold-start performance while complying with phased greenhouse gas restrictions. Nordic electric bus operators are requiring suppliers to demonstrate F-Gas-compliant formulations in procurement specifications, shifting competitive advantage toward chemistry houses with fluorine-free intellectual property.
Fleet operators in northern China and Scandinavia are consolidating procurement through multi-year battery-as-a-service contracts that transfer residual value risk to manufacturers. Cold-chain logistics providers are replacing spot purchases with performance-guaranteed leasing structures tied to guaranteed discharge capacity at minus-thirty degrees. This shift is concentrating supplier relationships among cell producers with captive financing arms and validated sub-zero field data spanning multiple winter cycles.
Ultra Low Temperature Lithium Battery Market Segmentation
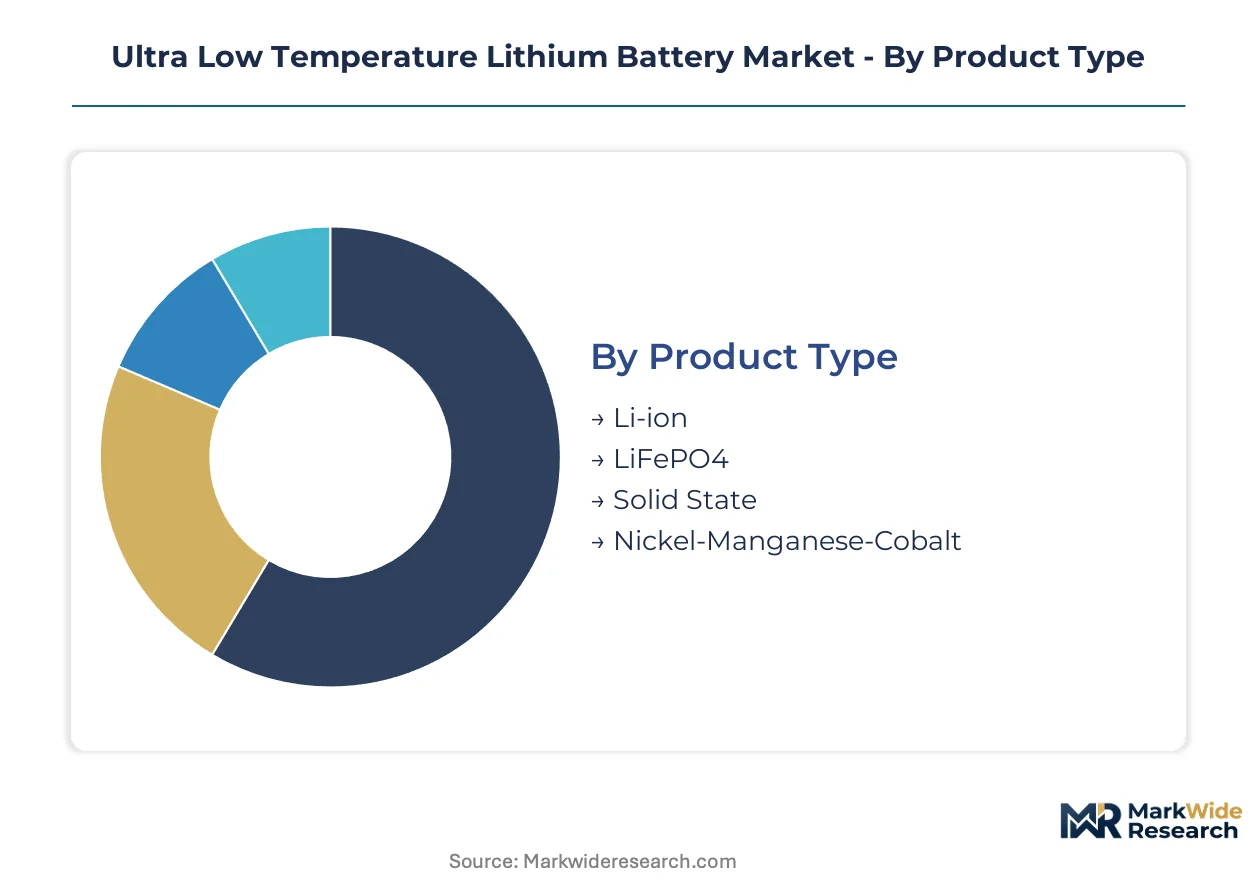
Ultra low temperature lithium battery procurement cycles vary dramatically by chemistry maturity and application criticality. Fleet operators replace electric vehicle packs on predictable wear schedules, while aerospace manufacturers certify cell architectures for decade-long service lives. Understanding these divergent replacement rhythms clarifies where manufacturers must prioritize inventory positioning versus long-term contract security.
Product Type:
LiFePO4 and solid-state architectures command the longest validation cycles, stretching from initial cell qualification through field deployment to replacement tenders. Li-ion and nickel-manganese-cobalt formulations rotate faster due to established supply chains and shorter OEM testing protocols.
- Li-ion:Conventional liquid-electrolyte cells with graphite anodes and lithium cobalt oxide or nickel-manganese-cobalt cathodes. Arctic logistics fleets in northern China and Nordic mining contractors specify these for heavy equipment where active thermal management subsystems can accommodate the mass penalty. Cost sensitivity in electric truck procurement keeps this chemistry competitive despite capacity fade below minus twenty degrees Celsius.
- LiFePO4:Lithium iron phosphate cathodes paired with carbon-based anodes deliver inherent thermal stability and extended cycle life. Military cold-climate deployments and stationary Arctic energy storage specify LiFePO4 for its non-flammable characteristics and tolerance of sustained sub-zero cycling without catastrophic degradation. China's NMPA cold-start mandates favor domestic producers with validated LiFePO4 sub-zero performance data.
- Solid State:Ceramic or sulfide electrolytes replacing liquid components, enabling lithium-metal anodes with wider temperature windows. Unmanned aerial systems above six thousand meters in the Himalayas pilot these for unattended multi-year operation.
- Nickel-Manganese-Cobalt:Layered oxide cathodes balancing energy density and thermal stability. Medical device cold-chain transport in North America and Europe specifies NMC for compact form factors where discharge capacity at minus thirty degrees is mandatory.
LiFePO4 anchors the volume base in military and stationary deployments while solid-state gains share at the steepest rate across aerospace applications.
Application:
Medical device and electric vehicle procurement scales with fleet turnover and regulatory recertification timelines. Aerospace and military programs extend across multi-year development cycles with frozen specifications post-qualification.
- Aerospace:Auxiliary power units and propulsion systems for high-altitude unmanned platforms require airworthiness certification under US FAA standards. Himalayan and Andean telecommunications relay operators specify ultra-low-temperature cells without ground support infrastructure.
- Military:Arctic expeditionary equipment and polar logistics vehicles demand minus-forty-degree discharge capability under NATO and national defense procurement rules. Extended unattended operation requirements prioritize cycle stability over energy density.
- Medical Devices:Portable cold-chain equipment and field diagnostic instruments require guaranteed capacity at clinical storage temperatures. Healthcare providers in northern climates specify sub-zero capable packs for emergency response vehicle integration.
- Electric Vehicles:Cold-climate bus and truck fleets in Scandinavia and northern China specify battery-as-a-service contracts transferring residual value risk to manufacturers. Active thermal management adds fifteen to twenty-five percent to pack cost structures.
Electric vehicles generate the highest procurement volume while aerospace commands the steepest pricing tiers due to certification complexity.
End User:
Automotive producers consolidate procurement through multi-year fleet contracts, while research institutions purchase on irregular grant-funded cycles tied to expedition schedules.
- Healthcare Providers:Hospital systems and emergency medical services specify cold-chain portable equipment for pharmaceutical transport and field deployment. Nordic operators increasingly require F-Gas-compliant electrolyte formulations in procurement specifications.
- Aerospace Manufacturers:Tier-one suppliers and original equipment manufacturers integrate cells into auxiliary power units and propulsion systems. US FAA airworthiness certification requirements filter supplier pools to validated domestic and foreign producers.
- Automotive Producers:Electric truck and bus manufacturers in cold-climate zones specify sub-zero capable packs through captive integration or external procurement. China's GB standards enforce mandatory cold-start performance testing.
- Research Institutions:Arctic and Antarctic scientific stations pilot solid-state architectures for unattended multi-year energy storage. Procurement concentrates through national polar research programs with extended qualification timelines.
Automotive producers anchor the volume base while research institutions adopt emerging chemistries at the steepest rate despite smaller absolute procurement.
Technology:
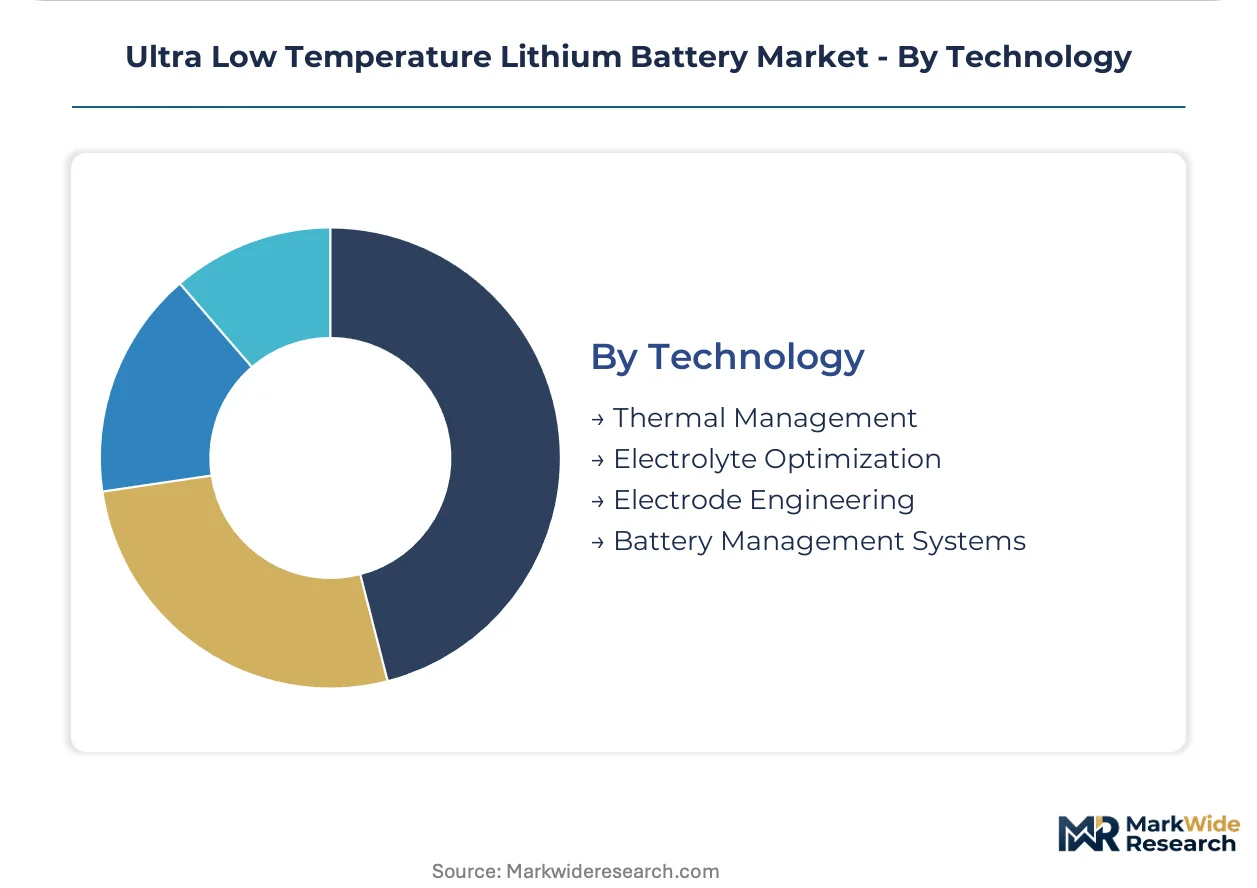
Electrolyte optimization and electrode engineering advance on compressed R&D cycles, while thermal management and battery management systems extend across platform generations with incremental firmware updates.
- Thermal Management:Active heating subsystems and phase-change materials maintain cell operating temperatures in ambient conditions below minus forty degrees Celsius. Electric truck segments absorb the cost burden for guaranteed cold-start performance.
- Electrolyte Optimization:Fluorinated salt formulations and hydrofluoroether alternatives widen liquid-phase stability windows. European automotive producers reformulate to comply with EU F-Gas Regulation phase-down timelines.
- Electrode Engineering:Silicon-doped anode architectures and lithium-metal stabilization techniques collapse temperature-performance tradeoffs. Solid-state development programs concentrate patent activity around ceramic electrolyte interfaces.
- Battery Management Systems:Firmware-controlled charge algorithms and cell balancing circuits optimize sub-zero cycling behavior. Field data from validated winter deployments differentiates supplier competitive positioning.
Battery management systems anchor the volume base across all chemistry platforms while electrode engineering attracts the steepest R&D investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean vehicle tax credits under the US Inflation Reduction Act and China's NMPA cold-start mandates are redirecting procurement flows toward validated domestic suppliers. Arctic logistics electrification in Scandinavia and high-altitude aerospace demand in the Himalayas are creating geographically concentrated growth pockets.
China
Electric truck and bus fleets in Harbin and Changchun specify sub-zero capable packs through battery-as-a-service contracts. The NMPA enforces mandatory GB standards cold-start performance testing that filters out unqualified cell producers. Shenzhen and Ningbo anchor electrolyte formulation clusters where domestic manufacturers validate fluorinated salt architectures.
United States
Federal fleet electrification under IRA domestic content rules favors North American-assembled cold-climate packs. The FAA airworthiness certification requirements constrain supplier pools for aircraft auxiliary power units. Michigan and Ohio-based automotive producers integrate sub-zero validated cells into electric truck platforms for Great Lakes winter operation.
Germany
Automotive producers in Bavaria and Baden-Württemberg reformulate cell chemistries to comply with EU F-Gas Regulation phase-down timelines. The ECHA oversees chemical safety assessments for hydrofluoroether electrolyte alternatives. Stuttgart-based OEMs specify cold-start performance guarantees in procurement contracts for Nordic electric bus deployments.
Norway
Arctic shipping operators and mining contractors in Tromsø and Kirkenes specify minus-forty-degree capable packs for heavy equipment replacement cycles. National procurement rules favor F-Gas-compliant formulations in public fleet tenders. Bergen-based cold-chain logistics providers consolidate procurement through multi-year performance-guaranteed leasing structures.
Japan
High-reliability cell architectures from METI-supported R&D programs supply aerospace manufacturers for auxiliary power units. Osaka and Nagoya industrial clusters concentrate silicon-doped anode development for solid-state cold-climate applications. Domestic producers prioritize medical device cold-chain specifications for pharmaceutical transport equipment.
Ultra Low Temperature Lithium Battery Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with captive financing arms and validated sub-zero field data. Chemistry houses with fluorine-free intellectual property are gaining share in European procurement. Three archetypes dominate: vertically integrated conglomerates with in-house electrolyte production, specialized high-reliability cell architects, and scale-driven automotive-integrated producers. Competitive moves center on strategic partnerships for solid-state patent licensing and geographic expansion of environmental test chamber networks.
Among Asia-Pacific-based producers, CATL, Samsung SDI, and BYD occupy distinct positioning tiers. CATL represents the chemistry-integrated archetype with upstream control over electrolyte formulations. Samsung SDI exemplifies the high-reliability specialist model serving aerospace and medical device end users. BYD anchors the automotive-captive tier through in-house vehicle integration. Shenzhen Grepow and Lishen sit within the emerging challenger segment, while CALB Technology, Maxell, Soundon New Energy, and EJEVE represent regional specialists with concentrated domestic market presence.
| Leading Market Players |
|---|
| Samsung SDI |
| CATL |
| BYD |
| Shenzhen Grepow |
| Lishen |
| CALB Technology |
| Maxell |
| Soundon New Energy |
| EJEVE |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese electrolyte formulation facilities is compressing supplier margins while simultaneously enabling aggressive pricing postures for cold-climate cell contracts. Utilization rates below sixty percent in Ningbo and Shenzhen chemical clusters are forcing domestic producers to absorb input cost volatility to maintain fleet procurement relationships.
Pricing Analysis
Certification level (FAA airworthiness, NMPA GB-standard, EU CE marking) creates the primary spread between aerospace-grade premiums and electric truck commodity tiers. Three-tier pricing structure across aerospace-certified, automotive-validated, and industrial-standard levels reflects the cost of sub-zero validation infrastructure. Pricing pressure stems from battery-as-a-service contracts transferring residual value risk to manufacturers. Electric truck fleet operators exhibit highest price sensitivity, while Himalayan telecommunications relay operators accept steep premiums for unattended reliability.
Supply Chain Analysis
Upstream lithium hexafluorophosphate and fluorinated salt feedstocks draw from concentrated chemical processing capacity in China, South Korea, and Japan. Silicon-doped anode precursors and ceramic electrolyte substrates rest on specialized semiconductor-grade manufacturing in Taiwan and Germany. Single-source vulnerability in Chinese electrolyte additives exposes cell producers to supply disruption risk. Distribution runs through validated environmental test chamber networks concentrated in China, Germany, and the United States before final pack assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra low temperature lithium batteries sit in early-cycle expansion as polar logistics electrification and high-altitude aerospace adoption accelerate penetration beyond established cold-climate automotive demand.
For Market Incumbents: Harden defensive positioning by locking multi-year battery-as-a-service contracts with captive financing arms before emerging chemistry houses achieve validation scale. Accelerate backward integration into fluorine-free electrolyte formulations to preempt EU F-Gas compliance displacement. Prioritize environmental test chamber geographic expansion to reduce certification bottlenecks threatening contract timelines.
For New Entrants and Emerging Players: Mid-sized cold-chain logistics operators in Scandinavia and northern China represent the most penetrable entry point given their transition from spot purchasing to performance-guaranteed leasing structures. Unmanned aerial systems above six thousand meters in the Himalayas and Andes offer unserved demand without incumbent validation data advantages. Lead with solid-state ceramic electrolyte pilot programs to bypass liquid-formulation patent thickets.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemistry consolidation play because electrolyte formulation talent scarcity and validation infrastructure concentration favor scaled producers with R&D depth. Target acquisition archetypes include fluorine-free intellectual property holders and environmental test chamber operators in underserviced geographies. Watch NMPA cold-start mandate enforcement stringency as the signal for domestic Chinese supplier margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Chemistry | CATL's upstream control over fluorinated salt formulations sustains margin defense against battery-as-a-service pricing pressure. |
| Solid-State Patent Licensing Agreements | Ceramic electrolyte interface licensing collapses temperature-performance tradeoffs for Himalayan aerospace deployments. |
| Environmental Test Chamber Geographic Expansion | Validation infrastructure scarcity in emerging markets creates certification bottlenecks for second-tier manufacturers. |
| F-Gas-Compliant Formulation Development | European automotive producers reformulate to meet EU phase-down timelines while maintaining Nordic bus fleet contracts. |
| Battery-as-a-Service Platform Launch | Asset-light leasing structures open procurement access for mid-sized cold-chain operators previously blocked by capital requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with battery cell engineering directors, fleet procurement managers at Arctic logistics operators, electrolyte formulation specialists, and FAA certification consultants; and secondary validation through NMPA GB standard filings, EU F-Gas Regulation implementation documents, SEC 10-K disclosures from listed cell producers, and customs trade data on lithium salt imports. Bottom-up cell shipment estimates by chemistry and application were triangulated against top-down procurement budget analysis from national polar research programs and defense logistics agencies.
Forecast inputs across the analysis window incorporated chemistry-specific adoption curves, regulatory mandate implementation timelines, and validation infrastructure expansion rates. Segmentation modeling spanned product type, application criticality, end-user procurement rhythm, and technology maturity tier. CAGRs were derived from weighted scenario analysis of electric vehicle fleet turnover cycles and aerospace program development timelines. Solid-state electrode engineering breakthroughs and F-Gas regulatory friction were treated as scenario-dependent variables with asymmetric upside and downside cases.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate pricing volatility, rare earth export restrictions, or Arctic shipping route expansion would shift the trajectory. Forecasts reflect documented assumptions about electrolyte formulation cost curves and cold-climate certification protocol harmonization. Cross-checking against IEA clean technology deployment benchmarks and national defense procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market