
 Wave Energy Converter Market | 2026-2036
Wave Energy Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Wave Energy Converter Market Outlook
Grid-scale certification standards for wave energy arrays is unwinding project finance barriers that previously limited commercial deployment. Ocean Power Technologies leverages its autonomous PowerBuoy platform to dominate early-stage remote power contracts for offshore monitoring. CorPower Ocean sustains technology leadership through its compact high-efficiency point absorber design optimized for Atlantic swell conditions. Eco Wave Power anchors nearshore deployment economics with shore-mounted converter architecture that eliminates deep-water mooring costs.
Wave energy converters are electromechanical systems that transform ocean surface oscillations into electrical output through hydraulic, direct-drive, or pneumatic energy transfer mechanisms, typically rated between 100 kW and 2 MW per unit depending on technology class. Their primary commercial purpose is to deliver predictable baseload-compatible renewable power to coastal grids and industrial offtakers. Point absorbers command the deepest R&D investment pipeline due to modularity and lower material intensity per megawatt. Offshore deployment configurations attract the majority of capital allocation despite higher installation costs, as sustained wave energy density justifies the premium. Floating systems represent the fastest-growing deployment category as shared mooring infrastructure spreads capital burdens across multi-unit arrays.
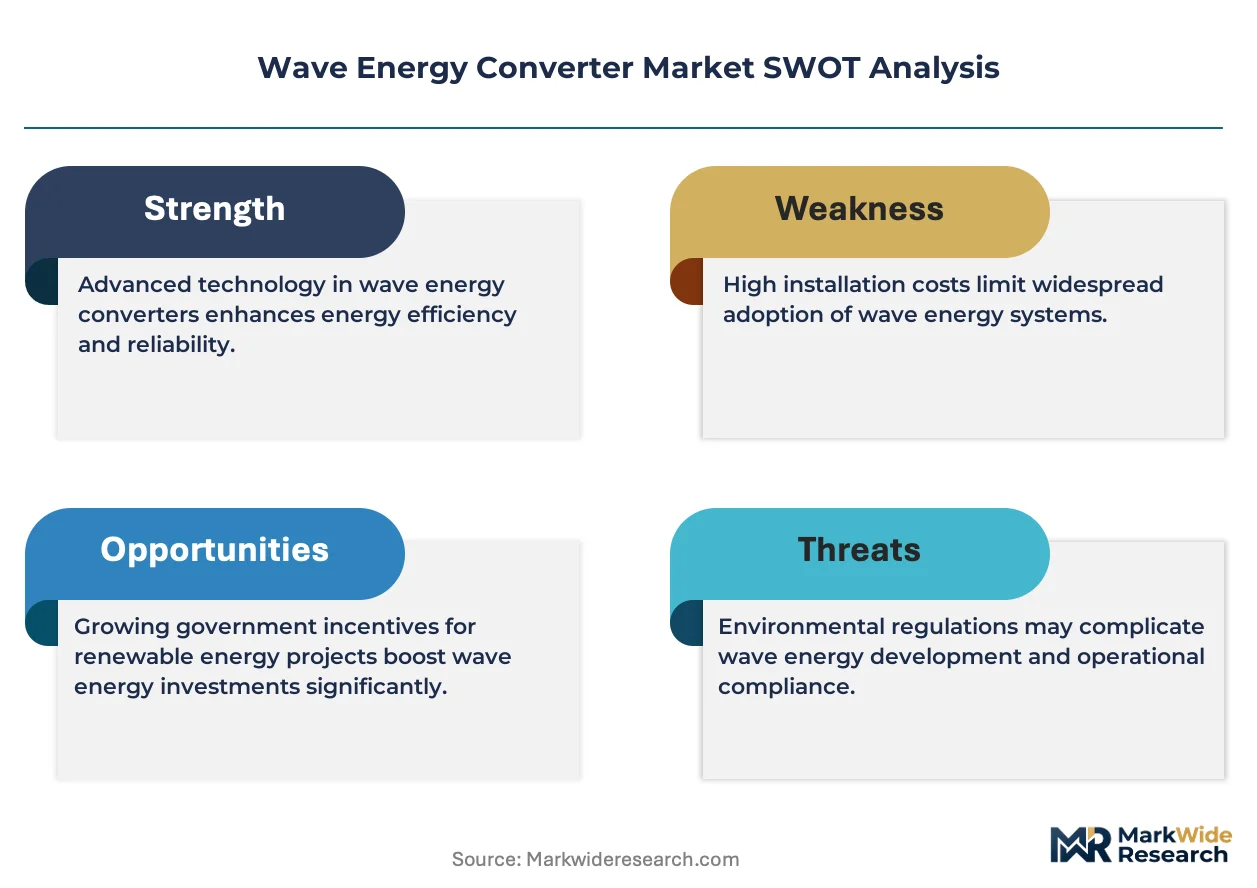
European regulators including EMA, the EU Green Deal framework, and national marine licensing authorities in Scotland and Portugal shape permitting timelines and environmental compliance thresholds for demonstration and commercial arrays. The F-Gas Regulation and REACH chemical standards constrain hydraulic fluid selection and composite material composition in converter manufacturing. Stakeholders must monitor how evolving seabed lease auctions and grid interconnection queue reforms determine which technology developers secure priority access to high-potential wave resource zones.
Market Dynamics
Grid-scale certification standards for wave energy arrays are unwinding project finance barriers that previously limited commercial deployment, while shared mooring infrastructure spreads capital burdens across multi-unit arrays and accelerates floating system adoption.
Growth Catalysts
- EU Green Deal marine spatial planning:Portugal and Scotland have streamlined licensing timelines for demonstration projects, reducing regulatory uncertainty for developers seeking seabed leases.
- Atlantic swell resource density:Sustained wave energy density along Europe's Atlantic coast justifies premium offshore deployment costs and attracts utility offtake commitments.
- Point absorber modularity:Lower material intensity per megawatt and standardized manufacturing processes enable rapid capacity scaling and supply chain replication.
Market Restraints
- Hydraulic fluid compliance costs:Europe's F-Gas Regulation and REACH chemical standards constrain fluid selection and composite material composition, raising manufacturing complexity.
- Deep-water mooring supply concentration:Specialized anchoring system suppliers cluster in Norway and Scotland, creating bottleneck risk for floating array deployments.
- Baseload intermittency mismatch:Wave energy's seasonal variability limits direct grid substitution for dispatchable generation without hybrid storage integration.
Strategic Opportunities
- Orkney Islands cluster expansion:Scotland's established test infrastructure and grid interconnection queue reforms position the archipelago for first commercial array scaling.
- Remote offshore monitoring power:Autonomous platforms for aquaculture and subsea asset monitoring create early revenue streams independent of utility procurement cycles.
- Hybrid wave-wind co-location:Shared electrical infrastructure and marine licensing reduces levelized cost of energy for multi-technology offshore renewable zones.
Industry Challenges
- Marine electrical certification timelines:IEC 62600-30 standards for wave energy converter performance assessment remain underdeveloped, delaying type certification for commercial projects.
- Specialized installation vessel scarcity:Heavy-lift jack-up vessels with dynamic positioning capability face competing demand from offshore wind, compressing deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wave Energy Converter Market |
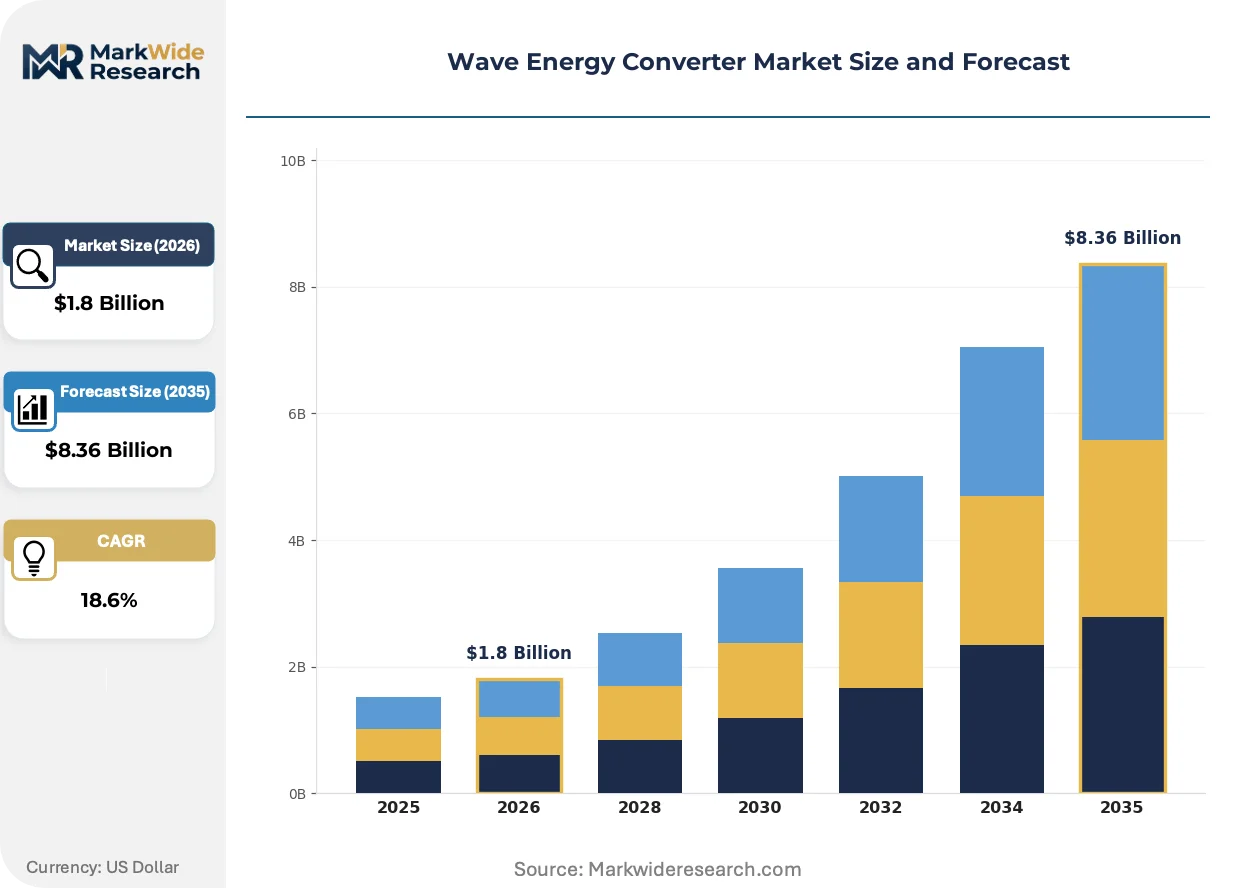
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Point Absorbers, Oscillating Water Columns, Attenuators, Terminators Application: Power Generation, Desalination, Coastal Protection, Aquaculture End User: Utilities, Government, Industrial, Research Institutions Deployment: Offshore, Nearshore, Onshore, Floating Systems |
| Companies Covered | Ocean Power Technologies, CorPower Ocean, Eco Wave Power, Carnegie Clean Energy, Marine Power Systems, SINN Power GmbH, AWS Ocean Energy, NEMOS GmbH, AW-Energy Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wave Energy Converter Market Strategic Shifts
Technology convergence between wave and offshore wind infrastructure is reshaping capital deployment patterns, while regulatory frameworks mature from demonstration support to commercial procurement mandates.
Point absorber technology is fragmenting the converter landscape as compact high-efficiency designs optimized for Atlantic swell conditions attract the deepest R&D investment pipeline. Offshore utilities are prioritizing these modular units for grid-connected arrays. The technology is fragmenting traditional technology categories by enabling standardized manufacturing that compresses supply chain lead times.
Europe's F-Gas Regulation and REACH chemical standards are tightening material compliance thresholds for hydraulic fluids and composite manufacturing. Converter producers must reformulate fluid systems and resin matrices to maintain market access. Portuguese and Scottish licensing authorities are incorporating these standards into environmental impact assessments for seabed lease awards.
Utility procurement departments are consolidating offtake negotiations around long-term power purchase agreements with baseload-compatible performance guarantees. Aggregators and energy trading houses are displacing direct developer-to-utility contracting in the Orkney Islands and northern Portugal. This consolidation is most visible among Atlantic coast European utilities seeking renewable portfolio diversification.
Wave Energy Converter Market Segmentation
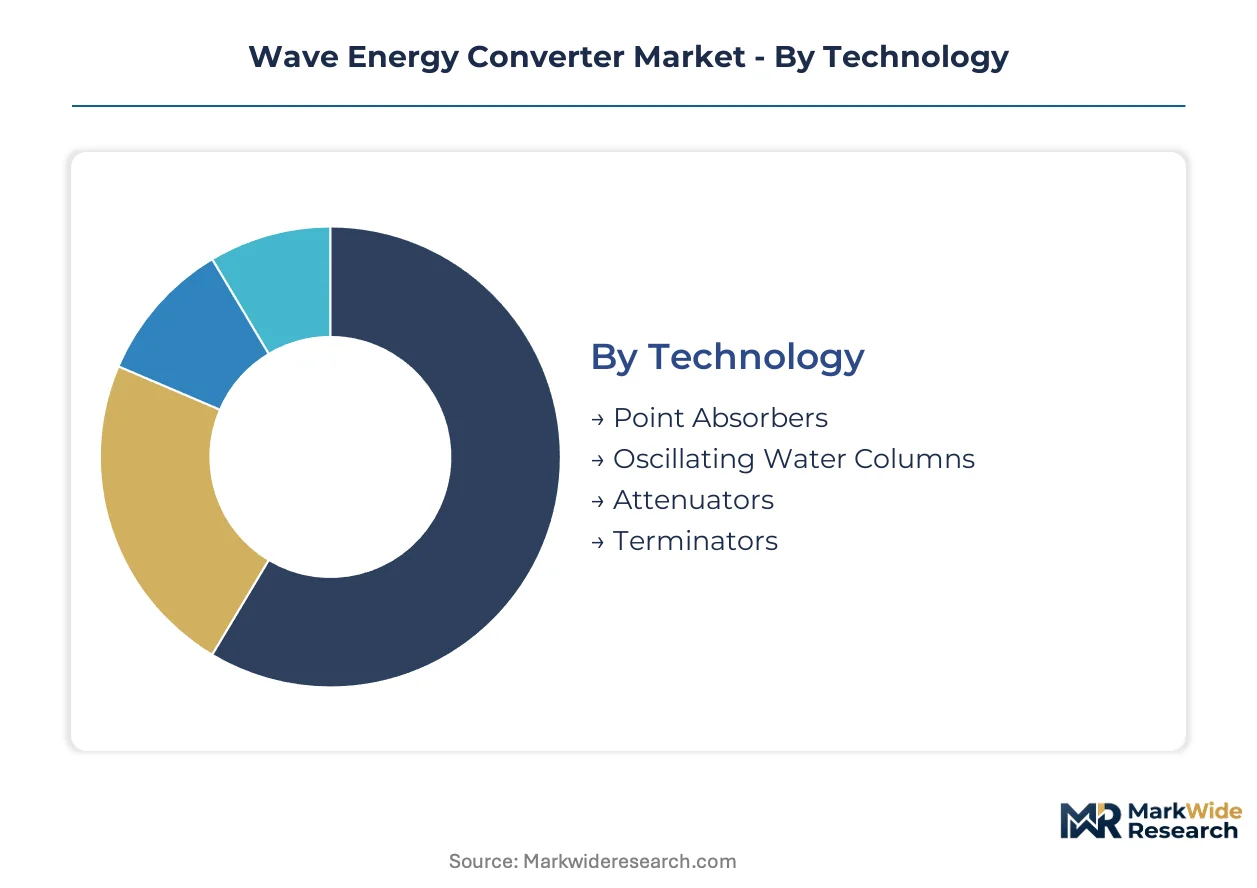
Wave energy converter segmentation reveals how technology maturity, deployment economics, and regulatory frameworks interact to determine commercial viability. Each category carries distinct compliance thresholds and capital requirements that reshape project finance structures across Atlantic demonstration zones.
Technology:
EMA and EU Green Deal certification pathways diverge sharply across converter architectures, with IEC 62600-30 performance standards applying unevenly to hydraulic versus direct-drive systems.
- Point Absorbers:Compact buoyant structures harvest energy through heave motion via hydraulic or direct-drive power take-off systems, typically rated 100-500 kW. Scotland's Orkney Islands cluster concentrates procurement for these modular units as utility offtakers prioritize standardized manufacturing and lower material intensity per megawatt.
- Oscillating Water Columns:Shore-mounted or floating chambers compress air through wave-driven water pistons driving bidirectional turbines. Portugal's northern coastline attracts deployment commitments for these systems as F-Gas Regulation compliance costs favor pneumatic over hydraulic energy transfer mechanisms.
- Attenuators:Long multi-segment floating structures oriented parallel to wave fronts.
- Terminators:Shore-perpendicular structures that capture wave energy at coastline termination points.
Established volume favors Point Absorbers; emerging adoption favors Oscillating Water Columns.
Application:
Cost tier differentiation separates grid-connected revenue streams from subsidized demonstration purposes, with power purchase agreement eligibility determining project bankability.
- Power Generation:Grid-connected arrays delivering baseload-compatible renewable electricity through utility-scale interconnection infrastructure. Atlantic coast European utilities concentrate procurement here as EU Green Deal marine spatial planning streamlines seabed leasing for commercial arrays.
- Desalination:Direct mechanical or electrical drive of reverse osmosis systems without grid interconnection. Coastal municipalities in water-stressed Atlantic regions pilot these configurations where grid connection costs exceed desalination equipment capital expenditure.
- Coastal Protection:Dual-purpose installations that attenuate wave energy while generating power.
- Aquaculture:Remote power supply for offshore fish farm monitoring and feeding systems.
Power Generation commands the deepest capital allocation; Desalination offers the steepest expansion trajectory for off-grid coastal installations.
End User:
Customer type determines procurement timeline urgency, with utility procurement cycles spanning 18-36 months versus research institution grant-driven schedules.
- Utilities:Vertically integrated European energy companies and independent power producers seeking renewable portfolio diversification through long-term power purchase agreements. EMA and national marine licensing authorities in Scotland and Portugal prioritize these applicants in seabed lease auctions.
- Government:National energy agencies and regional development authorities funding demonstration projects. These entities absorb technology risk through grant mechanisms that commercial offtakers avoid.
- Industrial:Offshore oil and gas operators, aquaculture conglomerates, and desalination plant developers.
- Research Institutions:Universities and national laboratories conducting performance validation and environmental impact assessment.
Utilities drive commercial scaling; Research Institutions enable technology maturation.
Deployment:
Supply concentration for specialized installation vessels and mooring systems creates bottleneck risk that varies dramatically by water depth and foundation type.
- Offshore:Deep-water installations beyond 50 meters depth accessing sustained Atlantic swell energy density. Norway and Scotland anchor the global supply base for dynamic positioning heavy-lift vessels and specialized anchoring systems required here.
- Floating Systems:Multi-unit arrays sharing mooring infrastructure to distribute capital burdens across generating capacity. These configurations expand most quickly as shared electrical infrastructure reduces levelized cost of energy for multi-technology offshore renewable zones.
- Nearshore:Shallow-water installations within visual range of coastline.
- Onshore:Cliff-mounted or shoreline-integrated structures with no marine foundation requirements.
Offshore deployment attracts premium capital allocation; Floating Systems gain share fastest through infrastructure sharing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized anchoring system suppliers cluster in Norway and Scotland, creating geographic chokepoints for floating array deployments. This supply concentration shapes where demonstration projects secure priority access to seabed leases and grid interconnection capacity.
Portugal
Atlantic swell conditions along the northern coastline attract utility offtake commitments for grid-connected arrays. The EU Green Deal marine spatial planning directive has streamlined licensing timelines for demonstration projects. The Aguçadoura cluster anchors early commercial scaling as seabed lease auctions prioritize wave-wind hybrid zones.
Scotland
The Orkney Islands host Europe's densest concentration of wave energy test infrastructure and operational validation sites. EMA and national marine licensing authorities prioritize utility applicants in interconnection queue reforms. Aberdeen and the Pentland Firth corridor concentrate specialized installation vessel supply and dynamic positioning heavy-lift capacity.
Norway
Deep-water mooring system fabricators dominate global supply for floating converter arrays. The country's offshore oil and gas engineering base transfers expertise into marine renewable anchoring solutions. Stavanger and Bergen anchor the supply chain for specialized anchoring systems required in Atlantic swell conditions.
Ireland
Western coastline wave resource density matches Atlantic conditions in Portugal and Scotland. The national marine spatial planning framework incorporates F-Gas Regulation compliance into environmental impact assessments for seabed awards. Galway Bay hosts test infrastructure where point absorber developers validate performance against IEC 62600-30 standards.
Spain
Basque Country engineering clusters support component fabrication for attenuator and terminator architectures. The national energy agency channels grant mechanisms toward demonstration projects that commercial offtakers avoid. Bilbao anchors manufacturing partnerships between converter developers and offshore wind supply chain incumbents.
Wave Energy Converter Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across the value chain. Point absorber specialists compete on modularity and material efficiency against shore-mounted architecture providers that eliminate deep-water mooring costs. Three archetypes dominate: autonomous platform developers serving remote power contracts, compact high-efficiency designers optimized for Atlantic swell, and nearshore deployment specialists capitalizing on simplified foundation requirements. Strategic moves concentrate on shared mooring infrastructure partnerships and hybrid wave-wind co-location arrangements that spread capital burdens across multi-technology arrays.
Among Atlantic-facing developers, Ocean Power Technologies, CorPower Ocean, and Eco Wave Power exemplify distinct competitive positions. Ocean Power Technologies occupies the autonomous platform tier where remote power contracts generate early revenue independent of utility procurement cycles. CorPower Ocean sits within the compact high-efficiency archetype that attracts the deepest R&D investment pipeline for grid-connected arrays. Eco Wave Power anchors the nearshore deployment category through shore-mounted converter architecture that eliminates deep-water mooring costs and associated supply chain bottlenecks.
| Leading Market Players |
|---|
| Ocean Power Technologies |
| CorPower Ocean |
| Eco Wave Power |
| Carnegie Clean Energy |
| Marine Power Systems |
| SINN Power GmbH |
| AWS Ocean Energy |
| NEMOS GmbH |
| AW-Energy Oy |
| Others |
Value Chain & Pricing Dynamics
Composite resin substitution for steel hull structures simultaneously shifts fabrication geography toward Basque Country engineering clusters and compresses capital expenditure per megawatt for floating converter arrays. This material transition concentrates pricing power among polymer suppliers qualified under REACH chemical standards while eroding traditional shipyard cost advantages.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across converter procurement contracts. Three-tier pricing structure across premium, standard, and economy levels segments by IEC 62600-30 certification progress and grid interconnection queue priority. Cost compression in economy-tier units is intensifying because F-Gas Regulation compliance adds hydraulic fluid reformulation expense. Research institutions exhibit highest price sensitivity due to grant-funded budgets, while Atlantic coast utilities prioritize performance guarantees over unit economics.
Supply Chain Analysis
Port congestion at Aberdeen and Stavanger elevates inbound logistics costs for dynamic positioning heavy-lift vessels serving floating array deployments. Supply concentrates in Norway for deep-water mooring systems, Scotland for installation vessel fleets, and Spain for composite hull fabrication. Converter manufacturing draws from carbon fiber composites, rare-earth permanent magnets, and specialized hydraulic fluids. Single-source vulnerability runs through Norwegian anchoring system fabricators. Distribution feeds from EPC contractors directly to utility project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wave energy converter market operates as a regulatory-moat arena where EU Green Deal licensing entrenchment and marine spatial planning queue priority create durable competitive shelter for first-movers.
For Market Incumbents: Secure shared mooring infrastructure partnerships across the Orkney Islands cluster to lock in seabed lease economics before interconnection queue reforms mature. Defend against shore-mounted architecture entrants by deepening backward integration into composite hull manufacturing in Basque Country fabrication facilities. Prioritize IEC 62600-30 certification investment to maintain premium-tier pricing access.
For New Entrants and Emerging Players: Lead with remote offshore monitoring power contracts for aquaculture and subsea asset operators where utility procurement cycles do not gate revenue. Target Portugal's northern coastline demonstration zones where streamlined licensing timelines reduce regulatory capital requirements. Pursue white-label manufacturing partnerships with established composite fabricators to compress supply chain lead times.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with point absorber specialists that have secured EMA validation but lack utility-scale deployment capital. Frame long-term viability around hybrid wave-wind co-location economics where shared electrical infrastructure spreads capital burdens. Monitor seabed lease auction participation rates as the inflection signal for commercial scaling readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Shared Mooring Infrastructure Partnership | Distributes capital burdens across multi-unit arrays in Scotland's Pentland Firth corridor. |
| Hybrid Wave-Wind Co-Location Arrangement | Reduces levelized cost of energy through shared electrical infrastructure with offshore wind developers. |
| Composite Material Supply Agreement | Secures REACH-compliant resin matrices from Basque Country engineering clusters. |
| IEC 62600-30 Certification Pathway | Unlocks premium-tier pricing for grid-connected utility procurement in Portugal and Scotland. |
| Remote Power Contract Portfolio | Generates early revenue streams from aquaculture operators independent of utility cycles. |
Study Parameters
Desk research of EIA marine energy databases, IEA ocean technology reports, and FERC interconnection filings preceded structured interviews with utility planning officers, wave energy project developers, EPC contractors, and grid operators. Primary fieldwork captured deployment cost structures and licensing timeline variability across Atlantic demonstration zones. Secondary validation drew from EU Green Deal policy documents, EMA seabed lease records, and REACH chemical compliance registries. Bottom-up project economics triangulated against top-down market sizing from regulatory capacity targets.
Variance decomposition across technology type, deployment configuration, and end-user category shaped the analytical framework over the projection horizon. Modeled dimensions span converter architecture, water depth classification, grid connection scale, and national regulatory framework. CAGRs derived from utility procurement pipeline analysis and seabed lease auction schedules. Forecast inputs incorporated F-Gas Regulation compliance cost trajectories and heavy-lift vessel availability assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding continuity and Atlantic swell resource stability would require recalibration. Forecasts reflect assumptions around marine electrical certification timeline progression and shared infrastructure deployment velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Nordic Countries Renewable Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Point Absorber Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Solar Chimney Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar Cooker Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
North America IoT in Renewable Energy Market