
 Global Organic Rankine Cycle Market | 2026-2036
Global Organic Rankine Cycle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Rankine Cycle Market Outlook
Waste heat recovery is rebalancing the end-use mix as industrial operators retrofit cement, steel, and chemical facilities. Ormat Technologies leverages its geothermal heritage to anchor utility-scale project development across multiple continents. Turboden S.p.A. specializes in biomass and waste heat installations, sustaining a dominant position in European industrial parks. Exergy International differentiates through small-scale modular architectures that compete for distributed generation contracts.
The Organic Rankine Cycle converts low-to-medium temperature heat into electricity using a vaporized organic working fluid with boiling points below water, typically operating between 80°C and 350°C thermal input. Expander-generator sets paired with shell-and-tube or plate heat exchangers constitute the core thermodynamic hardware, enabling power extraction from sources otherwise unsuitable for steam Rankine systems. Stationary installations occupy the largest installed base due to decades of geothermal and industrial cogeneration deployment, while modular units represent the fastest-growing configuration as containerized systems reduce site engineering and commissioning burdens. Dual-loop technology dominates safety-critical applications involving flammable or toxic heat sources, whereas direct expansion systems lead in geothermal brine operations where working fluid simplicity reduces maintenance overhead.
The EPA enforces industrial emissions standards that compel waste heat capture, while the EU F-Gas Regulation restricts high-GWP working fluids and accelerates adoption of low-flammability hydrocarbon and HFO alternatives. Japan's METI supports geothermal development through feed-in tariffs that improve project economics for ORC developers. Stakeholders must monitor working fluid phase-down schedules and national geothermal licensing frameworks to secure feedstock access and technology certification.
Market Dynamics
The EU F-Gas Regulation's phase-down of high-GWP working fluids is forcing simultaneous retooling of heat exchanger architectures and working fluid supply chains across the installed base.
Growth Catalysts
- Industrial Emissions Mandates:The EPA enforces waste heat capture requirements in cement and steel facilities, compelling retrofits that expand ORC deployment.
- Feed-in Tariff Structures:Japan's METI supports geothermal development through guaranteed pricing mechanisms that improve project returns for developers.
- Low-Flammability Fluid Innovation:Hydrocarbon and HFO alternatives are replacing phased-out refrigerants in safety-critical dual-loop installations.
Market Restraints
- Working Fluid Supply Concentration:European chemical producers dominate HFO manufacturing, creating import dependency for Asian and North American project developers.
- Heat Source Variability:Cement kiln off-gas temperature fluctuations reduce ORC capacity factors below geothermal baseload economics.
- Steam Rankine Competition:High-temperature waste streams above 350°C remain more efficiently served by conventional steam systems in utility-scale configurations.
Strategic Opportunities
- Modular Containerized Systems:Containerized ORC units reduce site engineering burdens and accelerate commissioning timelines for distributed generation contracts.
- Chemical Plant Integration:Exothermic process streams in petrochemical facilities represent underexploited heat sources for direct expansion architectures.
- EU Green Deal Alignment:Industrial decarbonization funding streams prioritize waste heat recovery investments in energy-intensive manufacturing clusters.
Industry Challenges
- Working Fluid Certification Timelines:ASME and PED compliance pathways for novel low-GWP fluids extend project development cycles by 12-18 months.
- Thermodynamic Engineer Scarcity:Specialized expertise in organic fluid property modeling and expander matching remains concentrated among legacy geothermal engineering firms.
- Legacy Control System Integration:Retrofit installations require protocol bridging between ORC plant controllers and existing DCS infrastructure in mature industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Rankine Cycle Market |
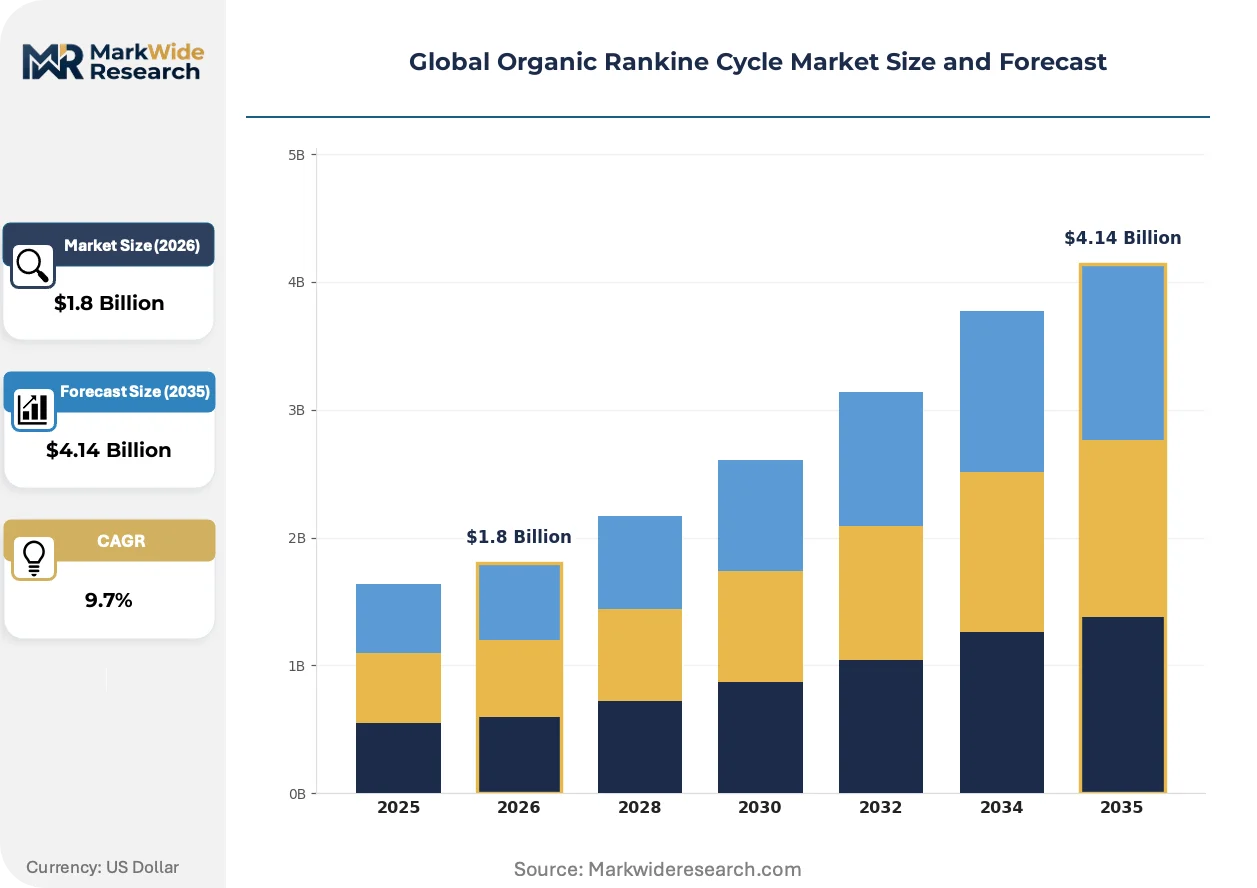
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary, Mobile, Modular, Hybrid Technology: Direct Expansion, Dual-Loop, Heat Transfer, Regenerative End User: Geothermal, Waste Heat Recovery, Biomass Power, Solar Thermal Application: Industrial, Commercial, Residential, Power Generation |
| Companies Covered | Ormat Technologies, Turboden S.p.A., Calnetix Technologies, Exergy International, Alfa Laval, Kaishan USA, ENOGIA, Triogen, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Rankine Cycle Market Strategic Shifts
Digital twin architectures and predictive maintenance platforms are compressing operational expenditure profiles while regulatory fluid transitions reshape equipment specifications.
Advanced expander-generator control systems is automating real-time optimization of working fluid flow rates against variable heat source temperatures. Cement operators in Germany and Italy are deploying these systems at pilot scale before fleet-wide rollout. The technology is automating load-following capabilities that previously required manual operator intervention, reducing parasitic losses during partial-load operation.
The EU F-Gas Regulation's staged phase-down of R-245fa and similar high-GWP fluids is mandating wholesale redesign of heat exchanger surface geometries and sealing systems. Equipment manufacturers must recertify pressure vessel designs for alternative thermodynamic properties. Geothermal brine applications in Italy and Japan are accelerating adoption of direct expansion architectures that eliminate secondary loop complexity and reduce fluid inventory requirements.
Performance-based service contracting is displacing traditional equipment purchase models in industrial waste heat recovery. EPC firms and technology licensors are capturing long-term revenue streams through availability guarantees and energy output commitments. This shift concentrates procurement authority with corporate sustainability officers rather than plant engineering departments, most visibly in German steel and chemical conglomerates pursuing Scope 2 emissions reductions.
Global Organic Rankine Cycle Market Segmentation
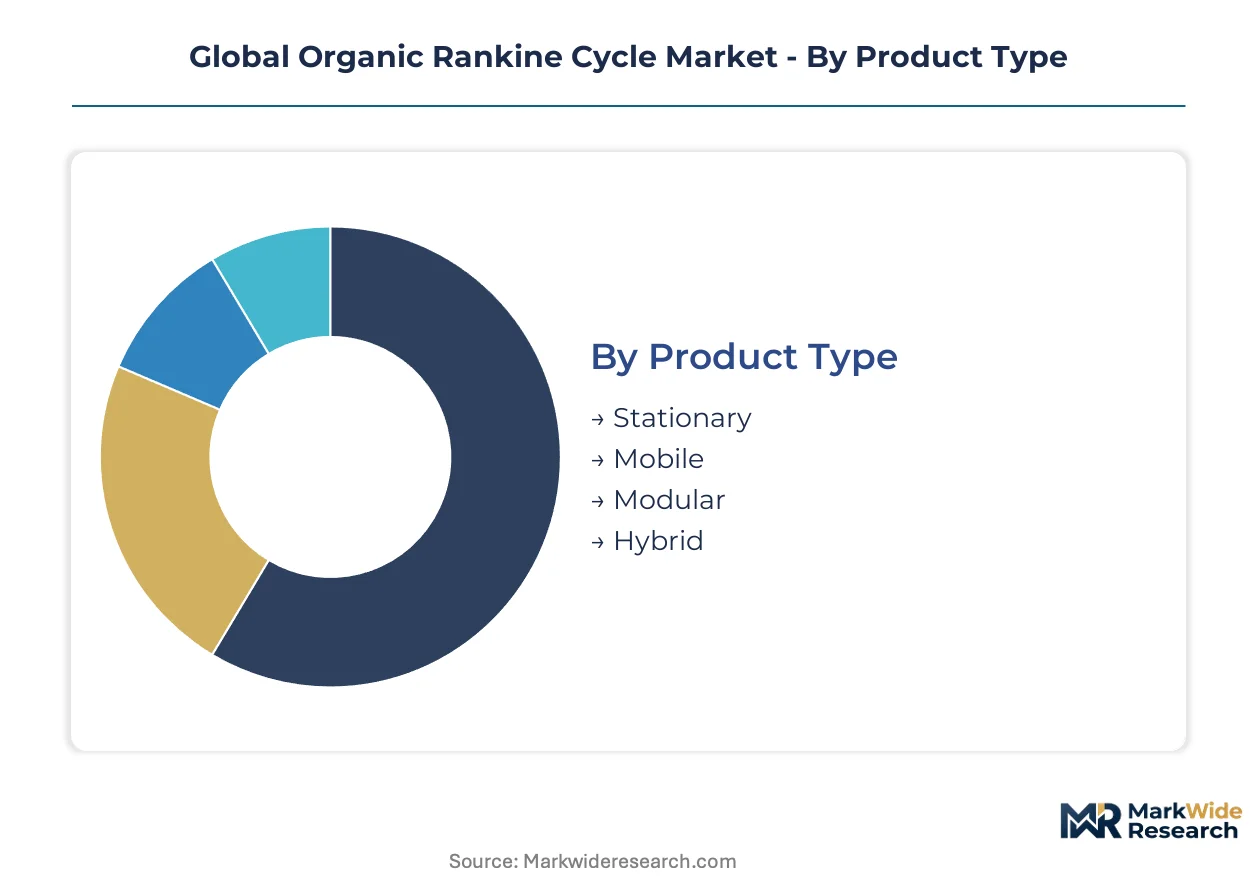
ORC equipment specifications diverge sharply across deployment contexts, with certification pathways from ASME, PED, and IEC shaping hardware selection for each segment. Working fluid compatibility and heat source characteristics further differentiate procurement criteria across the four primary segmentation dimensions.
Product Type:
ASME Section VIII and PED Module H certification burdens concentrate on stationary units given their pressure vessel scale, while modular systems navigate streamlined CE marking pathways through pre-fabrication.
- Stationary:Fixed-site installations anchor utility-scale geothermal and industrial cogeneration with field-erected turbine halls and permanent heat exchanger arrays. Cement plants in Germany and steel facilities in Japan deploy these for baseload waste heat recovery, though site-specific engineering extends commissioning timelines.
- Modular:Containerized skid-mounted systems compress deployment schedules through factory acceptance testing and reduced civil works. Distributed generation developers in Italy favor these for biomass and small-scale geothermal, with 40-foot ISO container footprints enabling rapid relocation.
- Mobile:Trailer-mounted units serve temporary power needs at remote drilling sites and military forward operating bases, with compact expander-generator sets rated below 500kWe.
- Hybrid:Configurations combining ORC with gas turbines or fuel cells optimize total system efficiency in combined heat and power architectures.
Stationary sits at the top of the volume ranking, with Modular climbing the fastest.
Technology:
Cost tiers separate direct expansion simplicity from dual-loop safety premiums, with working fluid inventory and heat exchanger surface area driving capital differentiation.
- Dual-Loop:Secondary thermal oil or water-glycol circuits isolate flammable hydrocarbon working fluids from toxic or high-temperature industrial heat sources. Chemical facilities in Germany mandate these for cement kiln off-gas recovery, with EPCs absorbing higher heat exchanger costs against liability reduction.
- Direct Expansion:Organic working fluid vaporizes directly against geothermal brine or clean biomass combustion gases, eliminating intermediate loop pressure losses. Italian geothermal operators in Tuscany deploy these with isobutane and pentane blends, minimizing parasitic pumping power.
- Heat Transfer:Optimized shell-and-tube or plate heat exchanger configurations prioritize thermal pinch point management over working fluid thermodynamics.
- Regenerative:Internal heat recovery between expander exhaust and pump discharge boosts cycle efficiency for low-temperature heat sources below 150°C.
Dual-Loop commands the premium pricing tier, while Direct Expansion gains share fastest in geothermal baseload contracts.
End User:
Application maturity determines service contracting prevalence, with geothermal developers favoring availability guarantees and industrial operators preferring equipment purchase.
- Geothermal:Brine extraction from volcanic reservoirs in Japan's Kyushu region and Italy's Monte Amiata district supplies continuous thermal input for utility-scale plants. METI feed-in tariffs and EU Green Deal funding improve project returns against high upfront drilling costs.
- Waste Heat Recovery:Cement kiln exhaust and steel furnace off-gas in Germany's industrial heartland drive retrofit demand as EPA emissions standards and EU ETS carbon pricing compel efficiency investments.
- Biomass Power:Agricultural residue combustion and anaerobic digestion biogas supply seasonal thermal profiles requiring load-following expander control.
- Solar Thermal:Concentrating solar power troughs and linear Fresnel collectors provide diurnal heat input variations that challenge ORC part-load optimization.
Geothermal dominates cumulative installed capacity, with Waste Heat Recovery expanding most quickly under tightening industrial emissions mandates.
Application:
Customer procurement authority varies by scale, with corporate sustainability officers driving industrial site decisions and utility procurement departments governing power generation tenders.
- Industrial:Energy-intensive manufacturing clusters in Germany's Ruhr region and Japan's Chubu prefecture retrofit ORC systems onto existing process heat infrastructure. Scope 2 emissions accounting pressures concentrate procurement authority with sustainability departments rather than plant engineering.
- Power Generation:Utility-scale geothermal developers in Italy and Japan negotiate long-term power purchase agreements with grid operators, with project finance contingent on resource verification and drilling success.
- Commercial:District heating networks and hospital cogeneration plants deploy sub-MW systems for baseload thermal and electrical output.
- Residential:Micro-scale biomass boilers with integrated ORC remain nascent, limited by working fluid safety codes and maintenance access constraints.
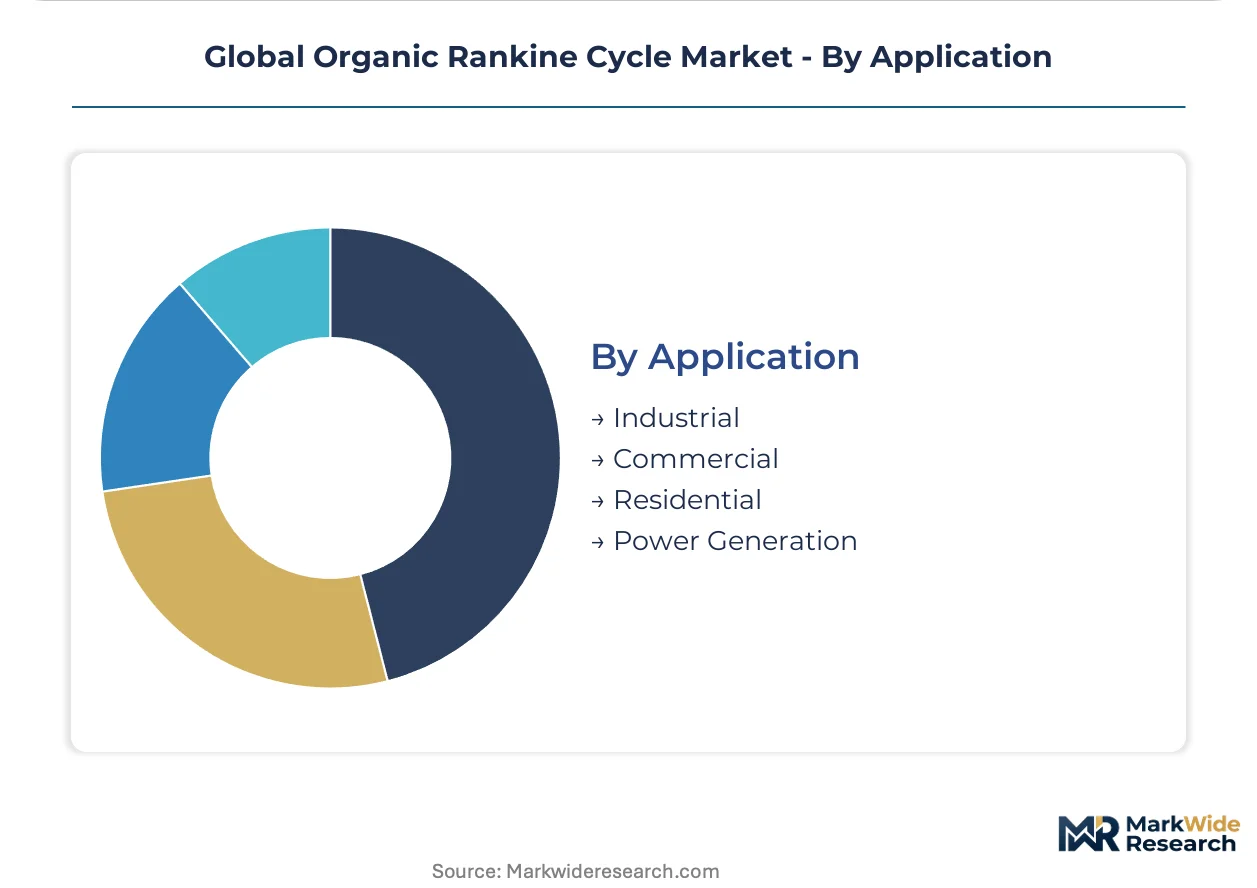
Industrial leads by active project pipeline, with Power Generation holding the steepest expansion trajectory in geothermal licensing rounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling project development toward jurisdictions where feed-in tariffs and carbon pricing narrow payback periods, while F-Gas compliance costs deter investment in markets with accelerated refrigerant phase-down schedules.
Germany
Cement and steel waste heat recovery dominate deployment as operators retrofit facilities to meet EU ETS compliance obligations. The EU F-Gas Regulation mandates working fluid transitions that elevate engineering costs for dual-loop installations. The Ruhr industrial cluster hosts multiple pilot programs integrating predictive control systems into existing kiln exhaust infrastructure.
Japan
Geothermal baseload development accelerates under METI feed-in tariff guarantees that improve project finance terms for brine extraction ventures. The country's national energy regulator maintains licensing frameworks that prioritize resource verification before construction approval. Kyushu's volcanic districts concentrate drilling activity where Tuscany-derived engineering expertise supports technology transfer partnerships.
Italy
Biomass cogeneration and geothermal power generation sustain equipment demand across Tuscany and Emilia-Romagna manufacturing corridors. The EU Green Deal channels decarbonization funding toward industrial park retrofits that pair ORC systems with district heating networks. Turboden S.p.A.'s Mantua headquarters anchors a regional supply chain for expander-generator assembly and heat exchanger fabrication.
United States
EPA emissions standards compel waste heat capture investments in cement and petrochemical facilities across Texas and Louisiana process industry corridors. FERC interconnection rules govern utility-scale geothermal developments in Nevada and Utah where brine temperatures favor direct expansion architectures. State-level renewable portfolio standards in California create secondary demand for landfill gas and anaerobic digestion applications.
Global Organic Rankine Cycle Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated energy conglomerates dominating utility-scale geothermal tenders while independent technology licensors capture industrial retrofit contracts. The vendor base concentrates among three strategic archetypes: heritage geothermal developers with drilling-to-generation capabilities, industrial equipment OEMs leveraging heat exchanger manufacturing scale, and pure-play ORC technology houses specializing in modular system architectures. Competitive positioning hardens through technology licensing partnerships that transfer working fluid expertise across regional markets, while vertical integration into expander manufacturing separates premium-tier suppliers from assembly-dependent competitors.
Within the heritage geothermal tier, Ormat Technologies exemplifies integrated project development spanning resource exploration through power purchase agreement execution. Turboden S.p.A. occupies a specialist position among European industrial equipment houses with concentrated biomass and waste heat recovery exposure. Exergy International represents the modular pure-play archetype, anchoring distributed generation segments through containerized system architectures that compress deployment timelines for smaller-scale thermal sources.
| Leading Market Players |
|---|
| Ormat Technologies |
| Turboden S.p.A. |
| Calnetix Technologies |
| Exergy International |
| Alfa Laval |
| Kaishan USA |
| ENOGIA |
| Triogen |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Specialty refrigerant price indices for HFO-1234yf and hydrocarbon blends cascade through ORC equipment supply chains, compressing margins on dual-loop installations while elevating premium tiers for certified low-GWP architectures. Buyers in Germany and Japan absorb fluid cost volatility through long-term offtake contracts that transfer inventory risk to EPC integrators.
Pricing Analysis
Distributor margins on modular ORC systems compress project-based pricing by 8-12 points against direct OEM procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified stationary units from CE-marked modular skids and uncertified mobile configurations. Pricing pressure stems from working fluid certification delays that extend project development cycles. Industrial waste heat recovery buyers in cement and steel sectors exhibit highest price sensitivity, while utility-scale geothermal developers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for HFO working fluids mandate qualification of European and Japanese chemical producers, reducing single-source dependency for project developers. Manufacturing concentrates in Italy, Germany, and Japan for expander-generator sets, heat exchanger fabrication, and control system integration. Raw material dependencies span copper alloys for shell-and-tube exchangers, rare-earth magnets for permanent-magnet generators, and specialty refrigerants for working fluid blends. Tariff exposure on Chinese-sourced electrical components elevates landed costs for North American EPCs. Distribution runs through technology licensors with captive service networks rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ORC equipment hinges on modular system standardization that collapses engineering hours per kilowatt installed, while premium-tier demand shifts toward integrated predictive maintenance platforms.
For Market Incumbents: To counter modular pure-play entrants in distributed generation segments, heritage geothermal developers should anchor backward integration into expander manufacturing and secure captive working fluid supply agreements with European chemical producers. Certification investment in ASME and PED pathways for novel low-GWP fluids creates switching costs against assembly-dependent competitors. For New Entrants and Emerging Players: Launch via performance-based service contracting models that displace traditional equipment purchase in industrial waste heat recovery. White-space targets concentrate on chemical plant exothermic stream integration and containerized biomass cogeneration in Italy's Emilia-Romagna corridor. Direct expansion architectures for geothermal brine applications offer the most penetrable technology entry point against established dual-loop specialists. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering talent scarcity concentrates among legacy geothermal firms with proprietary fluid property databases. Long-term viability favors integrated developers with drilling-to-generation capabilities and established power purchase agreement execution track records. The signal to watch is feed-in tariff revision schedules in Japan and licensing round announcements in Italy's Monte Amiata district.| Strategic Initiative | Industry Significance |
|---|---|
| Working Fluid Certification Investment | ASME and PED compliance for HFO alternatives accelerates project approval timelines under EU F-Gas Regulation phase-down schedules. |
| Modular System Standardization | Containerized 40-foot ISO footprints reduce civil works and compress commissioning schedules for Italian biomass developers. |
| Predictive Maintenance Platform Integration | Digital twin architectures automate load-following control against variable cement kiln off-gas temperatures in German Ruhr facilities. |
| Captive Working Fluid Supply Agreement | Long-term offtake contracts with European chemical producers hedge HFO price volatility for dual-loop installation EPCs. |
| Geothermal Resource Verification Partnership | Drilling-to-generation integration secures project finance contingent on brine temperature confirmation in Japan's Kyushu volcanic districts. |
Study Parameters
Coverage spans Germany, Italy, Japan, and the United States, with primary inputs from each market triangulated against secondary validation. Interviews with EPC contractors, plant engineering directors at cement and steel facilities, geothermal project developers, and technology licensors informed demand-side assumptions. Secondary sources include EPA emissions enforcement databases, EU ETS carbon pricing records, METI feed-in tariff filings, and equipment certification registries from ASME and PED authorities. Bottom-up project pipeline analysis and top-down market sizing were cross-referenced for convergence.
Rate-of-change decomposition separates volume growth from price/mix effects across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-use application, and regional regulatory framework. CAGRs derive from installed base expansion rates, replacement demand cycles, and penetration assumptions for waste heat recovery retrofits. Industry-specific inputs incorporate EU F-Gas Regulation phase-down schedules, METI tariff revision timelines, and cement sector emissions compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated refrigerant phase-down schedules or geothermal licensing delays. Forecasts reflect documented assumptions on working fluid substitution timelines, industrial emissions enforcement intensity, and feed-in tariff stability. Deviation in EU Green Deal funding allocation or Japanese resource verification protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Solar EPC Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Germany Renewable Energy Market