
 Hybrid Power System Market | 2026-2036
Hybrid Power System Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Power System Market Intelligence
The hybrid power system market is restructuring around a widening gap between premium integrated solutions and commodity component bundles. Plug Power leverages its fuel cell expertise to command positions in high-reliability military and telecom applications. First Solar anchors utility-scale hybrid deployments with thin-film solar dominance and captive project pipelines. Sungrow Power Supply competes aggressively on power electronics cost, shipping inverters and battery management systems that undercut integrated rivals on price.
A hybrid power system combines two or more generation sources—typically solar photovoltaic arrays, wind turbines, diesel generators, or fuel cells—with battery storage and unified control architecture to deliver continuous, dispatchable electricity. These systems synchronize variable renewable output with firm backup generation through DC-coupled or AC-coupled topologies, achieving target availability rates above 99% in off-grid configurations. Solar-battery hybrids now lead new installations, capturing the dominant share of capacity additions as module costs compress and lithium iron phosphate cells extend cycle life. Microgrid applications represent the fastest-expanding segment, driven by resilience mandates and islanding capabilities that command premium pricing from commercial and institutional buyers. Remote telecom remains a mature, volume-driven category where procurement runs through tower operators with standardized technical specifications and thin margins.
FERC Order 2222 in the United States enables hybrid resources to participate in wholesale markets as aggregated distributed energy resources, reshaping revenue stacking opportunities. The EU Green Deal and F-Gas Regulation push European deployments toward battery-dominant architectures that minimize diesel runtime and eliminate sulfur hexafluoride switchgear. India's CEA grid codes and PLI scheme for advanced chemistry cells accelerate domestic manufacturing of lithium-ion storage paired with solar hybrids. Stakeholders must track how jurisdictional market rules and local content requirements redistribute competitive advantage across technology suppliers and project developers.
Market Dynamics
Battery-dominant architectures are compressing diesel generator runtime to sub-ten-percent levels in new hybrid deployments, driven by lithium iron phosphate cost curves and dispatch optimization software that synchronizes multiple generation assets through unified control layers.
Growth Catalysts
- FERC Order 2222:Aggregated hybrid resources now access wholesale capacity markets in the United States, creating revenue stacking through energy, ancillary services, and demand response participation.
- Telecom tower electrification:Sub-Saharan Africa's off-grid tower operators are procuring solar-diesel-battery configurations to displace pure diesel generation and reduce fuel logistics costs.
- India's PLI scheme:Domestic advanced chemistry cell manufacturing incentives are localizing lithium-ion storage production for solar hybrid pairing under CEA grid code compliance.
Market Restraints
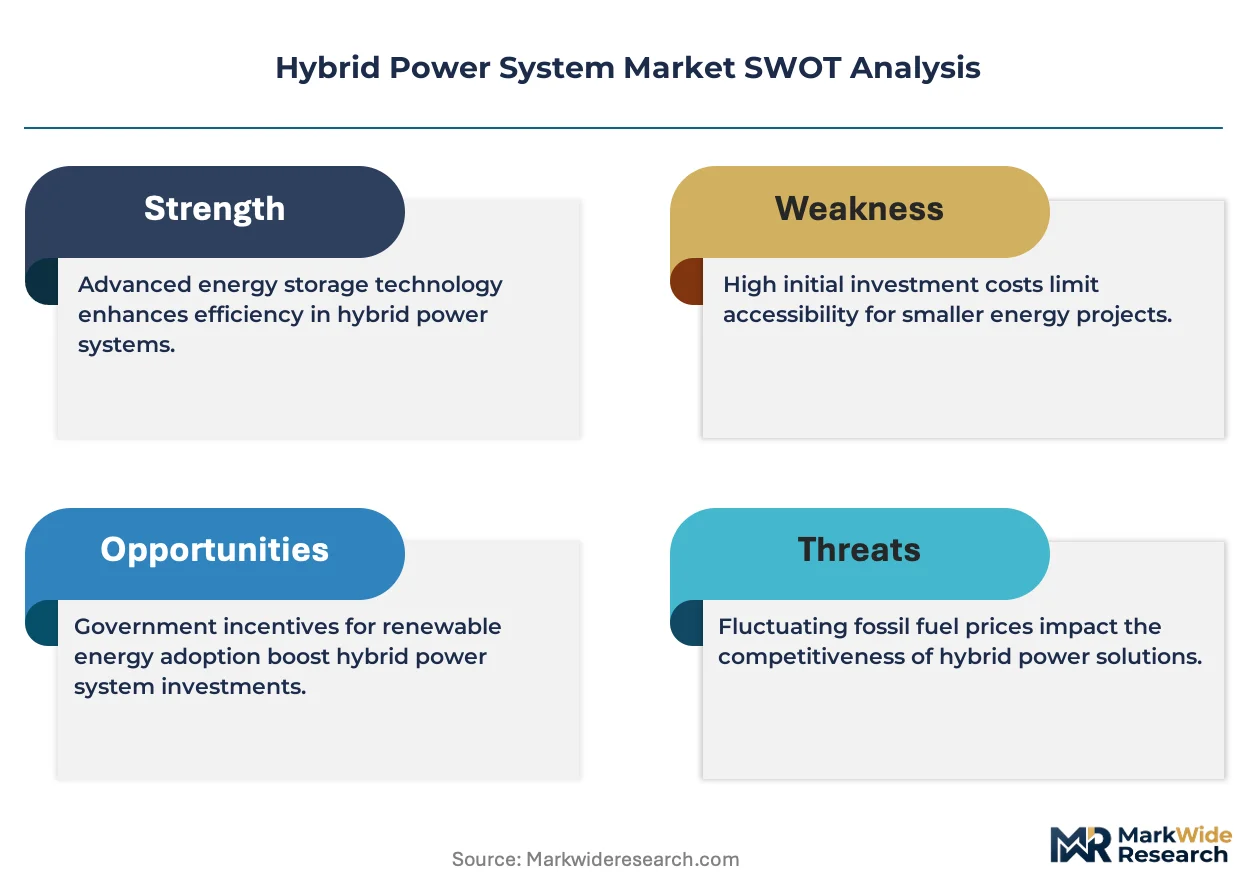
- Lithium carbonate price volatility:Battery storage economics remain exposed to raw material swings that compress project developer margins during procurement cycles.
- Power electronics supply concentration:Inverter and battery management system production clusters in East Asia create single-source vulnerability for non-integrated system assemblers.
- Diesel fuel subsidy dependence:Persisting fossil fuel price supports in emerging markets distort total cost of ownership calculations against renewable-battery alternatives.
Strategic Opportunities
- Commercial microgrid expansion:Islanding-capable hybrid systems command premium pricing from data centers and healthcare facilities seeking resilience against grid instability.
- EU Green Deal alignment:Battery-dominant architectures that eliminate sulfur hexafluoride switchgear qualify for accelerated permitting under F-Gas Regulation phase-down mandates.
- DC-coupled topology convergence:Single-inverter designs that integrate photovoltaic strings with battery storage are reducing balance-of-system costs and installation labor.
Industry Challenges
- Control software integration:Multi-vendor component sourcing creates protocol incompatibility between battery management systems, inverters, and generator controllers.
- Certification timeline compression:Grid code compliance testing for hybrid resources extends project development schedules in jurisdictions with evolving interconnection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Power System Market |
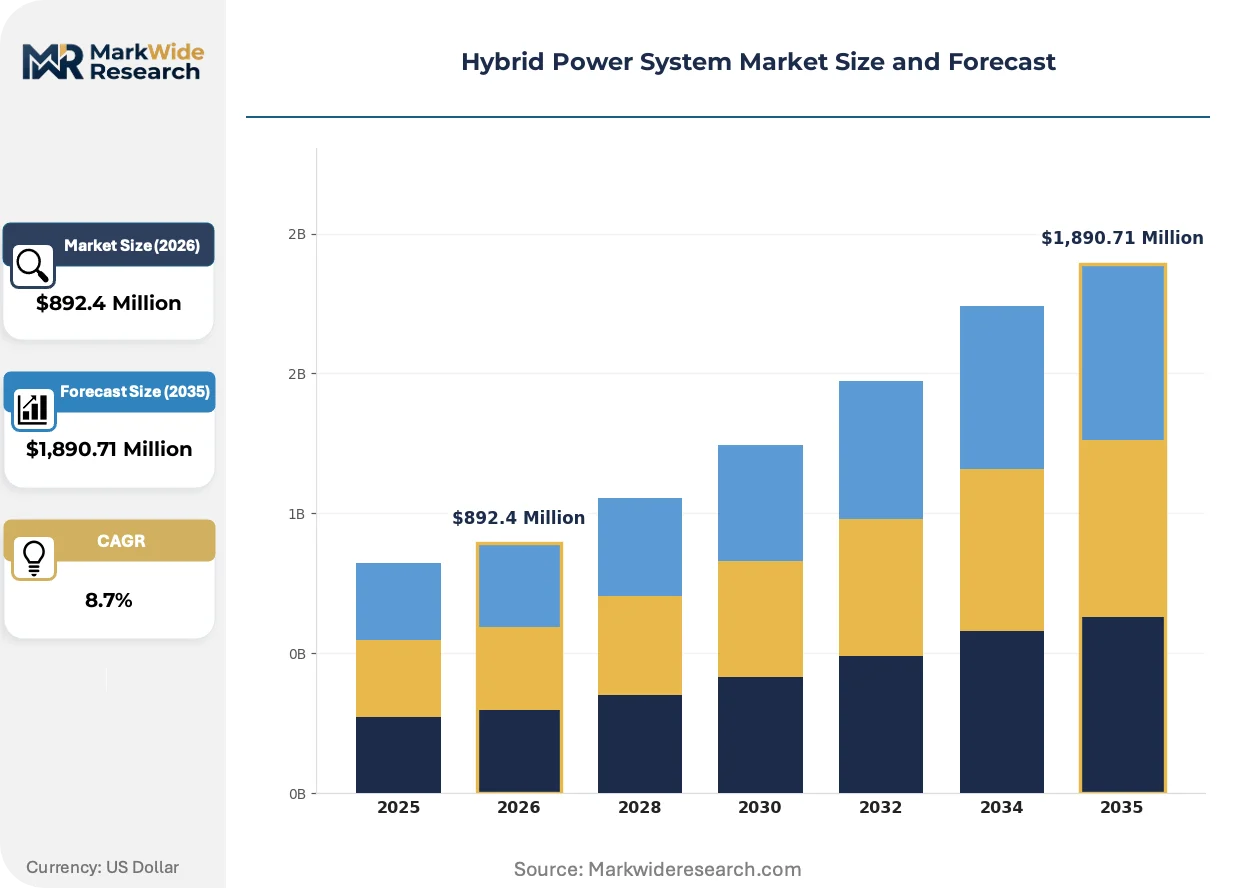
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source Type: Solar, Wind, Diesel Generator, Battery Storage, Fuel Cell Application: Remote Telecom, Microgrid, Military Bases, Agricultural Operations, Commercial Complexes Installation Type: Ground Mounted, Rooftop, Floating, Modular, Mobile Units End User: Energy Service Companies, Government Facilities, Nonprofit Organizations, Educational Institutions, Manufacturing Plants |
| Companies Covered | Plug Power, First Solar, NextEra Energy, Constellation, LS Power, Sungrow Power Supply, Brookfield Renewable Partners, NRG Energy, Bloom Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Power System Market Strategic Shifts & Innovations
Unified control architectures are displacing siloed component management as the defining technical frontier, compressing commissioning timelines and enabling predictive maintenance through machine learning layer integration.
AI-driven energy management software is unifying dispatch decisions across photovoltaic, battery, and thermal generation assets in real-time optimization loops. Remote mining operations in Australia and Chile are deploying these platforms to minimize fuel consumption while maintaining 99.9% availability targets. The technology is unifying previously separate vendor ecosystems into interoperable technology stacks that reduce operator training burdens.
The EU F-Gas Regulation is accelerating switchgear redesign toward vacuum interruption technologies that eliminate sulfur hexafluoride from hybrid substations. Equipment manufacturers must retest arc-quenching performance under new certification protocols. European utility-scale deployments are absorbing these compliance costs fastest, while emerging market projects lag in specification updates.
Power purchase agreement structures are fragmenting between equipment ownership and energy-as-a-service models. Commercial and industrial buyers in India and Southeast Asia increasingly prefer operational expenditure contracts that transfer technology risk to project developers. This shift concentrates capital requirements with specialized hybrid system integrators and squeezes component vendors toward pure hardware margins.
Hybrid Power System Market Segmentation
Hybrid power system procurement splits across four distinct axes that determine system architecture, financing structures, and vendor selection criteria. Upgrade cycles vary dramatically by segment—telecom infrastructure refreshes every 7-10 years while microgrid deployments follow 15-20 year asset lifecycles.
Power Source Type:
Replacement timelines diverge sharply across generation technologies, with battery storage requiring mid-cycle augmentation while solar arrays operate through full depreciation schedules.
- Solar:Photovoltaic arrays anchor new hybrid deployments through declining module costs and 25-year performance warranties. Demand clusters in India's rural electrification zones where CEA grid codes mandate domestic content ratios.
- Battery Storage:Lithium iron phosphate cells enable diesel displacement below 10% runtime through 6,000+ cycle lifespans. Procurement from India's PLI-subsidized cell manufacturers is accelerating under advanced chemistry cell localization mandates.
- Wind:Small-scale turbines supplement solar in high-resource corridors with complementary generation profiles.
- Diesel Generator:Backup thermal units shrink to contingency-only roles as battery economics improve.
- Fuel Cell:Hydrogen-fed systems serve military and telecom applications requiring silent operation and extended runtime.
Volume placements concentrate in Solar-Battery configurations; the faster expansion belongs to Fuel Cell hybrids for mission-critical installations.
Application:
Cost tier stratification separates price-sensitive volume buyers from premium resilience seekers willing to pay 40-60% premiums for islanding capabilities.
- Remote Telecom:Tower operators in sub-Saharan Africa procure standardized solar-diesel-battery configurations to eliminate fuel logistics to isolated sites. MTN and Airtel procurement frameworks drive component commoditization.
- Microgrid:Campus-scale systems integrate multiple generation assets through unified control layers for 99.9% availability targets. Healthcare facilities and data centers in India and Southeast Asia absorb premium pricing for blackout immunity.
- Military Bases:Fuel cell-battery hybrids meet signature management and fuel security requirements.
- Agricultural Operations:Irrigation-driven loads favor solar-diesel configurations with seasonal dispatch flexibility.
- Commercial Complexes:Retail and office installations prioritize rooftop solar-battery pairing for demand charge management.
Telecom dominates unit shipments; Microgrid commands the steepest expansion trajectory as resilience mandates proliferate.
Installation Type:
Customer type segmentation tracks capital availability—asset-heavy utilities prefer permanent ground mounts while energy service companies favor modular deployable units.
- Ground Mounted:Fixed-tilt and tracking arrays on dedicated land parcels serve utility-scale and agricultural hybrid systems. Permitting complexity varies by local zoning authorities.
- Rooftop:Commercial building-integrated systems leverage existing structural assets with minimal land acquisition.
- Floating:Reservoir-mounted solar pairs with battery storage for irrigation microgrids and water treatment facilities.
- Modular:Containerized, factory-integrated systems compress commissioning timelines for remote deployments.
- Mobile Units:Trailer-mounted configurations serve disaster response and temporary military installations.
Ground Mounted absorbs the majority of megawatt-scale capacity; Modular systems are gaining share fastest among energy service companies.
End User:
Supply concentration in power electronics manufacturing creates procurement bottlenecks for non-integrated system assemblers serving fragmented end-user categories.
- Energy Service Companies:ESCOs in India and Southeast Asia are shifting from equipment sales to energy-as-a-service contracts that transfer technology risk from commercial and industrial buyers.
- Government Facilities:Defense and civilian agencies mandate FERC Order 2222 compliance for wholesale market participation in the United States.
- Nonprofit Organizations:Development finance-backed rural electrification projects in sub-Saharan Africa prioritize lowest lifecycle cost over upfront capital minimization.
- Educational Institutions:University microgrids combine research objectives with operational resilience for laboratory facilities.
- Manufacturing Plants:Industrial buyers seek islanding capability to protect continuous process loads from grid instability.
Energy Service Companies command the largest procurement volumes; Government Facilities are expanding most quickly through resilience appropriations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore anchors procurement volume for hybrid power systems in India, where rural electrification programs and commercial microgrid deployments concentrate manufacturing and project development activity across the subcontinent.
United States
FERC Order 2222 enables aggregated hybrid resources to access wholesale capacity markets, creating revenue stacking through energy and ancillary services participation. The Inflation Reduction Act extends investment tax credits to standalone battery storage paired with solar generation. Texas and California lead deployment volumes, with ERCOT grid instability driving data center resilience investments in Dallas-Fort Worth and Austin corridors.
India
The CEA grid code mandates domestic content ratios for solar-battery hybrid installations under rural electrification programs. Production-linked incentives for advanced chemistry cells localize lithium-ion manufacturing in Gujarat and Tamil Nadu industrial zones. Maharashtra's commercial microgrid deployments in Pune and Mumbai suburbs command premium pricing for islanding capabilities from manufacturing plants.
Germany
The EU F-Gas Regulation accelerates switchgear redesign toward vacuum interruption technologies that eliminate sulfur hexafluoride from hybrid substations. EEG feed-in tariff revisions favor battery-dominant architectures that maximize self-consumption over grid export. Industrial clusters in Bavaria and North Rhine-Westphalia integrate hybrid systems for manufacturing resilience against grid volatility.
Australia
Remote mining operations in Western Australia and Queensland deploy AI-driven energy management platforms to minimize fuel consumption while maintaining availability targets. The Australian Energy Market Commission reforms enable hybrid resources to participate in frequency control ancillary services markets. Perth-based project developers concentrate on containerized modular systems for fly-in-fly-out mine sites.
South Africa
Eskom grid unreliability drives commercial and industrial procurement of islanding-capable hybrid systems in Johannesburg and Cape Metro manufacturing zones. The country's renewable energy independent power producer procurement program includes hybrid storage requirements for dispatchable capacity. Sub-Saharan telecom tower operators source standardized solar-diesel-battery configurations through South African distribution hubs.
Hybrid Power System Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the hybrid power system market, with integrated solution providers facing pressure from specialized component vendors. The vendor base splits between premium-positioned technology integrators and cost-optimized power electronics suppliers. Three archetypes dominate: fuel cell specialists commanding military and telecom premiums, thin-film solar anchors with captive project pipelines, and aggressive power electronics cost competitors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure battery cell supply and inverter manufacturing scale.
Within the fuel cell specialist tier, Plug Power occupies a position exemplifying high-reliability applications for silent operation requirements. First Solar anchors utility-scale deployment archetypes through thin-film solar dominance and integrated project development capabilities. Sungrow Power Supply sits within the cost-competitive power electronics tier, representing aggressive pricing on inverters and battery management systems that undercut integrated rivals.
| Leading Market Players |
|---|
| Plug Power |
| First Solar |
| NextEra Energy |
| Constellation |
| LS Power |
| Sungrow Power Supply |
| Brookfield Renewable Partners |
| NRG Energy |
| Bloom Energy |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up ESCOs in India and Southeast Asia concentrate procurement volumes through energy-as-a-service contracts, compressing hardware margins while shifting pricing power toward integrated system architects who control project finance and long-term performance risk.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for islanding-capable microgrids serving data centers and healthcare facilities in India and South Africa. Project-based equipment sales dominate telecom tower deployments where MTN and Airtel procurement frameworks commoditize solar-diesel-battery bundles. Price differentiation rests on certification grade—UL-listed power electronics command 15-25% premiums over CE-marked alternatives—and after-sales service bundling. Cost compression in lithium iron phosphate cells is intensifying because India's PLI scheme accelerates domestic manufacturing scale. Telecom tower operators exhibit highest price sensitivity; military and mission-critical buyers absorb premium tiers without volume negotiation.
Supply Chain Analysis
Direct-to-ESCO channels handle commercial microgrid demand in India, while distributor networks serve fragmented agricultural and small commercial buyers across sub-Saharan Africa. Manufacturing concentrates in China for lithium-ion cells and power electronics, India for PLI-subsidized battery assembly, and Germany for vacuum-interruption switchgear redesign. The supply chain draws from lithium carbonate processing in Chile and Australia, polysilicon refining in China, and rare earth magnet production for wind components. Single-source vulnerability in inverter and battery management system production clusters creates procurement bottlenecks. Distribution runs through South African hubs for sub-Saharan telecom infrastructure and Singapore trading houses for Southeast Asian project finance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from lithium carbonate price volatility and power electronics supply concentration will force smaller system assemblers into distressed sales or strategic exits over the projection horizon.
For Market Incumbents: Cement control over battery cell supply through backward integration into India's PLI-subsidized manufacturing zones or captive offtake agreements with Gujarat and Tamil Nadu producers. Escalate certification investment for F-Gas Regulation compliance in EU markets before vacuum-interruption switchgear mandates harden into procurement specifications. Threat substitution from Sungrow's aggressive inverter pricing demands channel control reinforcement through exclusive ESCO partnerships.
For New Entrants and Emerging Players: Capture modular containerized system demand from Australian mining operations and South African commercial-industrial buyers seeking rapid deployment without integrated EPC capabilities. Agricultural irrigation microgrids in Maharashtra and Queensland present the most penetrable white space, with seasonal dispatch requirements underserved by standardized telecom configurations. Lead with AI-driven energy management software licensing to bypass capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated specialists with captive lithium-ion supply in India and established FERC Order 2222 compliance pathways in Texas and California. Long-term viability centers on project development pipelines rather than component manufacturing scale. Watch for inflection in ERCOT grid instability frequency as the signal for accelerated data center resilience investment in Dallas-Fort Worth and Austin corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Manufacturing | PLI scheme subsidies in Gujarat and Tamil Nadu localize lithium iron phosphate supply for solar hybrid pairing. |
| F-Gas Regulation Compliance Certification | Vacuum interruption switchgear redesign qualifies European deployments for accelerated permitting under EU mandates. |
| AI-Driven Energy Management Platform Launch | Machine learning dispatch optimization unifies multi-vendor assets for Australian mining availability targets. |
| Energy-as-a-Service Contract Expansion | Operational expenditure models transfer technology risk from Indian commercial buyers to specialized integrators. |
| Modular Containerized System Scale-Up | Factory-integrated designs compress commissioning timelines for fly-in-fly-out mine sites in Western Australia. |
Research Approach
Multi-period observation of lithium carbonate price movements, PLI scheme disbursement rates, and FERC Order 2222 implementation timelines anchored the trend analysis, supplemented by interviews with IPP project developers, EPC contractors, utility planning officers, and grid operators across India, the United States, and Australia. Secondary validation drew from EIA generation data, IEA renewable investment reports, FERC interconnection filings, and CEA grid code compliance databases. Bottom-up project pipeline aggregation and top-down regulatory impact modeling were triangulated against vendor shipment disclosures.
Segment-weighting applied differential growth rates across power source configurations, with solar-battery hybrids receiving heavier modeling weight than fuel cell or wind-hybrid alternatives. Application segmentation distinguished telecom volume tiers from microgrid premium pricing. Generation capacity tiers, regulatory framework clusters, and regional grid stability indices shaped the analytical framework across the projection horizon. CAGRs were derived from installed capacity buildout curves and component cost trajectories, with lithium iron phosphate cycle life extension and inverter efficiency improvements as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility, East Asian power electronics supply disruptions, and evolving grid code compliance timelines in India and the United States. Forecasts reflect documented assumptions regarding PLI scheme continuation, F-Gas Regulation enforcement intensity, and ERCOT market reform implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Argentina Renewable Energy Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Solar Boat Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Marine Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Republic of Congo Renewable Energy Market