
 Oblong Jar Market | 2026-2036
Oblong Jar Market Size, Share, and Industry Trends Forecast 2026-2036
Oblong Jar Market Outlook
Post-consumer recycled polyethylene terephthalate is shifting the cost structure of oblong jar production as converters reduce virgin resin dependence. Berry Global Inc leverages vertical integration across recycled resin sourcing to control input costs. Silgan Holdings Inc anchors North American supply through dedicated blow-molding capacity for food-grade containers. Graham Packaging Company differentiates via lightweighting technology that trims material per unit without sacrificing stack strength.
An oblong jar is a rectangular or elliptical cross-section container, typically manufactured through injection blow molding, extrusion blow molding, or glass pressing, with volumes ranging from under 100 milliliters to several liters. These vessels serve primary functions in product protection, shelf differentiation, and efficient cubic utilization during transport and retail display. Plastic jars lead volume due to cost scalability across the small-to-medium size range, while glass jars command premium placement in decorative and candle-making segments where aesthetic clarity and heat resistance justify higher unit economics. Closure type selection tracks application requirements, with screw-top configurations dominating food storage for reseal reliability and cork closures concentrating in decorative and artisan candle channels where tactile presentation drives purchase intent.
The FDA maintains food-contact notification standards that govern resin additives and migration limits for oblong jars holding edible contents, while the EPA regulates volatile organic compound emissions from solvent-based decorating processes used in container finishing. The EU Green Deal and REACH compliance requirements are restricting certain phthalate plasticizers and mandating recycled content thresholds, compelling converters to reformulate material specifications. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or secure long-term offtake agreements with specialized reprocessors.
Market Dynamics
Post-consumer recycled resin mandates are compressing virgin plastic demand across oblong jar converters, forcing material specification rewrites and supplier base consolidation as FDA and EU Green Deal compliance deadlines approach.
Growth Catalysts
- Food-contact safety standards:FDA migration limit updates for polyethylene terephthalate containers are accelerating resin certification investments by converters serving prepared meal and sauce segments.
- Extended producer responsibility frameworks:EU packaging waste directives mandate recycled content thresholds that pull post-consumer material into oblong jar supply chains ahead of statutory deadlines.
- E-commerce fulfillment optimization:Rectangular jar geometries maximize pallet cube utilization for direct-to-consumer shipping, driving adoption in subscription food and personal care channels.
Market Restraints
- Recycled resin price volatility:Post-consumer polyethylene terephthalate bale supply fluctuates with beverage container deposit return rates, squeezing converter margins during collection shortfalls.
- Food-grade reprocessing concentration:FDA-certified recycled resin capacity clusters in the United States and Germany, creating geographic supply risk for converters elsewhere.
- Glass substitution in premium segments:Artisan candle and cosmetic brands retain glass oblong jars for heat resistance and optical clarity, capping plastic penetration in high-margin decorative applications.
Strategic Opportunities
- Pharmaceutical compliance expansion:USP Class VI and EP 3.1.6 certification pathways for plastic oblong jars remain underdeveloped relative to glass, creating white space for resin suppliers investing in extractables testing.
- Dual-carbon alignment in China:MIIT circular economy targets and provincial plastic restriction policies incentivize domestic converters to localize post-consumer resin processing.
- Smart packaging integration:Near-field communication tags and temperature-sensitive inks are converging with oblong jar blow-molding lines, enabling traceability for cold-chain food and pharmaceutical applications.
Industry Challenges
- Migration testing backlog:FDA food-contact notification review timelines extend 12-18 months for novel recycled resin formulations, delaying product launches.
- Legacy decorating equipment incompatibility:Solvent-based label adhesives and UV-cured inks require capital-intensive retrofit to meet EPA volatile organic compound emission limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oblong Jar Market |
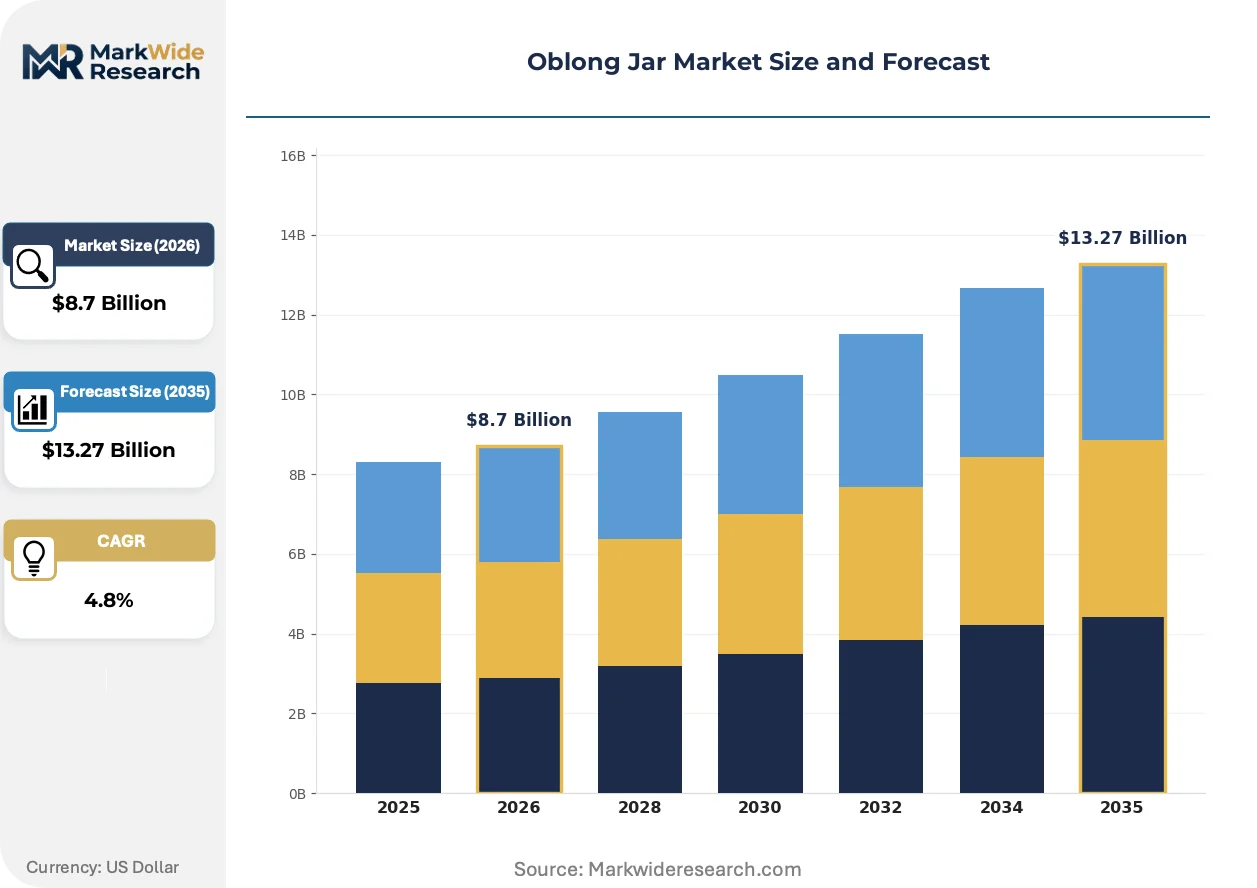
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Jars, Plastic Jars, Metal Jars, Ceramic Jars Size: Small, Medium, Large, Extra Large Closure Type: Screw Top, Snap Lid, Cork, Push On Application: Food Storage, Decorative Use, Packaging, Candle Making |
| Companies Covered | Dahl-Tech, Inc, US Pack Group, Dash Packaging, Canyon Plastics Inc, MJS Packaging, Berry Global Inc, Graham Packaging Company, Plastipak Holdings, Inc, Silgan Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oblong Jar Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine oblong jar specifications, with sustainability credentials and functional performance now jointly determining procurement decisions across end-use verticals.
Barrier-enhanced polyethylene terephthalate is integrating oxygen-scavenging additives and multilayer co-injection structures to extend shelf life for oxygen-sensitive foods. Premium sauce and condiment brands in the United States and Germany are adopting these specifications fastest. The technology is integrating recycled content streams without compromising migration compliance, compressing the cost premium between virgin and circular material grades.
REACH restriction proposals on intentionally added microplastics are tightening specifications for polymer-based decorative coatings and glitter additives used in cosmetic oblong jars. ECHA consultation timelines suggest enforcement by mid-decade, compelling converters to reformulate surface finishes. Decorative and personal care segments are responding by accelerating matte and soft-touch coating certifications that eliminate microplastic constituents.
Direct-to-retail procurement consolidation is compressing supplier negotiation cycles as major food retailers centralize private-label packaging specifications. Brand owners are displacing fragmented regional converter relationships with national framework agreements that bundle volume commitments against sustainability audit requirements. This pattern is most visible in Germany and the United Kingdom, where discounter and supermarket consolidation has concentrated buying power among fewer procurement teams.
Oblong Jar Market Segmentation
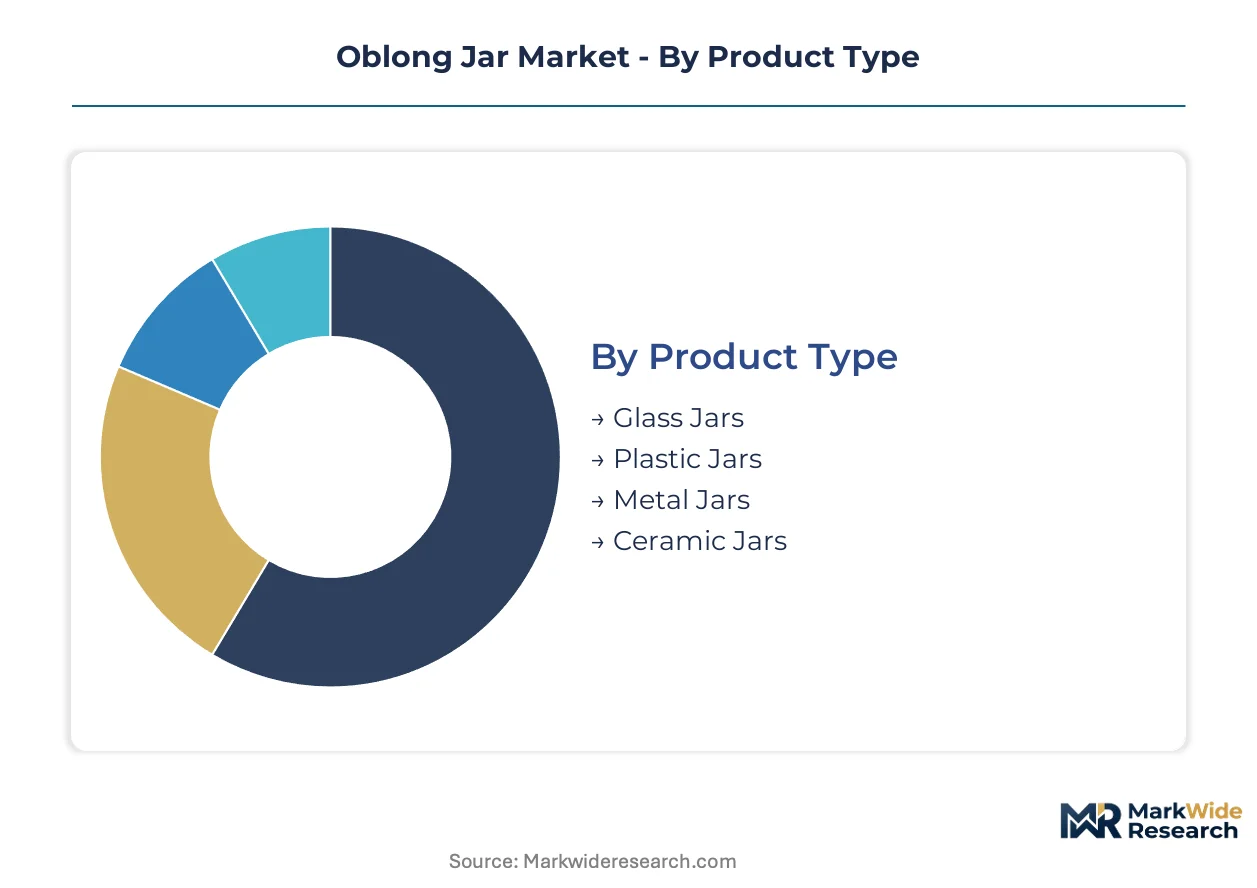
Oblong jar procurement decisions split across material performance requirements, dimensional constraints, and regulatory compliance burdens. Each segmentation dimension carries distinct margin profiles and supplier qualification thresholds that reshape converter competitive positioning.
Product Type:
Replacement cycles vary sharply by material durability and end-use stress conditions, with food-contact applications driving faster upgrade schedules than decorative deployments.
- Plastic Jars:Injection and extrusion blow-molded polyethylene terephthalate or polypropylene structures dominate volume through cost scalability and lightweighting compatibility. Demand concentrates in United States prepared meal and sauce segments where FDA migration compliance and e-commerce cube efficiency jointly determine specification. Recycled content mandates are compressing virgin resin tolerance windows and forcing resin certification investments.
- Glass Jars:Pressed or blown soda-lime silica containers command premium placement where thermal shock resistance and optical clarity justify unit economics. Heat-resistant requirements in artisan candle and cosmetic channels in Germany sustain demand despite higher freight costs and breakage rates.
- Metal Jars:Tinplate or aluminum constructions serve industrial chemical and specialty food niches requiring absolute light and oxygen barrier performance.
- Ceramic Jars:Glazed stoneware or porcelain vessels occupy decorative and gift segments where tactile differentiation and artisan positioning override cost sensitivity.
Volume placements concentrate in Plastic Jars; the faster expansion belongs to Glass Jars as premium cosmetic and candle brands retreat from plastic sustainability scrutiny.
Size:
Dimensional specifications track channel economics, with direct-to-consumer fulfillment favoring compact formats and club retail anchoring bulk configurations.
- Small:Sub-100 milliliter capacities serve sample, travel, and single-serve condiment applications where portability and shelf differentiation outweigh per-unit cost.
- Medium:100-500 milliliter range captures mainstream food storage and personal care volumes in Germany and United States retail. Pallet cube optimization and automated filling line compatibility concentrate procurement specifications.
- Large:500 milliliter to 1 liter formats serve family-size food and institutional channels where unit economics favor fewer container purchases per volume consumed.
- Extra Large:Above 1 liter capacities address foodservice, industrial, and bulk retail segments with specialized handling equipment requirements and reduced per-milliliter packaging cost.
Procurement gravity sits with Medium formats; Large formats are climbing the fastest as club retail and foodservice channels expand oblong jar adoption.
Closure Type:
Sealing mechanism selection balances reseal reliability, production line speed, and sensory presentation requirements across end-use contexts.
- Screw Top:Threaded plastic or metal caps with gasket seals dominate food storage where repeated opening cycles demand consistent closure torque and contamination prevention. United States sauce and condiment brands specify tamper-evident variants.
- Snap Lid:Press-fit polypropylene or polyethylene closures serve ready-to-eat meal and dairy applications where consumer convenience and audible seal confirmation drive adoption.
- Cork:Natural or synthetic stopper closures concentrate in decorative, candle, and premium cosmetic segments where tactile authenticity and acoustic opening experience justify higher unit cost and manual assembly.
- Push On:Friction-fit lids address temporary storage and non-food applications where reseal frequency remains low and production throughput priorities dominate.
Screw Top configurations hold the volume base; Cork closures are gaining share fastest as artisan candle and cosmetic brands emphasize unboxing experience differentiation.
Application:
End-use verticals impose divergent performance specifications, with food-contact compliance burdens separating commodity and premium supply tiers.
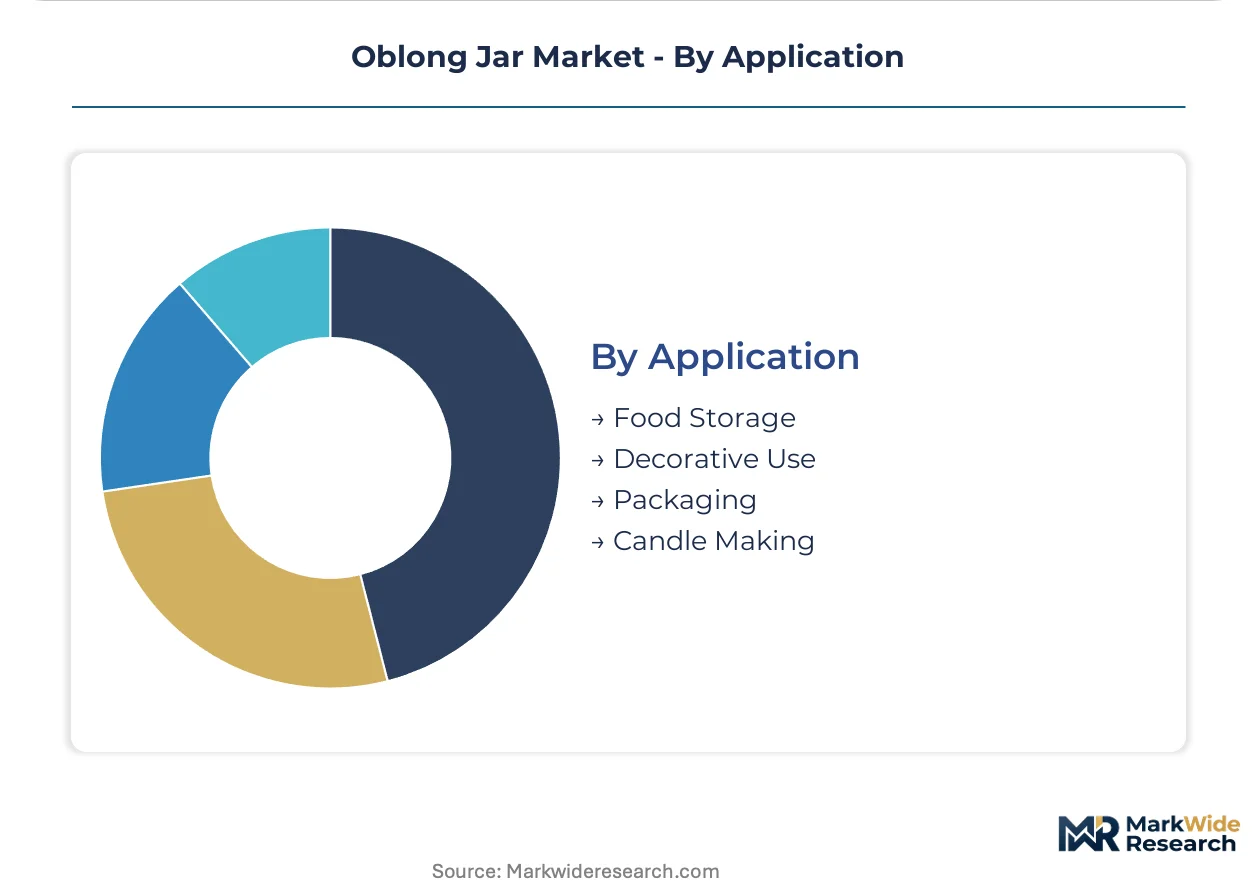
- Food Storage:Oxygen barrier, migration compliance, and reseal integrity requirements dominate specification. United States and Germany retail channels drive demand for barrier-enhanced polyethylene terephthalate with scavenging additives.
- Decorative Use:Aesthetic surface finish, dimensional consistency, and compatibility with coatings and labels determine procurement. REACH microplastic restrictions are eliminating glitter and certain polymer coatings.
- Packaging:Industrial and commercial containment applications prioritize cubic efficiency, stack strength, and chemical resistance over consumer-facing presentation elements.
- Candle Making:Thermal shock resistance and fragrance compatibility specifications favor glass and heat-tolerant ceramic constructions in artisan and premium segments.
Food Storage commands absolute volume; Candle Making is expanding most quickly as home fragrance and wellness categories sustain premium jar demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retail and foodservice channels concentrate absolute demand for oblong jar procurement, with Germany and China following as secondary volume centers where regulatory mandates and manufacturing scale respectively reshape supply patterns.
United States
Prepared meal subscription services and direct-to-consumer sauce brands drive specification for barrier-enhanced polyethylene terephthalate jars with scavenging additives. FDA migration limit updates for recycled resin containers accelerate converter certification investments ahead of compliance deadlines. Chicago and New Jersey industrial corridors host concentrated blow-molding capacity serving national retail distribution networks.
Germany
Discounter consolidation and private-label centralization compress supplier negotiation cycles for food-grade oblong jars across medium-format specifications. EU Green Deal recycled content thresholds and ECHA REACH microplastic restrictions compel material reformulation and coating substitutions. North Rhine-Westphalia packaging clusters specialize in food-contact compliant reprocessing infrastructure.
China
Provincial plastic restriction policies and MIIT circular economy targets incentivize domestic converters to localize post-consumer resin processing for export and domestic food packaging. Dual-carbon alignment pressures accelerate substitution of virgin resin dependence in Yangtze River Delta manufacturing bases. Shanghai and Jiangsu province converters scale barrier-enhanced multilayer co-injection capacity for oxygen-sensitive condiment exports.
Japan
Premium cosmetic and personal care brands sustain glass oblong jar demand where thermal shock resistance and optical clarity justify unit economics against plastic alternatives. METI resource circulation policies and JIS standards for recycled plastics tighten material traceability requirements. Kansai region Osaka-based converters specialize in small-format decorative jar finishing for luxury fragrance and skincare channels.
India
Organized retail expansion and quick-commerce fulfillment networks drive adoption of rectangular jar geometries optimizing pallet cube utilization for last-mile delivery. FSSAI food-contact safety standards and BIS packaging material specifications create compliance thresholds for imported resin formulations. Maharashtra and Gujarat industrial belts concentrate injection blow-molding capacity serving domestic FMCG and emerging export markets.
Oblong Jar Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with food-contact certification capabilities concentrating procurement power among fewer qualified suppliers. The vendor base organizes around three archetypes: resin-integrated conglomerates controlling upstream recycled material flows, dedicated blow-molding specialists with FDA-certified cleanroom capacity, and regional converters serving decorative and non-food niches. Dominant competitive moves include backward integration into post-consumer resin sourcing and lightweighting technology licensing to defend margin position against virgin resin price volatility.
Among North American resin-integrated players, Berry Global Inc and Silgan Holdings Inc exemplify archetypes of captive supply chain control and dedicated food-grade manufacturing infrastructure respectively. Graham Packaging Company occupies a position within the technology-differentiated tier where lightweighting patents create specification stickiness with national retail accounts. These three entities anchor competitive intensity across the United States and German procurement channels where certification burdens and volume scale jointly determine supplier selection.
| Leading Market Players |
|---|
| Dahl-Tech, Inc |
| US Pack Group |
| Dash Packaging |
| Canyon Plastics Inc |
| MJS Packaging |
| Berry Global Inc |
| Graham Packaging Company |
| Plastipak Holdings, Inc |
| Silgan Holdings Inc |
| Others |
Value Chain & Pricing Dynamics
Post-consumer recycled polyethylene terephthalate bale costs cascade through converter pricing tiers, with FDA-certified resin commanding premium placement against uncertified grades as buyers sort compliance obligations from commodity substitution.
Pricing Analysis
Volume concentrates in medium-format plastic jars where per-unit margins compress under recycled content mandates, while glass jars in artisan candle segments sustain premium-mid-economy pricing differentiation through thermal performance certification. Price differentiation hinges on FDA food-contact notification status and EU Green Deal recycled content thresholds, with uncertified converters facing price erosion from margin-squeezed buyers. Cost compression in virgin resin tiers is intensifying because post-consumer bale supply fluctuates with beverage deposit return volatility. Quick-commerce retailers exhibit highest price sensitivity; premium cosmetic brands show least.
Supply Chain Analysis
Reverse-logistics flows for post-consumer polyethylene terephthalate beverage containers anchor resin supply to deposit return system performance in the United States and Germany. Manufacturing concentrates in the United States, Germany, and China, with FDA-certified reprocessing capacity clustering in Chicago and North Rhine-Westphalia industrial corridors. Raw material flows draw from post-consumer bales, virgin resin pellets, and oxygen-scavenging additive formulations. Single-source vulnerability sits with food-grade recycled resin capacity concentration. Distribution runs through national retail framework agreements and direct-to-consumer fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oblong jar market is becoming a vertical-integration race as converters pursue backward control over post-consumer resin sourcing to defend margin position against virgin price volatility.
For Market Incumbents: Cement FDA certification moats by accelerating migration testing investments ahead of notification review backlogs. Lock long-term offtake agreements with specialized reprocessors before EU Green Deal deadlines concentrate supply further. Threat substitution from glass in premium candle segments demands barrier-enhanced polyethylene terephthalate performance parity claims. For New Entrants and Emerging Players: Regional converters in India and China represent the most penetrable channel partner type for quick-commerce fulfillment networks seeking pallet-cube-optimized geometries. Target pharmaceutical compliance white space where USP Class VI certification remains underdeveloped relative to glass. Lead with lightweighting technology licensing to differentiate against resin-integrated incumbents. For Investors and Strategic Acquirers: FDA food-contact notification approval for novel recycled resin formulations is the leading indicator that certification-capable converters will consolidate supply relationships. Long-term viability favors entities with captive post-consumer bale sourcing and multilayer co-injection capacity. Watch ECHA REACH microplastic enforcement timelines as signal for coating reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Resin Sourcing | Captive bale supply from deposit return systems insulates Berry Global and Silgan Holdings from price volatility. |
| FDA Food-Contact Notification Investment | Migration testing capacity backlog creates 12-18 month qualification barriers for uncertified competitors. |
| Barrier-Enhanced Multilayer Co-Injection Scale-Up | Oxygen-scavenging additive integration extends shelf life for prepared meal subscription channels in the United States. |
| Lightweighting Technology Licensing | Graham Packaging patents on material reduction without stack strength compromise create specification stickiness with national retail accounts. |
| Smart Packaging Integration Partnership | Near-field communication tag convergence with blow-molding lines enables cold-chain traceability for pharmaceutical applications. |
Study Parameters
Multi-period observation of post-consumer resin bale pricing, FDA notification approval timelines, and EU packaging waste directive implementation anchored the trend analysis, supplemented by interviews with blow-molding plant managers, retail category buyers, resin procurement leads, and regulatory affairs directors at converters. Secondary validation drew from FDA food-contact notification databases, EPA volatile organic compound emission filings, ECHA REACH restriction proposals, and EU Green Deal policy documents. Bottom-up capacity assessments across United States, German, and Chinese manufacturing clusters triangulated against top-down demand modeling from retail channel procurement data.
Input-output matrix framing structured demand projections across material type, size format, closure mechanism, and end-use application dimensions throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by recycled content mandate compliance costs and lightweighting technology adoption curves. Industry-specific forecast inputs included post-consumer polyethylene terephthalate bale supply elasticity and pharmaceutical certification pathway development rates.
Caveats apply where FDA migration testing backlog extensions, EU Green Deal recycled content threshold accelerations, or provincial plastic restriction policy shifts in China could materially shift the outlook. Practitioners should monitor deposit return system expansion rates and ECHA microplastic enforcement timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
EMEA Container Technology Market
Containers
PET Hinged Containers Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Trigger Sprayer Market
Containers
Container Fixed Fittings Market
Containers
Lab Storage Container Market
Containers
Trays Market
Containers
Takeout Containers Market
Containers
Single Wall Jars Market
Containers
Lever Lid Tinplate Containers Market
Containers
Two Compartment Bottles Market
Containers
ISO Container Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
HDPE Bottles Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Modular Container Market