
 Oblong Tub Lids Market | 2026-2036
Oblong Tub Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Oblong Tub Lids Market Analytics
Food service buyer consolidation is recalibrating procurement leverage across the oblong tub lid supply base. Greiner Packaging leverages Austrian manufacturing scale to anchor European dairy accounts. Berry Global competes through North American vertical integration in resin compounding and thermoforming. Amcor sustains global reach via multi-material platform breadth across food and personal care channels.
Oblong tub lids are rectangular or oval closures engineered to seal multi-serve containers, typically manufactured through injection molding or thermoforming with specified snap-fit tolerances and hermetic sealing performance for moisture-sensitive contents. Plastic dominates material type due to cost-efficient conversion and compatibility with tamper-evident banding, though regulatory pressure on polypropylene recyclability is elevating post-consumer resin formulations. Food packaging leads application share as ready-meal and deli segment volumes expand, while pharmaceutical-grade silicone closures command premium positioning in laboratory end use where autoclave resistance and inert surface properties justify higher unit economics.
FDA food-contact substance notifications govern polymer selection and migration limits for dairy and prepared food applications in the United States. EFSA and EU Packaging and Packaging Waste Regulation shape recyclability mandates and extended producer responsibility frameworks across European supply chains. Stakeholders must monitor evolving state-level recycled content mandates and bio-based substrate certifications to secure formulation approvals before specification lock-in by consolidated food service buyers.
Market Dynamics
Consolidated food service procurement is compressing supplier margins while mandating tamper-evident closure specifications across dairy and prepared meal segments. Buyers now demand hermetic sealing performance and post-consumer resin content as baseline qualification criteria.
Growth Catalysts
- Tamper-evident banding mandates:Institutional kitchens and cold-chain dairy operators in Germany now require snap-fit closures with visual breach indicators. This specification pull is accelerating replacement cycles for legacy flat-seal designs.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility frameworks are forcing material transitions toward recyclable polypropylene substrates. Compliance deadlines are compressing formulation development timelines across European supply chains.
- Japan prepared meal segment expansion:Convenience store chains and meal-kit distributors are scaling multi-serve container volumes. Dairy and deli applications in metropolitan Tokyo and Osaka clusters are driving precision tolerance requirements for oblong geometries.
Market Restraints
- Post-consumer resin cost volatility:Recycled polypropylene flake prices fluctuate with collection infrastructure gaps in the United States. Food-grade PCR availability constraints are elevating raw material input costs beyond virgin resin parity.
- Thermoforming equipment concentration:High-output inline thermoforming systems for thin-gauge lids concentrate among German and Austrian machinery suppliers. Capital equipment lead times extend 18-24 months, constraining capacity expansion for mid-scale converters.
- Silicone closure substitution in laboratory end use:Pharmaceutical-grade silicone formulations offer autoclave resistance that thermoplastic alternatives cannot match. Premium laboratory applications are migrating toward elastomeric closures despite higher unit economics.
Strategic Opportunities
- India cold-chain infrastructure buildout:Dairy cooperatives and organized retail in Maharashtra and Gujarat are adopting tamper-evident packaging for pasteurized milk and dahi. FSSAI food-contact regulations are creating specification windows for compliant closure suppliers.
- Bio-based substrate certification alignment:USDA BioPreferred and TUV Austria OK Compost HOME certifications are opening premium positioning channels. Early certification lock-in before buyer specification freezes represents defensive positioning.
- Direct-to-food-service distribution platforms:Digital procurement portals are disintermediating traditional distributor networks. Institutional buyers in the United States are aggregating demand through group purchasing organizations, creating channel access for specialized lid converters.
Industry Challenges
- Multi-material platform integration complexity:Food-contact substance notification pathways for novel polymer blends require 12-18 month FDA review cycles. Formulation lock-in before approval completion risks specification exclusion by consolidated buyers.
- Thermoforming die precision talent scarcity:Snap-fit tolerance engineering for hermetic sealing demands specialized mold flow simulation expertise. The intersection of polymer rheology and thin-wall structural design represents a constrained skill set in North American manufacturing labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oblong Tub Lids Market |
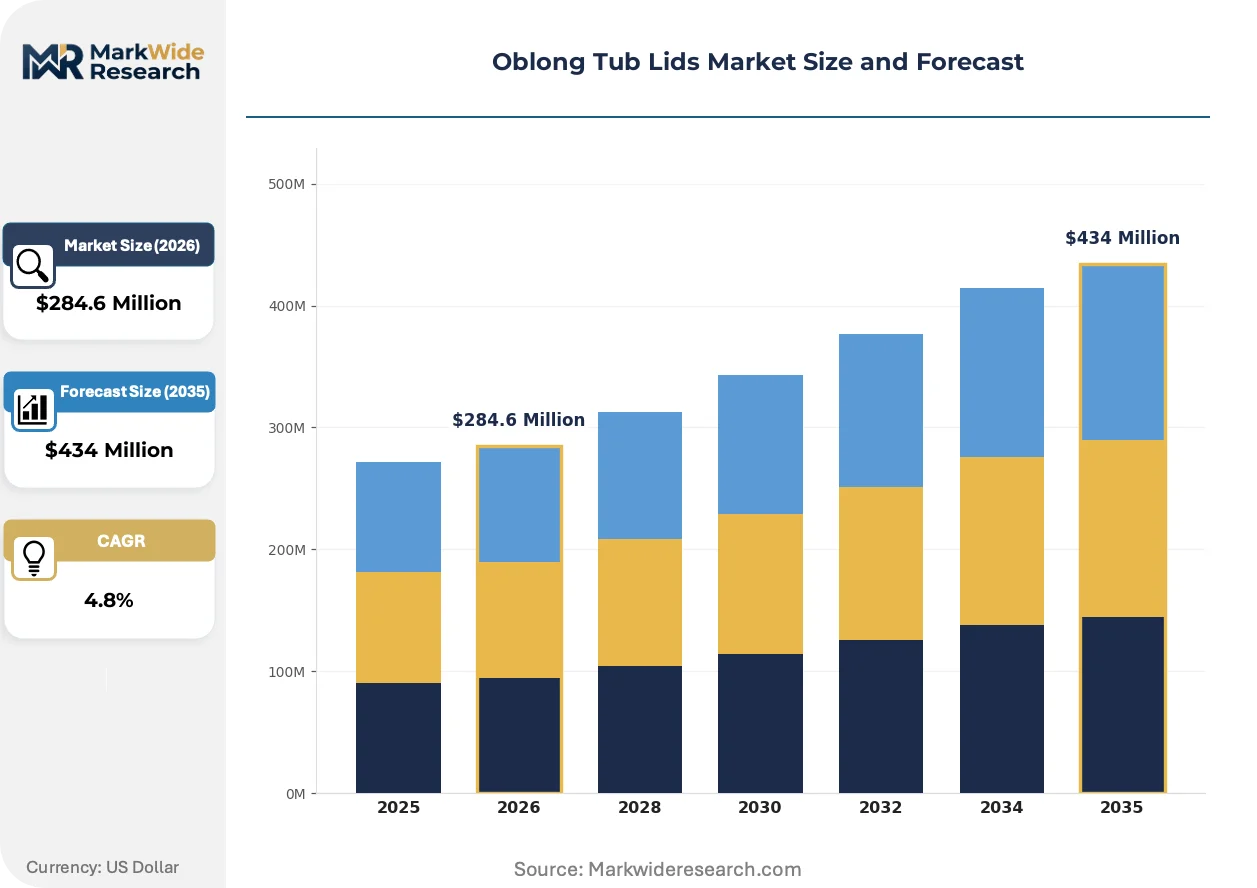
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $434 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Silicone, Glass Application: Food Packaging, Personal Care, Pharmaceuticals, Household End User: Retail, Restaurants, Laboratories, Manufacturers Closure Type: Screw-On, Snap-On, Push-On, Flip-Top |
| Companies Covered | Berry Global, Silgan Holdings, Greiner Packaging, Amcor, Sonoco Products Company, Reynolds Group Holdings, Huhtamaki Oyj, ProAmpac, AptarGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oblong Tub Lids Market Evolving Landscape
Material science advances and regulatory compliance automation are restructuring competitive capability requirements. Conversion technologies and specification workflows are converging toward closed-loop recyclability and real-time compliance verification.
In-mold labeling with integrated RFID traceability is overtaking conventional adhesive-applied labels in premium dairy applications. German dairy cooperatives are specifying this technology for batch-level cold-chain monitoring. The structural consequence is compressing margin for converters without in-mold decoration capability, as buyers bundle traceability with closure supply contracts.
EFSA migration limit updates for food-contact polypropylene are tightening additive approval requirements. Industrial consequence includes reformulation of nucleating agents and clarifiers to maintain optical properties under reduced migration thresholds. The prepared meal segment across France and Italy is most affected, with suppliers accelerating third-party testing protocols to maintain shelf presence.
Food service operators are consolidating specification authority at regional procurement centers, displacing site-level purchasing autonomy. Multi-unit restaurant chains in the United States are centralizing closure qualification through corporate supply chain functions. This concentration is most visible in the quick-service sandwich and salad segments, where national menu standardization demands uniform packaging performance across distribution zones.
Oblong Tub Lids Market Segmentation
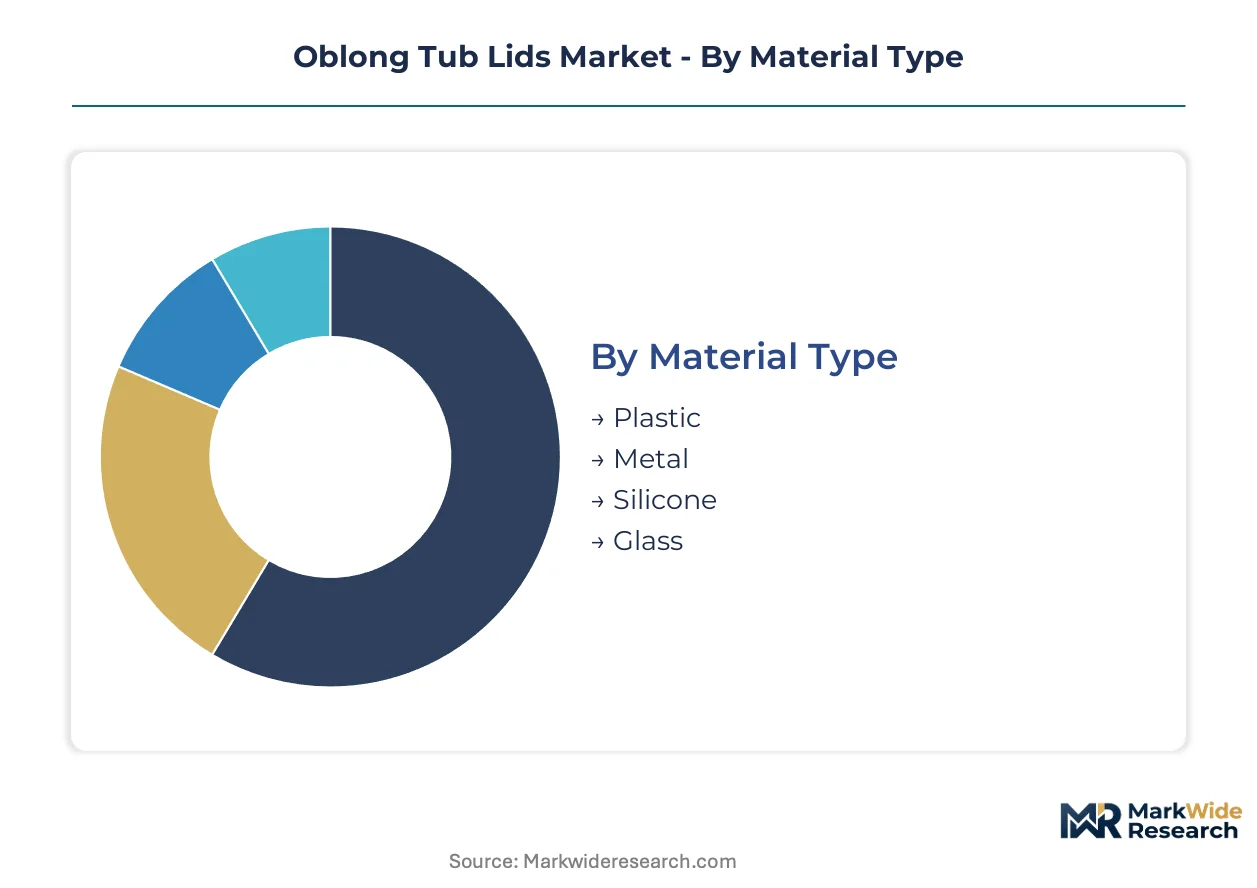
Material selection and closure geometry dictate capital deployment patterns across oblong tub lid manufacturing. Specification requirements vary sharply between cold-chain dairy, laboratory autoclave, and retail shelf applications.
Material Type:
Injection molding and thermoforming equipment for polypropylene substrates demands the heaviest upfront capital outlay among material categories, with multi-cavity tooling and inline extrusion systems representing seven-figure investments per production line.
- Plastic:Polypropylene and polyethylene terephthalate formulations dominate dairy and prepared meal applications through cost-efficient conversion and compatibility with tamper-evident banding. FDA food-contact substance notifications govern polymer selection for US dairy cooperatives, while EU Packaging and Packaging Waste Regulation deadlines are accelerating post-consumer resin formulation transitions across German and French supply chains.
- Metal:Aluminum and tinplate closures serve premium personal care and specialty food segments requiring oxygen barrier performance and extended shelf stability. Demand concentrates in Japanese cosmetics packaging and European preserves applications where hermetic sealing justifies higher unit economics against thermoplastic alternatives.
- Silicone:Pharmaceutical-grade formulations command laboratory end-use specifications requiring autoclave resistance and inert surface properties.
- Glass:Borosilicate and soda-lime closures serve niche premium food and beverage applications with aesthetic differentiation requirements.
Most installed capacity flows through Plastic. Expansion is steepest in Silicone as laboratory automation drives precision closure demand.
Application:
Volume scale and specification complexity separate commodity food packaging from premium pharmaceutical-grade requirements, with margin structures inversely related to production throughput.
- Food Packaging:Ready-meal, deli, and dairy segments drive the largest unit volumes through multi-serve container standardization. Cold-chain operators in Germany and Japan specify snap-fit tolerances and hermetic sealing performance as baseline procurement criteria, with convenience store chains in metropolitan Tokyo and Osaka accelerating replacement cycles for legacy flat-seal designs.
- Pharmaceuticals:Autoclave-resistant silicone closures and precision-molded polypropylene serve laboratory and diagnostic applications where USP Class VI compliance and low-extractable profiles justify 3-5x unit economics over food-grade alternatives. Demand clusters in Massachusetts and North Carolina life sciences corridors.
- Personal Care:Premium skincare and haircare brands specify oblong geometries for tub formats in Asian and European markets.
- Household:Cleaning product and storage applications prioritize cost efficiency over sealing performance.
Food Packaging absorbs the majority of production throughput. Pharmaceuticals delivers the highest margin per unit.
End User:
Procurement authority concentration varies sharply across customer types, with consolidated restaurant chains wielding specification leverage that fragmented retail channels cannot match.
- Restaurants:Quick-service sandwich and salad chains in the United States centralize closure qualification through corporate supply chain functions, mandating tamper-evident specifications and post-consumer resin content as baseline criteria. Group purchasing organizations aggregate institutional demand, compressing supplier margins while locking in volume commitments.
- Retail:Supermarket deli and prepared meal counters specify oblong lids for multi-serve containers with in-mold labeling compatibility. German dairy cooperatives are bundling RFID traceability requirements with closure supply contracts.
- Laboratories:Academic and commercial research facilities prioritize autoclave resistance and dimensional stability.
- Manufacturers:Co-packing and private-label operations source lids as component inputs for branded food and personal care products.
Restaurants command the tightest specification authority. Laboratories pay the steepest premium per unit.
Closure Type:
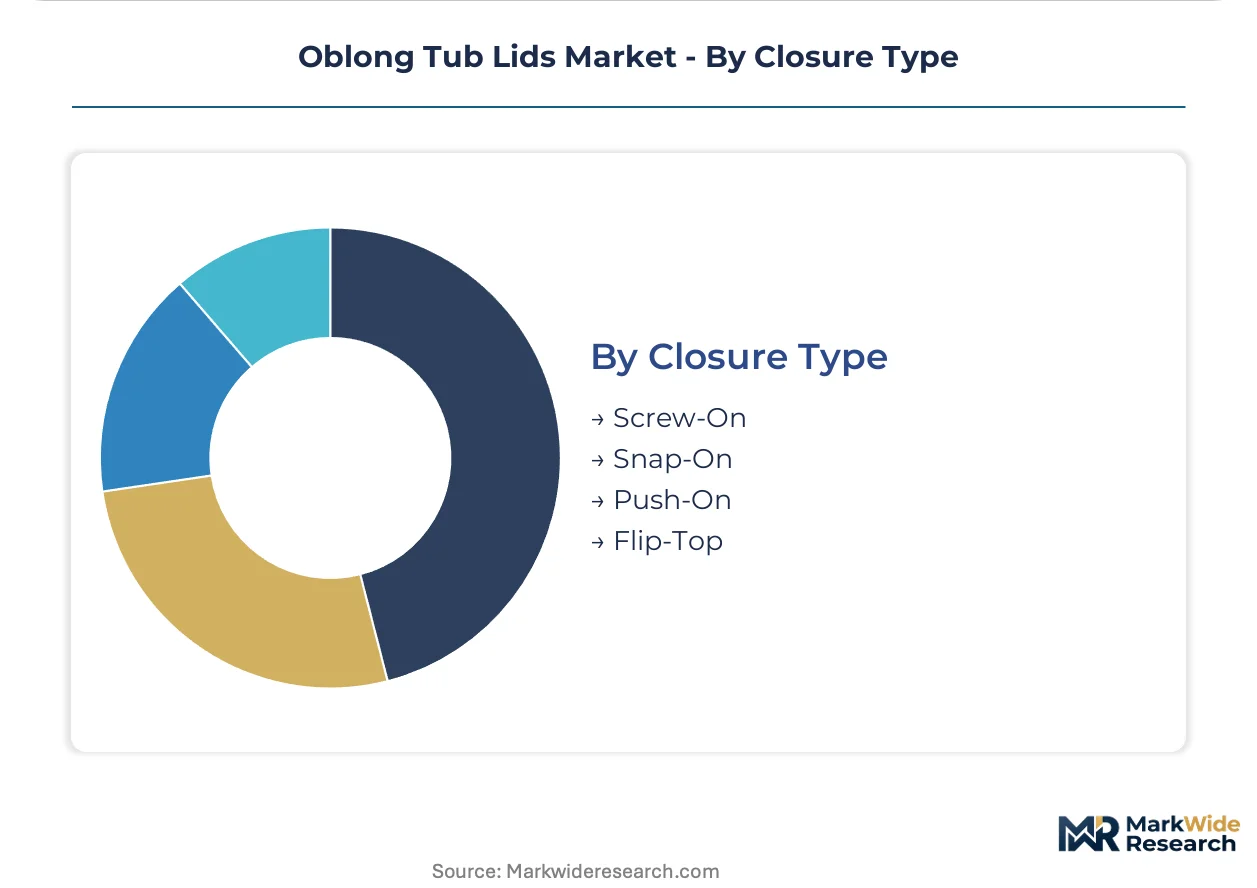
Tooling complexity and cycle time economics favor snap-on geometries for high-volume dairy applications, while screw-on formats retain positioning in premium segments requiring resealability.
- Snap-On:Single-motion engagement with visual tamper-evident indicators dominates cold-chain dairy and institutional food service applications. German and Austrian machinery suppliers concentrate high-output inline thermoforming capacity for thin-gauge snap-fit lids, with 18-24 month equipment lead times constraining mid-scale converter expansion.
- Screw-On:Threaded engagement provides resealability for personal care and premium food segments where repeated access justifies higher per-unit cost. Japanese cosmetics brands specify precision thread tolerances for luxury skincare tub formats.
- Push-On:Friction-fit designs serve cost-sensitive household and disposable food applications.
- Flip-Top:Hinged integration enables single-handed access for on-the-go consumption formats.
Snap-On carries the heaviest installed base. Screw-On maintains the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermoforming toolmakers cluster in southern Germany and upper Austria, anchoring European precision lid manufacturing. Japanese cold-chain logistics engineers concentrate in Kanto and Kansai metropolitan zones. FDA compliance specialists and dairy packaging procurement teams populate the upper Midwest and Northeast corridor of the United States.
United States
Quick-service restaurant chains and institutional food service buyers drive tamper-evident closure specifications. FDA food-contact substance notifications govern polymer selection and migration limits for dairy applications. Chicago and Minneapolis-St. Paul clusters host dairy cooperative procurement headquarters specifying hermetic sealing performance.
Germany
Dairy cooperatives and prepared meal distributors mandate post-consumer resin content in closure specifications. EU Packaging and Packaging Waste Regulation deadlines accelerate recyclable polypropylene transitions across Bavarian and North Rhine-Westphalian supply chains. Munich and Stuttgart industrial zones concentrate high-output inline thermoforming capacity for thin-gauge snap-fit lids.
Japan
Convenience store chains and meal-kit distributors scale multi-serve container volumes for dairy and deli segments. METI circular economy guidelines shape material transition timelines for packaging converters. Tokyo and Osaka metropolitan clusters drive precision tolerance requirements for oblong geometries in cold-chain applications.
India
Dairy cooperatives in Maharashtra and Gujarat adopt tamper-evident packaging for pasteurized milk and dahi. FSSAI food-contact regulations create specification windows for compliant closure suppliers. Ahmedabad and Pune manufacturing corridors attract thermoforming equipment investments serving organized retail expansion.
France
Prepared meal suppliers and deli counter operators specify in-mold labeling compatibility for traceability requirements. EFSA migration limit updates for food-contact polypropylene tighten additive approval requirements. Lyon and Paris basin food packaging clusters accelerate third-party testing protocols to maintain shelf presence under reduced migration thresholds.
Oblong Tub Lids Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material platform and geographic coverage dimensions. The supply base exhibits tiered concentration, with global packaging groups wielding specification influence over consolidated food service buyers while regional converters serve fragmented retail channels. Three archetypes dominate: resin-to-lid integrated manufacturers, multi-material platform operators, and precision thermoforming specialists. Capacity expansion and post-consumer resin formulation development represent the dominant competitive moves as regulatory deadlines compress.
Among diversified packaging conglomerates, Berry Global exemplifies North American vertical integration spanning resin compounding through thermoformed lid production. Greiner Packaging anchors European dairy accounts through Austrian manufacturing scale and regional specification authority. Amcor occupies a position as multi-material platform breadth enables cross-channel supply to food and personal care segments globally.
| Leading Market Players |
|---|
| Berry Global |
| Silgan Holdings |
| Greiner Packaging |
| Amcor |
| Sonoco Products Company |
| Reynolds Group Holdings |
| Huhtamaki Oyj |
| ProAmpac |
| AptarGroup |
| Others |
Value Network & Pricing Analysis
Consolidated food service procurement in the United States is mandating post-consumer resin content and tamper-evident specifications as baseline qualification criteria, forcing converters to absorb formulation transition costs and compressing margin structures across mid-scale suppliers unable to achieve virgin-to-recycled resin parity.
Pricing Analysis
Capacity additions in Germany and Austria are reshaping price floors for precision thermoformed lids as high-output inline systems concentrate among Munich and Stuttgart industrial zones. Three-tier pricing structure across pharmaceutical-grade silicone, food-grade post-consumer resin, and virgin polypropylene commodity tiers reflects certification grade and volume scale differentiation. Cost compression in the recycled polypropylene tier is intensifying because food-grade PCR availability constraints elevate raw material input costs beyond virgin resin parity. Quick-service restaurant chains exhibit the steepest price sensitivity through group purchasing organization aggregation, while laboratory end users pay minimal attention to unit economics given autoclave resistance requirements.
Supply Chain Analysis
Direct-to-food-service channels handle hyperscale buyer demand through digital procurement portals that disintermediate traditional distributor networks. Manufacturing gravity centers on Germany, Austria, and the United States where specialized thermoforming toolmakers and resin compounding operations cluster. Raw material feeds draw from polypropylene resin production, recycled flake collection infrastructure, and pharmaceutical-grade silicone precursor supply. Single-source vulnerability concentrates in high-output inline thermoforming equipment where German and Austrian machinery suppliers command 18-24 month lead times. Distribution runs through group purchasing organizations for institutional buyers and direct contracts for dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oblong tub lids market functions as a geographic-arbitrage play where EU Packaging and Packaging Waste Regulation compliance costs in Germany diverge from FSSAI specification windows in India, creating cost-advantaged positioning for early entrants in emerging cold-chain infrastructure buildouts.
For Market Incumbents: Anchor European dairy accounts through accelerated post-consumer resin formulation lock-in before EU compliance deadlines freeze specifications. Defensive consolidation through captive supply of recycled polypropylene flake and in-mold labeling capability bundling protects against specialized lid converters disintermediating through traceability-integrated contracts. Threats from pharmaceutical-grade silicone substitution in laboratory end use demand counter-positioning via autoclave-resistant thermoplastic development. For New Entrants and Emerging Players: FSSAI food-contact regulations in India open a window for compliant closure suppliers to capture dairy cooperative procurement in Maharashtra and Gujarat where organized retail expansion outpaces domestic thermoforming capacity. White-space targets cluster in cold-chain dairy tamper-evident packaging and bio-based substrate certification for premium positioning channels. Direct-to-food-service digital platforms offer the most penetrable go-to-market angle for bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with precision thermoforming specialists possessing mold flow simulation expertise and FDA food-contact substance notification pathways. Long-term viability over a multi-year horizon favors acquisition targets with locked-in post-consumer resin formulations and established group purchasing organization channel access. The signal to watch as inflection indicator is recycled polypropylene flake price stabilization relative to virgin resin parity.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Formulation Lock-In | FDA notification completion before EU Packaging and Packaging Waste Regulation deadlines secures specification continuity with consolidated buyers. |
| In-Mold Labeling Capability Integration | German dairy cooperative bundling of RFID traceability requirements compresses margin for converters without decoration technology. |
| Direct-to-Food-Service Platform Launch | Digital procurement portal disintermediation captures institutional demand aggregation through group purchasing organizations. |
| Precision Thermoforming Capacity Expansion | Munich and Stuttgart industrial zone proximity to Austrian machinery suppliers reduces equipment lead time exposure. |
| Bio-Based Substrate Certification Alignment | USDA BioPreferred and TUV Austria OK Compost HOME credentials open premium positioning before buyer specification freezes. |
Research Methodology
Bottom-up food packaging and laboratory end-use modeling reconciled against top-down resin compounding and thermoforming capacity tracking forms the analytical core. Primary interviews with dairy cooperative procurement directors, quick-service restaurant supply chain executives, thermoforming plant managers, and FDA regulatory affairs consultants combined with secondary validation through FDA food-contact substance notification databases, EU Packaging and Packaging Waste Regulation filings, FSSAI compliance records, and customs trade data for polypropylene resin and recycled flake flows. Triangulation across stakeholder inputs and documentary sources validates volume and value estimates.
Input-output matrices connect polymer resin throughput to lid unit production across material type, application, end user, and closure type segmentation dimensions. CAGRs derive from trend extrapolation of tamper-evident specification adoption rates, post-consumer resin formulation transition timelines, and cold-chain infrastructure investment patterns. Industry-specific forecast inputs include dairy cooperative procurement cycle timing and convenience store chain multi-serve container volume scaling.
Revisions become necessary when FDA migration limit updates, EFSA additive approval requirement tightening, or recycled polypropylene collection infrastructure gaps materialize beyond modeled scenarios. Forecasts reflect assumptions about regulatory deadline adherence and resin price parity convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Metal Crates Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Compartment Take-Out Container Market
Containers
Global Container Monitoring Market
Containers
Shipping Container Liners Market
Containers
Multi Cavity Tray Market
Containers
Steel Containers Market
Containers
Jerry Cans Market
Containers
Die Cut Display Container Market
Containers
Intermediate Bulk Container Liner Market
Containers
EPS Shippers Market
Containers
Popcorn Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Essential Oil Containers Market
Containers
Feeder Containers Market
Containers
ISO Ocean Containers Market