
 Modular Container Market | 2026-2036
Modular Container Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Container Market Intelligence
Skilled welder availability is bifurcating the competitive landscape between automated producers and labor-dependent fabricators. CIMC leverages robotic seam-welding lines to sustain output volumes across its Shenzhen and Yangzhou plants. WillScot anchors North American rental fleet expansion through proprietary logistics software that optimizes container repositioning. Algeco competes on pan-European density, with Module-T specializing in Turkey-to-Caucasus project logistics for oilfield accommodation modules.
Modular containers are prefabricated steel or aluminum enclosures, typically built to ISO dimensional frameworks with weather-sealed corner castings and stackable structural ratings, designed for rapid deployment and repeated relocation across industrial, commercial, and humanitarian settings. Accommodation modules command premium pricing due to MEP integration complexity and habitability certification requirements, while portable units represent the highest-volume segment driven by disaster-response stockpiling and construction cyclicality. Steel dominates material demand for load-bearing multi-story configurations, though composite panels are gaining share in climate-controlled pharmaceutical storage applications where thermal bridging penalties matter.
China's SAMR enforces GB/T structural welding standards that disqualify manual-only shops from state-tender eligibility, while the EU's Construction Products Regulation mandates CE-marked fire resistance testing for accommodation modules sold across member states. India's BIS certification for prefabricated steel buildings creates compliance bottlenecks that favor established players with in-house testing laboratories. Stakeholders must monitor how building-code harmonization between ASEAN economies affects cross-border module acceptance, as divergent seismic and insulation standards currently fragment procurement decisions.
Market Dynamics
Automated seam-welding systems are bifurcating the competitive landscape between capital-intensive fabricators and labor-dependent shops as China's SAMR tightens GB/T certification requirements for state-tender eligibility.
Growth Catalysts
- India's industrial corridor fast-tracking:State governments in Gujarat and Maharashtra are accelerating temporary worker housing approvals for petrochemical and logistics hub construction, compressing procurement cycles from 18 months to 90 days.
- EU Construction Products Regulation harmonization:CE-marked fire resistance testing for accommodation modules is enabling cross-border fleet redeployment between Germany, Poland, and Romania without recertification costs.
- Composite panel thermal performance:Pharmaceutical cold-chain operators are specifying vacuum-insulated sandwich cores over steel monocoque construction to eliminate thermal bridging penalties in climate-controlled storage.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs swing 40% within fiscal quarters, eroding fixed-price contract margins for fabricators without upstream hedging instruments.
- Welder certification bottlenecks:China's SAMR disqualification of manual-only shops from infrastructure tenders is concentrating supply among automated producers in Guangdong and Jiangsu provinces.
- On-site concrete foundation substitution:Permanent tilt-up construction retains cost advantages for multi-year industrial facilities exceeding 5,000 square meters, capping modular penetration in heavy manufacturing.
Strategic Opportunities
- ASEAN building-code harmonization:Divergent seismic and insulation standards across Vietnam, Thailand, and Indonesia currently fragment procurement; early alignment positioning captures cross-border project logistics.
- Disaster-response stockpile modernization:FEMA and UNDP procurement frameworks are shifting from tent-based to containerized accommodation, opening 72-hour deployment specification opportunities.
- Offshore wind accommodation vessels:North Sea turbine installation fleets require stackable, crane-liftable module systems with DNV-GL marine certification, a specification tier few land-based fabricators occupy.
Industry Challenges
- Robotic welding technician scarcity:Automated fabrication lines require programmers fluent in both ISO welding protocols and FANUC or KUKA motion control, a skill intersection concentrated in Shenzhen and Yangzhou industrial clusters.
- Multi-jurisdiction certification overlap:Accommodation modules sold into India's BIS framework, the EU's CPR, and China's GB/T simultaneously face conflicting fire-resistance test protocols, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Container Market |
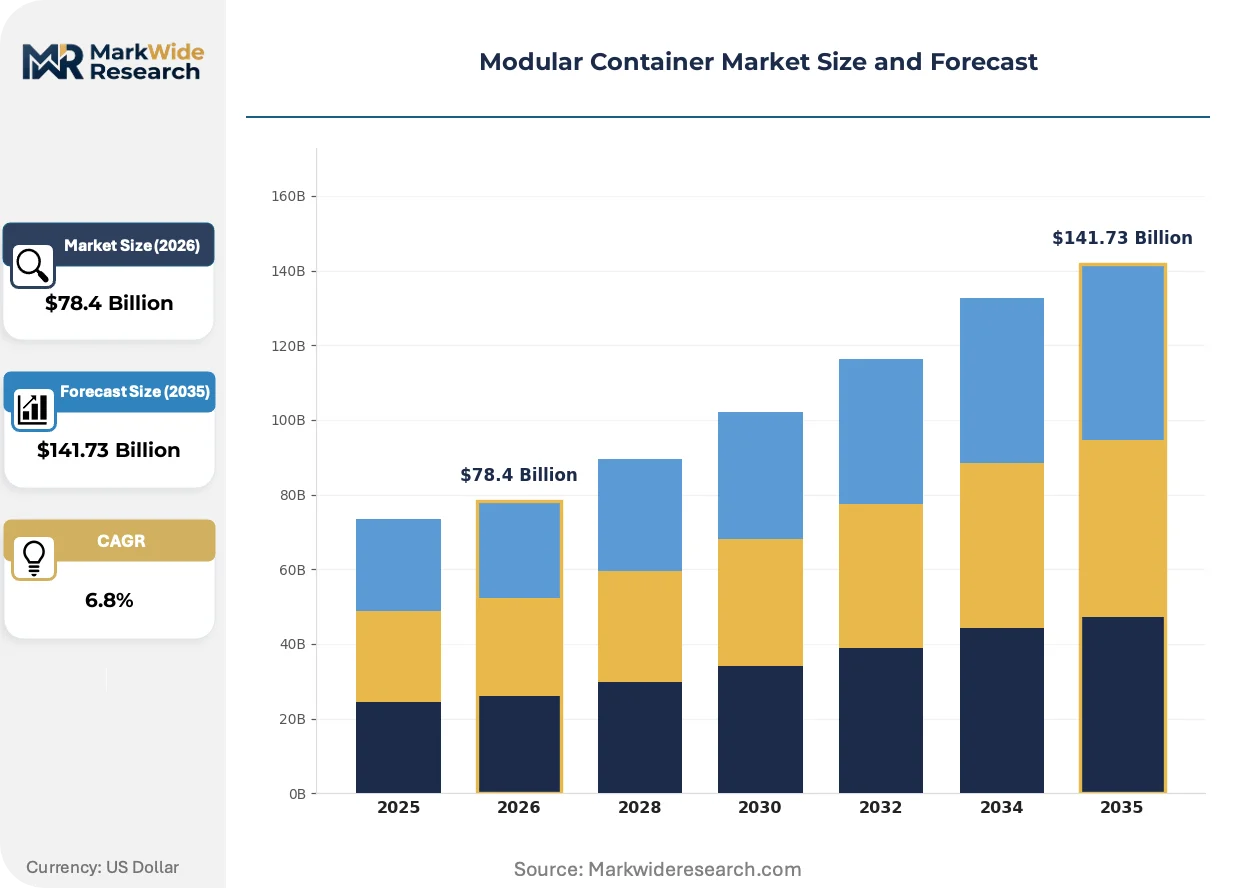
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Storage Containers, Accommodation Modules, Office Containers End User: Construction, Military, Transportation, Events Application: Permanent Housing, Temporary Shelter, Site Office, Retail Space Material: Steel, Aluminum, Wood, Composite |
| Companies Covered | Algeco, Container Technology Inc, CIMC, Module-T, Modular Space Corporation, Containex, WillScot, Henan K-Home, Portakabin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Container Market Strategic Shifts & Innovations
Digital twin configuration platforms are compressing design-to-delivery cycles while material science advances in phase-change insulation and corrosion-resistant alloys expand deployment environments beyond traditional construction sites.
Phase-change material (PCM) thermal buffering is decomposing the traditional HVAC-oversizing paradigm in accommodation modules. Arctic oilfield operators in Norway and Alaska are adopting PCM-lined wall assemblies that flatten diurnal temperature swings. This technology is decomposing the historical requirement for 30% excess cooling capacity in extreme-climate deployments.
China's SAMR enforcement of GB/T 26951 automated welding standards is disqualifying manual fabrication shops from state infrastructure tenders. Provincial transport bureaus in Shandong and Sichuan now require digital weld-traceability logs for bridge-site office modules. Tier-two fabricators without robotic seam-welding lines are retreating to private commercial projects with lower compliance thresholds.
Rental fleet operators are unbundling after-sales service from hardware procurement, shifting toward availability-guarantee contracts with penalty clauses for deployment delays. Construction site managers in Germany's Baden-Württemberg region now specify 48-hour replacement commitments rather than equipment ownership. This model compresses vendor selection criteria toward logistics software sophistication and depot network density rather than unit manufacturing cost alone.
Modular Container Market Segmentation
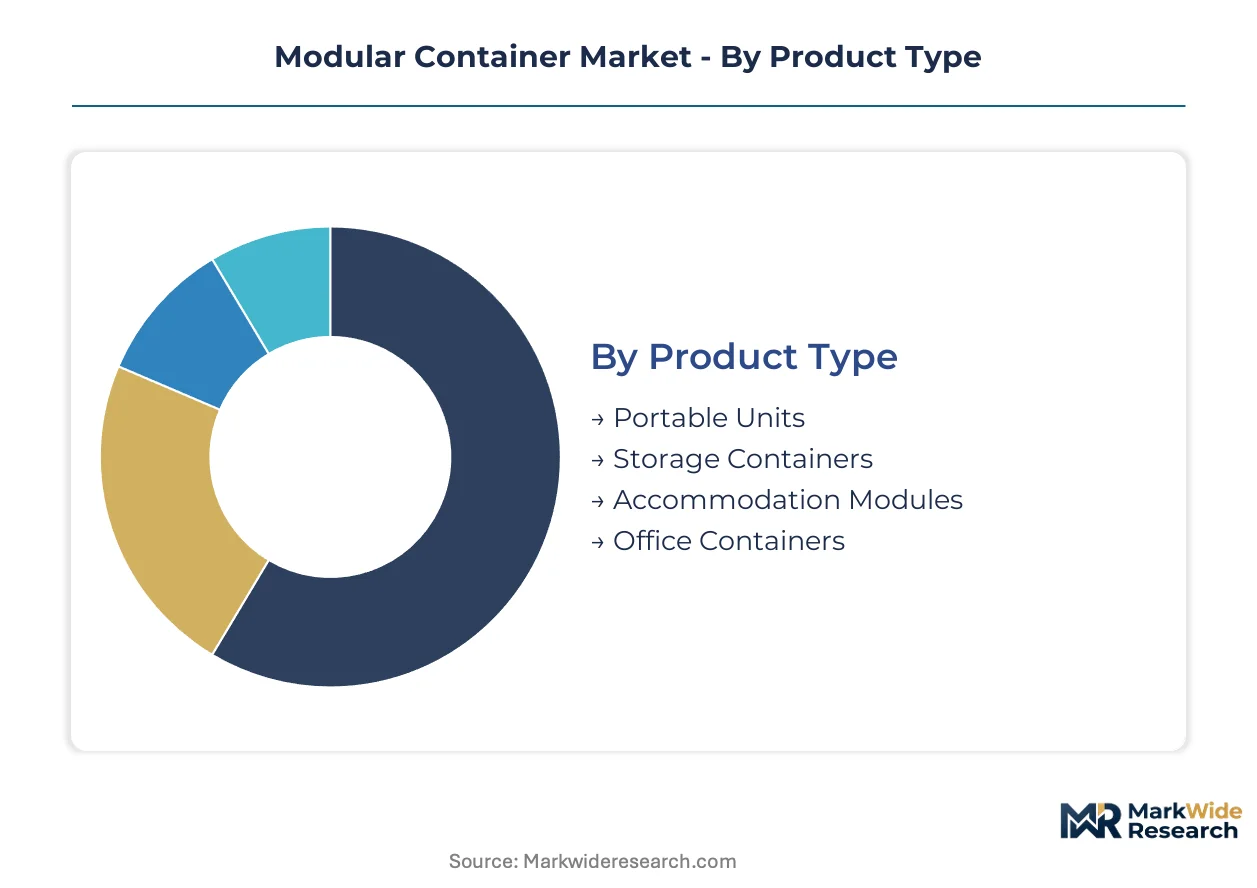
Modular container procurement decisions bifurcate sharply between certification-intensive accommodation specifications and volume-driven portable deployment. Regulatory frameworks across GB/T, CE marking, and BIS standards create divergent compliance cost structures that reshape competitive positioning within each segment tier.
Product Type:
GB/T 26951 automated welding certification in China and CE fire-resistance testing in the EU impose tiered compliance burdens that segment producers by capital intensity rather than unit economics alone.
- Accommodation Modules:MEP-integrated steel enclosures with habitability certifications command premium positioning. India's industrial corridor projects in Gujarat and Maharashtra compress 18-month procurement cycles to 90 days for worker housing specifications.
- Portable Units:Rapid-deployment ISO-framed containers dominate disaster-response stockpiling and construction cyclicality. FEMA and UNDP procurement frameworks are shifting from tent-based to containerized accommodation, opening 72-hour deployment specifications.
- Storage Containers:Climate-controlled pharmaceutical applications specify vacuum-insulated sandwich cores to eliminate thermal bridging penalties in cold-chain operations.
- Office Containers:Bridge-site modules in Shandong and Sichuan provinces now require digital weld-traceability logs under provincial transport bureau rules.
Established volume favors Portable Units; emerging adoption favors Accommodation Modules.
End User:
Customer procurement sophistication varies from spot-rental construction managers to multi-year defense contractors with embedded logistics requirements.
- Construction:German site managers in Baden-Württemberg specify 48-hour replacement commitments through availability-guarantee contracts, compressing vendor selection toward logistics software sophistication.
- Military:DNV-GL marine certification requirements for offshore wind accommodation vessels create specification tiers few land-based fabricators occupy.
- Transportation:Pan-European fleet operators optimize container repositioning through proprietary software platforms.
- Events:Temporary retail and hospitality deployments favor rapid-configuration units with minimal foundation preparation.
Procurement maturity concentrates in Military; deployment velocity drives Construction.
Application:
Duration of use determines material specification, with permanent installations requiring seismic compliance absent from temporary shelter standards.
- Site Office:Construction site managers across Germany and Australia are expanding orders as labor mobility rises, with modular units replacing permanent tilt-up for sub-5,000 square meter facilities.
- Temporary Shelter:Disaster-response stockpile modernization shifts procurement from tent-based to containerized systems with 72-hour deployment windows.
- Permanent Housing:Multi-story steel configurations face substitution pressure from on-site concrete for industrial facilities exceeding 5,000 square meters.
- Retail Space:Pop-up commercial configurations prioritize rapid assembly and relocation capability over structural longevity.
Volume concentration sits with Site Office; steepest expansion trajectory appears in Temporary Shelter.
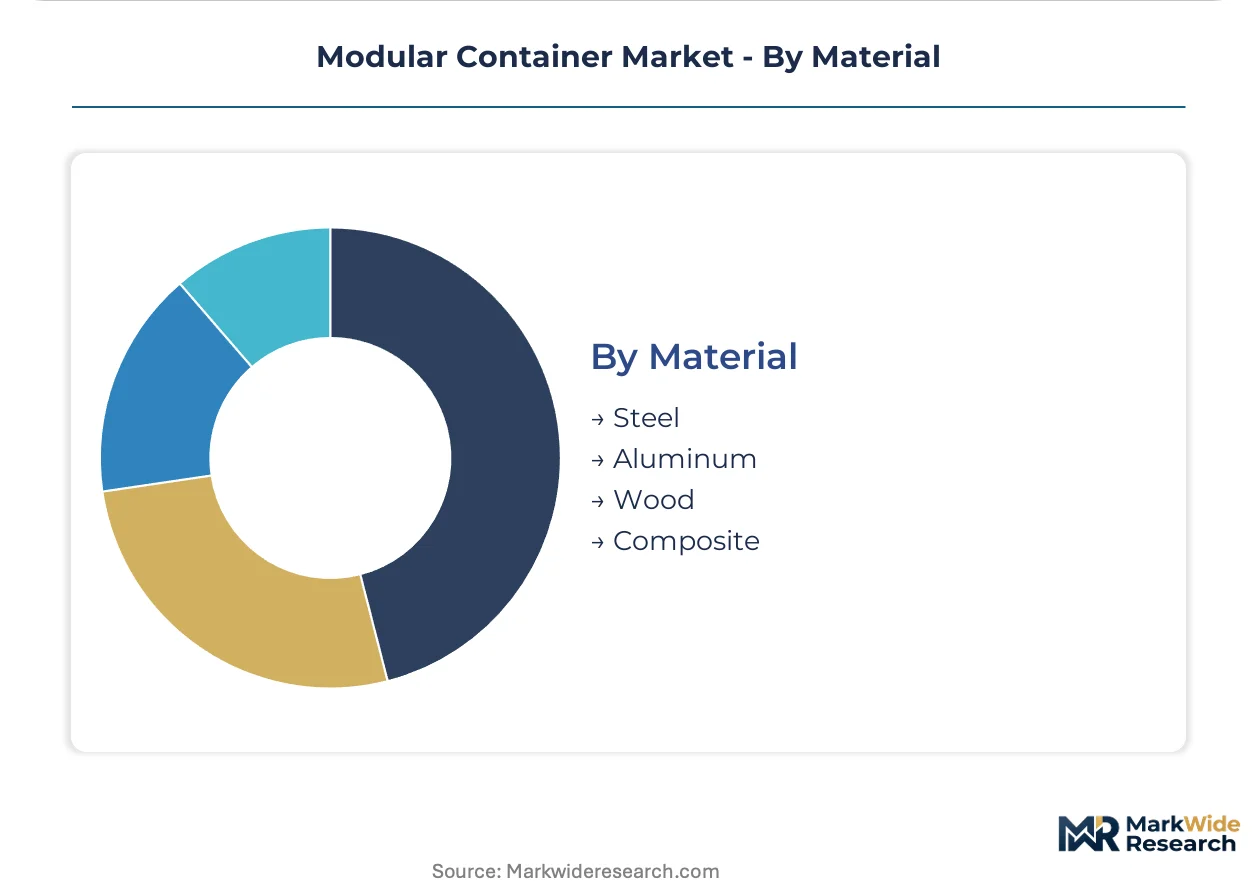
Material:
Input cost volatility and thermal performance requirements segment material selection by end-use climate sensitivity and load-bearing specifications.
- Steel:Hot-rolled coil input costs swing 40% within fiscal quarters, eroding fixed-price contract margins for fabricators without upstream hedging instruments. Dominates multi-story load-bearing configurations.
- Composite:Vacuum-insulated sandwich cores gain share in pharmaceutical cold-chain storage where thermal bridging penalties matter.
- Aluminum:Corrosion-resistant alloys expand deployment environments in marine and coastal applications.
- Wood:Limited to low-rise temporary structures with minimal seismic or fire-resistance requirements.
Structural duty favors Steel; thermal performance favors Composite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German construction managers prioritize rental availability guarantees, while Indian state governments compress procurement timelines for worker housing, and Chinese fabricators face automated welding mandates that reshape competitive access.
Germany
Site managers in Baden-Württemberg specify 48-hour replacement commitments through availability-guarantee contracts rather than equipment ownership. CE marking under the EU Construction Products Regulation enables cross-border fleet redeployment without recertification costs. Industrial concentration centers on the Rhine-Ruhr corridor, where pan-European rental operators optimize container repositioning through proprietary logistics platforms.
China
State infrastructure tenders now require GB/T 26951 automated welding certification, disqualifying manual-only fabrication shops from eligibility. SAMR enforcement tightens weld-traceability rules for bridge-site office modules in Shandong and Sichuan provinces. Production gravity clusters in Shenzhen and Yangzhou, where robotic seam-welding lines sustain output volumes for compliant producers.
India
State governments in Gujarat and Maharashtra fast-track temporary worker housing approvals for petrochemical and logistics hub construction, compressing procurement cycles from 18 months to 90 days. BIS certification for prefabricated steel buildings creates compliance bottlenecks favoring established players with in-house testing laboratories. Demand concentrates along the Delhi-Mumbai Industrial Corridor, where modular accommodation serves migrant construction labor.
Australia
Construction site managers expand orders for portable site offices as labor mobility rises across mining and infrastructure projects. The country's national building code regulator mandates structural compliance for temporary worker accommodations in remote resource extraction zones. Fabrication activity clusters in Western Australia, where fly-in-fly-out workforce logistics drive specification for crane-liftable, stackable module systems.
United States
FEMA procurement frameworks shift from tent-based to containerized accommodation for disaster-response stockpiling, opening 72-hour deployment specifications. OSHA workplace standards influence site office configurations for construction sector compliance. Fleet operators anchor capacity in Texas and the Southeast, where proprietary logistics software optimizes container repositioning across cyclical construction demand.
Modular Container Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital-intensive automated fabricators separating from labor-dependent shops under tightening certification regimes. The market structure reflects bifurcation between rental fleet operators with dense depot networks and project-focused fabricators serving oilfield and infrastructure specifications. Two strategic archetypes dominate: pan-regional rental platforms with logistics software advantages, and certified specialty producers occupying marine or seismic-grade niches. Competitive moves concentrate on automated welding line investments and availability-guarantee contract structures that shift customer relationships from equipment ownership to service-level commitments.
Among the named players, CIMC and WillScot exemplify divergent strategic positions. CIMC represents the capital-intensive automated fabrication archetype, with Chinese regulatory compliance positioning it for state-tender eligibility. WillScot anchors the North American rental fleet expansion model, where proprietary logistics software drives vendor selection criteria. Module-T occupies a specialist position in Turkey-to-Caucasus project logistics, serving oilfield accommodation modules across divergent seismic and insulation standards. Algeco competes on pan-European depot density, reflecting the geographic consolidation logic of rental availability guarantees.
| Leading Market Players |
|---|
| Algeco |
| Container Technology Inc |
| CIMC |
| Module-T |
| Modular Space Corporation |
| Containex |
| WillScot |
| Henan K-Home |
| Portakabin |
| Others |
Cost & Logistics Intelligence
Capacity utilization at automated welding lines in Guangdong and Jiangsu provinces shapes both supply concentration and price floors for compliant producers. Fabricators without robotic seam-welding capability retreat to private commercial segments with lower certification thresholds, compressing margins in those tiers while state-tender eligible suppliers command premium positioning.
Pricing Analysis
Long-term availability-guarantee contracts with penalty clauses for deployment delays now dominate procurement in Germany's Baden-Württemberg region, displacing spot equipment purchases. Pricing stratifies across premium certification tiers—CE-marked fire resistance for EU accommodation modules, GB/T 26951 automated welding compliance for Chinese state tenders, and BIS-certified prefabricated steel for Indian industrial corridors. Cost compression in portable units is intensifying as manual-only shops compete for private commercial work. Construction site managers show highest price sensitivity on standard office containers, while offshore wind operators accept substantial premiums for DNV-GL marine-certified accommodation vessels.
Supply Chain Analysis
China, Germany, and India anchor fabrication capacity for distinct specification tiers. Chinese producers in Shenzhen and Yangzhou feed state infrastructure tenders with automated welding output. German fabricators serve pan-European rental fleet demand through Rhine-Ruhr corridor depots. Indian production clusters along the Delhi-Mumbai Industrial Corridor address compressed 90-day procurement cycles for worker housing. Raw material inputs draw from hot-rolled coil suppliers, vacuum-insulated sandwich core producers, and corrosion-resistant alloy foundries. Single-source vulnerability concentrates in robotic welding technician pools concentrated in Shenzhen and Yangzhou industrial clusters. Distribution runs through rental fleet operators with proprietary logistics software and project-based fabricators serving oilfield specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as certification requirements bifurcate between automated capital-intensive producers and labor-dependent shops. India's 90-day procurement compression and ASEAN's divergent seismic standards create addressable niches for specialists.
For Market Incumbents: Secure automated welding line capacity in Guangdong and Jiangsu provinces to maintain GB/T 26951 state-tender eligibility as SAMR enforcement tightens. Secure proprietary logistics software advantages for availability-guarantee contract structures that shift customer relationships from equipment ownership to service-level commitments, defending against rental fleet operators with dense depot networks. For New Entrants and Emerging Players: Lead with Turkey-to-Caucasus project logistics for oilfield accommodation modules across divergent seismic and insulation standards, where established pan-European density players lack localized presence. Target disaster-response stockpile modernization specifications as FEMA and UNDP procurement frameworks shift from tent-based to containerized systems with 72-hour deployment windows. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated fabricators with GB/T compliance and DNV-GL marine certification capabilities over labor-dependent shops facing regulatory disqualification. Long-term viability hinges on capital intensity alignment with tightening certification regimes rather than volume scale alone. Watch ASEAN building-code harmonization progress as inflection indicator for cross-border project logistics consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Line Investment | GB/T 26951 compliance secures eligibility for Chinese state infrastructure tenders. |
| Availability-Guarantee Contract Structure | 48-hour replacement commitments in Baden-Württemberg shift vendor selection criteria toward logistics sophistication. |
| DNV-GL Marine Certification Acquisition | Offshore wind accommodation specifications in the North Sea remain underserved by land-based fabricators. |
| Proprietary Logistics Software Development | Container repositioning optimization drives rental fleet operator competitive positioning across cyclical construction demand. |
| PCM Thermal Buffering Integration | Phase-change material wall assemblies flatten diurnal temperature swings for Arctic oilfield deployments. |
Research Approach
A spread of perspectives from construction site managers, rental fleet operators, welding certification auditors, and state procurement officers converged on the working assumptions for demand quantification. Secondary validation drew from SAMR enforcement bulletins, EU Construction Products Regulation harmonization updates, BIS prefabricated steel building standards, and customs data on hot-rolled coil trade flows. Bottom-up unit economics from fabrication facilities triangulated against top-down industrial corridor investment announcements.
Segmentation dimensions modeled include product type across accommodation modules, portable units, storage containers, and office containers; end user across construction, military, transportation, and events; application across site office, temporary shelter, permanent housing, and retail space; and material across steel, composite, aluminum, and wood. CAGRs were derived from shipment volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporated procurement cycle compression in Indian state governments and automated welding certification penetration in Chinese provincial tender requirements.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement, ASEAN code harmonization, or steel price volatility stabilization would require recalibration. Forecasts reflect assumptions on certification timeline standardization and rental fleet software adoption curves. Recalibration cycles align with material shifts in regulatory enforcement intensity and industrial corridor project acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
North America Plastic Bottles and Containers Market
Containers
Compartment Take-Out Container Market
Containers
Essential Oil Containers Market
Containers
Edible Oil Cans Market
Containers
Screw Top Pails Market
Containers
Half Height Containers Market
Containers
Pail Lids Market
Containers
Bulk Containers Market
Containers
Conipack Pails Market
Containers
Screw Top Jar Market
Containers
Metal Cans and Glass Jars Market
Containers
Takeout Containers Market
Containers
Durable Insulated Containers Market
Containers
Sandwich Containers Market
Containers
Wooden Crates Market
Containers
Slip Lid Can Market