
 Single Wall Jars Market | 2026-2036
Single Wall Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Single Wall Jars Market Analytics
REACH is restructuring material sourcing protocols for European single wall jar suppliers, forcing reformulation of plastic resins and expanded migration testing. Berry Global leverages captive resin compounding to sustain cost predictability across its European footprint. Gerresheimer AG anchors premium glass jar demand through pharmaceutical-grade borosilicate capacity. Amcor competes in Asia-Pacific through lightweight PET jar platforms designed for cosmetics dispensers.
Single wall jars are cylindrical containers fabricated from one continuous material layer, typically ranging from 15 ml to 1000 ml capacity, formed through injection blow molding, extrusion blow molding, or press-and-blow glass processes. They serve as primary packaging for creams, serums, food preserves, and topical medications where barrier requirements permit single-layer construction without additional lamination or coating. Plastic closures dominate volume shipments due to compatibility with automated capping lines, though glass jars paired with metal screw caps command premium positioning in clean beauty and apothecary segments. The food industry end user category remains mature with stable replacement cycles, while cosmetics applications generate accelerating demand for bamboo-bodied jars with cork closures as brand sustainability commitments harden.
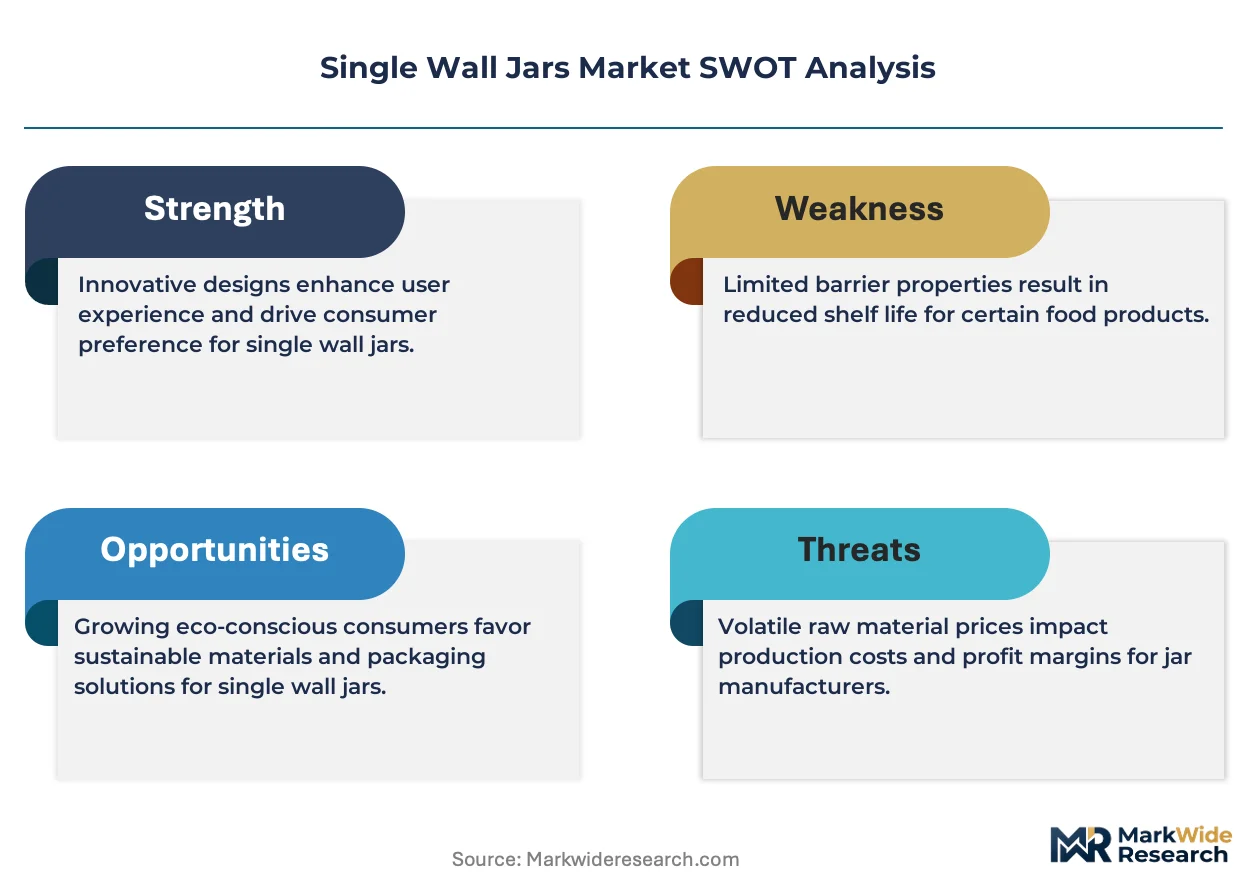
FDA maintains active oversight of food-contact and cosmetic packaging through 21 CFR standards, while EPA regulates resin manufacturing emissions and post-consumer recycling targets. The EU Green Deal and associated Packaging and Packaging Waste Directive revisions are mandating minimum recycled content thresholds that reshape raw material procurement for jar converters. Stakeholders must monitor regulatory divergence between California's SB 54 implementation and EU harmonization timelines, as compliance strategy fragmentation threatens to segment supply chains into incompatible technical specifications.
Market Dynamics
REACH compliance deadlines are compressing formulation cycles for European single wall jar converters, forcing simultaneous resin substitution and migration testing investments that reshape procurement economics across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content mandates accelerate demand for post-consumer rPET and rPP jar formats. Brand owners in Germany and France advance supplier qualification timelines to secure compliant capacity.
- Bamboo composite material platforms:Lignocellulosic fiber-polymer blends enable 40-60% biobased jar bodies with injection molding compatibility. Clean beauty brands in Scandinavia and California specify these for premium skincare lines.
- India Maharashtra manufacturing corridor:State-level packaging cluster incentives attract blow molding capacity for domestic cosmetics and pharmaceutical markets. Local converters benefit from proximity to Mumbai-Ahmedabad freight corridors.
Market Restraints
- Post-consumer recycled resin price volatility:rPET flake and food-grade pellet spreads swing with collection infrastructure bottlenecks. Jar converters face margin compression when virgin-to-recycled price inversions occur.
- Pharmaceutical-grade borosilicate glass supply concentration:Specialty glass melting capacity clusters in Germany and India. Cosmetic brands seeking apothecary aesthetics encounter allocation constraints during capacity maintenance cycles.
- Multi-layer barrier jar substitution:Co-extruded and coated containers capture oxygen-sensitive food and pharmaceutical applications. Single wall formats lose specification share in retort and hot-fill segments.
Strategic Opportunities
- Indonesia cosmetics manufacturing expansion:Halal-certified jar demand outpaces local blow molding capacity. Regional brands seek compliant single wall PET and PP suppliers for Southeast Asian distribution.
- Digital printing direct-to-shape:UV-cured inkjet systems enable lot-size-one customization without label substrates. Short-run beauty and gift jar applications bypass traditional silkscreen minimums.
- California SB 54 extended producer responsibility:Plastic packaging reduction mandates create first-mover advantage for refillable jar systems. Brands investing in durable primary packaging with take-back infrastructure qualify for fee reductions.
Industry Challenges
- Migration testing laboratory capacity:EU 10/2011 compliance for novel biobased resins requires specialized analytical queues. Jar converters face 12-18 month approval timelines for sustainable material transitions.
- Automated capping line retrofit complexity:Lightweighting and material stiffness variations demand gripper and torque head recalibration. Cosmetic contract manufacturers absorb downtime costs during format switches.
- Food-contact certification fragmentation:Divergent FDA, EFSA, and FSSAI additive positive lists complicate global jar platform standardization. Multi-territory brands maintain parallel resin specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Wall Jars Market |
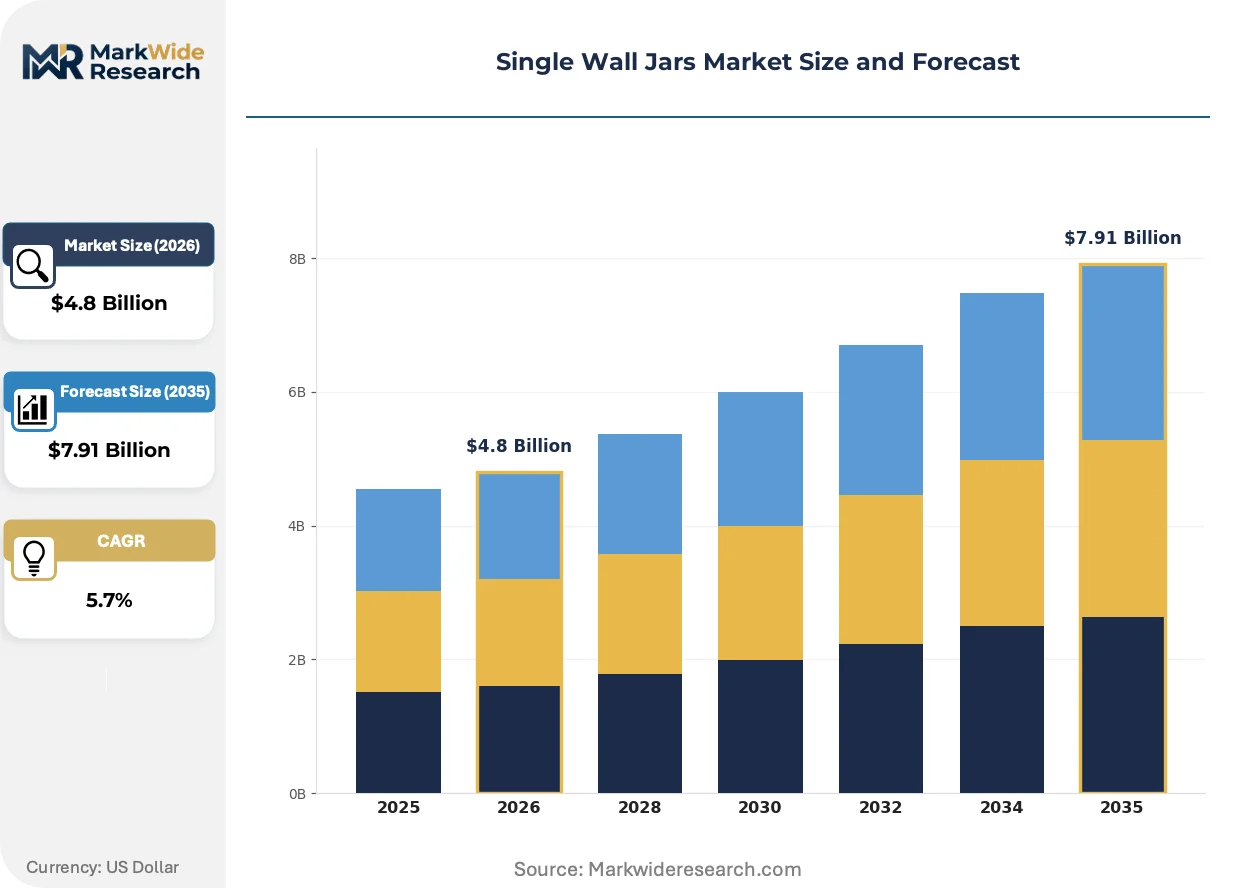
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Metal, Bamboo Closure Type: Screw Cap, Flip Top, Snap-On, Cork End User: Food Industry, Cosmetics, Pharmaceuticals, Home Use Design Style: Traditional, Modern, Vintage, Minimalist |
| Companies Covered | Berry Global, O.Berk Company, Raepak Limited, Parkway Plastics, Amcor, Alpha Packaging, Ball Corporation, Gerresheimer AG, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Wall Jars Market Evolving Landscape
Material science advances and regulatory compression are converging to redefine single wall jar performance specifications, with sustainability metrics now embedded in procurement scorecards alongside unit economics.
Mono-material PET jar construction with integrated snap-hinge closures is absorbing specification share from multi-component assemblies. Mass-market cosmetics brands in Brazil and Mexico accelerate adoption for recyclability messaging. The technology is absorbing design complexity into single-injection molding cycles, reducing assembly labor and compatibility failure modes.
REACH Annex XVII restrictions on intentionally added microplastics extend to glitter and exfoliant suspension in rinse-off cosmetics. Jar converters serving European personal care brands reformulate masterbatch additives and surface treatments. The regulation is compressing decorative options for single wall jars, pushing demand toward structural differentiation through shape and texture rather than embedded particles.
Direct-to-consumer subscription refills are restructuring primary packaging durability requirements. Beauty brands in South Korea and the United States specify heavier-wall jars designed for 8-12 refill cycles. The model concentrates demand with converters capable of dimensional precision and cosmetic-grade surface finish, displacing commodity blow molders from premium positioning.
Single Wall Jars Market Segmentation
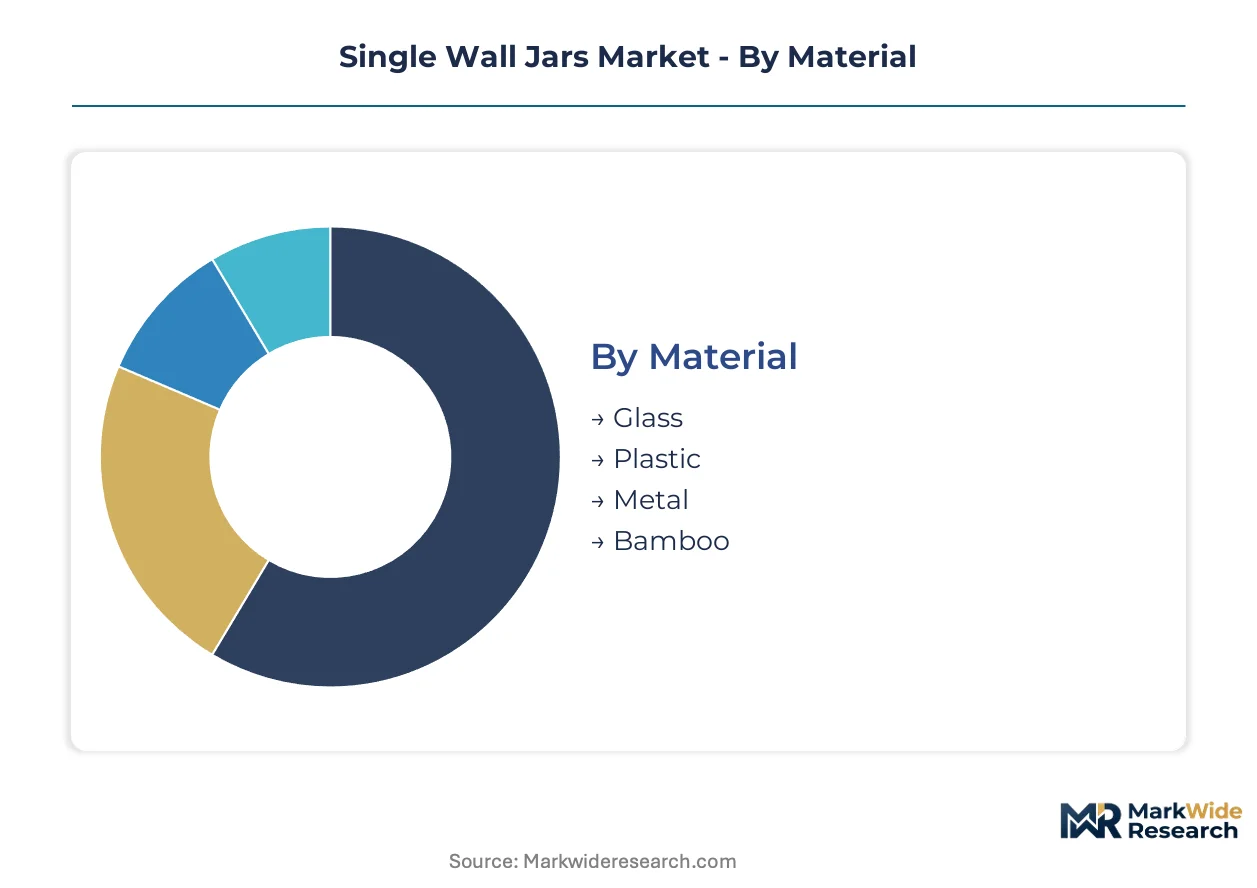
Single wall jar procurement decisions cascade through material compliance, closure compatibility, and end-use barrier requirements. Brand owners weight sustainability credentials against capping line throughput and regional regulatory acceptance.
Material:
Buyers prioritize barrier performance against carbon footprint transparency when selecting jar substrates.
- Glass:Pharmaceutical-grade borosilicate and soda-lime formulations deliver oxygen and moisture barriers for retort-stable applications. Cosmetic brands in Germany and France specify amber and cobalt variants for UV-sensitive formulations, though freight cost penalties constrain distribution radius.
- Plastic:PET, PP, and HDPE grades dominate volume through injection and extrusion blow molding flexibility. Maharashtra converters supply rPET formats for domestic cosmetics brands facing EPR compliance pressure.
- Metal:Aluminum and tin-plated steel serve niche pharmaceutical and luxury food segments requiring absolute light exclusion. Tinplate sourcing concentrates with European and Japanese rolling mills.
- Bamboo:Lignocellulosic fiber-polymer composites achieve 40-60% biobased content with injection molding compatibility. Scandinavian clean beauty brands specify these for premium skincare positioning.
Volume sits with Plastic; growth tilts toward Bamboo.
Closure Type:
Automation compatibility and consumer convenience preferences determine closure specification across filling line investments.
- Screw Cap:Threaded plastic and metal closures dominate pharmaceutical and food applications requiring reseal integrity. PP and HDPE cap resins face REACH migration testing queues for novel biobased alternatives.
- Flip Top:Hinged polypropylene closures enable single-hand dispensing for personal care and home use segments. Korean beauty brands specify these for shower-accessible packaging.
- Snap-On:Press-fit closures reduce component count for single-use cosmetic samples and promotional formats. California contract manufacturers favor these for line speed optimization.
- Cork:Natural and agglomerated cork closures serve apothecary aesthetics and sustainable brand narratives. Portuguese and Spanish cork suppliers face allocation constraints during harvest variability cycles.
Volume concentrates with Screw Cap; expansion tilts toward Cork.
End User:
Regulatory stringency and replacement cycle frequency differentiate procurement patterns across downstream verticals.
- Food Industry:Acidified preserves, sauces, and condiments demand thermal shock resistance and hermetic seal performance. FDA 21 CFR compliance dominates North American sourcing protocols.
- Cosmetics:Creams, serums, and masks drive lightweighting and decoration innovation. EU REACH Annex XVII restrictions on microplastics compress decorative masterbatch options.
- Pharmaceuticals:Topical ointments and medical devices require USP Class VI and EP 3.1.9 compliance for extractables testing. Borosilicate glass concentration in Germany creates supply vulnerability.
- Home Use:Candle, craft, and storage applications prioritize cost efficiency over barrier performance. Private label penetration concentrates volume with high-volume converters.
Food Industry holds volume share; Cosmetics climbs fastest.
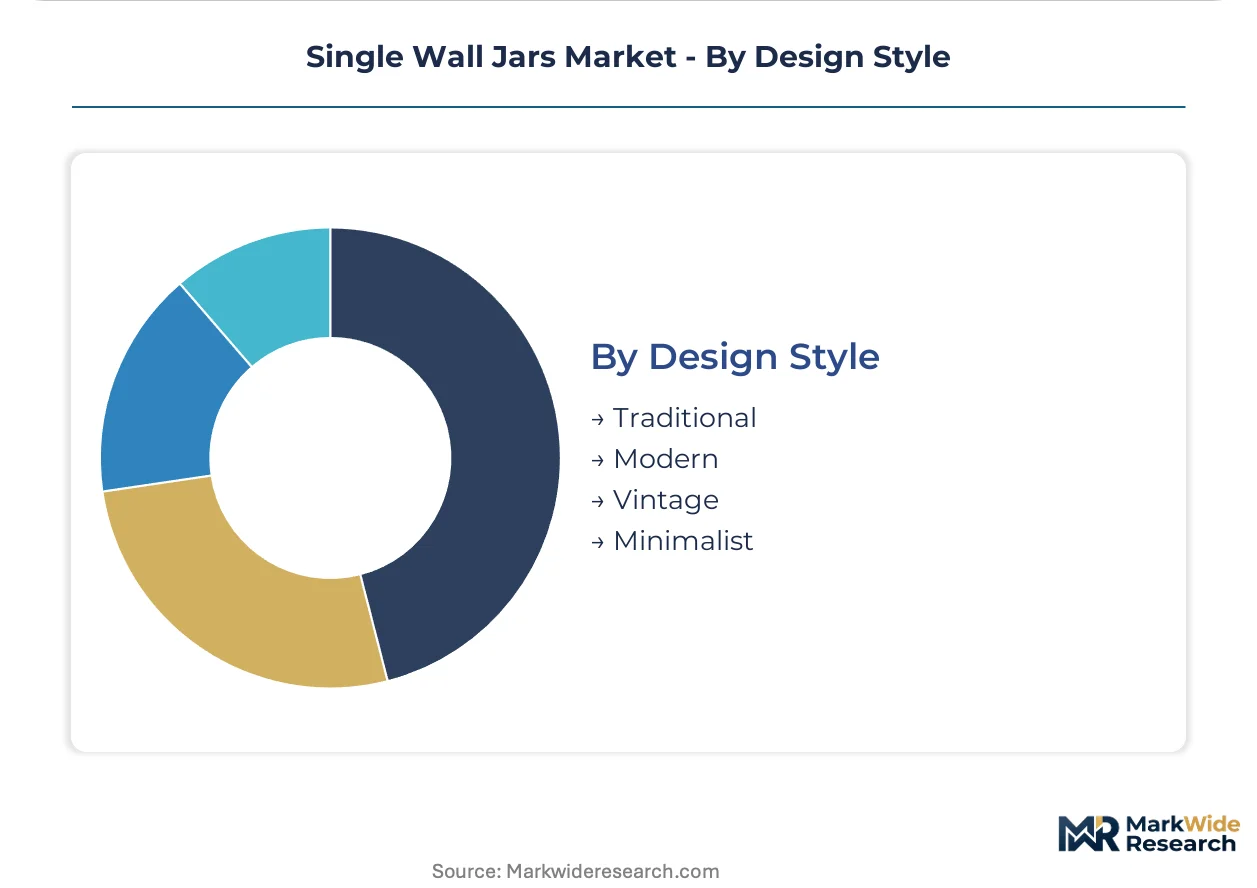
Design Style:
Shelf differentiation strategies and brand positioning hierarchies shape aesthetic investment levels.
- Traditional:Cylindrical profiles with embossed logos serve heritage food and pharmaceutical brands. Italian and French glass decorators maintain specialized furnace capacity.
- Modern:Angular geometries and matte soft-touch finishes target millennial skincare demographics. Direct-to-shape digital printing enables lot-size-one customization.
- Vintage:Apothecary-inspired profiles with cork and metal closure pairings command premium positioning. Brooklyn and Berlin indie beauty brands drive specification.
- Minimalist:Unadorned clear substrates with subtle branding respond to clean beauty transparency demands. South Korean refill subscription models specify heavier-wall formats for durability.
Traditional commands volume; Minimalist gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics brands in Germany and France are accelerating sustainable packaging procurement, while India's Maharashtra corridor attracts blow molding capacity for domestic pharmaceutical and personal care markets.
United States
California's SB 54 extended producer responsibility mandates are reshaping procurement for refillable jar systems. FDA 21 CFR compliance dominates food-contact sourcing protocols. The Pacific Northwest hosts specialized converters serving clean beauty subscription refill models.
Germany
REACH Annex XVII restrictions on intentionally added microplastics are compressing decorative masterbatch options for cosmetic jars. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds. The Rhine-Ruhr manufacturing corridor concentrates pharmaceutical-grade borosilicate glass melting capacity.
India
Maharashtra state packaging cluster incentives are attracting blow molding investment for domestic cosmetics and pharmaceutical markets. FSSAI food-contact certification requirements complicate export platform standardization. The Mumbai-Ahmedabad freight corridor enables efficient distribution to domestic and export channels.
France
Clean beauty brands in Paris and Lyon are specifying bamboo composite jars with cork closures for premium skincare positioning. ECHA migration testing queues extend 12-18 months for novel biobased resin approvals. The Île-de-France region hosts specialized glass decorators maintaining heritage furnace capacity.
South Korea
Direct-to-consumer subscription refill models are driving demand for heavier-wall jars designed for 8-12 reuse cycles. MFDS pharmaceutical packaging standards govern topical ointment specifications. Seoul-based beauty brands concentrate specification power with converters capable of cosmetic-grade surface finish.
Single Wall Jars Market Competitive Landscape
European producers anchor premium glass and compliance-heavy tiers; North American specialists hold scale-driven plastic conversion positions. The vendor base separates into three strata: integrated resin-to-jar conglomerates, regional blow molding specialists, and niche sustainable material innovators. Two dominant competitive moves are reshaping positioning: captive resin compounding investments to manage recycled content cost volatility, and digital printing direct-to-shape partnerships to capture short-run customization demand.
Among Germany-based fabricators, Gerresheimer AG occupies a position exemplifying pharmaceutical-grade glass specialization. Berry Global and Amcor represent the integrated resin-to-jar conglomerate archetype across North American and Asia-Pacific footprints. These three anchors illustrate the geographic and capability splits defining competitive rivalry.
| Leading Market Players |
|---|
| Berry Global |
| O.Berk Company |
| Raepak Limited |
| Parkway Plastics |
| Amcor |
| Alpha Packaging |
| Ball Corporation |
| Gerresheimer AG |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade borosilicate glass certification tiers create sharp cost divergence between premium cosmetic positioning and commodity food preservation, with German and Indian melting capacity commanding price premiums while Maharashtra blow molders compete on rPET volume scale. REACH compliance investments and recycled content mandates reshape procurement economics, forcing converters to absorb migration testing costs or pass through resin substitution premiums.
Pricing Analysis
Volume concentration in standard-grade PET and PP jars runs on thin margins, while pharmaceutical-grade borosilicate and bamboo composite formats sustain pricing power through certification scarcity and biobased content premiums. Price differentiation hinges on EU 10/2011 migration testing completion and FSSAI food-contact certification status. Cost compression in virgin resin tiers intensifies as post-consumer recycled flake supply bottlenecks trigger price inversions. Contract manufacturers in California and Seoul demonstrate highest price sensitivity; luxury clean beauty brands in Scandinavia and Paris show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cosmetics brand demand, while specialty distributors serve indie apothecary labels requiring cork closure allocation management. Manufacturing gravity centers on Germany's Rhine-Ruhr corridor for pharmaceutical glass, India's Maharashtra state for blow molded plastics, and Portugal for cork harvesting. Raw material flows draw from Saudi petrochemical feedstocks, German specialty glass sand deposits, and Southeast Asian lignocellulosic fiber sources. Single-source vulnerability concentrates in pharmaceutical-grade borosilicate melting capacity. Distribution runs through Mumbai-Ahmedabad freight corridors for Asia-Pacific reach and Rhine-Ruhr logistics nodes for European coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material PET construction with integrated snap-hinge closures is displacing multi-component assemblies, while bamboo-lignocellulosic composites erode conventional plastic specification share in premium skincare.
For Market Incumbents: Extend captive resin compounding investments to buffer post-consumer recycled price volatility and secure REACH-compliant material pipelines. Deepen backward integration into rPET flake processing to defend margin position against virgin-to-recycled price inversions. Accelerate digital printing direct-to-shape partnerships to capture lot-size-one customization demand from Korean and California subscription beauty brands. For New Entrants and Emerging Players: Launch via halal-certified manufacturing partnerships to access Indonesia's cosmetics production gap, where local blow molding capacity trails brand demand. Target Scandinavian clean beauty brands seeking bamboo composite jars with cork closures, a segment where Portuguese cork allocation constraints create entry windows. Pursue Maharashtra state packaging cluster incentives to establish cost-competitive rPET supply for domestic Indian pharmaceutical markets. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty glass decorators with heritage furnace capacity and digital printing equipment partnerships. Five-to-ten year viability favors converters with demonstrated EU 10/2011 compliance track records and refillable jar system infrastructure. Watch California SB 54 fee reduction qualification rates as the signal for durable primary packaging demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Investment | Berry Global's European footprint demonstrates cost predictability under REACH resin substitution pressure. |
| Digital Printing Direct-to-Shape Partnership | UV-cured inkjet systems enable Seoul-based beauty brands to bypass silkscreen minimums for subscription refills. |
| Halal-Certified Manufacturing Expansion | Indonesia's cosmetics production gap outpaces local blow molding capacity for Southeast Asian distribution. |
| Refillable Jar System Infrastructure | California SB 54 fee reductions reward brands with take-back programs and durable primary packaging. |
| Pharmaceutical-Grade Borosilicate Capacity Addition | Gerresheimer AG's German melting capacity anchors premium glass demand amid supply concentration risk. |
Research Methodology
Independent corroboration across regulatory filings, customs trade records, and converter capacity disclosures underwrites the qualitative findings in this study. Primary interviews with blow molding plant managers, cosmetics brand procurement leads, pharmaceutical packaging engineers, and cork supplier harvest coordinators combined with secondary validation from ECHA substance registrations, FSSAI food-contact additive lists, and EU Packaging and Packaging Waste Directive implementation timelines. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition across material substitution trajectories, regulatory compliance deadlines, and regional manufacturing cluster incentives structures the analytical framework. Segmentation dimensions include material substrate, closure type, end-use vertical, and design style, with regional regulatory cluster effects modeled separately. CAGRs derive from installed capacity expansion schedules, brand sustainability commitment timelines, and substitution elasticity between single wall and multi-layer formats. Migration testing laboratory queue lengths and recycled resin price spread volatility inform near-term trajectory adjustments.
REACH Annex XVII restriction scope expansion, post-consumer collection infrastructure investment shortfalls, and pharmaceutical-grade glass capacity maintenance cycles are the dominant revision risks. Forecasts reflect assumptions regarding regulatory harmonization timelines and brand owner qualification acceleration patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Foldable Steel Containers Market
Containers
Trigger Sprayer Market
Containers
Stack and Nest Containers Market
Containers
Oblong Jar Market
Containers
PET Containers Market
Containers
Global Food Storage Container Market
Containers
North America Insulated Shipping Containers Market
Containers
Asia and Africa Food Cans Market
Containers
Light Resistant Containers Market
Containers
PET Hinged Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
PS Containers Market
Containers
Oblong Container Market
Containers
Containerboard Market
Containers
Foldable Large Containers Market
Containers
Compartment Trays Market