
 EMEA Container Technology Market | 2026-2036
EMEA Container Technology Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Container Technology Market Analysis
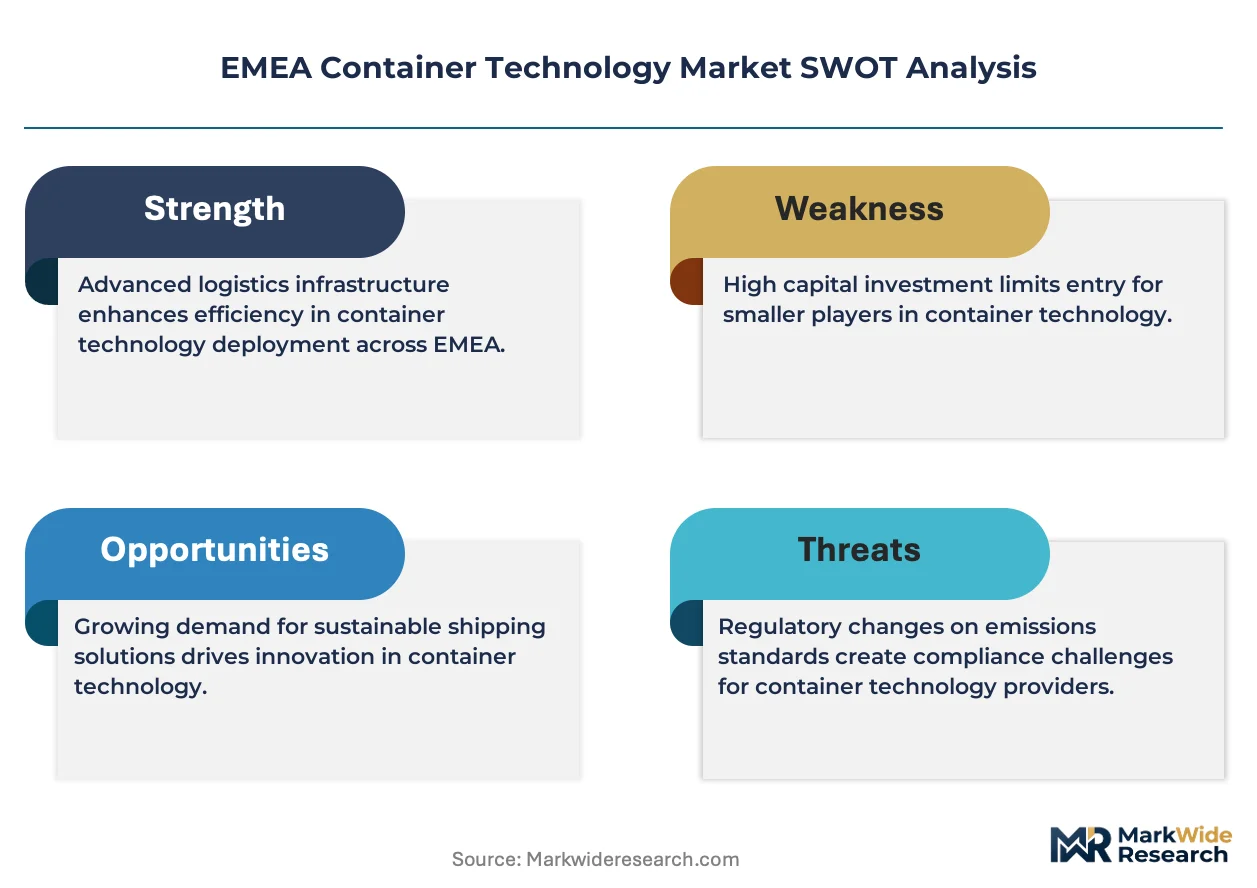
Enterprise-grade security certification is bifurcating the EMEA container landscape into sovereign-compliant and standard deployment tiers. Docker Inc. leverages its open-source foundation to anchor developer mindshare across European fintech clusters. Red Hat competes through its OpenShift platform, sustaining premium positioning in regulated German and French enterprise accounts. VMware differentiates by extending hybrid cloud orchestration into Middle Eastern telecom operators seeking data residency guarantees.
Container technology encapsulates application code with dependencies into portable, isolated runtime units deployable across heterogeneous infrastructure, typically measured by startup latency under one second and resource overhead below ten percent versus virtual machines. The technology serves industrial and commercial purposes by enabling consistent software delivery from development through production without environment drift. Docker and Kubernetes deployments dominate the technology dimension, with Kubernetes capturing the fastest expansion as enterprises standardize on cloud-native orchestration. Hybrid cloud models lead the deployment dimension, reflecting EMEA organizations' need to balance EU data sovereignty requirements against public cloud elasticity, while full integration solutions command margin premiums by reducing operational complexity for BFSI end users.
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification framework are reshaping container architecture requirements, mandating audit trails, data localization, and explainability hooks for AI-infused workloads. EMEA national regulators in France, Germany, and the UAE are layering sector-specific guidelines atop these baseline requirements, fragmenting compliance templates across jurisdictions. Stakeholders must monitor evolving certification schemes and decide whether to build multi-tenant sovereign platforms or partner with established regional cloud providers holding pre-cleared compliance status.
Market Dynamics
Sovereign data residency mandates are fragmenting container deployment architectures across European financial centers, forcing institutions to maintain parallel infrastructure stacks that satisfy divergent national interpretations of GDPR and the EU AI Act.
Growth Catalysts
- EU AI Act risk-classification framework:Financial services firms in Frankfurt and Paris are retrofitting container pipelines with explainability hooks and audit trails to satisfy high-risk system requirements, accelerating demand for compliant orchestration platforms.
- Factory-floor analytics:German automotive manufacturers are deploying private Kubernetes clusters at industrial scale to process real-time telemetry from connected production lines, creating a concentrated demand pocket for edge-optimized container runtimes.
- Dubai International Financial Centre:The UAE's data localization policies are attracting regional headquarters deployments, with Middle Eastern banks building sovereign cloud container estates to serve Gulf Cooperation Council markets.
Market Restraints
- Specialized talent scarcity:Certified Kubernetes administrators command premium compensation in London and Frankfurt, inflating operational costs for container platform teams beyond budgeted run rates.
- Silicon supply concentration:Accelerated computing hardware for AI-infused container workloads remains concentrated with limited foundry capacity, creating procurement bottlenecks for European enterprises scaling inference clusters.
- Fragmented national implementations:France's CNIL, Germany's BSI, and the UAE's NESA have issued divergent technical guidance on container security baselines, multiplying compliance engineering overhead for multi-jurisdictional deployments.
Strategic Opportunities
- Edge container orchestration:Industrial sites across the Ruhr Valley are deploying lightweight K3s distributions on factory floors, opening a whitespace segment between hyperscale cloud and traditional embedded systems.
- Confidential computing integration:Hardware-based trusted execution environments from ARM and Intel are converging with container runtimes to enable encrypted-in-use processing for sensitive healthcare and financial data.
- Sector-specific sovereign clouds:French aerospace and defense contractors are procuring cleared container platforms that pre-integrate ANSSI certification requirements, creating templateable offerings for regulated European verticals.
Industry Challenges
- Legacy mainframe integration:Core banking systems running on IBM z/OS architectures in London and Zurich require complex sidecar patterns to interoperate with cloud-native container services, extending project timelines.
- Cross-border data flow engineering:Institutions operating across UK-EU boundaries post-Brexit must architect container traffic routing that satisfies divergent adequacy determinations without duplicating entire application estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Container Technology Market |
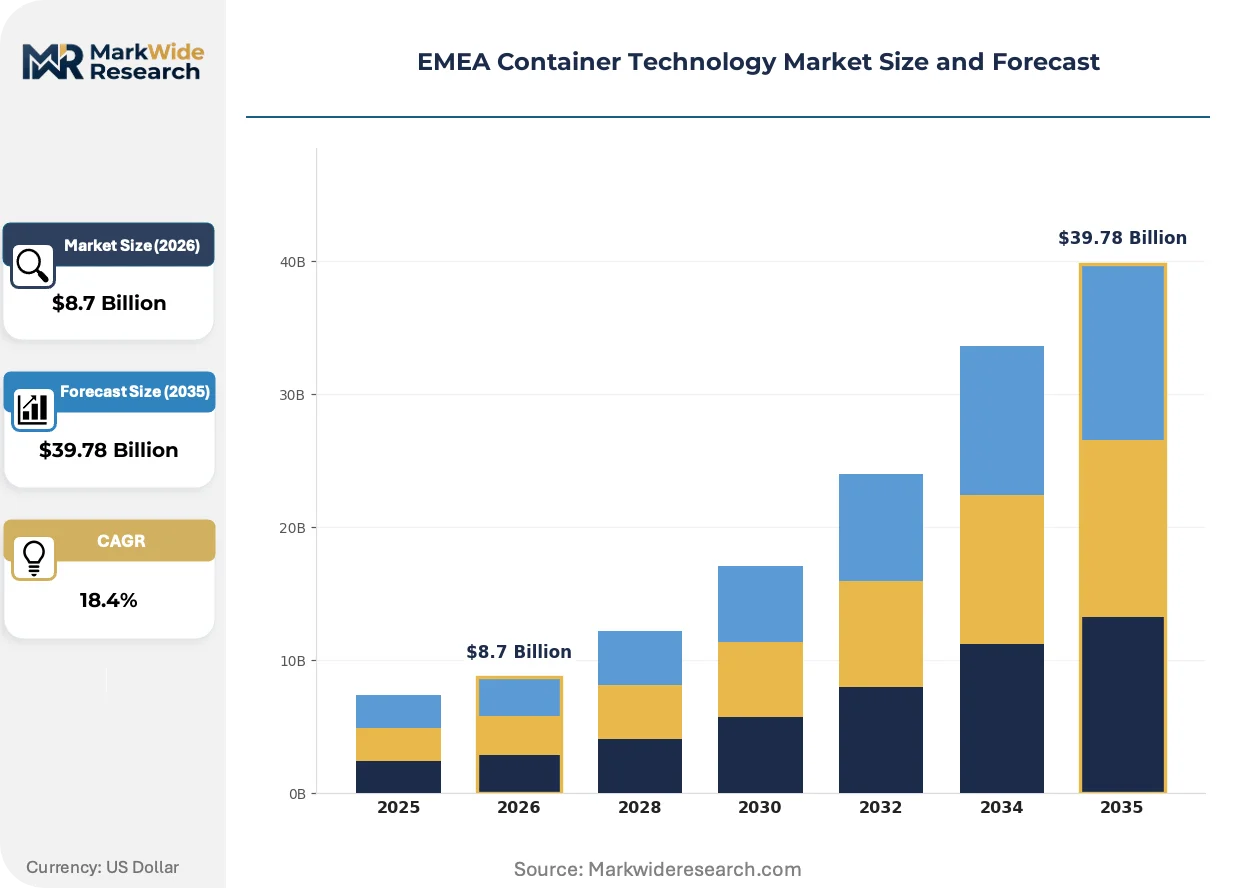
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Docker, Kubernetes, OpenShift, Mesos End User: IT Services, Telecommunications, BFSI, Retail Integration Level: Full Integration, Partial Integration, Open Integration, Standalone |
| Companies Covered | Docker Inc., Amazon Web Services, Microsoft, IBM Corporation, Cisco Systems, Red Hat, VMware, Google Cloud, CoreOS, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Container Technology Market Emerging Trajectories
Container runtime architectures are bifurcating between lightweight edge distributions and hardened sovereign platforms, with regulatory pressure acting as the primary forcing function for technical differentiation across European deployment scenarios.
WebAssembly (Wasm) runtimes are displacing traditional container engines for microservice workloads requiring sub-100-millisecond cold start latency. Frankfurt-based fintechs are piloting Wasm modules for payment processing functions that must scale to zero between batch cycles. The structural consequence is compressing the addressable market for conventional containerd deployments in latency-sensitive financial applications.
The EU AI Act's transparency obligations are mandating container image provenance tracking from build pipeline through production runtime. Industrial manufacturers in Stuttgart are embedding software bill of materials (SBOM) generation into CI/CD workflows to satisfy upcoming conformity assessment requirements. Medical device developers face the steepest compliance burden, with notified bodies requiring container-level evidence for algorithmic risk classification.
Buyers are consolidating vendor relationships around platforms that bundle Kubernetes distribution with pre-certified compliance modules. Large German insurers are displacing point-solution container tools with integrated stacks that embed BSI technical guidelines. The shift is most visible in DAX-listed enterprises, where procurement teams prioritize audit-ready deployments over best-of-breed component flexibility.
EMEA Container Technology Market Segmentation
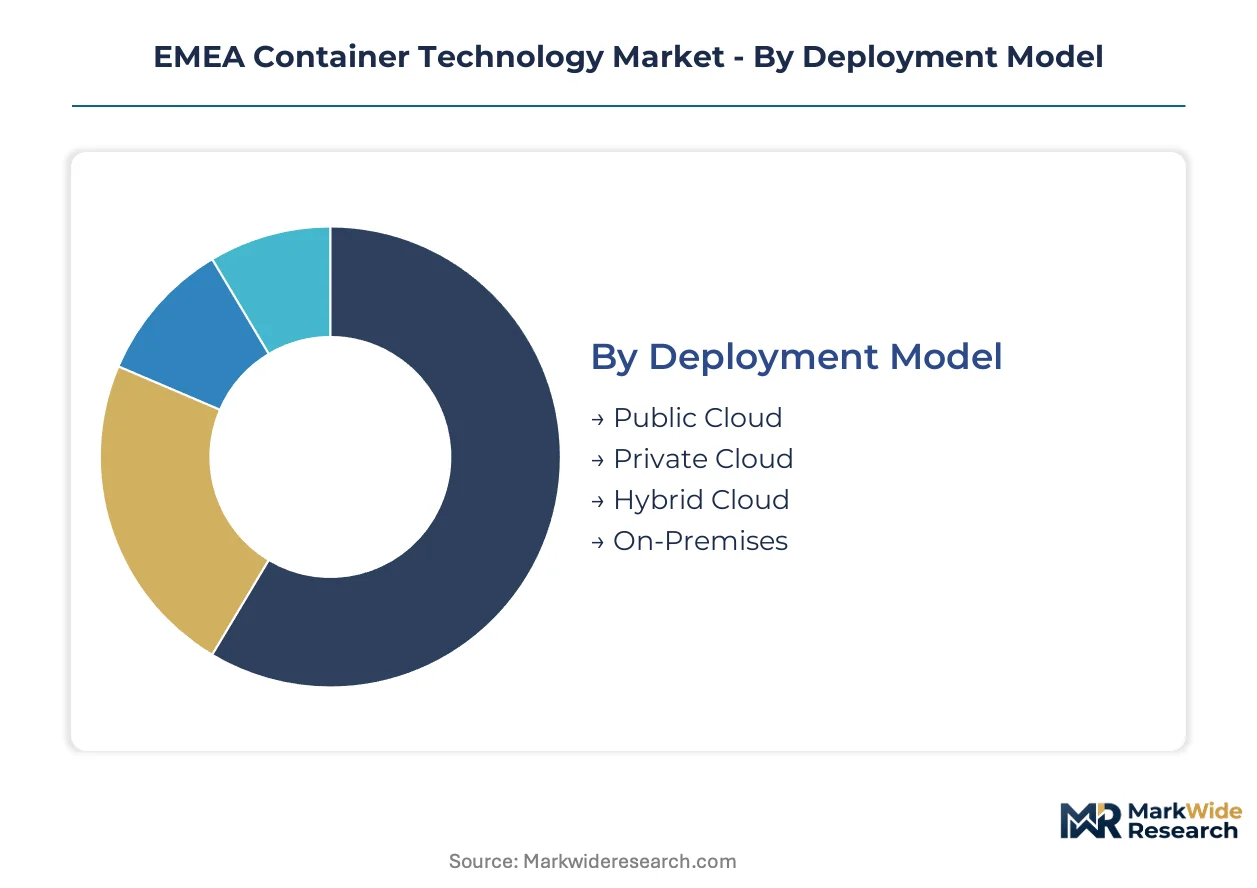
Regulatory fragmentation across EMEA jurisdictions is forcing buyers to select container architectures based on data residency requirements rather than pure technical merit. Deployment models, orchestration technologies, and integration approaches now map directly to compliance tiers, reshaping how procurement teams evaluate vendor offerings.
Deployment Model:
GDPR enforcement intensity and sector-specific mandates from Germany's BSI, France's CNIL, and the UAE's NESA are bifurcating infrastructure choices between sovereign-compliant and standard tiers.
- Public Cloud:Elastic container services from hyperscalers dominate development workloads and non-sensitive batch processing. Frankfurt-based fintechs leverage public Kubernetes clusters for sandbox environments while maintaining strict data classification protocols.
- Hybrid Cloud:Workload portability between on-premises sovereign zones and burst capacity in public infrastructure addresses the core tension facing London and Dubai financial institutions. German automotive manufacturers deploy this model to keep factory-floor telemetry local while training ML models in scalable cloud environments.
- Private Cloud:Dedicated container estates satisfy the strictest interpretations of EU AI Act risk classification for high-risk automated decision systems.
- On-Premises:Air-gapped deployments persist in French aerospace and defense supply chains where ANSSI certification mandates physical infrastructure control.
Established volume favors Hybrid Cloud; emerging adoption favors Private Cloud as AI Act enforcement tightens.
Technology:
Developer familiarity and enterprise support contracts are concentrating procurement around two dominant platforms, with niche alternatives serving specialized latency or legacy requirements.
- Kubernetes:The de facto orchestration standard for production container fleets, now embedded in BSI technical guidelines for German federal IT procurement. Stuttgart industrial clusters standardize on upstream Kubernetes for factory-floor analytics pipelines requiring precise pod scheduling.
- Docker:Container runtime and developer tooling retain dominant mindshare in European fintech incubators and CI/CD pipelines, though production orchestration increasingly migrates to Kubernetes control planes.
- OpenShift:Red Hat's enterprise distribution captures regulated French and German enterprise accounts seeking pre-certified compliance modules.
- Mesos:Legacy deployments persist in early-adopter telecom operators across the Middle East with entrenched operational playbooks.
Kubernetes captures the steepest expansion trajectory as standardization reduces operational complexity; Docker sustains the broadest developer footprint.
End User:
Sector-specific compliance engineering requirements are concentrating vendor R&D investment in financial services and telecommunications verticals.
- BFSI:Core banking modernization in London, Frankfurt, and Dubai drives demand for sovereign-compliant container platforms with embedded audit trails. High-risk AI system classification under the EU AI Act mandates explainability hooks in containerized credit decisioning workflows.
- Telecommunications:UAE and Saudi operators build sovereign cloud container estates to satisfy data residency guarantees for government and enterprise customers. Edge-optimized distributions support 5G network function virtualization at scale.
- IT Services:Managed container platform offerings from European systems integrators bundle compliance engineering for mid-market clients lacking in-house Kubernetes expertise.
- Retail:Seasonal demand spikes and payment processing latency requirements drive adoption of serverless container patterns in ecommerce platforms.
BFSI commands premium pricing for certified deployments; telecommunications is climbing fastest on infrastructure modernization cycles.
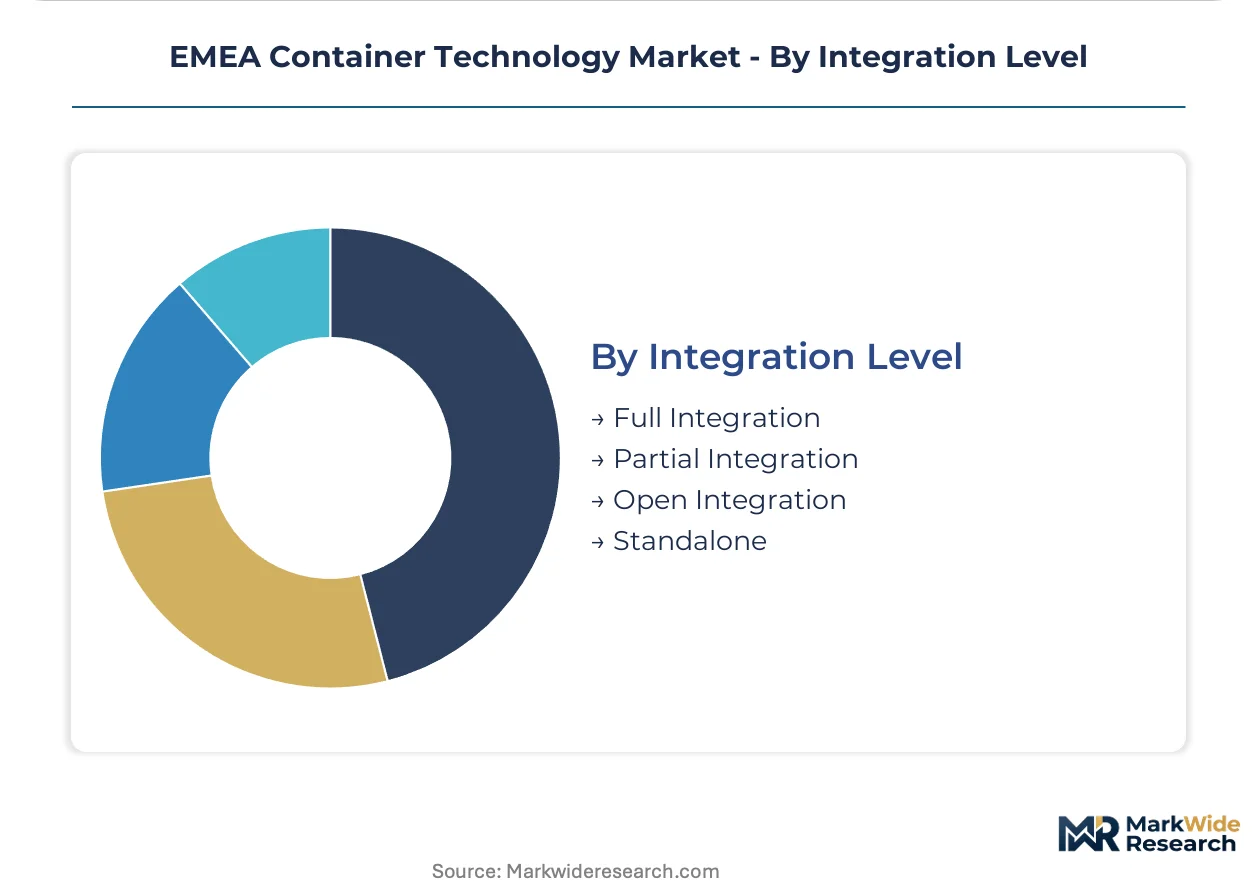
Integration Level:
Procurement teams are consolidating around bundled platforms that reduce operational engineering burden, displacing best-of-breed component assembly.
- Full Integration:Kubernetes distribution pre-packaged with CI/CD, observability, and compliance modules captures DAX-listed German enterprises prioritizing audit-ready deployments over configuration flexibility.
- Partial Integration:Selective platform components allow specialized teams to retain preferred toolchain elements while standardizing core orchestration.
- Open Integration:Maximum component flexibility persists in technology-forward fintechs with dedicated platform engineering capabilities.
- Standalone:Single-purpose container runtimes address edge computing constraints in industrial IoT gateways with severe resource limitations.
Full Integration claims expanding share among risk-averse regulated buyers; Open Integration retains footholds in technically sophisticated early adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container technology supply concentrates in Western European financial centers and German industrial clusters, with emerging deployment gravity shifting toward Gulf sovereign cloud zones. National data residency mandates fragment procurement patterns across jurisdictions.
Germany
Automotive manufacturers in Stuttgart and Munich deploy private Kubernetes clusters for factory-floor analytics, processing real-time telemetry from connected production lines. Germany's BSI technical guidelines mandate container security baselines for federal IT procurement. The Ruhr Valley industrial corridor adopts lightweight K3s distributions at scale, bridging hyperscale cloud and embedded systems.
United Kingdom
London's financial services firms accelerate container adoption for core banking platform modernization, retrofitting pipelines with audit trails for regulatory compliance. Post-Brexit cross-border data flow requirements force complex container traffic routing between UK and EU infrastructure estates. Canary Wharf institutions maintain parallel stacks to satisfy divergent adequacy determinations.
France
Paris-based fintechs embed explainability hooks into containerized credit decisioning workflows to satisfy EU AI Act high-risk system classification. ANSSI certification requirements drive French aerospace and defense contractors toward air-gapped, pre-cleared container platforms. Île-de-France enterprises consolidate procurement around bundled platforms with embedded compliance modules.
United Arab Emirates
Dubai International Financial Centre attracts regional headquarters deployments as UAE data localization policies strengthen. Middle Eastern banks build sovereign cloud container estates to serve Gulf Cooperation Council markets without data egress. NESA technical guidance on container security baselines shapes procurement specifications for government and enterprise customers.
Switzerland
Zurich's private banking sector grapples with legacy mainframe integration, deploying complex sidecar patterns to connect IBM z/OS architectures with cloud-native container services. Swissmedic requirements for medical device software traceability extend into container image provenance tracking. The Zug crypto valley cluster experiments with confidential computing integration for sensitive financial data processing.
EMEA Container Technology Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the EMEA container landscape. The vendor base stratifies into three tiers: open-source foundation providers anchoring developer mindshare, enterprise distribution vendors capturing regulated accounts through pre-certified compliance modules, and hyperscale cloud operators leveraging elastic infrastructure scale. Dominant competitive moves include strategic partnerships with national cloud providers holding pre-cleared sovereign status and portfolio diversification into edge-optimized runtime distributions.
Within the open-source archetype, Docker Inc. occupies a foundational position anchoring European fintech developer communities. Red Hat and VMware exemplify the enterprise distribution tier, with the former sustaining premium positioning in regulated German and French accounts and the latter extending hybrid cloud orchestration into Middle Eastern telecom operators seeking data residency guarantees. These three entities represent the structural poles around which procurement decisions in London, Frankfurt, and Dubai currently organize.
| Leading Market Players |
|---|
| Docker Inc. |
| Amazon Web Services |
| Microsoft |
| IBM Corporation |
| Cisco Systems |
| Red Hat |
| VMware |
| Google Cloud |
| CoreOS |
| Others |
Supply Flow & Price Mechanics
Long-term enterprise licensing contracts with embedded compliance modules lock in both supply access and price visibility for German automotive manufacturers and French aerospace contractors navigating BSI and ANSSI certification requirements. These multi-year agreements insulate buyers from spot-market volatility in specialized Kubernetes distributions while anchoring vendor revenue predictability across the EMEA container technology landscape.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across the EMEA container technology market, separating sovereign-compliant platforms with embedded audit trails from standard deployment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with premium tiers capturing DAX-listed enterprises requiring pre-cleared BSI alignment. Cost compression in standard tiers is intensifying because hyperscaler elastic container services commoditize baseline orchestration capabilities. Mid-market IT services firms exhibit the highest price sensitivity, while regulated BFSI institutions in London and Dubai prioritize audit-ready deployments over unit economics.
Supply Chain Analysis
Inventory lead times for AI-accelerated computing hardware extend procurement cycles for European enterprises scaling inference clusters, constraining rapid platform expansion. Supply concentrates in the United States for advanced semiconductors, Taiwan for foundry capacity, and Germany for industrial edge hardware, creating geographic dependencies that amplify vulnerability to single-source foundry bottlenecks. Container runtime software draws from open-source upstream repositories with distributed contributor bases, while distribution runs through hyperscaler marketplaces and direct enterprise sales channels serving Frankfurt and Paris financial centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMEA container technology market represents a high-growth disruption as sovereign cloud mandates and EU AI Act enforcement rearchitect procurement priorities across financial and industrial verticals.
For Market Incumbents: Secure pre-cleared compliance status with Germany's BSI and France's ANSSI to defend against emerging sovereign cloud specialists capturing regulated accounts. Anchor developer mindshare through open-source foundation contributions while embedding vertical-specific modules for factory-floor analytics in Stuttgart industrial clusters. Capacity addition in UAE sovereign zones addresses data residency guarantees for Gulf Cooperation Council banking estates.
For New Entrants and Emerging Players: Lead with edge-optimized K3s distributions targeting Ruhr Valley manufacturing sites where lightweight orchestration bridges hyperscale cloud and embedded systems. The whitespace between traditional industrial control systems and full Kubernetes deployments offers the most penetrable segment for specialized runtime vendors. A sector-specific go-to-market angle through German automotive supplier networks accelerates factory-floor validation cycles.
For Investors and Strategic Acquirers: Container platform engineering boutiques with embedded GDPR compliance modules represent the most attractive acquisition target archetype for hyperscalers seeking European sovereign cloud credibility. Long-term viability hinges on sustained regulatory fragmentation across EMEA jurisdictions that preserves premium pricing for certified deployments. The signal to watch is ANSSI and BSI certification timeline acceleration that would compress competitive moats for pre-cleared vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Establishes data residency guarantees for UAE and German financial institutions under NESA and BSI guidelines. |
| Edge Runtime Distribution | Captures factory-floor analytics demand from Stuttgart automotive manufacturers deploying lightweight K3s clusters. |
| Confidential Computing Integration | Enables encrypted-in-use processing for Swiss private banking clients handling sensitive z/OS mainframe data. |
| Compliance Module Pre-Certification | Reduces procurement friction for French aerospace contractors requiring ANSSI-cleared container platforms. |
| Managed Platform Service Launch | Addresses Kubernetes talent scarcity in London through bundled operational support for mid-market BFSI clients. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the EMEA container technology ecosystem, including platform engineering directors at Frankfurt fintechs, cloud procurement officers at DAX-listed industrial enterprises, Kubernetes administrators in London financial services, and sovereign cloud architects at UAE telecommunications operators. Secondary validation drew from hyperscaler capex disclosures, EU regulatory filings documenting GDPR enforcement actions, BSI technical guideline publications, and container runtime repository contribution analytics. Bottom-up deployment volume estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled deployment model transitions, orchestration technology standardization curves, and end-user vertical penetration patterns specific to BFSI modernization cycles and industrial edge analytics adoption. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion trajectories. Forecast inputs incorporated AI Act implementation timeline assumptions and silicon supply constraint persistence indicators affecting accelerated computing procurement.
The analysis sits within stated boundaries; outcomes outside sustained regulatory fragmentation or accelerated sovereign cloud standardization would require recalibration. Forecasts reflect documented assumptions regarding GDPR enforcement intensity and EU AI Act risk classification adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stackable Container Market
Containers
Foldable Large Containers Market
Containers
ISO Container Market
Containers
Stock Clamshell Packaging Market
Containers
Screw Top Pails Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Snap-Lock Container Market
Containers
Conipack Pails Market
Containers
Hinged Lid Tins Market
Containers
North America Insulated Shipping Containers Market
Containers
Flexible Water Tanks Market
Containers
Metal Cans and Glass Jars Market
Containers
Die Cut Display Container Market
Containers
Oblong Jar Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Popcorn Containers Market