
 Brazil Gluten-Free Food and Beverages Market | 2026-2036
Brazil Gluten-Free Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Gluten-Free Food and Beverages Market Outlook
Supermarket shelf allocation is tilting toward dedicated gluten-free sections in Brazil's major retail chains. Dr. Schar leverages its European manufacturing heritage to sustain premium positioning in Brazilian health food stores. General Mills Inc. competes through scaled distribution of ready-to-eat cereal alternatives across Carrefour and GPA networks. Nestlé S.A. anchors its portfolio with rice flour-based snack lines that occupy expanding shelf space in the Southeast.
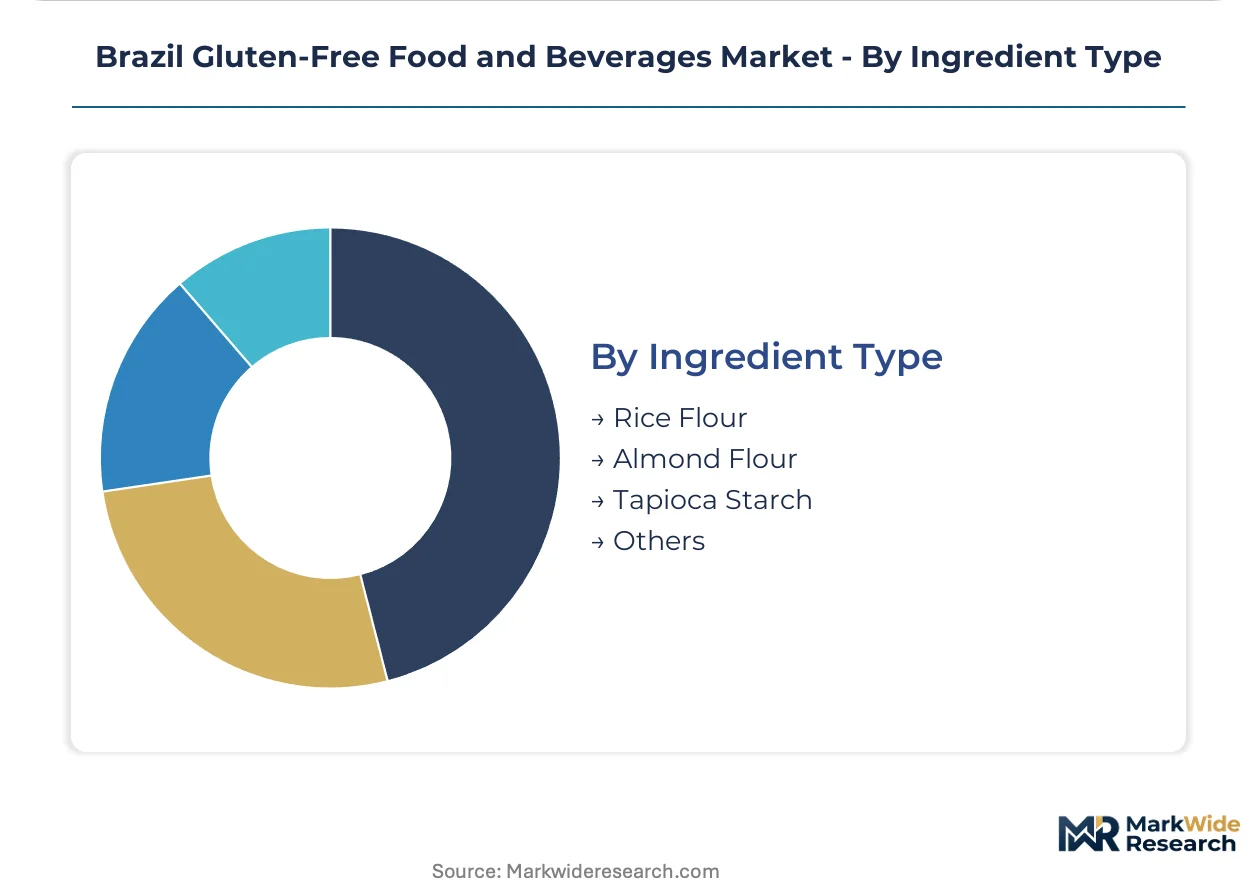
Gluten-free food and beverages comprise products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or almond flour to achieve comparable texture and shelf stability. These formulations serve celiac patients, diagnosed gluten-intolerant consumers, and health-aware buyers seeking reduced-inflammatory dietary patterns. Bakery products dominate current revenue contribution due to bread and cake substitution being the most entrenched consumer habit, while beverages represent the fastest-expanding margin pool as functional hydration SKUs gain traction among athletes. The ingredient dimension shows tapioca starch sustaining cost-competitive positioning against pricier almond flour alternatives, concentrating volume in family-oriented SKUs.
ANVISA mandates strict gluten threshold labeling for packaged foods, compelling manufacturers to invest in certified clean-room production or risk market exclusion. The Brazilian Ministry of Agriculture's inspection protocols for imported specialty grains add compliance layers that favor domestic millers with established traceability systems. Stakeholders must monitor how proposed updates to Mercosur food standards could harmonize—or fragment—cross-border certification requirements affecting raw material sourcing strategies.
Market Dynamics
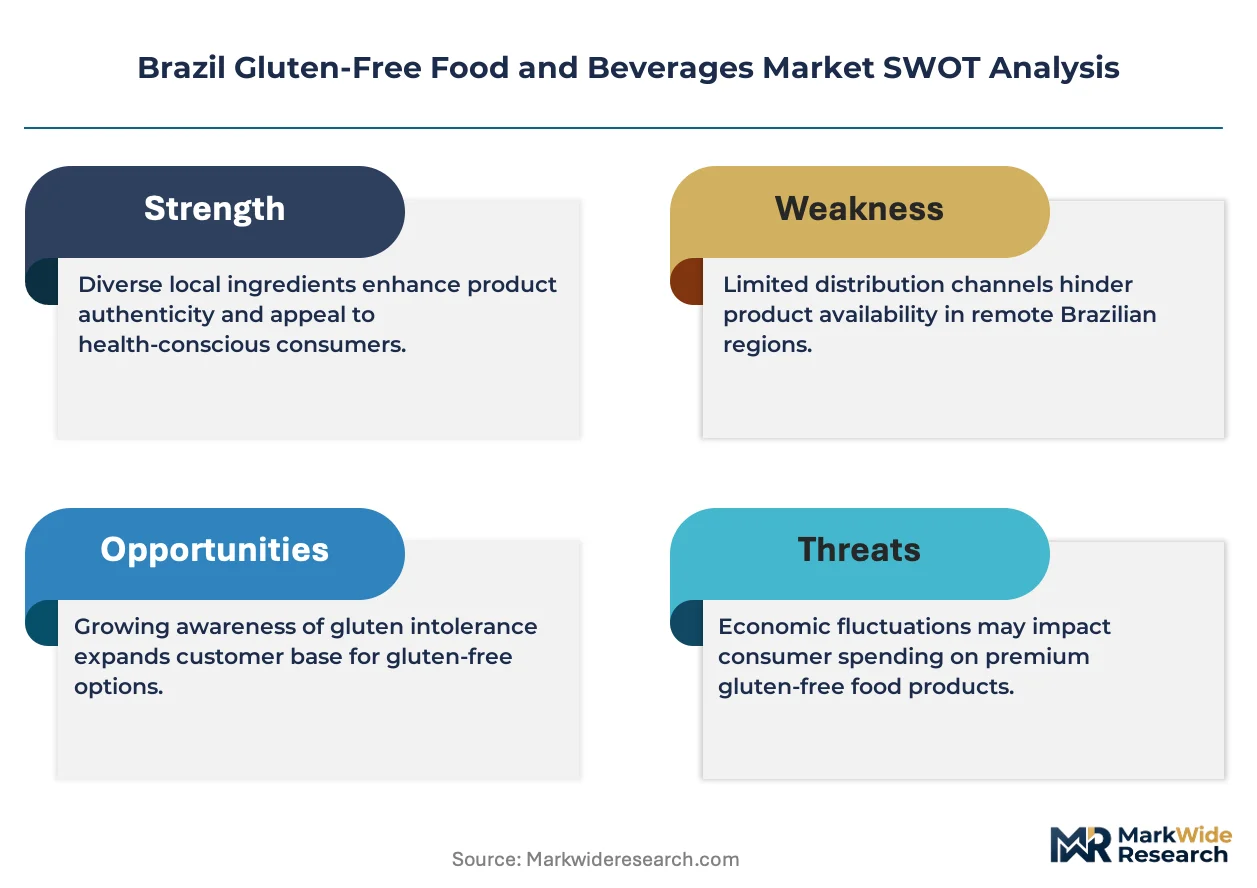
ANVISA's allergen labeling enforcement is compressing formulation timelines and forcing certified production investments across Brazilian gluten-free manufacturers, reshaping competitive entry barriers.
Growth Catalysts
- Celiac disease diagnosis expansion:Public health campaigns in São Paulo and Rio de Janeiro are expanding patient identification, creating pull-through demand for certified SKUs in pharmacy and retail channels.
- ANVISA Resolution RDC 26/2015:Mandatory gluten threshold labeling below 20 ppm creates regulatory clarity that rewards compliant domestic millers with traceability systems.
- Southeast urban retail density:Specialty store networks in Belo Horizonte and Curitiba are deepening shelf access for certified gluten-free bakery alternatives.
Market Restraints
- Tapioca starch price volatility:Cassava harvest fluctuations in Brazil's Center-West region compress margins on family-oriented SKUs dependent on this input.
- Import inspection protocols:The Brazilian Ministry of Agriculture's traceability requirements for specialty grains create compliance friction that disadvantages smaller importers.
- Almond flour cost premium:Dollar-denominated nut flour pricing limits premium positioning to affluent urban segments, constraining mass-market penetration.
Strategic Opportunities
- Northeast urban expansion:Salvador and Recife represent underpenetrated demand pools where health-conscious middle-class formation outpaces certified SKU availability.
- Functional hydration beverages:Athlete-targeted electrolyte and protein-fortified drinks create margin expansion potential beyond saturated bakery categories.
- Mercosur harmonization prospects:Proposed cross-border certification alignment could unlock Argentine and Uruguayan sourcing for Brazilian manufacturers with compliant systems.
Industry Challenges
- Clean-room capex requirements:ANVISA-mandated certified production environments demand facility investments that strain mid-tier manufacturer balance sheets.
- Gluten-free certification timeline:Third-party laboratory validation cycles for new product launches extend time-to-shelf beyond conventional food innovation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Gluten-Free Food and Beverages Market |
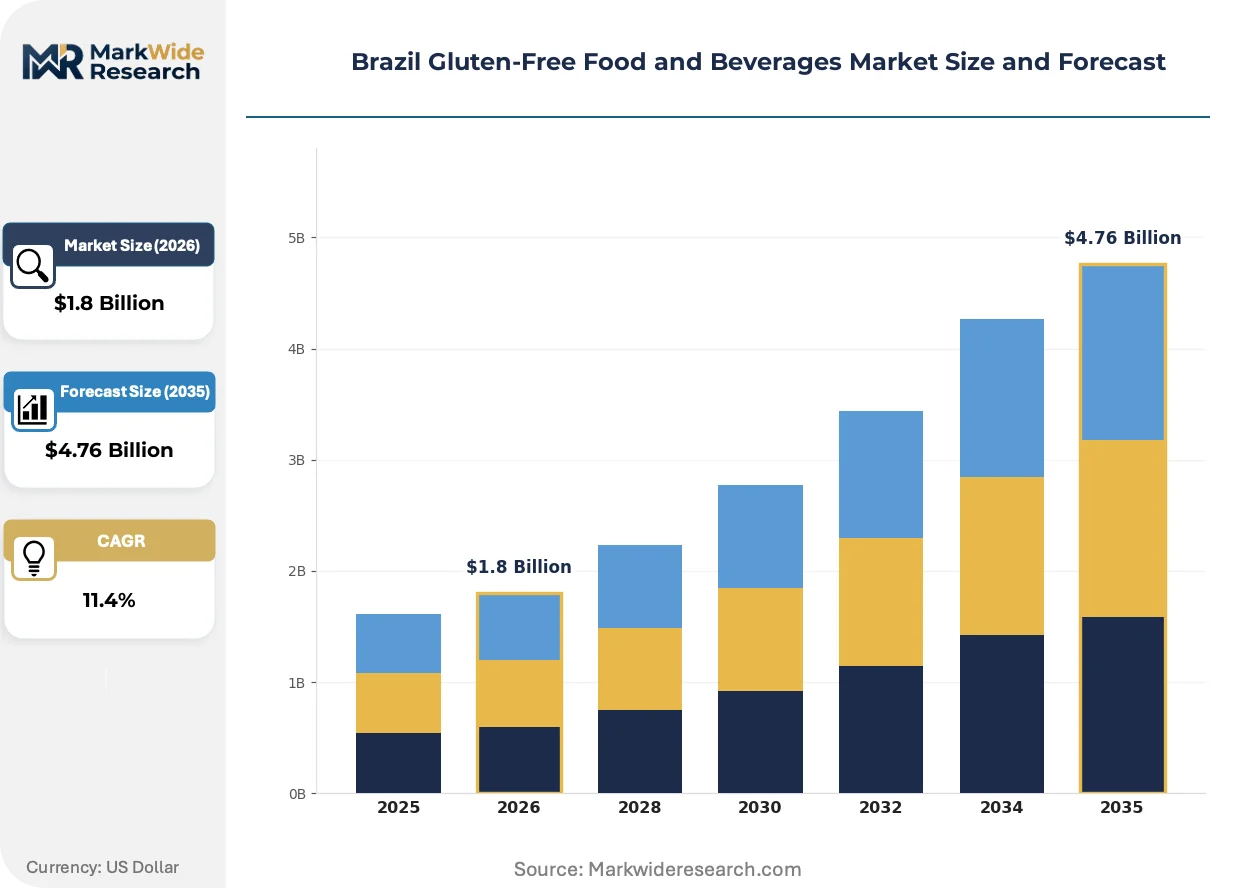
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Bakery Products, Pasta, Beverages Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Stores End User: Health-Conscious Consumers, Celiac Patients, Athletes, Families Ingredient Type: Rice Flour, Almond Flour, Tapioca Starch, Others |
| Companies Covered | Bob's Red Mill, Dr. Schar, General Mills Inc., Brazi Bites, H.J. Heinz Company, Raisio PLC, Hero Group AG, Nestlé S.A., Aminna, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Gluten-Free Food and Beverages Market Strategic Shifts
Digital traceability platforms and reformulation science are compressing production cycles while regulatory pressure accelerates investment in certified infrastructure across Brazilian manufacturing.
Enzymatic gluten degradation technology is virtualizing traditional wheat-free formulation constraints. Mid-sized Brazilian bakeries are adopting transglutaminase and protease treatments to improve rice-flour dough elasticity. This biotechnology is virtualizing the texture gap between conventional and gluten-free bread, reducing consumer switching friction.
ANVISA's proposed updates to allergen cross-contamination protocols are forcing segregation investments in shared facilities. Manufacturers must now implement dedicated production lines or contract with certified co-packers. The bakery segment faces the steepest compliance costs due to flour dust aerosolization risks in conventional plants.
Direct-to-pantry subscription models are fragmenting traditional retail dependency for diagnosed celiac consumers. São Paulo-based specialty platforms are bundling certified SKUs with nutritional counseling, capturing loyalty from households managing strict dietary protocols. This channel shift is most visible among dual-income professional families seeking convenience without label-verification burden.
Brazil Gluten-Free Food and Beverages Market Segmentation
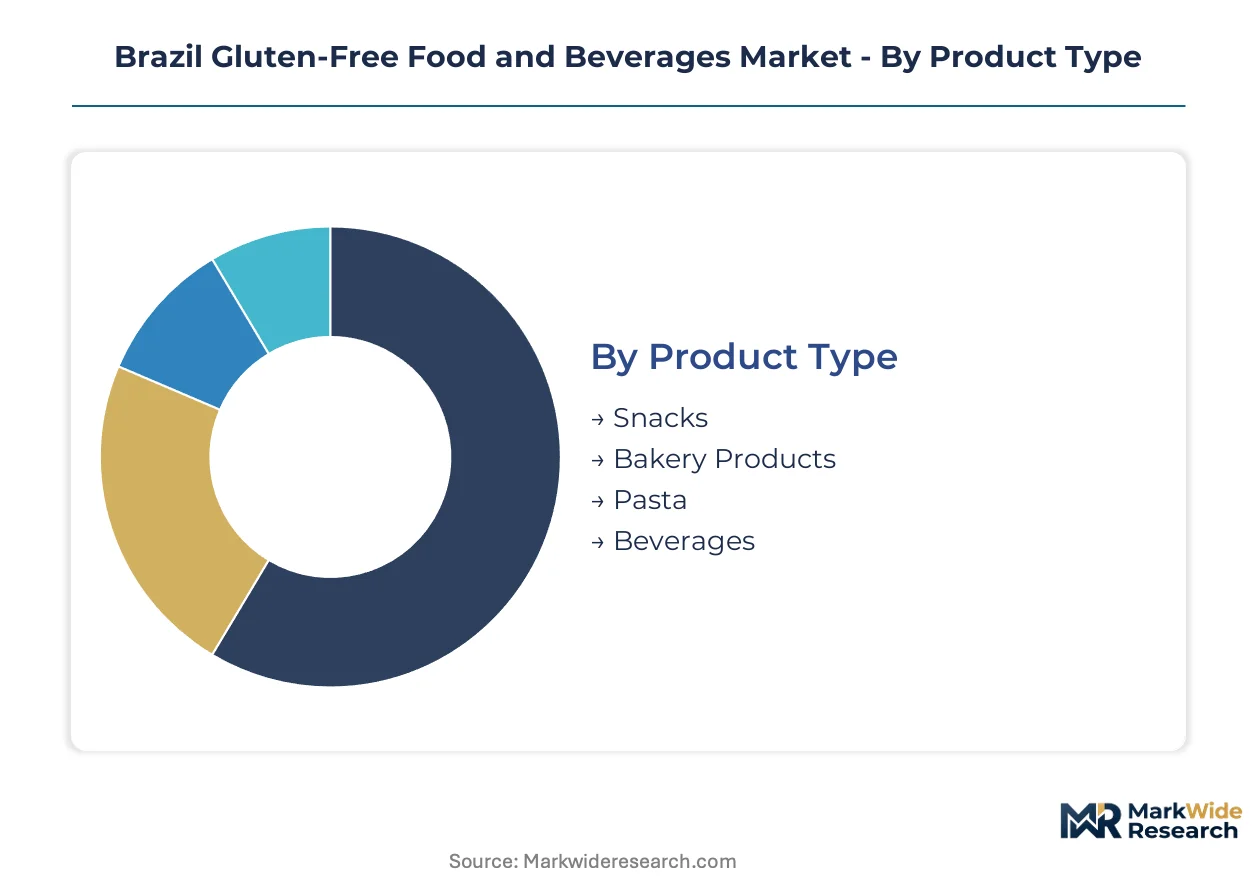
Segmentation in Brazil's gluten-free market reveals how distinct consumer motivations and supply constraints fragment commercial opportunity. ANVISA certification requirements and regional ingredient availability create tiered access patterns that manufacturers must navigate across product formats and channel strategies.
Product Type:
Application-based segmentation separates entrenched substitution habits from emerging functional consumption patterns across Brazilian households.
- Bakery Products:Bread, cake, and pastry formulations using rice flour and tapioca starch bases dominate current shelf space. São Paulo's specialty retail networks sustain premium positioning for certified loaves targeting diagnosed celiac households.
- Beverages:Electrolyte-enhanced and protein-fortified functional drinks target athlete segments with higher margin profiles. Southeast urban fitness culture drives trial adoption beyond traditional medical necessity positioning.
- Snacks:Cracker and chip alternatives leverage tapioca starch cost advantages for family-oriented volume SKUs.
- Pasta:Rice and corn-based noodle formulations serve weeknight meal substitution needs in dual-income households.
Bakery Products commands the established base. The steepest expansion runs through Beverages.
Distribution Channel:
Channel concentration reflects how certification trust and convenience trade off across Brazil's urban retail hierarchy.
- Supermarkets:Dedicated gluten-free aisle expansion at Carrefour and GPA networks democratizes access for health-conscious buyers without strict medical diagnosis. Shelf allocation decisions in São Paulo and Rio de Janeiro stores signal mainstream acceptance thresholds.
- Specialty Stores:Curated certified SKU assortments with nutritional counseling services capture loyalty from strict protocol households. Belo Horizonte and Curitiba networks deepen penetration in Southeast secondary cities.
- Online:Direct-to-pantry subscription models reduce label-verification burden for time-constrained professional families.
- Health Food Stores:Premium European import positioning serves affluent urban segments seeking heritage certification marks.
Supermarkets anchor volume throughput. Specialty Stores capture margin expansion through service differentiation.
End User:
Customer-type segmentation maps how diagnostic status, lifestyle orientation, and household structure shape purchasing behavior and price sensitivity.
- Celiac Patients:Medically diagnosed consumers with strict zero-tolerance requirements drive certified product validation and repurchase loyalty. Public health screening expansion in Southeast state programs enlarges this addressable base.
- Families:Multi-person households managing mixed dietary needs prioritize cost-efficient tapioca-based SKUs for daily meal integration. Center-West cassava supply proximity supports margin sustainability for this volume segment.
- Health-Conscious Consumers:Perceived wellness benefits motivate trial without medical necessity, expanding category boundaries beyond clinical positioning.
- Athletes:Performance-oriented functional nutrition demands drive premium hydration and recovery beverage adoption.
Families generate the volume foundation. Athletes deliver the steepest per-unit margin expansion.
Ingredient Type:
Cost-tier segmentation in raw material sourcing directly constrains formulation flexibility and end-market accessibility.
- Tapioca Starch:Domestic cassava processing in Brazil's Center-West region supplies cost-competitive carbohydrate bases for mass-market bakery and snack applications. Harvest volatility introduces margin compression risk that manufacturers hedge through forward contracting.
- Rice Flour:Established milling infrastructure in Rio Grande do Sul provides traceable supply chains that satisfy ANVISA documentation requirements for certified production. Texture limitations in bread applications drive enzymatic treatment adoption.
- Almond Flour:Dollar-denominated import dependency restricts deployment to premium-positioned SKUs targeting affluent urban segments.
- Others:Coconut flour and cassava-derived alternatives fill niche formulation gaps in specialty bakery applications.
Tapioca Starch underpins volume economics. Rice Flour secures regulatory-compliant supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's gluten-free supply chain, handling imported specialty grains and European finished goods that feed Southeast retail networks. Rail corridors from Mato Grosso deliver cassava feedstock to Center-West processing plants, while highway distribution webs radiate certified products toward urban consumption clusters.
São Paulo
São Paulo's metropolitan consumer base drives premium SKU adoption through dense specialty store networks and pharmacy retail channels. ANVISA's São Paulo regional office conducts the bulk of facility inspections, creating compliance familiarity among local manufacturers. The capital's dual-income professional households sustain direct-to-pantry subscription services that bundle certified products with nutritional counseling.
Minas Gerais
Belo Horizonte anchors Southeast secondary-city demand expansion, with specialty retailers deepening shelf access for diagnosed celiac households. State-level public health screening programs in Minas Gerais expand patient identification beyond São Paulo's diagnostic density. Local bakery cooperatives adopt enzymatic treatment technologies to improve rice-flour product texture for regional distribution.
Rio Grande do Sul
Rio Grande do Sul's established rice milling infrastructure supplies traceable flour streams that satisfy ANVISA documentation requirements for certified production. State agricultural extension services promote gluten-free crop rotation among smallholder farmers, diversifying raw material sourcing. Porto Alegre's retail networks serve as a testbed for mass-market SKU launches before national rollout.
Bahia
Salvador's underpenetrated market presents expansion opportunity as health-conscious middle-class formation outpaces certified product availability. Northeast regional distributors face higher logistics costs from Southeast manufacturing centers, compressing margins on price-sensitive family SKUs. Local tapioca starch processors leverage proximity to Bahia's cassava cultivation zones for cost-competitive ingredient supply.
Paraná
Curitiba's specialty retail networks capture demand from health-aware consumers seeking European-import positioning alongside domestic certified alternatives. The state's agricultural research institutions trial alternative gluten-free grains suited to southern Brazil's climate conditions. Paraná-based manufacturers benefit from Mercosur highway corridors that facilitate cross-border sourcing from Argentine suppliers.
Brazil Gluten-Free Food and Beverages Market Competitive Environment
On the supply side, the industry is tiered between multinational packaged food conglomerates with scaled distribution infrastructure and specialty manufacturers focused on certified clean-room production. European heritage brands occupy premium positioning through import channels, while domestic millers compete on tapioca-based volume SKUs. Strategic archetypes include: (1) diversified multinationals leveraging existing retail relationships, (2) gluten-free pure-plays investing in ANVISA-certified facilities, and (3) regional bakeries adopting enzymatic reformulation. Dominant competitive moves center on supermarket shelf allocation negotiations and certified production capacity expansion.
Within the multinational tier, General Mills Inc. and Nestlé S.A. anchor market presence through existing Brazilian retail relationships and scaled distribution networks. Dr. Schar represents the European heritage archetype, occupying premium positioning in health food channels. Among domestic specialists, Brazi Bites exemplifies regional manufacturing adaptation to local ingredient availability and consumer taste preferences.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Dr. Schar |
| General Mills Inc. |
| Brazi Bites |
| H.J. Heinz Company |
| Raisio PLC |
| Hero Group AG |
| Nestlé S.A. |
| Aminna |
| Others |
Value Chain & Pricing Dynamics
Rail corridors from Mato Grosso to Southeast processing centers anchor cost dynamics that concentrate supply power among domestic millers while fragmenting downstream price tiers across pharmacy, supermarket, and subscription channels.
Pricing Analysis
Volume-discount tiering structures separate certified clean-room SKUs from conventional reformulation alternatives. Three-tier pricing stratifies across ANVISA-certified premium lines, traceable rice-flour standard offerings, and tapioca-based economy family packs. Price differentiation centers on certification grade and geographic delivery cost to Northeast urban centers. Cost compression in economy tiers is intensifying because Center-West cassava harvest volatility feeds input uncertainty.
Supply Chain Analysis
Import inspection protocols for specialty grains create compliance friction that disadvantages smaller traders without established traceability documentation. Raw material flows draw from Rio Grande do Sul rice mills, Center-West cassava processors, and dollar-denominated almond flour imports. Single-source vulnerability concentrates in European heritage ingredient channels. Distribution runs through Carrefour and GPA supermarket networks with deepening specialty store penetration in secondary Southeast cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified clean-room production capacity represents the binding constraint that separates viable competitors from margin-compressed alternatives, with ANVISA facility approval timelines creating acquisition premiums for compliant assets.
For Market Incumbents: Insulate market position by accelerating certified co-packer partnerships ahead of ANVISA's proposed cross-contamination protocol updates. Secure backward integration into Rio Grande do Sul rice milling to lock traceable supply chains against import inspection delays. Channel control through direct-to-pantry subscription bundling reduces price transparency and builds switching costs among diagnosed celiac households.
For New Entrants and Emerging Players: Salvador and Recife's health-conscious middle-class formation represents the most penetrable entry point where certified SKU availability lags demand expansion. Functional hydration beverages targeting athlete segments bypass saturated bakery competition and command premium positioning. A go-to-market angle anchored in enzymatic texture improvement for rice-flour bread can differentiate against incumbent tapioca-dominant formulations.
For Investors and Strategic Acquirers: ANVISA's allergen labeling enforcement reshapes the acquisition landscape by inflating valuations for facilities with existing clean-room certification. Long-term viability centers on manufacturers with compliant infrastructure capable of scaling across Mercosur harmonization scenarios. The signal to watch is proposed updates to cross-border certification requirements that would unlock Argentine sourcing for Brazilian millers with established traceability systems.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Clean-room facility approval creates defensible positioning against reformulation competitors. |
| Enzymatic Reformulation Adoption | Transglutaminase treatments bridge texture gaps between conventional and gluten-free bread alternatives. |
| Direct-to-Pantry Subscription Launch | São Paulo-based platforms bundle certified SKUs with nutritional counseling to capture professional household loyalty. |
| Backward Integration into Rice Milling | Rio Grande do Sul traceable supply chains satisfy ANVISA documentation requirements for certified production. |
| Northeast Urban Distribution Expansion | Salvador and Recife networks address underpenetrated demand pools where health-conscious formation outpaces SKU availability. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at multinational food conglomerates, ANVISA regulatory affairs specialists, category buyers at Carrefour and GPA networks, and supply planners at domestic cassava processors, then refined through secondary validation against customs records, Nielsen retail audit data, and agricultural extension service crop reports. Bottom-up SKU-level volume builds were triangulated with top-down category spend estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user diagnostic status, and ingredient cost tier. CAGRs were derived from segment-level growth trajectory analysis incorporating ANVISA compliance cost pass-through assumptions and regional retail density expansion curves.
Macroeconomic conditions sit as an overlay; deviation in Center-West cassava harvest yields or dollar exchange rate volatility would shift the trajectory for import-dependent premium formulations. Forecasts reflect documented assumptions regarding regulatory timeline adherence and retail shelf allocation negotiations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Lactose Free Products Market