
 Global Gluten Free Prepared Foods Market | 2026-2036
Global Gluten Free Prepared Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gluten Free Prepared Foods Market Foresight
Multi-source ingredient procurement is shifting toward vertically integrated supply chains among leading gluten-free prepared food manufacturers. General Mills, Inc. leverages dedicated milling facilities to control cross-contamination risk across its production network. Amy's Kitchen, Inc. sustains its competitive edge through organic-certified, gluten-free frozen meal specialization. Dr. Schär AG anchors European distribution with pharmacy and retail channel dominance in Germany and Italy.
Gluten-free prepared foods are manufactured products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, tapioca starch, or alternative grain blends to achieve comparable texture and shelf stability. These products serve celiac patients, gluten-sensitive consumers, and health-focused buyers seeking convenient meal solutions without dietary restriction compromise. Breads and bakery items occupy the largest product-type position due to daily consumption frequency and established substitution behavior among diagnosed celiac populations. Online retailers represent the fastest-expanding distribution channel, driven by subscription models and direct-to-consumer sampling programs that reduce trial barriers for new gluten-free buyers. Snack foods concentrate margin pools through premium pricing on portable, portion-controlled formats targeting workplace and travel occasions.
The FDA enforces gluten-free labeling standards requiring less than 20 ppm gluten content, while the EU's Regulation (EC) No 41/2009 mandates equivalent thresholds with additional allergen disclosure requirements. Health Canada and the FSA in the United Kingdom operate parallel certification schemes that create compliance complexity for multinational suppliers. Celiac disease support organizations in Australia and Brazil are pressing national regulators toward mandatory testing protocols. Stakeholders must monitor evolving threshold harmonization debates and traceability technology investments that will determine which suppliers retain shelf access across fragmented national standards.
Market Dynamics
Cross-contamination prevention protocols are forcing gluten-free prepared food manufacturers to reconfigure production footprints, as dedicated facility requirements separate compliant from non-compliant supply tiers and reshape capital allocation across the industry.
Growth Catalysts
- FDA gluten-free labeling enforcement:The FDA's 20 ppm threshold mandate has eliminated ambiguous product claims, accelerating consumer trust and repeat purchase rates among diagnosed celiac populations in the United States.
- Rice flour processing advances:Modified starch extrusion technologies now replicate wheat gluten's viscoelastic properties, enabling texture parity in frozen pasta and breaded prepared meals without formulation compromise.
- Pharmacy channel expansion:Dr. Schär AG's pharmacy-first distribution model in Germany and Italy has created a prescription-adjacent purchase pathway that legitimizes gluten-free prepared foods as medical nutrition.
Market Restraints
- Alternative grain input cost volatility:Tapioca starch and sorghum flour prices fluctuate with Brazilian and Nigerian harvest cycles, compressing margin stability for manufacturers without long-term purchase agreements.
- Certification timeline friction:The EU's Regulation (EC) No 41/2009 requires batch-level testing documentation that extends new product introduction cycles by four to six months versus conventional prepared foods.
- Oat cross-contamination risk:Commercial oat supply chains remain contaminated with wheat pollen and harvest equipment residue, eliminating a theoretically ideal gluten-free carbohydrate source for most prepared food formulations.
Strategic Opportunities
- Brazilian regulatory momentum:ANVISA is evaluating mandatory gluten-free certification protocols following pressure from celiac disease support organizations, creating first-mover advantage for suppliers establishing local testing infrastructure.
- Subscription direct-to-consumer models:Online retailers are capturing trial-resistant consumers through curated monthly boxes that reduce the risk premium of unfamiliar gluten-free prepared meal brands.
- Clean-label convergence:Organic certification overlap with gluten-free claims is commanding shelf-space premiums in United States natural grocery channels, rewarding dual-certified product development.
Industry Challenges
- Allergen testing technician scarcity:ELISA and PCR testing expertise for 20 ppm verification is concentrated among a limited pool of laboratory specialists, creating bottlenecks in quality assurance hiring.
- Legacy equipment retrofit costs:Converting shared production lines to dedicated gluten-free status requires capital outlays for segregated storage, conveying, and packaging systems that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gluten Free Prepared Foods Market |
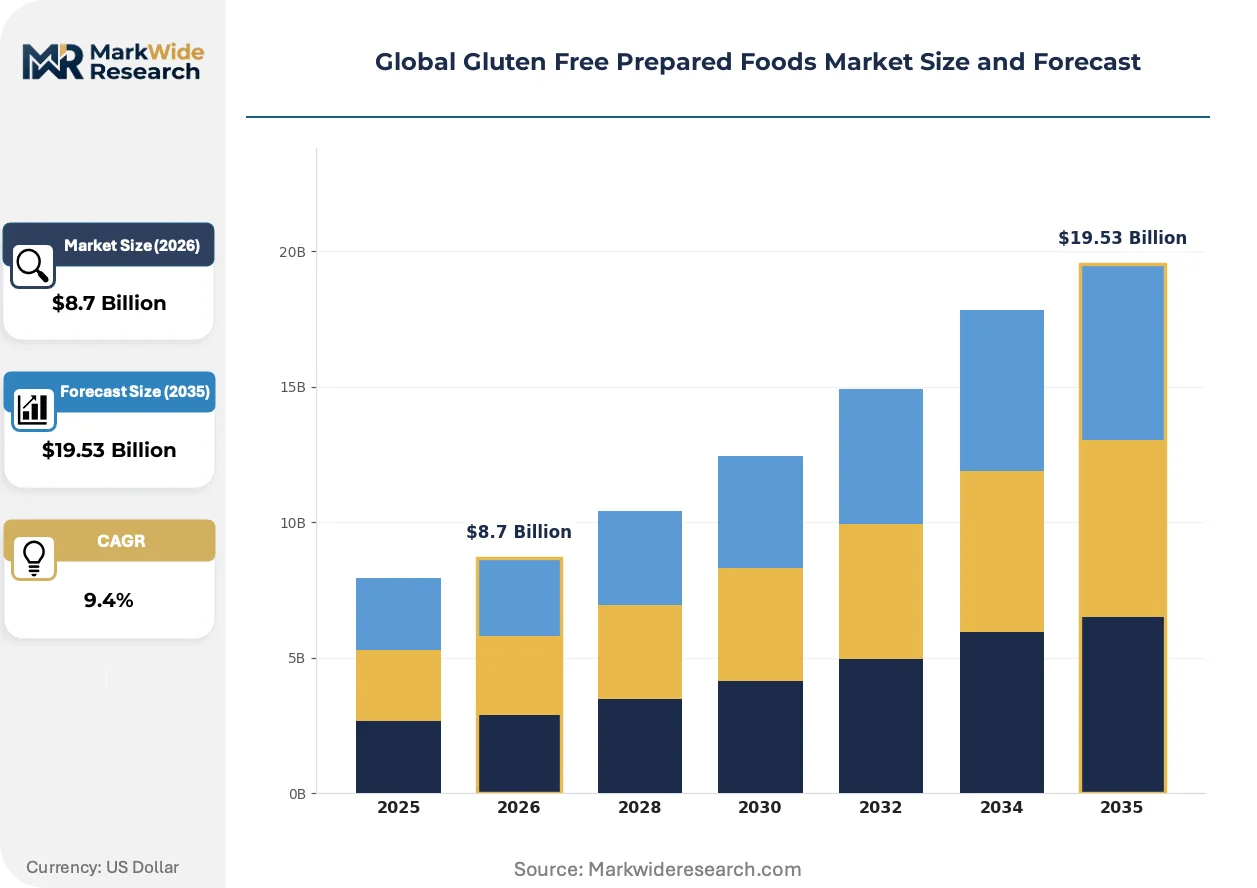
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads & Bakery, Pasta & Noodles, Snack Foods, Breakfast Cereals, Frozen Meals Distribution Channel: Supermarkets & Hypermarkets, Specialty Stores, Online Retailers, Convenience Stores, Natural Food Stores Customer Type: Celiac Patients, Health-Conscious Consumers, Allergy Sufferers, Fitness Enthusiasts, Vegan Consumers Packaging Type: Plastic Containers, Cardboard Boxes, Vacuum Packs, Resealable Bags, Glass Jars |
| Companies Covered | Dr. Schär AG, General Mills, Inc., The Hain Celestial Group Inc., The Kraft Heinz Company, Conagra Brands, Inc., Nestlé SA, Unilever, Amy's Kitchen, Inc., Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gluten Free Prepared Foods Market Shifts & Advancements
Digital traceability systems and alternative protein-carbohydrate combinations are compressing formulation development cycles while expanding the acceptable ingredient universe for gluten-free prepared food manufacturers.
Near-infrared spectroscopy is automating real-time gluten detection on production lines, replacing batch-sampling laboratory protocols with continuous monitoring. Large-scale frozen meal manufacturers in the United States are deploying this technology to eliminate hold-and-release inventory buffers. The compression of quality assurance timelines is enabling just-in-time production scheduling previously unavailable to allergen-controlled facilities.
REACH chemical safety assessments in Europe are tightening scrutiny on processing aids used in gluten-free starch modification, particularly oxidizing agents and emulsifiers. Manufacturers are reformulating to preempt regulatory exclusion of legacy additives. Frozen dough and batter segments face the steepest compliance recalibration as their additive load exceeds that of shelf-stable formats.
Retail buyer consolidation is concentrating assortment decisions among fewer United States and United Kingdom grocery chains, each demanding exclusive gluten-free prepared meal SKUs as condition of distribution. Smaller manufacturers are responding with co-manufacturing partnerships that aggregate volume to meet minimum order thresholds. Channel control has shifted decisively toward retailers with dedicated free-from category management teams.
Global Gluten Free Prepared Foods Market Segmentation
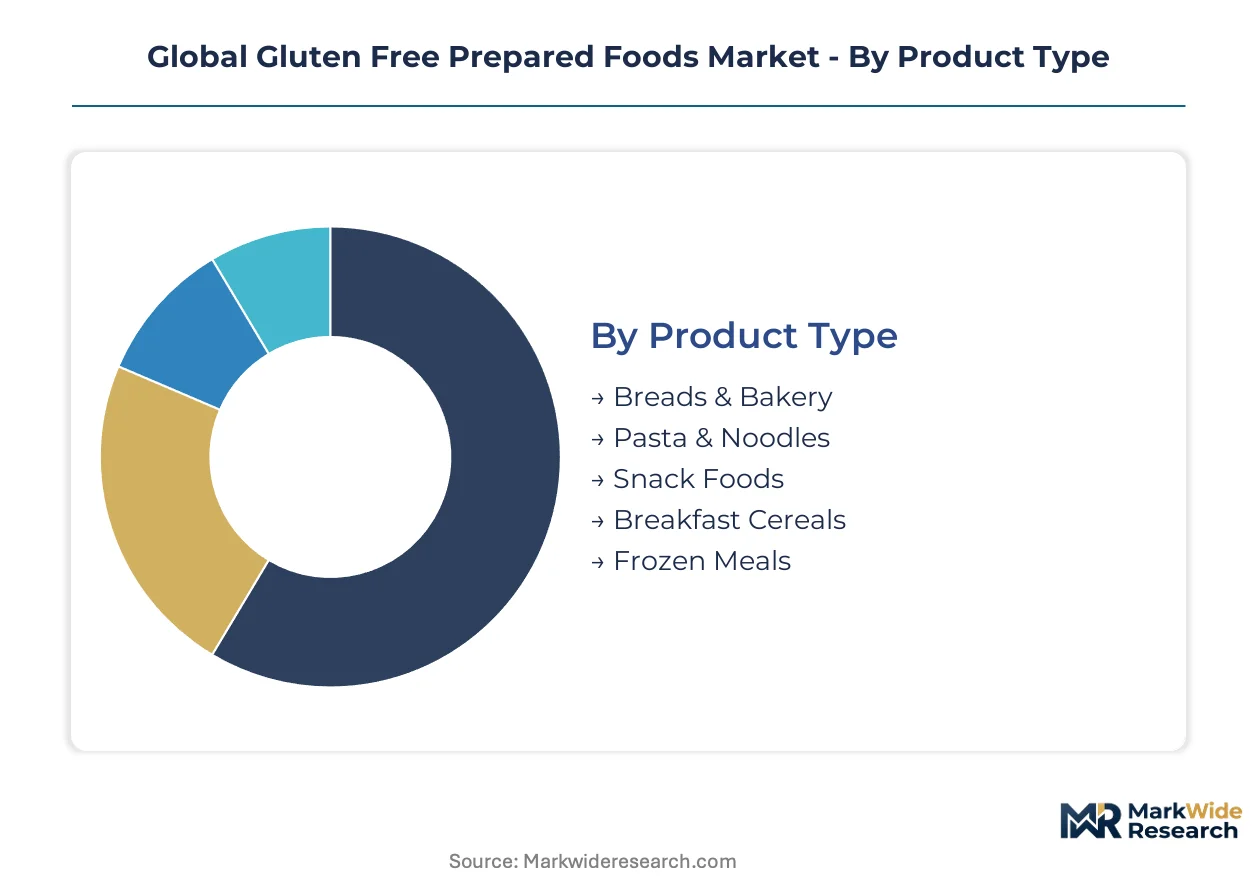
Gluten-free prepared foods demand fragments across four distinct segmentation axes, each revealing divergent margin structures and channel control points. Product type stratification separates daily staples from impulse purchases, while distribution channel dynamics determine which manufacturers capture repeat purchase loyalty versus trial-driven volume.
Product Type:
Consumption frequency and substitution economics separate winners from margin-diluted segments in this category.
- Breads & Bakery:Formulations rely on rice flour, tapioca starch, and xanthan gum to replicate wheat gluten's viscoelastic structure in sandwich loaves, rolls, and flatbreads. Daily consumption frequency among diagnosed celiac populations in the United States sustains the largest revenue pool, though price compression from private-label entrants is narrowing branded premiums.
- Snack Foods:Portable formats including crackers, pretzels, and energy bars command the highest unit margins through portion-controlled packaging and workplace consumption occasions. Health-conscious buyers in Germany and Italy drive per-capita spending premiums for clean-label certified variants.
- Pasta & Noodles:Extruded rice and corn blends serve family meal occasions with texture parity improving through modified starch technologies.
- Breakfast Cereals:Granola and puffed grain formulations target children of celiac parents seeking school-safe options.
- Frozen Meals:Complete entrées with protein-carbohydrate balance concentrate in United States natural grocery channels.
Breads & Bakery leads volumes today; Snack Foods is gaining share fastest.
Distribution Channel:
Channel selection determines whether manufacturers capture subscription loyalty or transactional trial volume.
- Online Retailers:Direct-to-consumer platforms and subscription box models reduce trial barriers through curated sampling programs. Celiac patients in the United Kingdom leverage auto-replenishment for staple pantry items, while specialty meal kits target health-conscious urban consumers seeking variety without label-reading burden.
- Specialty Stores:Dedicated gluten-free retailers and pharmacy-adjacent formats in Germany and Italy provide prescription-adjacent legitimacy and trained staff consultation. Dr. Schär AG's channel dominance demonstrates how medical nutrition positioning commands price premiums unavailable in mass retail.
- Supermarkets & Hypermarkets:Shelf-space allocation in United States and United Kingdom chains increasingly consolidates under dedicated free-from category managers.
- Natural Food Stores:Whole Foods Market and regional cooperatives demand dual organic-gluten-free certification for entry.
- Convenience Stores:Grab-and-go snack formats target travel and workplace occasions with limited SKU breadth.
Supermarkets & Hypermarkets anchor volume today; Online Retailers is climbing the fastest.
Customer Type:
Diagnostic status and dietary motivation stratify price sensitivity and brand loyalty intensity.
- Celiac Patients:Medically diagnosed individuals require strict adherence to sub-20 ppm gluten thresholds, creating zero-tolerance quality expectations and regulatory compliance dependency. United States diagnosis rates continue climbing as screening protocols expand, concentrating demand among households with multiple affected members.
- Health-Conscious Consumers:Non-celiac buyers pursuing perceived digestive wellness or weight management drive trial volume and flavor innovation demands. This segment in Brazil and Australia exhibits highest churn rates as dietary trends shift.
- Allergy Sufferers:Multi-allergen households seek gluten-free plus dairy-free or nut-free combined formulations.
- Fitness Enthusiasts:Athletes adopting gluten-free protocols for inflammation reduction target high-protein prepared meals.
- Vegan Consumers:Plant-based plus gluten-free overlap commands shelf-space premiums in natural grocery channels.
Celiac Patients dominates revenue concentration today; Health-Conscious Consumers shows steepest expansion trajectory.
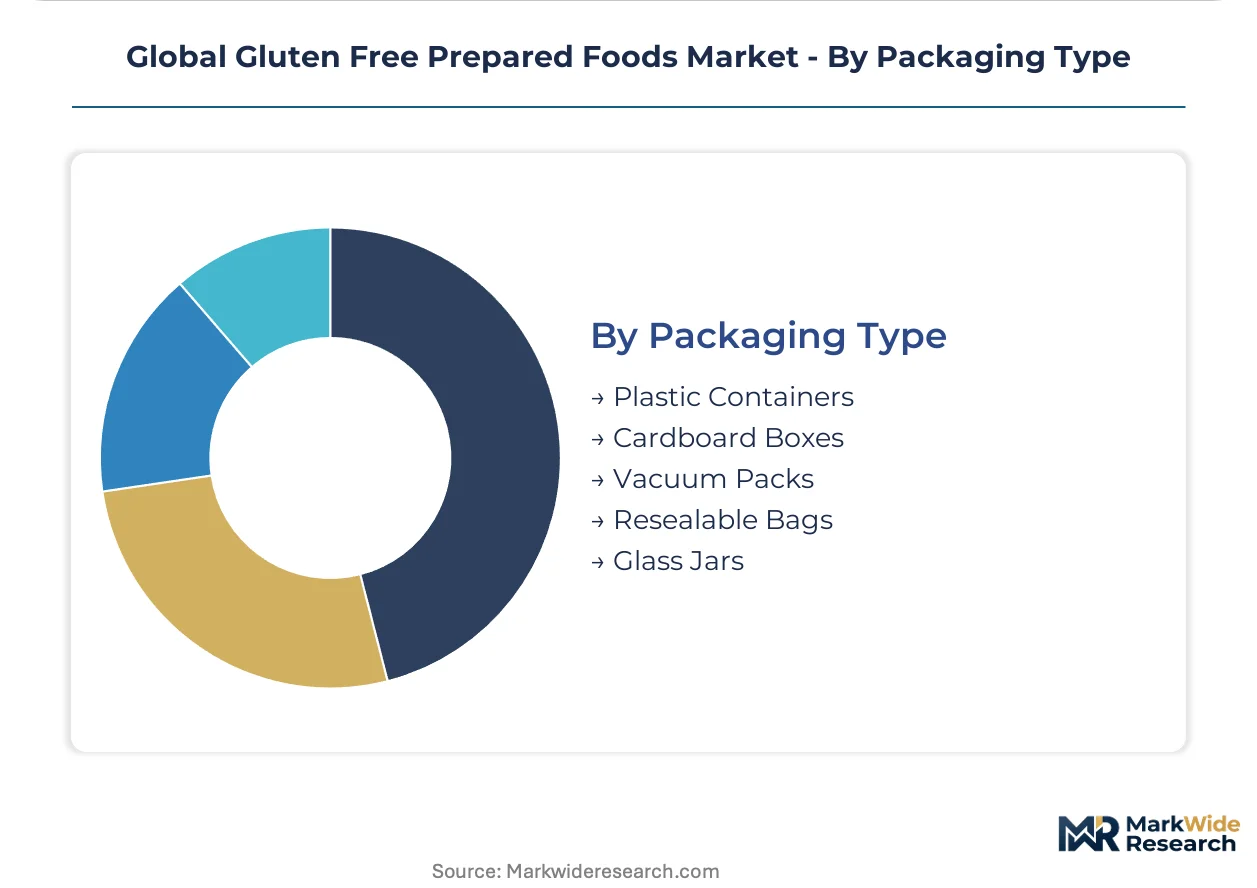
Packaging Type:
Shelf stability requirements and sustainability positioning create divergent material cost structures.
- Resealable Bags:Multi-layer polymer structures with oxygen barrier properties extend shelf life for dry snack foods and bakery items. United States retail buyers increasingly demand post-consumer recycled content minimums as condition of distribution.
- Vacuum Packs:Modified atmosphere packaging eliminates oxygen exposure for refrigerated pasta and prepared meal formats. European regulatory pressure under REACH assessments is accelerating migration from legacy barrier films to bio-based alternatives.
- Plastic Containers:Rigid PET and PP formats dominate frozen meal and ready-to-eat salad segments.
- Cardboard Boxes:Recyclable outer shells with inner barrier liners serve cereal and cracker multipacks.
- Glass Jars:Premium positioning for sauces, condiments, and wet meal components in specialty retail.
Plastic Containers holds volume leadership today; Resealable Bags is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Chicago metropolitan area anchors North American gluten-free prepared food manufacturing through its concentration of dedicated milling infrastructure and cold-chain distribution networks serving retail buyers across the continent.
United States
FDA enforcement of the 20 ppm gluten threshold has standardized labeling claims and accelerated consumer trust among diagnosed celiac populations. The agency's batch-level verification requirements have forced manufacturers to invest in dedicated testing laboratories. Minneapolis-St. Paul hosts General Mills' vertically integrated production network controlling cross-contamination risk from grain intake through finished goods packaging.
Germany
Dr. Schär AG's pharmacy-first distribution model has created prescription-adjacent legitimacy for gluten-free prepared foods as medical nutrition. The country's national food regulator enforces EU Regulation (EC) No 41/2009 with additional allergen disclosure mandates exceeding baseline European standards. Bavaria's industrial food processing corridor concentrates certified gluten-free bakery and pasta manufacturing serving Italian and Austrian export markets.
Italy
Diagnosed celiac prevalence rates exceed European averages, sustaining dense retail shelf allocation for prepared pasta and bread substitutes. The Ministry of Health operates a national celiac disease registry that channels patients toward subsidized gluten-free product purchases. Emilia-Romagna's agri-food cluster has specialized in modified starch extrusion technologies replicating wheat gluten's viscoelastic properties.
Brazil
ANVISA is evaluating mandatory gluten-free certification protocols following sustained pressure from celiac disease support organizations in São Paulo and Rio de Janeiro. This regulatory momentum creates first-mover advantage for suppliers establishing local testing infrastructure ahead of formal implementation. The São Paulo metropolitan area concentrates health-conscious consumer demand and natural grocery retail expansion.
Australia
Celiac disease support organizations are pressing national regulators toward mandatory testing protocols beyond current voluntary standards. Food Standards Australia New Zealand maintains parallel certification schemes that create compliance complexity for multinational suppliers. Melbourne's food manufacturing belt has attracted co-manufacturing partnerships aggregating volume to meet supermarket chain minimum order thresholds.
Global Gluten Free Prepared Foods Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and organic-certified adjacent spaces to differentiate shelf positioning. The vendor base stratifies across three maturity tiers: multinational packaged food conglomerates with dedicated gluten-free divisions, mid-cap specialists controlling vertically integrated supply chains, and regional co-manufacturers serving private-label retail programs. Dominant competitive moves include backward integration into dedicated grain milling capacity and exclusive SKU development for consolidated retail buyers.
Within the specialist tier, Dr. Schär AG and Amy's Kitchen, Inc. exemplify divergent geographic and channel strategies. Dr. Schär AG anchors European distribution through pharmacy and retail channel dominance in Germany and Italy, while Amy's Kitchen, Inc. sustains competitive positioning through organic-certified frozen meal specialization in United States natural grocery channels. General Mills, Inc. represents the multinational archetype leveraging dedicated milling facilities to control cross-contamination risk across its production network.
| Leading Market Players |
|---|
| Dr. Schär AG |
| General Mills, Inc. |
| The Hain Celestial Group Inc. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| Nestlé SA |
| Unilever |
| Amy's Kitchen, Inc. |
| Kellanova |
| Others |
Supply & Pricing Matrix
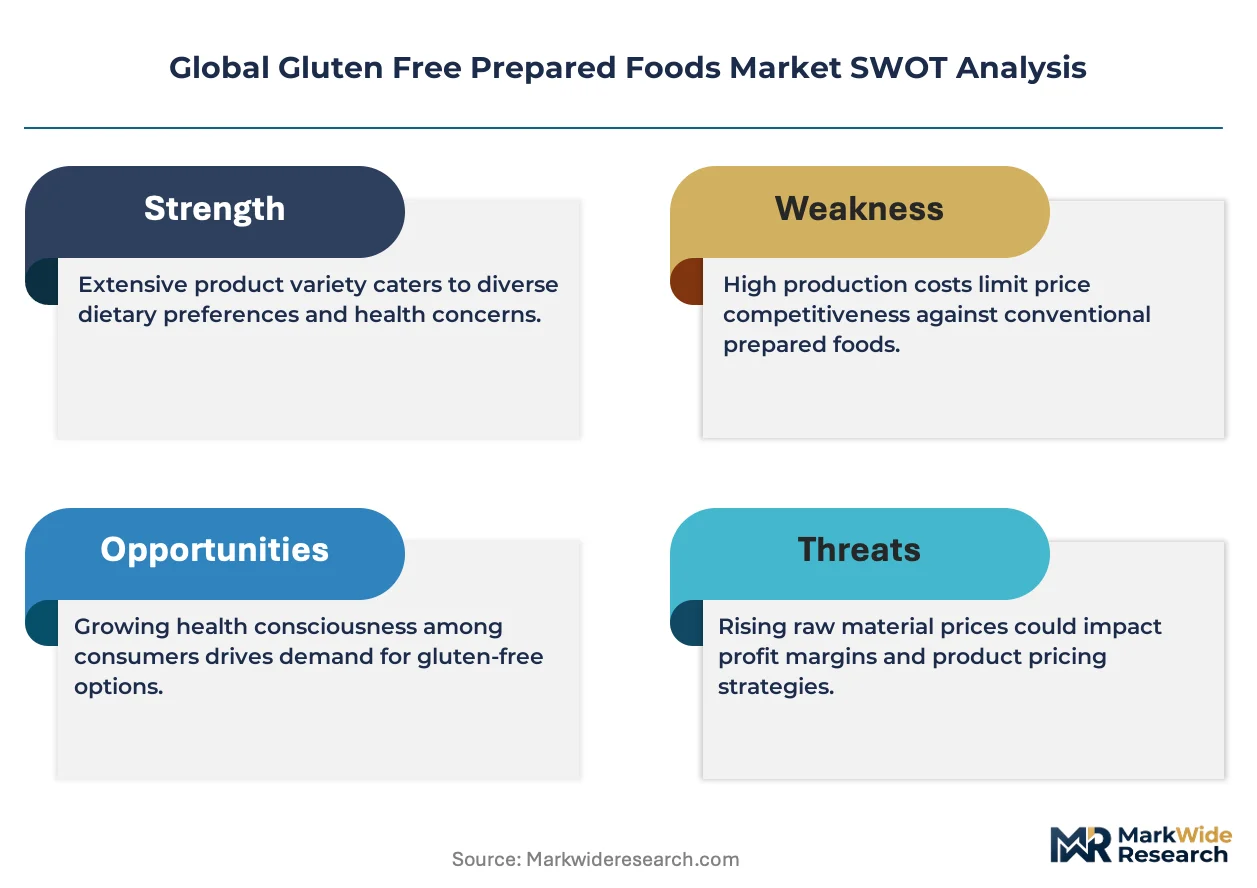
Certification-grade bifurcation between sub-20 ppm medical nutrition and conventional free-from products manifests in both pricing premiums and dedicated facility requirements across the gluten-free prepared foods sector. FDA and EU Regulation (EC) No 41/2009 compliance tiers separate pharmacy-channel positioning from mass retail penetration, with batch-level testing costs embedding directly into landed pricing.
Pricing Analysis
Input-cost pass-through from tapioca starch and sorghum flour volatility runs through formulation economics, with Brazilian and Nigerian harvest cycles compressing margin stability for manufacturers lacking long-term purchase agreements. Three-tier pricing structure across premium organic-certified, standard certified-gluten-free, and economy private-label levels reflects certification depth and channel positioning. Pricing pressure stems from retail buyer consolidation demanding exclusive SKUs as distribution conditions. Celiac patients exhibit lowest price sensitivity due to medical necessity, while health-conscious consumers in Brazil and Australia drive highest churn at premium tiers.
Supply Chain Analysis
Certification gating through dedicated facility requirements anchors supply concentration in the United States, Germany, and Italy where vertically integrated milling infrastructure controls cross-contamination risk. Raw material dependencies center on rice flour, modified starches, and alternative grain blends sourced from controlled-origin suppliers. Single-source vulnerability concentrates in ELISA and PCR testing expertise for 20 ppm verification, creating quality assurance bottlenecks. Distribution runs through pharmacy-adjacent channels in Europe and natural grocery chains in North America, with direct-to-consumer subscription models expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where diagnosis-rate expansion and regulatory harmonization are shifting demand toward certified medical nutrition specifications. Premium positioning now requires dual organic-gluten-free certification and pharmacy-channel legitimacy.
For Market Incumbents: Anchor market position through backward integration into dedicated grain milling capacity in Minneapolis-St. Paul or Greater Chicago corridors, eliminating third-party cross-contamination risk. Defend against emerging clean-label specialists by locking exclusive SKU development with consolidated United States and United Kingdom retail buyers. Certification investment in Brazilian ANVISA pre-compliance infrastructure captures first-mover advantage ahead of mandatory protocols. For New Entrants and Emerging Players: The price-point gap between Dr. Schär AG's pharmacy-premium positioning and private-label economy tiers opens white-space in mid-market subscription direct-to-consumer models. Target health-conscious urban consumers in São Paulo and Melbourne through curated monthly boxes reducing trial barriers. Penetrate Brazil's natural grocery expansion with local testing infrastructure ahead of regulatory formalization. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers face legacy equipment retrofit costs for dedicated gluten-free line conversion. Long-term viability favors vertically integrated specialists controlling milling through packaging with pharmacy-channel dominance. Acquisition targets should demonstrate batch-level testing laboratory ownership and exclusive retail SKU relationships. Watch ANVISA certification mandate timing and FDA threshold harmonization debates as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Facility Certification | Dr. Schär AG's pharmacy-first model demonstrates how medical nutrition positioning commands price premiums unavailable in mass retail. |
| Backward Integration into Milling | General Mills' captive supply of grain intake through finished goods packaging eliminates third-party cross-contamination liability. |
| Subscription Direct-to-Consumer Launch | Amy's Kitchen leverages auto-replenishment models to reduce trial barriers for celiac patients seeking staple pantry security. |
| Dual Certification Investment | Organic-gluten-free overlap captures shelf-space premiums in Whole Foods Market and regional cooperative channels. |
| Regulatory Pre-Compliance Infrastructure | ANVISA evaluation momentum in São Paulo creates first-mover advantage for suppliers establishing local testing ahead of mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at gluten-free prepared food manufacturers, category buyers at United States and United Kingdom retail chains, supply planners managing alternative grain procurement, and regulatory affairs leads navigating FDA and EU compliance pathways. Secondary validation drew from FDA gluten-free labeling guidance documents, EFSA allergen disclosure frameworks, Nielsen retail audit data on free-from category performance, and customs records tracking rice flour and tapioca starch trade flows. Bottom-up SKU-level volume aggregation and top-down category expenditure analysis provided cross-check triangulation.
Comparable-period anchoring established baseline reference points across historical diagnosis-rate trajectories and regulatory implementation timelines, then extended projections over the analysis window through segmented modeling. Dimensions included product type stratification, distribution channel dynamics, customer diagnostic status, and packaging format requirements. CAGRs derived from compound growth trajectory fitting against penetration rate ceilings and substitution elasticity parameters. Forecast inputs incorporated pharmacy-channel expansion rates, near-infrared spectroscopy adoption curves for real-time gluten detection, and REACH chemical safety assessment impacts on processing aid reformulation.
Caveats apply where ANVISA regulatory formalization delays, oat cross-contamination resolution breakthroughs, or alternative grain harvest disruptions could materially shift the outlook. Forecasts reflect assumptions about certification threshold stability and retail buyer consolidation pace. A model refresh is warranted upon material change in FDA-EU threshold harmonization negotiations or Brazilian mandatory testing protocol implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Egg Allergy Market