
 Low GI Food Market | 2026-2036
Low GI Food Market Size, Share, and Industry Trends Forecast 2026-2036
Low GI Food Market Insights
Buyer concentration in the Low GI Food Market is rebalancing as hospital procurement networks consolidate purchasing power while fitness platforms fragment direct-to-consumer channels. Nestle leverages its clinical nutrition infrastructure to anchor institutional supply contracts across European healthcare systems. Ingredion competes through specialty starch modification technologies that reduce glycemic response in processed formulations. Alchemy Foodtech positions its plant-based fiber systems to capture emerging demand from Asia-Pacific functional food manufacturers seeking clean-label low GI solutions.
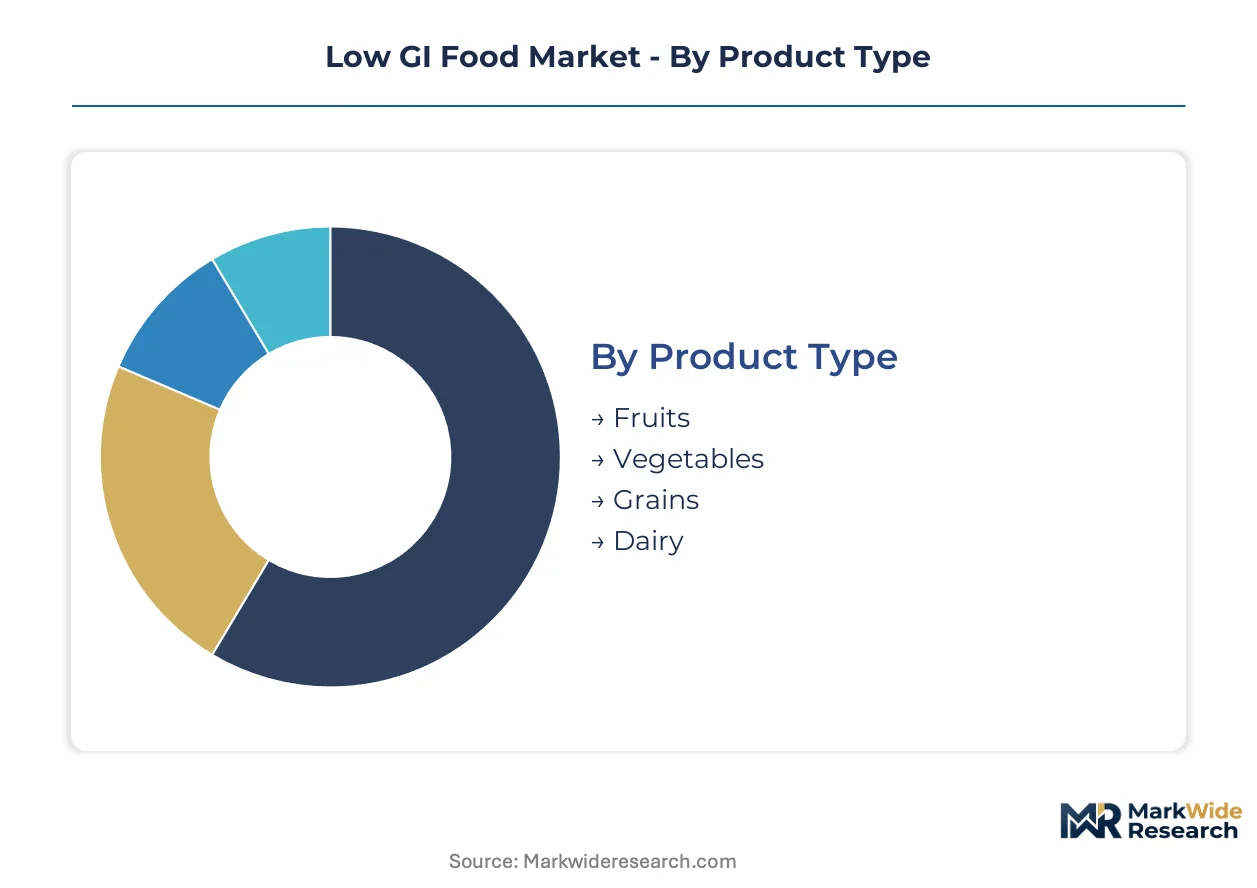
Low GI foods are carbohydrate-containing products formulated to produce a smaller rise in blood glucose relative to reference foods, typically achieving glycemic index values below 55 through modified starch structures, soluble fiber enrichment, or specific grain selection and processing protocols. Their primary commercial purpose centers on metabolic management applications including diabetes nutrition, weight control protocols, and sustained energy delivery for athletic performance. Grains dominate product type value pools due to established milling infrastructure and consumer familiarity with low GI bread and pasta alternatives, while dairy represents the fastest-growing category as protein-forward, reduced-sugar yogurts and beverages capture sports nutrition shelf space. The diabetes nutrition application commands the deepest margin pools because clinical validation requirements create formulation barriers that limit competitive entry.
The EU Nutrition and Health Claims Regulation and EFSA glycemic response assessment protocols shape permissible marketing language and substantiation burdens across European markets. FDA recognition of glycemic index as a voluntary nutrient disclosure element influences U.S. product positioning and label architecture without mandating standardized testing. China's National Health Commission dietary guidelines for diabetes prevention amplify low GI messaging through state-backed nutrition education channels. Stakeholders must monitor evolving glycemic testing standardization between ISO methodology and national reference food protocols to anticipate compliance cost shifts and market access requirements.
Market Dynamics
Clinical procurement networks are consolidating purchasing power for certified low GI formulations while EFSA glycemic response protocols tighten substantiation requirements, compressing margins for non-compliant suppliers and rewarding vertically integrated manufacturers with in-house testing capabilities.
Growth Catalysts
- Diabetes nutrition protocols:Hospital systems across Germany are embedding low GI meal planning into standardized patient discharge programs, creating institutional pull-through for certified formulations.
- EFSA glycemic claims pathway:The EU Nutrition and Health Claims Regulation's clarified assessment criteria are reducing regulatory uncertainty for substantiated products, accelerating formulation investment from established food manufacturers.
- Soluble fiber modification:Enzymatic processing of resistant starches is enabling clean-label low GI solutions without synthetic additives, opening reformulation opportunities in conventional bakery categories.
Market Restraints
- Reference food standardization costs:ISO 26642 testing methodology requires expensive controlled human studies with glucose reference protocols, creating capital barriers for mid-tier manufacturers without clinical research infrastructure.
- Raw material concentration:Specialty resistant wheat starch supply concentrates among North American grain processors, exposing European formulators to currency and tariff volatility on critical inputs.
- Consumer comprehension gaps:Glycemic index literacy remains limited outside diabetes patient populations, constraining mainstream retail velocity and requiring expensive education investments at point-of-sale.
Strategic Opportunities
- Sports nutrition white space:Protein-forward low GI dairy beverages targeting endurance athletes represent an underdeveloped application with premium pricing potential and limited incumbent competition.
- Asia-Pacific clean-label demand:China's National Health Commission dietary guidelines are amplifying low GI messaging through state nutrition education channels, creating regulatory tailwind for imported certified products.
- Direct-to-clinic distribution:Bypassing conventional retail through registered dietitian recommendation networks reduces marketing spend while capturing high-margin prescription-adjacent nutrition sales.
Industry Challenges
- Clinical validation timelines:EFSA Article 13.5 health claim approvals require 12-18 month scientific assessment periods, delaying product launches and tying up R&D resources without revenue certainty.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in sensory science and metabolic response modeling command premium compensation, constraining scale-up capacity for emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low GI Food Market |
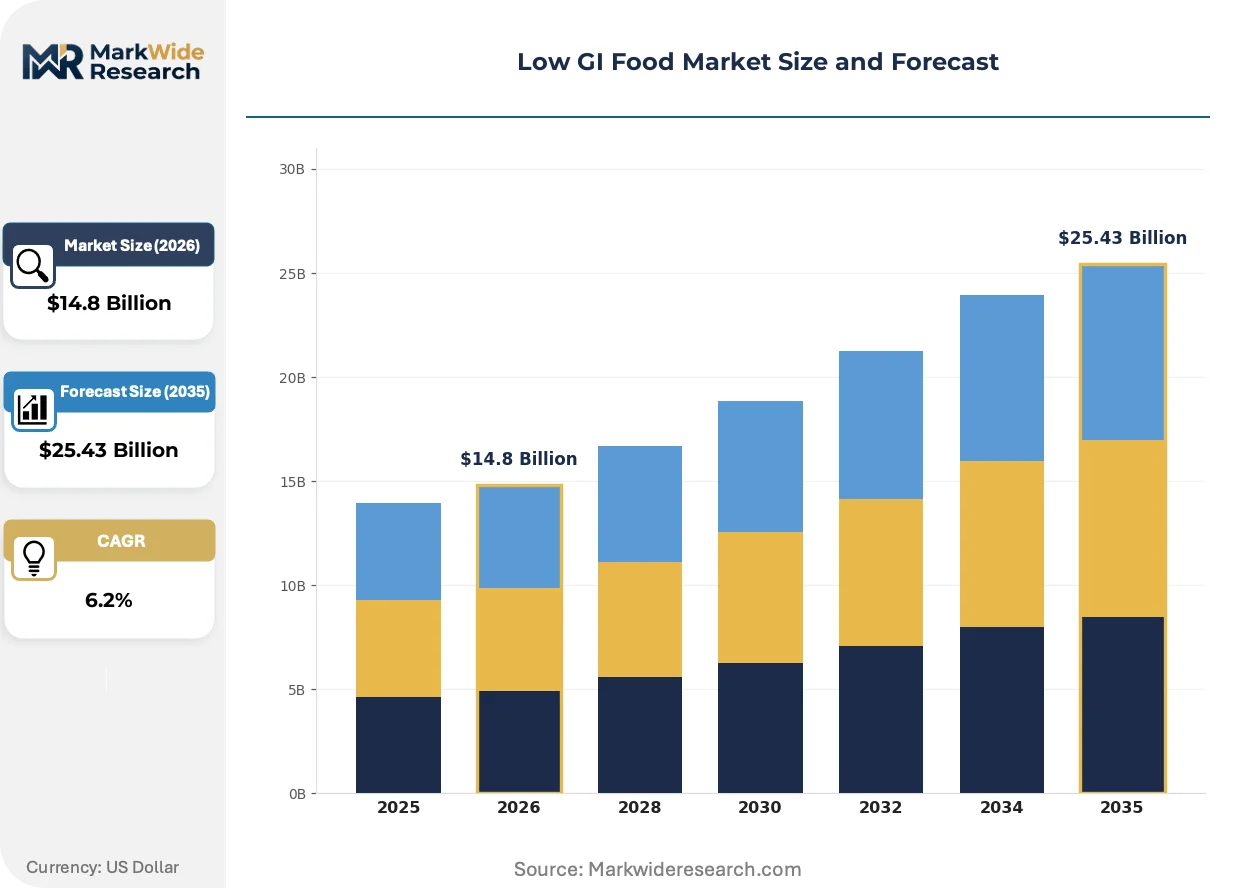
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy End User: Healthcare Professionals, Dieticians, Fitness Enthusiasts, General Public Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Application: Weight Management, Diabetes Nutrition, Sports Nutrition, Meal Replacement |
| Companies Covered | Nestle, PepsiCo, Cargill, Ingredion, Tate & Lyle, Archer Daniels Midland, EID Parry, General Mills, Alchemy Foodtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low GI Food Market Trends and Innovations
Reformulation science is advancing beyond simple fiber fortification toward molecular starch restructuring, while regulatory clarity around glycemic claims is separating substantiated products from marketing-driven positioning.
Enzymatic debranching of amylopectin is electrifying low GI ingredient production by creating slowly digestible starch structures without the sensory compromises of traditional fiber enrichment. Sports nutrition manufacturers in Germany and Australia are adopting these modified starches at accelerated procurement cycles. The technology is electrifying competitive positioning by enabling premium price points in categories previously resistant to functional ingredient costs.
REACH compliance requirements for novel food enzymes are extending safety dossier preparation timelines, forcing reformulation roadmaps to incorporate 24-month regulatory buffers. Industrial consequence includes consolidation of enzyme supply contracts among manufacturers with established EFSA novel food approval track records. Bakery applications utilizing new amylase variants face the steepest timeline compression, with several European projects delayed pending toxicology package completion.
Hospital procurement committees are embedding glycemic response certification into mandatory supplier scorecards, displacing incumbent vendors without ISO-compliant testing documentation. This specification tightening concentrates contract awards among manufacturers with captive clinical research capabilities. Germany's university hospital networks display the most aggressive certification requirements, with several systems now requiring batch-level glycemic testing documentation.
Low GI Food Market Segmentation
Low GI food purchasing decisions pivot on metabolic validation requirements, retail accessibility, and end-user health literacy. Segmentation reveals how formulation complexity, channel infrastructure, and clinical endorsement networks concentrate value across distinct buyer categories.
Product Type:
Buyers prioritize sensory familiarity and processing infrastructure maturity when selecting low GI carbohydrate formats.
- Grains:Modified wheat and rice starches achieve glycemic index values below 55 through enzymatic debranching or resistant starch enrichment. Hospital procurement networks in Germany specify certified low GI bread and pasta for diabetes discharge programs, leveraging established milling infrastructure and patient acceptance.
- Dairy:Protein-forward yogurts and beverages incorporate soluble fiber systems or specific lactose profiles to blunt glucose response. Sports nutrition manufacturers in Australia and Germany are accelerating procurement cycles for these formats, capturing premium shelf space in performance-focused retail channels.
- Fruits:Berries and stone fruits with naturally lower glycemic loads serve clean-label positioning for direct-to-consumer brands.
- Vegetables:Legumes and select root vegetables anchor meal replacement formulations targeting sustained energy release.
Grains lead on scale; dairy leads on momentum.
End User:
Prescription-adjacent recommendation networks command margin premiums over mass-market consumer channels.
- Healthcare Professionals:Clinical nutrition programs and hospital discharge protocols require ISO 26642-compliant glycemic testing documentation, creating procurement barriers that reward manufacturers with captive research capabilities. EU hospital systems embed these specifications into mandatory supplier scorecards.
- Dieticians:Registered practitioner networks drive high-margin direct-to-clinic sales through personalized meal planning recommendations, bypassing conventional retail marketing expenditure.
- Fitness Enthusiasts:Endurance athletes and sports nutrition consumers seek protein-integrated low GI solutions for sustained energy delivery during training protocols.
- General Public:Mainstream retail consumers display limited glycemic index literacy, constraining velocity and requiring point-of-sale education investments.
Healthcare professionals concentrate purchasing power; dieticians concentrate margin extraction.
Distribution Channel:
Channel selection determines compliance documentation requirements and price realization potential.
- Health Food Stores:Staff-trained environments support complex product education and certification storytelling, enabling premium positioning for substantiated low GI claims. These channels concentrate in Germany and Australia where functional food retail density supports specialized merchandising.
- Online Retailers:Direct-to-consumer platforms fragment purchasing patterns while enabling fitness platforms to target specific metabolic management segments with subscription-based nutrition programs.
- Supermarkets:Conventional grocery channels struggle with glycemic index comprehension gaps, limiting shelf space allocation without regulatory mandate.
- Specialty Shops:Diabetes-focused retailers and clinical nutrition boutiques serve prescription-adjacent demand with batch-level testing documentation.
Health food stores anchor premium pricing; online retailers anchor volume expansion.
Application:
Clinical validation depth separates high-margin nutrition protocols from commodity meal solutions.
- Diabetes Nutrition:Formulations targeting blood glucose management require EFSA Article 13.5 health claim substantiation or equivalent national regulatory approval, creating 12-18 month assessment timelines that limit competitive entry. Hospital procurement networks specify these certified products for standardized patient discharge programs.
- Sports Nutrition:Protein-forward low GI dairy beverages for endurance athletes represent underdeveloped white space with limited incumbent competition and premium pricing headroom.
- Weight Management:Satiety-focused formulations leverage soluble fiber enrichment to extend gastric emptying time and reduce caloric intake.
- Meal Replacement:Complete nutrition formats balance macronutrient profiles with controlled glycemic response for convenience-oriented consumers.
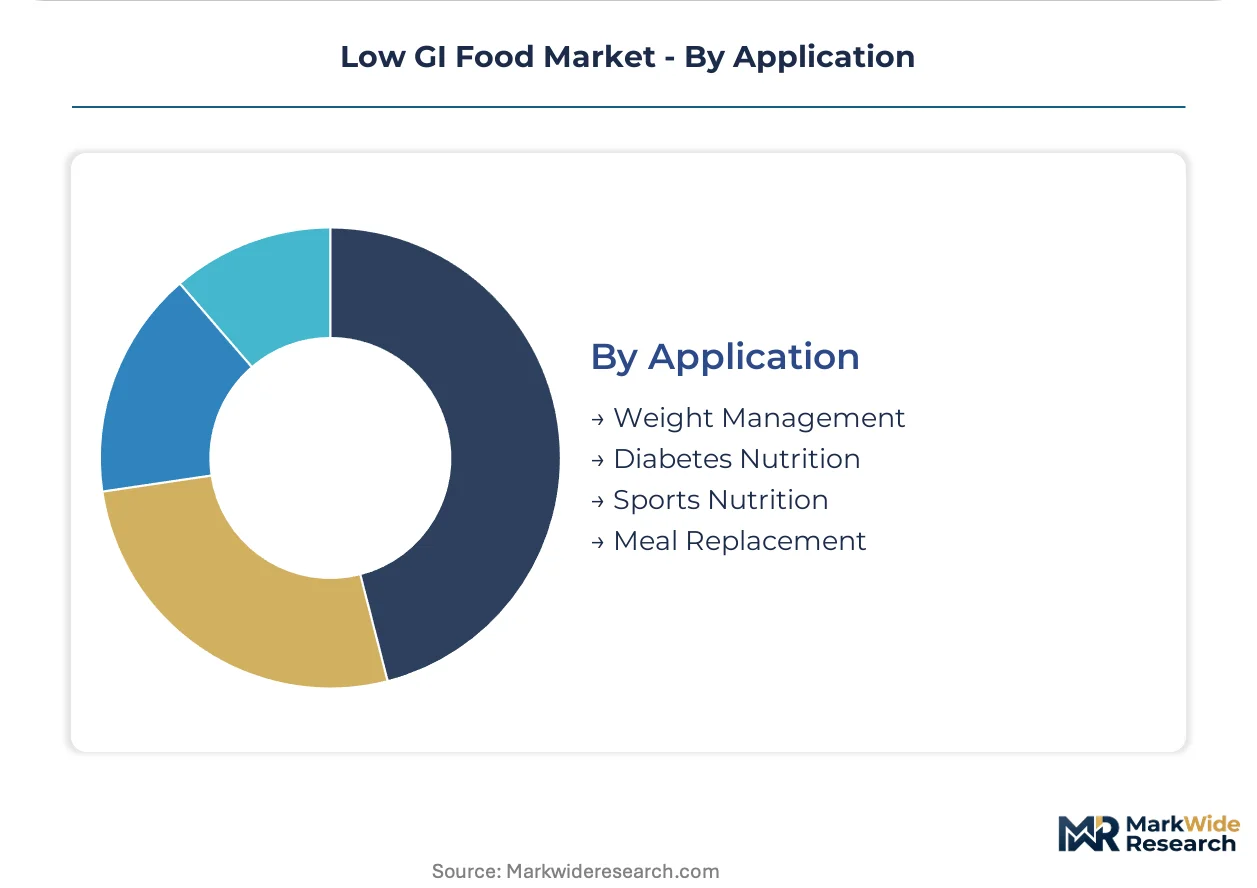
Diabetes nutrition commands margin depth; sports nutrition commands growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical nutrition specialists cluster in Germany's university hospital networks, while food technologists concentrate in Australia's sports nutrition hubs and Singapore's functional ingredient research parks. These talent concentrations anchor regional competitive positioning.
Germany
University hospital procurement committees mandate ISO 26642 glycemic testing documentation for diabetes discharge meal programs. EFSA Article 13.5 health claim protocols shape permissible marketing language across EU member states. Berlin and Munich anchor concentrated adoption corridors where functional food retail density intersects with elevated diabetes prevalence.
Australia
Sports nutrition manufacturers accelerate procurement cycles for protein-integrated low GI dairy beverages targeting endurance athletes. TGA recognition of glycemic index labeling supports voluntary nutrient disclosure frameworks. Sydney and Melbourne cluster specialized health food retail channels that support complex product education and premium positioning.
United States
FDA voluntary glycemic index disclosure policies influence label architecture without mandating standardized testing protocols. Hospital systems embed certified low GI formulations into standardized patient discharge programs. Chicago and Minneapolis concentrate milling infrastructure for modified wheat starch production serving institutional nutrition contracts.
China
National Health Commission dietary guidelines amplify low GI messaging through state-backed nutrition education channels targeting diabetes prevention. SAMR oversight of functional food claims creates regulatory clarity for substantiated products. Shanghai and Guangzhou anchor demand from Asia-Pacific functional food manufacturers seeking clean-label ingredient solutions.
Singapore
Food technology research parks attract enzymatic starch modification specialists developing resistant starch structures without synthetic additives. State investment in metabolic health innovation supports clinical validation infrastructure. Biopolis and one-north clusters concentrate R&D talent for plant-based fiber systems serving regional clean-label demand.
Low GI Food Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where scale advantages in procurement networks clash with agility in formulation innovation. Hospital supply contracts concentrate among manufacturers with captive clinical research capabilities, while direct-to-consumer channels fragment toward niche positioning. Three archetypes dominate: multinational nutrition conglomerates with institutional infrastructure, specialty ingredient technology providers, and emerging plant-based formulation specialists. Competitive moves center on backward integration into resistant starch supply and strategic partnerships with registered dietitian recommendation networks.
Within the multinational tier, Nestle leverages clinical nutrition infrastructure to anchor institutional supply contracts across European healthcare systems. Ingredion competes through specialty starch modification technologies that reduce glycemic response in processed formulations. Alchemy Foodtech represents the emerging specialist archetype, positioning plant-based fiber systems to capture demand from Asia-Pacific functional food manufacturers seeking clean-label solutions.
| Leading Market Players |
|---|
| Nestle |
| PepsiCo |
| Cargill |
| Ingredion |
| Tate & Lyle |
| Archer Daniels Midland |
| EID Parry |
| General Mills |
| Alchemy Foodtech |
| Others |
Pricing and Supply Chain Analysis
Specialty resistant wheat starch costs cascade from North American grain processors through three distinct pricing tiers downstream, with enzymatic modification premiums widening spreads between certified clinical-grade formulations and conventional retail alternatives.
Pricing Analysis
Bundled certification-and-testing services command substantial premiums over unbundled commodity formulations. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated clinical products from voluntary-label retail goods and unverified mass-market alternatives. Price differentiation hinges on ISO 26642 compliance documentation and captive clinical research infrastructure. Pricing pressure stems from hospital procurement consolidation in Germany, squeezing mid-tier suppliers without vertical integration into resistant starch supply. Healthcare professionals demonstrate lowest price sensitivity due to reimbursement-adjacent procurement protocols, while general retail consumers resist functional food premiums without regulatory mandate.
Supply Chain Analysis
Reverse-logistics flows for expired or non-conforming glycemic-certified products remain underdeveloped, creating working capital drag for distributors managing batch-level testing documentation. Upstream supply concentrates in the United States, Canada, and Australia, where specialty grain processors control resistant wheat starch and enzymatic modification capacity. Formulation draws from amylopectin debranching enzymes, soluble fiber systems, and modified starch structures. Single-source vulnerability in North American specialty starch supply exposes European manufacturers to currency and tariff volatility. Distribution runs through health food retail channels in Germany and Australia, hospital procurement networks, and direct-to-clinic dietitian recommendation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU clinical nutrition premiums and Asia-Pacific clean-label manufacturing costs, with EFSA substantiation requirements creating regulatory moats that justify European price premiums against lower-cost Asian production bases.
For Market Incumbents: Anticipate margin compression from enzymatic starch modification technology diffusion by securing backward integration into resistant starch supply and embedding ISO 26642 testing capabilities within captive clinical research infrastructure. Hospital procurement consolidation in Germany threatens non-integrated suppliers; certification investment serves as the critical defensive lever.
For New Entrants and Emerging Players: Enzymatic debranching technology offers entry wedge into sports nutrition white space, where protein-integrated low GI dairy beverages for endurance athletes remain underpenetrated with limited incumbent competition. Target Australia's specialized health food retail channels through direct-to-clinic dietitian recommendation networks, bypassing conventional marketing expenditure.
For Investors and Strategic Acquirers: Roll-up economics work for plant-based fiber system specialists because clean-label demand from Asia-Pacific functional food manufacturers concentrates contract awards among providers with EFSA novel food approval track records. Five-to-ten-year viability hinges on regulatory tailwind persistence; monitor China's National Health Commission guideline amplification intensity as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Article 13.5 Health Claim Submission | Substantiation unlocks premium pricing in EU hospital procurement networks. |
| Backward Integration into Resistant Starch Supply | Captive sourcing mitigates North American supply concentration risk. |
| Direct-to-Clinic Distribution Partnership | Dietitian recommendation networks capture prescription-adjacent margin pools. |
| Enzymatic Modification Capacity Expansion | Clean-label positioning opens conventional bakery reformulation opportunities. |
| Asia-Pacific Manufacturing Footprint | Proximity to China's state-backed nutrition education channels reduces go-to-market friction. |
Research Methodology
Bottom-up clinical nutrition and sports nutrition demand modeling reconciled against top-down specialty ingredient supply tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, registered dietitians, formulation chemists, and sports nutrition brand executives combined with secondary validation from EFSA health claim registers, ISO 26642 testing documentation, and hospital supplier scorecard specifications. Triangulation across these sources calibrated market sizing and competitive positioning assessments.
Historical trendline analysis of glycemic-certified product adoption across diabetes discharge protocols and sports nutrition applications established baseline growth trajectories. The analytical framework modeled segmentation dimensions including product type, end user archetype, distribution channel, and application across the projection horizon. CAGRs derived from weighted average of clinical procurement growth rates and retail velocity assumptions, incorporating EFSA regulatory timeline impacts and enzymatic technology adoption curves as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA glycemic claims pathway evolution and REACH compliance timeline compression for novel food enzymes. Practitioners should monitor hospital procurement committee certification requirement tightening and China's National Health Commission guideline updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Reduced Salt Food Products Market