
 India Sodium Reduction Ingredients Market | 2026-2036
India Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
India Sodium Reduction Ingredients Market Foresight
Mid-sized regional food manufacturers are reorganizing procurement priorities around clean-label sodium alternatives, displacing legacy reliance on basic salt substitutes among multinational quick-service chains. Tata Chemicals Limited leverages its integrated soda ash and specialty salt infrastructure to dominate bulk mineral salt supply for institutional buyers. Cargill India Pvt. Ltd. competes through flavor systems that mask potassium chloride off-notes in savory applications. Kerry Group plc anchors premium positioning with taste-modulation technologies tailored to masala and pickle segments where sodium reduction meets regional palatability thresholds.
Sodium reduction ingredients comprise functional compounds—potassium chloride, yeast extracts, amino acid-based enhancers, and mineral blends—engineered to replicate sodium chloride's osmotic, preservative, and sensory properties while delivering sub-140 mg sodium per serving in reformulated products. Their primary commercial purpose centers on enabling processed food compliance with progressive sodium caps without sacrificing shelf stability or consumer acceptance. Mineral salts command the deepest margin pools due to technical barriers in taste optimization and supply concentration among chlor-alkali derivatives, while flavor enhancers represent the fastest-expanding category as clean-label yeast and vegetable extracts displace synthetic alternatives in snack and sauce applications.
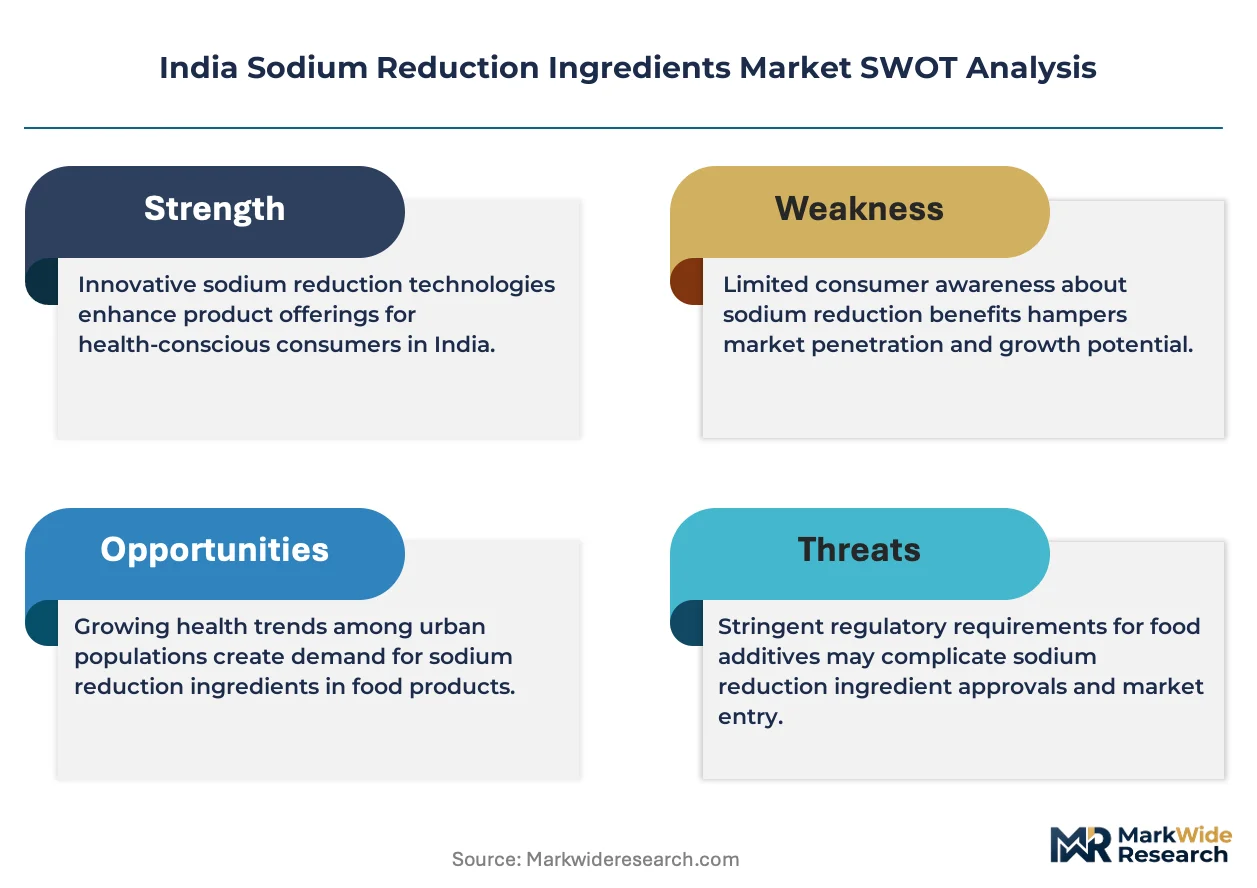
FSSAI's draft labeling regulations and proposed front-of-pack warning symbols for high-sodium products are tightening formulation standards and accelerating R&D budgets across domestic food manufacturers. BIS certification requirements for food-grade potassium chloride and the PLI scheme's food processing incentives are reshaping ingredient sourcing patterns toward domestic mineral salt value chains. Stakeholders must monitor evolving state-level enforcement intensity and the trajectory of consumer willingness-to-pay for reduced-sodium premium positioning against persistent price sensitivity in mass-market segments.
Market Dynamics
FSSAI's tightening sodium caps for packaged foods are forcing processed food manufacturers to reformulate entire product portfolios, triggering a wholesale reorganization of ingredient procurement priorities across Maharashtra and Gujarat's dense food processing clusters.
Growth Catalysts
- FSSAI Front-of-Pack Labeling Mandate:Draft regulations requiring warning symbols on high-sodium packaged goods are compelling instant noodle and snack manufacturers to accelerate reformulation timelines.
- Yeast Extract Technology:Clean-label umami enhancers derived from baker's yeast are displacing synthetic flavor boosters in sauce and seasoning applications without triggering allergen labeling requirements.
- PLI Scheme Incentives:Production-linked incentives for food processing infrastructure are expanding domestic mineral salt refining capacity, shortening supply chains for regional manufacturers in Gujarat.
Market Restraints
- Potassium Chloride Supply Concentration:Domestic production of food-grade potassium chloride remains concentrated among chlor-alkali derivatives from Gujarat's chemical belt, creating single-source vulnerability.
- Bitterness Masking Costs:Technical limitations in masking metallic off-notes from mineral salt substitutes require expensive flavor system overlays that compress margins in mass-market biscuits.
- BIS Certification Delays:Bureau of Indian Standards approval timelines for novel sodium reduction compounds extend commercialization cycles by 18-24 months.
Strategic Opportunities
- Uttar Pradesh Food Processing Corridor:Underpenetrated demand from emerging snack manufacturing units in Noida and Greater Noida offers first-mover positioning for mineral salt distributors.
- Pickle and Chutney Segment:Traditional preservation applications represent untapped white space where amino acid-based enhancers can replace salt without altering shelf stability.
- State-Level Enforcement Divergence:Maharashtra's proactive food safety cell inspections create premium positioning opportunities for certified reduced-sodium products versus neighboring states with weaker enforcement.
Industry Challenges
- Flavor Chemist Talent Scarcity:Reformulation of masala profiles requires specialized sensory scientists familiar with regional palatability thresholds, a skill set concentrated among retired Unilever and Nestle India veterans.
- Legacy Equipment Retrofit Costs:Salt reduction alters dough rheology and brine osmolarity, forcing bakeries and meat processors to recalibrate mixing and injection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sodium Reduction Ingredients Market |
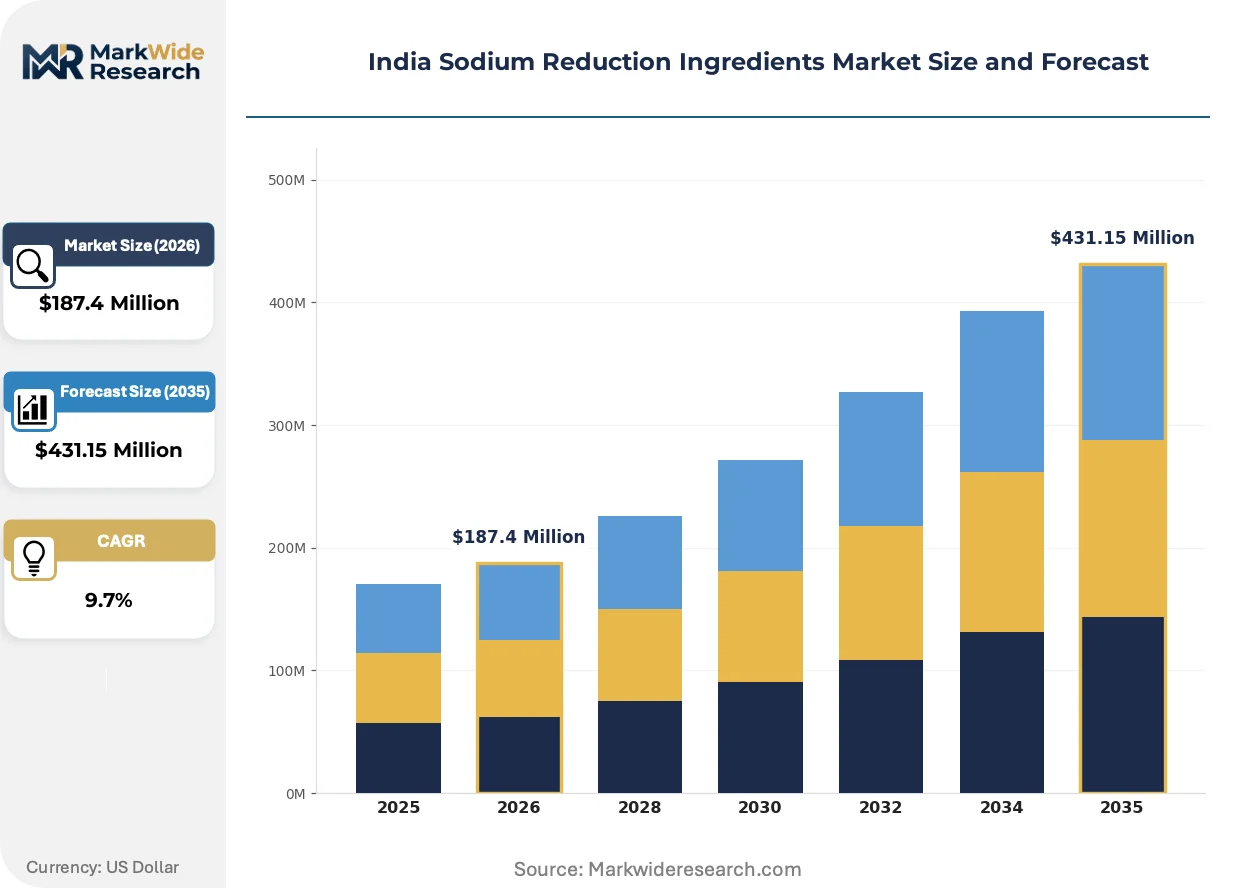
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Mineral Salts, Natural Extracts Application: Processed Foods, Snacks, Dairy Products, Sauces End User: Food Manufacturers, Catering Services, Retail Outlets, Consumers Form: Powder, Liquid, Granules, Tablet |
| Companies Covered | Tata Chemicals Limited, Cargill India Pvt. Ltd., Kerry Group plc, Archer Daniels Midland Company, Tate & Lyle PLC, DSM Nutritional Products, Givaudan, Ajinomoto Co., Inc., Bunge Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sodium Reduction Ingredients Market Shifts & Advancements
Clean-label ingredient portfolios are displacing synthetic sodium alternatives across India's processed food sector, with technology convergence between mineral salt processing and precision fermentation creating new formulation possibilities.
Encapsulated potassium chloride is fragmenting the conventional mineral salt category by enabling timed-release sodium reduction in heat-processed snacks. Haldiram's and Balaji Wafers are piloting microencapsulated formulations in their Maharashtra facilities to mask bitterness without flavor system overlays. This delivery technology is compressing the addressable market for basic potassium chloride by demanding higher-value modified mineral salts.
FSSAI's proposed sodium thresholds for packaged foods are tightening labeling standards ahead of formal adoption. The draft regulations mandate per-serving sodium disclosure alongside front-of-pack warning symbols for products exceeding 140 mg per serving. Instant noodle manufacturers in Gujarat's Ahmedabad-Surat corridor are pre-emptively reformulating to avoid classification as high-sodium products.
Direct procurement contracts between ingredient suppliers and mid-sized regional food manufacturers are displacing traditional distributor networks in sodium reduction ingredient sourcing. Karnataka and Tamil Nadu-based snack producers now negotiate annual mineral salt supply agreements directly with Tata Chemicals, bypassing Mumbai-based trading houses. This channel shift is most visible in South India's organized retail supply chains where traceability requirements favor documented direct relationships.
India Sodium Reduction Ingredients Market Segmentation
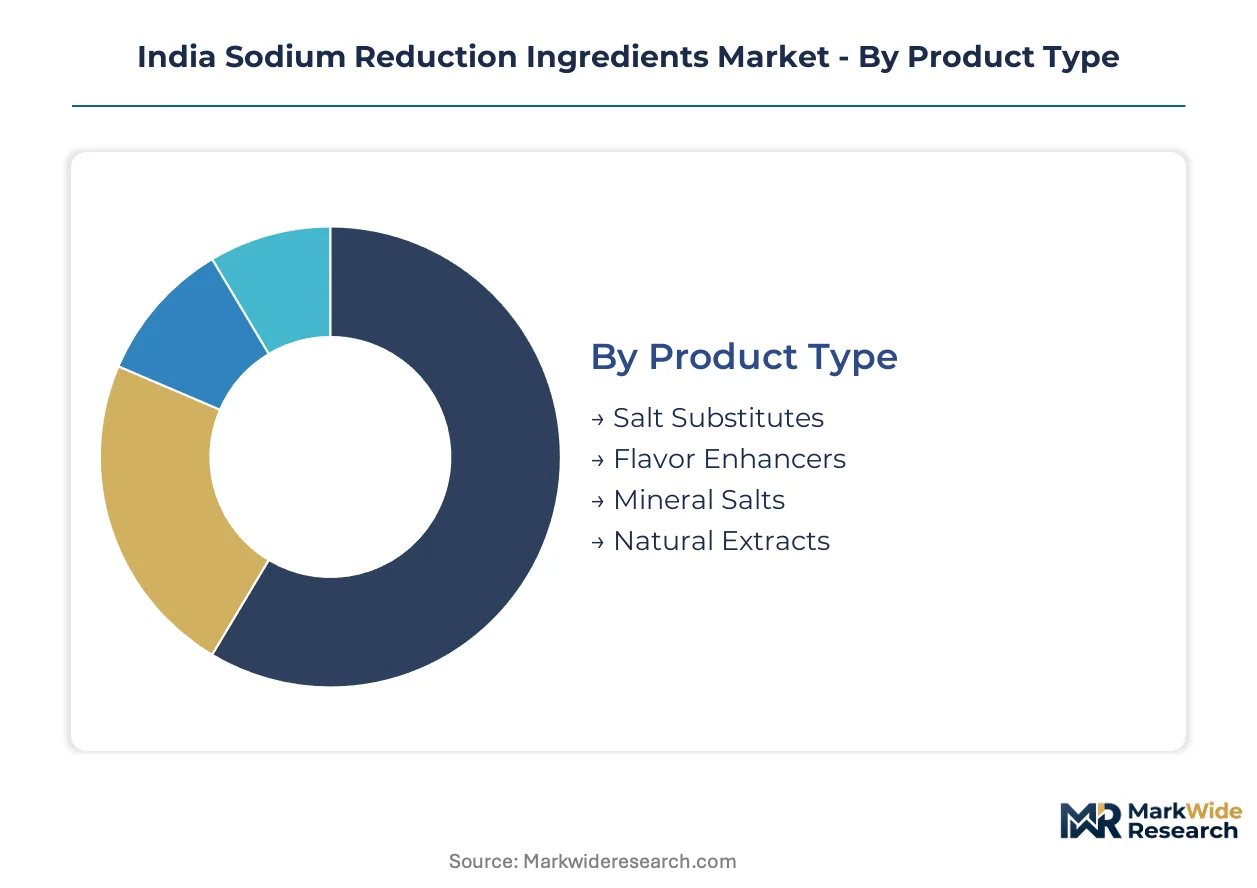
Segmentation reveals how sodium reduction ingredients traverse distinct technical specifications and procurement channels across India's food processing belt. Each category exposes divergent margin structures and regulatory exposure that reshape supplier strategies.
Product Type:
Domestic production of mineral salts and salt substitutes concentrates in Gujarat's chemical corridor, while flavor enhancers and natural extracts draw heavier import dependency from European fermentation specialists.
- Salt Substitutes:Potassium chloride and potassium-based compounds engineered to replicate sodium chloride's osmotic and preservative functions. Demand clusters in Maharashtra's instant noodle and bakery clusters where FSSAI sodium caps are enforced most aggressively.
- Flavor Enhancers:Yeast extracts, amino acids, and nucleotide-based compounds that amplify umami perception without sodium loading. Gujarat's snack manufacturers are displacing synthetic MSG with clean-label alternatives to avoid front-of-pack warning symbols.
- Mineral Salts:Blended potassium-magnesium-calcium formulations processed from chlor-alkali derivatives. Tata Chemicals anchors domestic supply for institutional buyers seeking BIS-certified food-grade material.
- Natural Extracts:Seaweed-derived flavor modulators and vegetable-based sodium replacers. Import volumes from South Korean suppliers are climbing as premium sauce manufacturers reformulate for export markets.
Mineral salts hold the largest share; momentum sits with flavor enhancers.
Application:
Cost tier differentiation separates mass-market reformulation from premium positioning, with snack and sauce applications absorbing higher ingredient premiums than processed foods.
- Processed Foods:Frozen meals, ready-to-eat curries, and canned vegetables requiring shelf-stable sodium reduction. Maharashtra's Thane-Pune corridor drives procurement volume as manufacturers pre-empt FSSAI labeling mandates.
- Snacks:Extruded products, chips, and namkeen where salt visibility directly impacts consumer acceptance. Encapsulated potassium chloride is gaining traction in Haldiram's and Balaji Wafers reformulation pipelines.
- Dairy Products:Cheese, butter, and fermented milk applications where sodium reduction intersects with preservation requirements. Technical barriers remain highest in this segment due to microbial stability constraints.
- Sauces:Ketchup, soy sauce, and chutney formulations where umami enhancement masks mineral salt off-notes. South Indian manufacturers in Karnataka are piloting amino acid-based enhancers for regional pickle applications.
Processed foods anchor volume demand; sauces are expanding most quickly on clean-label premiumization.
End User:
Customer type fragmentation splits procurement between price-sensitive institutional buyers and specification-driven retail channels with divergent compliance documentation requirements.
- Food Manufacturers:Mid-sized regional processors in Gujarat and Maharashtra reorganizing procurement around direct supplier contracts. Annual mineral salt agreements with Tata Chemicals are displacing Mumbai-based distributor networks.
- Catering Services:Institutional kitchens and cloud kitchen aggregators facing indirect regulatory pressure through client audit requirements. Bulk purchasing favors basic potassium chloride over modified mineral salts.
- Retail Outlets:Organized supermarket chains and e-commerce platforms driving traceability documentation. Direct procurement relationships are shortening supply chains for South India's retail networks.
- Consumers:Household purchasers of table-top salt substitutes and reduced-sodium seasonings. Urban Maharashtra and Delhi-NCR show highest willingness-to-pay for premium positioning.
Food manufacturers command the deepest volume; retail outlets are gaining share fastest on traceability mandates.
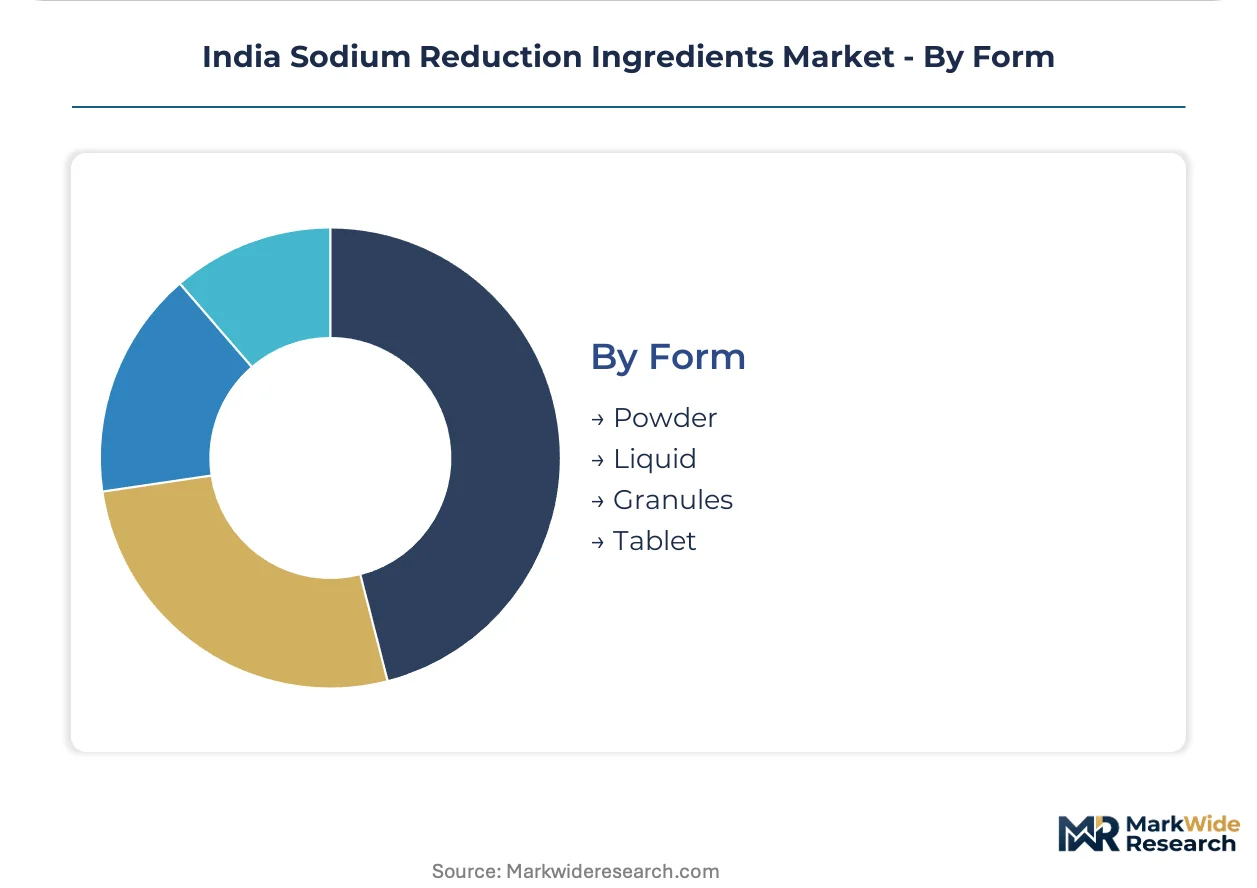
Form:
Supply concentration in powder processing creates margin pressure for liquid and granule specialists serving niche application requirements.
- Powder:Standardized crystalline and milled formulations for dry blending applications. Dominates mineral salt and salt substitute categories with established BIS certification pathways.
- Liquid:Brine-based solutions for meat injection and sauce formulation. Limited domestic production capacity constrains adoption outside multinational quick-service chains.
- Granules:Agglomerated and spray-dried formats for controlled dissolution in heat-processed snacks. Encapsulation technology is fragmenting this category toward higher-value modified structures.
- Tablet:Compressed salt substitutes for direct consumer table-top use. Smallest segment with concentrated demand in urban household channels.
Powder forms dominate supply; granules show steepest expansion trajectory on encapsulation technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlor-alkali derivatives from Gujarat's chemical belt supply the bulk of food-grade mineral salts, concentrating upstream capacity in western India while downstream formulation demand fragments across state-level food processing clusters.
Maharashtra
Instant noodle manufacturers in Thane-Pune corridor drive potassium chloride procurement volumes as FSSAI enforcement tightens sodium disclosure requirements. The state's food safety cell conducts proactive inspections of packaged goods, compelling reformulation ahead of national mandate adoption. Mumbai-based trading houses are losing ground to direct supplier contracts as regional processors seek documented traceability.
Gujarat
Ahmedabad-Surat snack producers are pre-emptively reformulating to avoid front-of-pack warning symbols under draft FSSAI regulations. PLI scheme incentives are expanding domestic mineral salt refining capacity, shortening supply chains for regional manufacturers. Haldiram's and Balaji Wafers pilot encapsulated potassium chloride formulations in local facilities to mask bitterness without flavor system overlays.
Karnataka
South Indian sauce manufacturers in Bengaluru-Mysuru belt are piloting amino acid-based enhancers for regional pickle applications where sodium reduction intersects with preservation requirements. Organized retail networks here favor direct procurement relationships with documented supply chain traceability. State-level food safety enforcement remains less aggressive than western counterparts, slowing premium positioning for certified reduced-sodium products.
Tamil Nadu
Chennai-based dairy processors face technical barriers in sodium reduction due to microbial stability constraints in cheese and fermented milk applications. The state's snack manufacturing units in Coimbatore-Tiruppur corridor absorb higher ingredient premiums than mass-market biscuit producers elsewhere. Import volumes of seaweed-derived flavor modulators are climbing as premium sauce manufacturers reformulate for export markets.
Delhi-NCR
Urban household channels in Delhi-NCR show highest willingness-to-pay for premium table-top salt substitutes among Indian metros. Cloud kitchen aggregators face indirect regulatory pressure through client audit requirements, favoring basic potassium chloride over modified mineral salts. The region's underpenetrated demand from emerging snack manufacturing units in Noida and Greater Noida offers first-mover positioning for mineral salt distributors.
India Sodium Reduction Ingredients Market Competitive Landscape
Concentration sits with integrated chemical conglomerates controlling chlor-alkali feedstock and specialty salt infrastructure, while flavor system specialists compete through taste-modulation technologies. The market structures around three archetypes: bulk mineral salt suppliers with backward integration into soda ash production, flavor enhancer developers masking potassium chloride off-notes, and clean-label extract importers serving premium export-oriented manufacturers. Dominant competitive moves include direct procurement contract expansion with mid-sized regional food processors and encapsulation technology licensing to displace basic salt substitutes.
Within the integrated chemical tier, Tata Chemicals Limited anchors domestic supply for institutional buyers seeking BIS-certified food-grade material. Cargill India Pvt. Ltd. occupies a position among flavor system developers, while Kerry Group plc exemplifies the premium taste-modulation specialist archetype. These three represent distinct strategic postures: captive mineral salt production versus outsourced flavor masking versus regional palatability customization. Smaller regional distributors are consolidating around documented traceability capabilities as organized retail procurement shifts toward direct supplier relationships.
| Leading Market Players |
|---|
| Tata Chemicals Limited |
| Cargill India Pvt. Ltd. |
| Kerry Group plc |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| DSM Nutritional Products |
| Givaudan |
| Ajinomoto Co., Inc. |
| Bunge Limited |
| Others |
Supply & Pricing Matrix
Encapsulated potassium chloride displacing basic mineral salts in Maharashtra's snack processing corridors simultaneously concentrates supply geography in Gujarat's chlor-alkali belt and compresses pricing economics for unmodified potassium chloride. This substitution dynamic rewards suppliers with flavor-masking capabilities while eroding margins for commodity-grade mineral salt traders.
Pricing Analysis
FSSAI's draft front-of-pack labeling mandate dictates the pricing tier structure across India's sodium reduction ingredient market. Three-tier pricing structure across premium, standard, and economy levels separates encapsulated mineral salts with bitterness-masking technology from basic potassium chloride and ungraded salt substitutes. Price differentiation rests on BIS certification status and flavor system integration depth. Cost compression in economy-tier mineral salts is intensifying because mid-sized regional manufacturers negotiate direct procurement contracts that bypass Mumbai-based trading margins. Mass-market biscuit producers exhibit highest price sensitivity, while export-oriented sauce manufacturers absorb premium positioning for documented traceability.
Supply Chain Analysis
Inventory cycles for food-grade potassium chloride extend 45-60 days due to BIS certification batch testing requirements, constraining just-in-time procurement for reformulating manufacturers. Geographic supply concentration centers on India for chlor-alkali derivatives, with secondary sourcing from South Korea for seaweed-derived flavor modulators and European fermentation specialists for yeast extracts. Raw material dependencies draw from soda ash feedstock, baker's yeast biomass, and marine algae harvesting. Single-source vulnerability pervades Gujarat's chemical belt where domestic food-grade potassium chloride production concentrates among integrated chlor-alkali operators. Distribution runs through direct supplier contracts with mid-sized regional food manufacturers, displacing traditional Mumbai-based trading houses in Maharashtra and South India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India sodium reduction ingredients market rewards specialized formulation capabilities that remain scarce among domestic suppliers, with flavor chemist expertise concentrated among retired multinational veterans and encapsulation technology licensing controlled by a narrow supplier tier.
For Market Incumbents: Secure backward integration into chlor-alkali feedstock to defend margin position against imported mineral salt alternatives. Anchor direct procurement relationships with mid-sized regional manufacturers in Uttar Pradesh's emerging food processing corridor to preempt distributor network consolidation. Prioritize BIS certification maintenance for food-grade potassium chloride to sustain institutional buyer lock-in as FSSAI enforcement tightens labeling standards. For New Entrants and Emerging Players: BIS certification fast-track for novel amino acid-based enhancers unlocks first-mover positioning in Karnataka's underpenetrated pickle and chutney segment. Target Uttar Pradesh's Noida-Greater Noida snack manufacturing cluster where mineral salt distributor networks remain thin. Lead with documented supply chain traceability to capture organized retail procurement shifting away from undocumented trading relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional flavor system developers possessing encapsulated mineral salt technology but lacking national distribution reach. Long-term viability hinges on regulatory enforcement trajectory rather than consumer preference shifts alone. Acquisition target archetype: mid-cap specialists with BIS-certified production and direct contracts with Maharashtra's instant noodle manufacturers. Watch FSSAI's formal adoption timeline for front-of-pack warning symbols as inflection indicator for reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Enables bitterness masking in heat-processed snacks without flavor system overlays, compressing addressable market for basic potassium chloride. |
| Direct Procurement Contract Expansion | Shortens supply chains for regional manufacturers in Gujarat and Maharashtra while displacing Mumbai-based trading house margins. |
| BIS Certification Investment | Accelerates commercialization timelines for novel sodium reduction compounds currently delayed by 18-24 month approval cycles. |
| Backward Integration into Soda Ash | Captures captive supply of chlor-alkali feedstock for food-grade mineral salt production, insulating against imported substitute pricing. |
| Regional Flavor System Customization | Addresses masala and pickle palatability thresholds where sodium reduction intersects with regional taste preferences in South India. |
Research Methodology
The analysis maps mineral salt processing, flavor enhancer fermentation, and encapsulation technology sub-sectors, each validated through procurement directors at mid-sized regional food manufacturers, flavor chemists at multinational quick-service chains, and regulatory affairs specialists navigating FSSAI labeling mandates. Primary interviews with plant managers at Gujarat's chlor-alkali facilities, R&D directors developing clean-label yeast extracts, and category buyers at organized retail chains combined with secondary validation from BIS certification databases, FSSAI draft regulation filings, and PLI scheme disbursement records. Bottom-up volume triangulation across product type and application segments reconciled with top-down market sizing from customs trade data and food processing industry association reports.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, application, end user, and form, with additional granularity on state-level enforcement intensity and certification status tiers. CAGRs were derived from regression analysis of historical procurement patterns and regulatory adoption curves, incorporating inputs from PLI scheme capacity expansion timelines and FSSAI mandate implementation phasing.
Underlying assumptions cover progressive FSSAI enforcement adoption, sustained PLI scheme incentives for food processing infrastructure, and stable chlor-alkali feedstock availability from Gujarat's chemical belt, with deviation risk concentrated in BIS certification timeline delays and consumer willingness-to-pay elasticity for reduced-sodium premium positioning. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Phytosterols Market
Ingredients
Lipids Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Sodium Alginate Market
Ingredients
Liquid Egg Market
Ingredients
Pea Flour Market
Ingredients
Europe Fats and Oil Market
Ingredients
Revivable Yeast Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
North America Vegetable Oils Market
Ingredients
Non-GMO Oil Market
Ingredients
Interesterified CBE Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Maracuja Oil Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Sodium Reduction Ingredients Market