
 India Gluten-Free Food and Beverage Market | 2026-2036
India Gluten-Free Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
India Gluten-Free Food and Beverage Market Foresight
Maharashtra's food processing corridor is narrowing the supply gap between imported gluten-free inputs and domestic formulation capacity. KRBL Limited leverages its rice-milling infrastructure to anchor gluten-free flour production for northern Indian markets. ITC Limited sustains broad distribution reach through its supermarket and convenience store networks. Dr. Schär AG competes on European formulation standards, positioning its imported bakery lines for affluent consumers in Delhi and Mumbai.
India gluten-free food and beverage encompasses products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting rice flour, almond flour, quinoa, or corn starch to achieve equivalent texture and shelf stability. Manufacturers employ enzymatic treatment and dedicated facility protocols to maintain gluten levels below the FSSAI-mandated threshold. Snacks and beverages command the largest current revenue pools, while bread and pasta segments attract premium pricing due to technical complexity in achieving structural integrity without gluten proteins. Health-conscious consumers represent the fastest-growing end-user cohort, outpacing diagnosed celiac disease patients in absolute volume terms.
FSSAI enforces gluten-free labeling thresholds and facility certification requirements that determine market access for domestic producers and importers alike. BIS standards for alternative flours and the PLI scheme for food processing infrastructure shape capital deployment decisions across manufacturing hubs. Stakeholders must monitor regulatory alignment between state-level food safety enforcement and evolving FSSAI notification timelines to secure first-mover positioning in emerging distribution channels.
Market Dynamics
FSSAI's mandatory gluten-free labeling standards are compressing formulation timelines while forcing domestic manufacturers to upgrade dedicated facility infrastructure ahead of enforcement deadlines.
Growth Catalysts
- Millet-based ingredient innovation:Sorghum and ragi flour substitution protocols developed at Indian agricultural institutes are reducing dependency on imported rice flour bases for snack formulations.
- FSSAI facility certification requirements:Mandatory third-party gluten threshold testing below 20 ppm is creating quality differentiation that premium urban retailers reward with shelf placement priority.
- Urban Maharashtra health-conscious cohorts:Mumbai and Pune consumers diagnosed with gluten sensitivity are expanding weekly purchase frequency beyond festival-season spikes into sustained household stocking patterns.
Market Restraints
- Imported enzyme cost volatility:Transglutaminase and xylanase inputs sourced from European suppliers expose domestic formulators to euro-rupee exchange rate swings that compress gross margins.
- Rice flour supply concentration:Basmati processing clusters in Haryana and Punjab control over 70% of food-grade rice flour suitable for gluten-free baking, creating geographic chokepoints.
- Structural shelf-life limitation:Absence of gluten protein networks reduces moisture retention in bread products, constraining distribution radius for fresh bakery lines without preservative loading.
Strategic Opportunities
- Karnataka underpenetrated tier-2 corridors:Mysuru and Mangaluru retail networks lack dedicated gluten-free aisles, presenting first-mover positioning for regional brand building ahead of national label entry.
- PLI scheme food processing incentives:Capital subsidy provisions for millet valorization infrastructure lower breakeven thresholds for domestic manufacturers investing in dedicated gluten-free milling lines.
- Direct-to-consumer subscription channels:Monthly curated snack boxes bypass traditional distributor markups while capturing consumer preference data for iterative product development cycles.
Industry Challenges
- Certified food technologist scarcity:Gluten-free formulation expertise requiring cross-training in cereal chemistry and enzymology commands salary premiums that strain mid-cap manufacturer payroll structures.
- FSSAI compliance timeline compression:Notification-to-enforcement windows as short as 180 days force simultaneous facility retrofitting, staff retraining, and label redesign without phased implementation relief.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gluten-Free Food and Beverage Market |
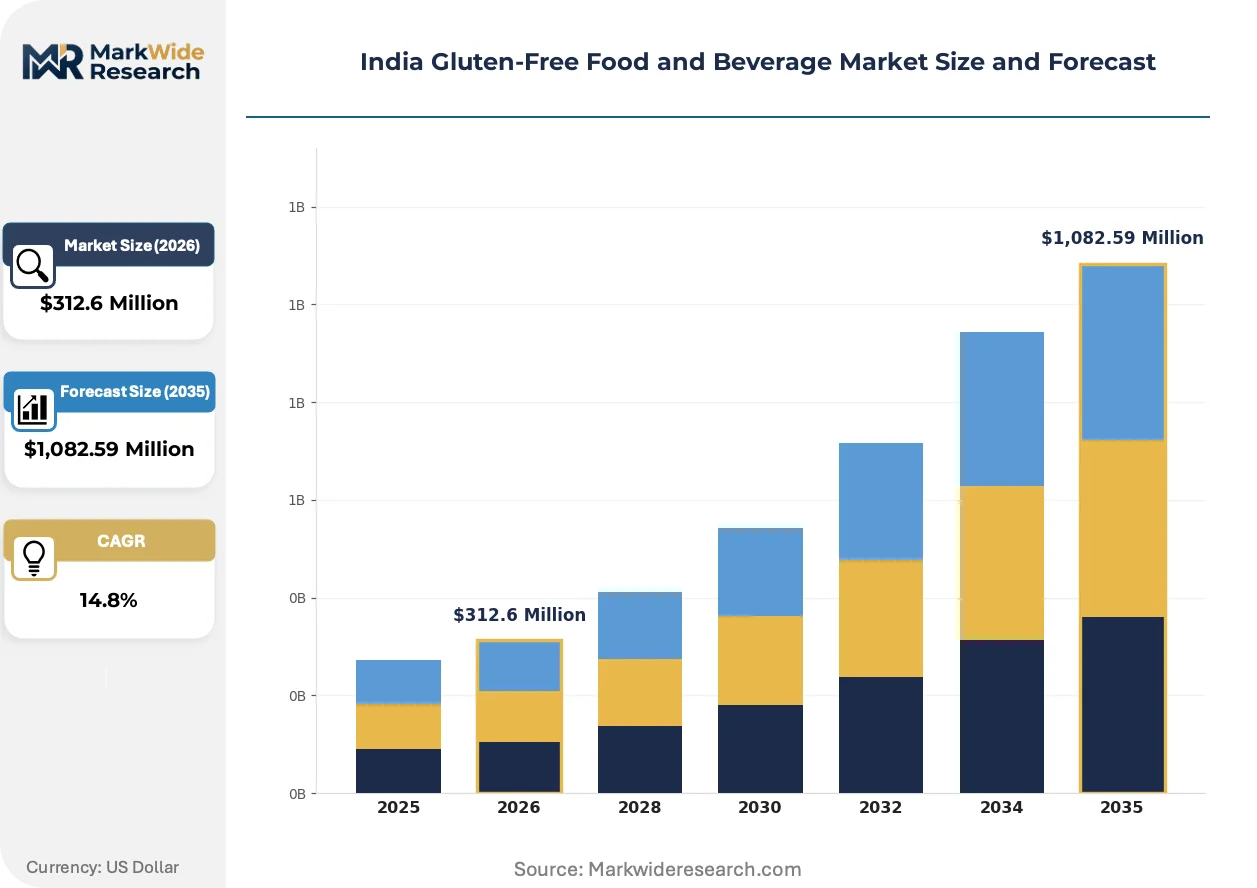
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,082.59 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Pasta, Bread, Beverages End User: Individuals with Celiac Disease, Health-Conscious Consumers, Athletes, Families Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Ingredient Type: Rice Flour, Almond Flour, Quinoa, Corn Starch |
| Companies Covered | KRBL Limited, Kraft Heinz Company, Dr. Schär AG, Mondelez International Inc., Genius Foods, General Mills Inc., Amy's Kitchen Inc., Bob's Red Mill, ITC Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gluten-Free Food and Beverage Market Shifts & Advancements
Ingredient science and regulatory precision are converging to redefine acceptable texture benchmarks while digital channels fragment traditional distribution hierarchies across Indian metropolitan markets.
Enzymatic treatment technology is hybridizing conventional starch modification with targeted protein cross-linking to simulate gluten's viscoelastic properties in millet-based dough systems. Mid-tier bakeries in Bengaluru and Hyderabad are piloting these protocols at commercial scale. The approach is compressing the performance gap between domestic formulations and imported European benchmarks.
FSSAI's 2023 gluten-free labeling notification mandates quantitative threshold disclosure and prohibits cross-contamination claims without facility audit documentation. Domestic manufacturers must segregate production lines or absorb third-party certification costs. Snack producers in Maharashtra and Gujarat are responding fastest, restructuring plant layouts ahead of state-level enforcement variance.
Urban consumers are consolidating purchase decisions around FSSAI certification marks rather than brand heritage, displacing loyalty-based selection with verification-driven preference. Modern trade channels in Delhi and Mumbai are responding by featuring certified SKUs in dedicated health-food sections. This rotation is most visible among health-conscious professionals aged 28-40 purchasing weekly grocery baskets through organized retail formats.
India Gluten-Free Food and Beverage Market Segmentation
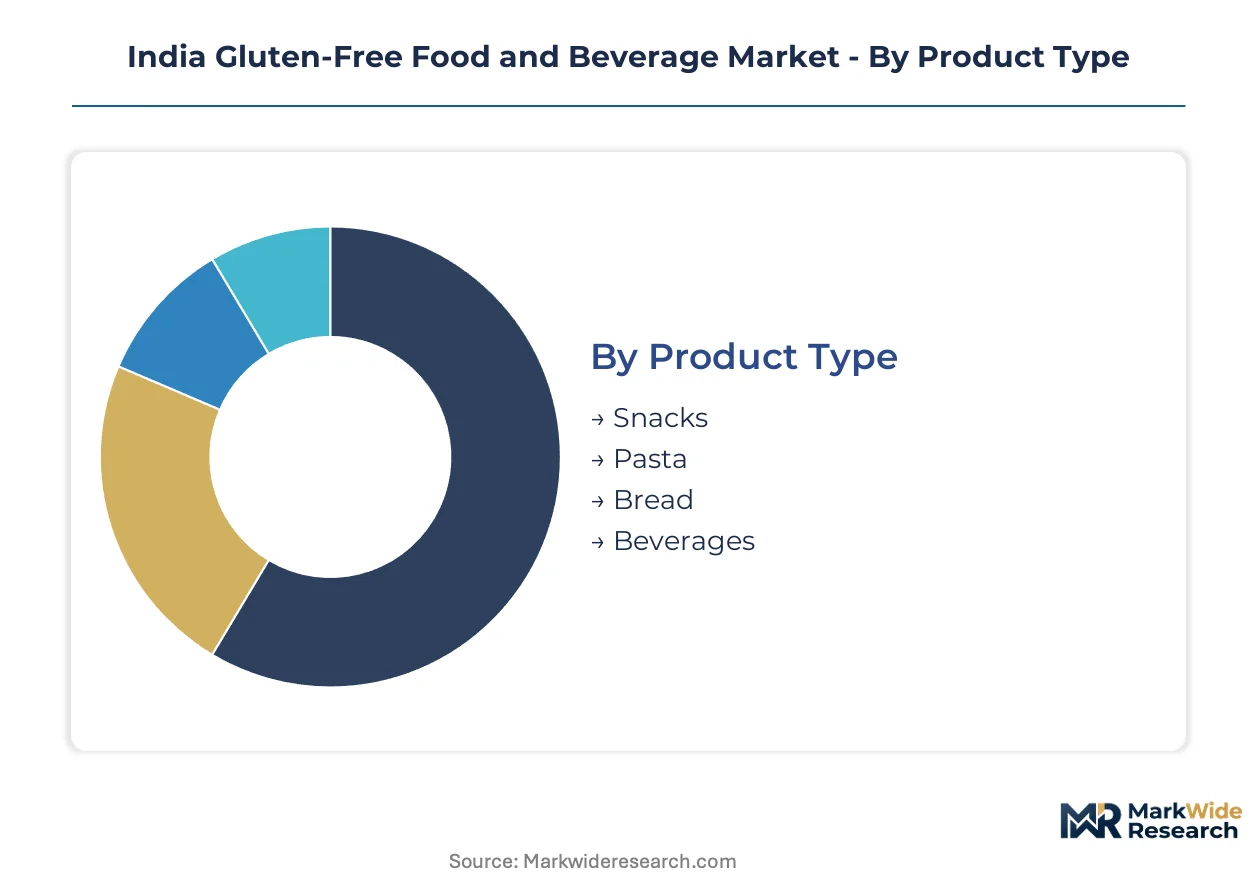
Segmentation in India's gluten-free market exposes divergent formulation requirements across consumer health profiles and retail channel economics. Product architecture and distribution access determine margin capture more than volume scale alone.
Product Type:
Cost tier stratification separates premium-positioned bakery lines from mass-market snack formulations.
- Snacks:Extruded and baked formats using rice flour or millet bases dominate shelf-stable portfolios. Maharashtra and Karnataka urban households stock these for daily consumption, with FSSAI certification marks driving purchase decisions over brand heritage.
- Beverages:Ready-to-drink formulations and malt-free alternatives leverage enzymatic processing to achieve texture parity with conventional grain-based drinks. Health-conscious professionals in Mumbai and Delhi metro corridors sustain weekly replenishment cycles.
- Bread:Technical complexity in achieving structural integrity without gluten proteins commands premium pricing, though moisture retention constraints limit distribution radius for fresh lines.
- Pasta:Durum wheat substitutes using quinoa or rice flour blends serve niche Italian-cuisine demand in affluent urban pockets.
Snacks command the established base. The steepest expansion runs through beverages.
End User:
Customer type differentiation separates medically mandated consumption from discretionary wellness purchasing.
- Health-Conscious Consumers:Urban professionals aged 28-40 without diagnosed gluten sensitivity drive absolute volume growth through preventive dietary choices. This cohort purchases through organized retail formats and direct-to-consumer subscription channels, generating preference data for iterative product development.
- Individuals with Celiac Disease:Medically diagnosed patients require strict FSSAI-certified products below 20 ppm gluten thresholds. Purchase frequency concentrates around specialty health food stores and verified online platforms.
- Athletes:Performance-oriented consumers seek high-protein gluten-free formulations for training regimens.
- Families:Household-level purchasing for children with gluten sensitivity or parental wellness preferences.
Health-conscious consumers anchor volume scale. Individuals with celiac disease concentrate value per transaction.
Distribution Channel:
Channel maturity determines certification visibility and consumer education depth.
- Supermarkets:Modern trade formats in Delhi and Mumbai feature dedicated health-food sections with FSSAI-certified SKU segregation. Shelf placement priority rewards third-party audited manufacturers.
- Online Retailers:Direct-to-consumer platforms bypass traditional distributor markups while capturing granular preference data. Monthly curated snack boxes gain traction among repeat purchasers.
- Health Food Stores:Specialty retailers in Bengaluru and Hyderabad provide formulation guidance for diagnosed patients.
- Convenience Stores:Limited gluten-free SKU penetration due to inventory turnover constraints and certification verification gaps.
Supermarkets consolidate the mass-market position. Online retailers capture the sharpest growth trajectory.
Ingredient Type:
Supply concentration across agricultural processing clusters shapes input cost volatility.
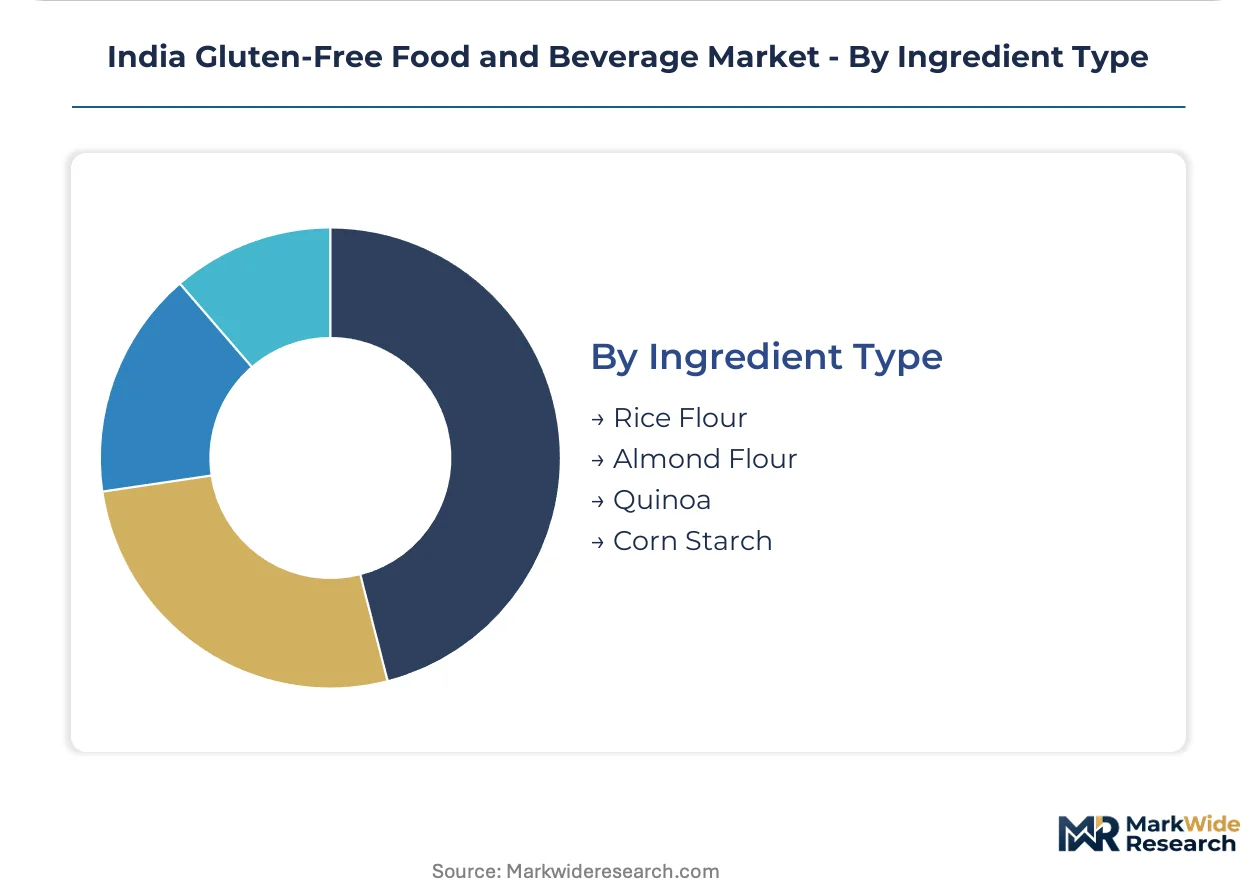
- Rice Flour:Basmati processing infrastructure in Haryana and Punjab controls over 70% of food-grade supply suitable for gluten-free baking. KRBL Limited leverages existing milling assets to anchor northern Indian market supply.
- Almond Flour:Premium positioning for keto-aligned and high-protein formulations attracts affluent urban consumers in Mumbai and Delhi. Import dependency creates margin exposure to dollar-rupee fluctuations.
- Quinoa:Limited domestic cultivation requires import reliance for consistent supply.
- Corn Starch:Cost-effective thickening agent for beverage and snack applications with established domestic sourcing.
Rice flour underpins mainstream production. Almond flour commands the premium tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI's mandatory gluten-free labeling standards anchor Maharashtra as the dominant geography, with Mumbai and Pune health-conscious cohorts driving weekly purchase frequency beyond seasonal spikes.
Maharashtra
Mumbai and Pune professionals aged 28-40 stock certified gluten-free snacks for daily consumption. FSSAI facility certification requirements below 20 ppm gluten thresholds reward third-party audited manufacturers with supermarket shelf priority. The state's food processing corridor narrows supply gaps between imported inputs and domestic formulation capacity.
Karnataka
Bengaluru and Hyderabad modern trade channels feature dedicated health-food sections with FSSAI-certified SKU segregation. BIS standards for alternative flours shape capital deployment decisions across manufacturing hubs. Mysuru and Mangaluru retail networks lack dedicated gluten-free aisles, presenting first-mover positioning opportunities.
Delhi-NCR
Affluent consumers in Delhi prioritize European formulation standards for premium bakery lines. The PLI scheme for food processing infrastructure lowers breakeven thresholds for manufacturers investing in dedicated gluten-free milling lines. Direct-to-consumer subscription channels capture granular preference data from repeat purchasers.
Gujarat
Snack producers in Ahmedabad and Surat restructure plant layouts fastest to meet state-level enforcement variance on FSSAI's 2023 labeling notification. Rice flour supply concentration in neighboring Haryana and Punjab creates geographic chokepoints for basmati processing clusters. Enzymatic treatment technology pilots compress performance gaps against imported European benchmarks.
Haryana
Basmati processing infrastructure in Karnal and Panipat controls over 70% of food-grade rice flour suitable for gluten-free baking. KRBL Limited leverages existing milling assets to anchor northern Indian market supply. PLI scheme incentives for millet valorization infrastructure attract capital subsidy provisions for dedicated gluten-free production lines.
India Gluten-Free Food and Beverage Market Competitive Landscape
Domestic rice-milling conglomerates and European specialty importers split the market between mass-market penetration and premium positioning. The vendor base organizes around three strategic archetypes: agricultural processors extending into alternative flour production, multinational CPG houses with broad distribution networks, and European gluten-free specialists competing on certification standards. Capacity expansion and portfolio diversification dominate competitive moves as players retrofit facilities for FSSAI compliance.
Among domestic agricultural processors, KRBL Limited and ITC Limited occupy positions that exemplify scale-driven supply anchoring. Dr. Schär AG represents the European specialty archetype, competing on formulation standards for affluent urban consumers. These three companies illustrate the market's bifurcation between rice-milling infrastructure leverage and imported premium positioning.
| Leading Market Players |
|---|
| KRBL Limited |
| Kraft Heinz Company |
| Dr. Schär AG |
| Mondelez International Inc. |
| Genius Foods |
| General Mills Inc. |
| Amy's Kitchen Inc. |
| Bob's Red Mill |
| ITC Limited |
| Others |
Supply & Pricing Matrix
The Mumbai-JNPT freight corridor's container haulage costs compress margins for basmati rice flour shipments from Haryana to Maharashtra processing hubs, forcing manufacturers to absorb logistics premiums or pass them to certified-premium SKUs. This transport economics layer compounds with FSSAI facility audit costs to stratify pricing across certification tiers, rewarding third-party verified producers with shelf placement leverage while squeezing uncertified competitors toward commodity snack segments.
Pricing Analysis
Price spreads between Mumbai supermarket shelves and Mysuru tier-2 retail points reach 35-45 percent for identical FSSAI-certified SKUs, reflecting distribution infrastructure gaps. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and brand heritage, with European-imported bakery lines commanding top tier. Pricing pressure stems from euro-rupee volatility on transglutaminase enzyme imports, compressing mid-tier formulator margins. Health-conscious professionals aged 28-40 show lowest price sensitivity, prioritizing threshold verification over cost.
Supply Chain Analysis
Upstream basmati rice flour feedstock concentrates in Haryana and Punjab processing clusters, with KRBL Limited and regional millers controlling over 70 percent of food-grade supply suitable for gluten-free baking. Sorghum and ragi inputs draw from Karnataka and Maharashtra agricultural belts, reducing import dependency for millet-based formulations. Single-source vulnerability runs through European enzyme suppliers for texture-modifying additives. Distribution feeds from dedicated gluten-free milling lines through modern trade channels and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FSSAI facility certification costs and 180-day compliance windows create switching barriers that favor incumbents with capital reserves.
For Market Incumbents: Pre-empt emerging millet-based entrants by securing captive sorghum supply contracts in Karnataka agricultural belts before PLI scheme subsidies attract new processing capacity. Accelerate enzymatic treatment R&D partnerships with Indian agricultural institutes to compress performance gaps against Dr. Schär AG formulation benchmarks. Defend shelf placement through exclusive modern trade category captain arrangements in Mumbai and Delhi-NCR corridors. For New Entrants and Emerging Players: Mysuru and Mangaluru retail networks present white-space positioning ahead of national label entry, with underserved health-conscious cohorts and absent dedicated gluten-free aisle infrastructure. Direct-to-consumer subscription channels offer bypass around distributor markup structures while capturing iterative product development data. Target FSSAI certification as primary go-to-market credential rather than brand heritage investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified rice-milling conglomerates seeking to monetize gluten-free milling assets as standalone verticals. Five-to-ten year viability hinges on millet valorization infrastructure scale and regulatory compliance automation. Watch for FSSAI enforcement variance acceleration across Gujarat and Maharashtra as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FSSAI Facility Certification Investment | Third-party audit documentation unlocks supermarket shelf priority in modern trade channels. |
| Millet Valorization Infrastructure Buildout | PLI scheme capital subsidies lower breakeven thresholds for dedicated gluten-free production lines. |
| Direct-to-Consumer Subscription Launch | Monthly curated snack boxes bypass distributor markups while capturing granular preference data. |
| Enzymatic Treatment Technology Licensing | Indian agricultural institute partnerships compress texture performance gaps against European benchmarks. |
| Regional Brand Building in Tier-2 Corridors | First-mover positioning in Mysuru and Mangaluru secures consumer loyalty before national label entry. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with FSSAI compliance officers at domestic manufacturers, category buyers at Mumbai and Delhi modern trade retailers, supply chain managers at rice-milling conglomerates, and formulation technologists at agricultural research institutes. Secondary validation drew from FSSAI notification archives, BIS standards documentation, PLI scheme administrative records, and customs import data for enzyme inputs. Bottom-up volume builds across product segments triangulated against top-down market sizing from distribution channel audits.
Calibration anchored historical growth patterns to observed facility certification timelines and enforcement variance across state-level food safety departments. Segmentation dimensions modeled include product type, end-user health profile, distribution channel maturity, and ingredient feedstock origin across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating urban household penetration rates for preventive dietary choices and diagnosed celiac disease prevalence estimates. Forecast inputs incorporated millet cultivation yield projections and euro-rupee exchange rate scenario bands.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European specialty importers or sudden FSSAI notification acceleration would shift outcomes beyond modeled ranges. Cross-checking against state-level food safety enforcement variance patterns and agricultural commodity price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Celiac Disease Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
North America Free from Food Market