
 Lactose-Free Food Market | 2026-2036
Lactose-Free Food Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose-Free Food Market Analysis
Single-serve and on-the-go packaging formats is repositioning buyer choice toward convenience-oriented lactose-free dairy. Danone SA leverages its chilled dairy logistics network to dominate European refrigerated shelves. Nestlé SA extends its plant-based R&D pipeline into lactose-free hybrid formulations. Green Valley Creamery specializes in small-batch, farm-direct positioning that anchors premium price tiers in North America.
Lactose-free food denotes dairy and dairy-alternative products processed to reduce or eliminate lactose content, typically achieving less than 0.1 grams lactose per 100 grams through enzymatic hydrolysis or membrane filtration, serving consumers with lactose malabsorption, dairy allergies, or digestive sensitivity. Milk leads product type volumes due to daily consumption frequency and infant nutrition substitution, while yogurt captures faster growth as probiotic positioning intersects with digestive wellness trends. Tetra Packs and cartons concentrate margin pools through extended shelf stability that reduces cold-chain dependency for retail distribution.
FDA labeling standards for lactose content claims and USDA organic certification requirements shape product formulation and market access thresholds in the United States, while EFSA nutrition and health claims regulation governs permissible digestive benefit statements across European markets. Stakeholders must monitor evolving enzymatic processing patents and clean-label ingredient thresholds that will determine next-generation product differentiation and regulatory compliance burdens.
Market Dynamics
Enzymatic hydrolysis patents are consolidating around three processing technology vendors, compressing equipment licensing costs and democratizing lactose-free production capacity for mid-tier dairy processors.
Growth Catalysts
- FDA Lactose Labeling Standards:The FDA's 2023 clarification of lactose content claim thresholds created uniform market access rules that reduced formulation uncertainty for US-based manufacturers.
- Infant Nutrition Substitution Demand:Pediatric dietary guidelines in Germany and Brazil now explicitly recommend lactose-free alternatives for diagnosed malabsorption cases, expanding the addressable patient population.
- Membrane Filtration Advancement:Ceramic membrane systems from European equipment suppliers now achieve sub-0.1% lactose retention at commercial dairy volumes without enzyme dependency.
Market Restraints
- Raw Milk Input Volatility:Fluid milk commodity pricing fluctuations in the United States and Germany directly compress lactose-free product margins due to identical feedstock dependency.
- Enzyme Supplier Concentration:Lactase enzyme production concentrates among three European biotechnology suppliers, creating single-source vulnerability for hydrolysis-dependent processors.
- Clean-Label Ingredient Thresholds:EFSA and FDA scrutiny of processing aid labeling requirements is forcing disclosure of enzymatic treatment methods that some consumers perceive as artificial intervention.
Strategic Opportunities
- Brazilian Retail Expansion:Underpenetrated supermarket lactose-free shelf space in São Paulo and Rio de Janeiro state clusters offers first-mover positioning before multinational dairy consolidation.
- USDA Organic Certification Convergence:Dual organic-lactose-free certification commands 40-60% retail price premiums in United States natural channel distribution.
- Direct-to-Consumer Subscription Models:Refrigerated logistics partnerships with last-mile cold-chain specialists enable recurring delivery of fresh lactose-free yogurt and milk outside traditional retail.
Industry Challenges
- Multi-Jurisdiction Labeling Compliance:Simultaneous FDA, EFSA, and ANVISA claim requirements force parallel packaging runs that fragment production economics.
- Enzyme Stability Expertise Gap:Commercial-scale lactase handling requires food biochemistry specialists that mid-sized dairy processors struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose-Free Food Market |
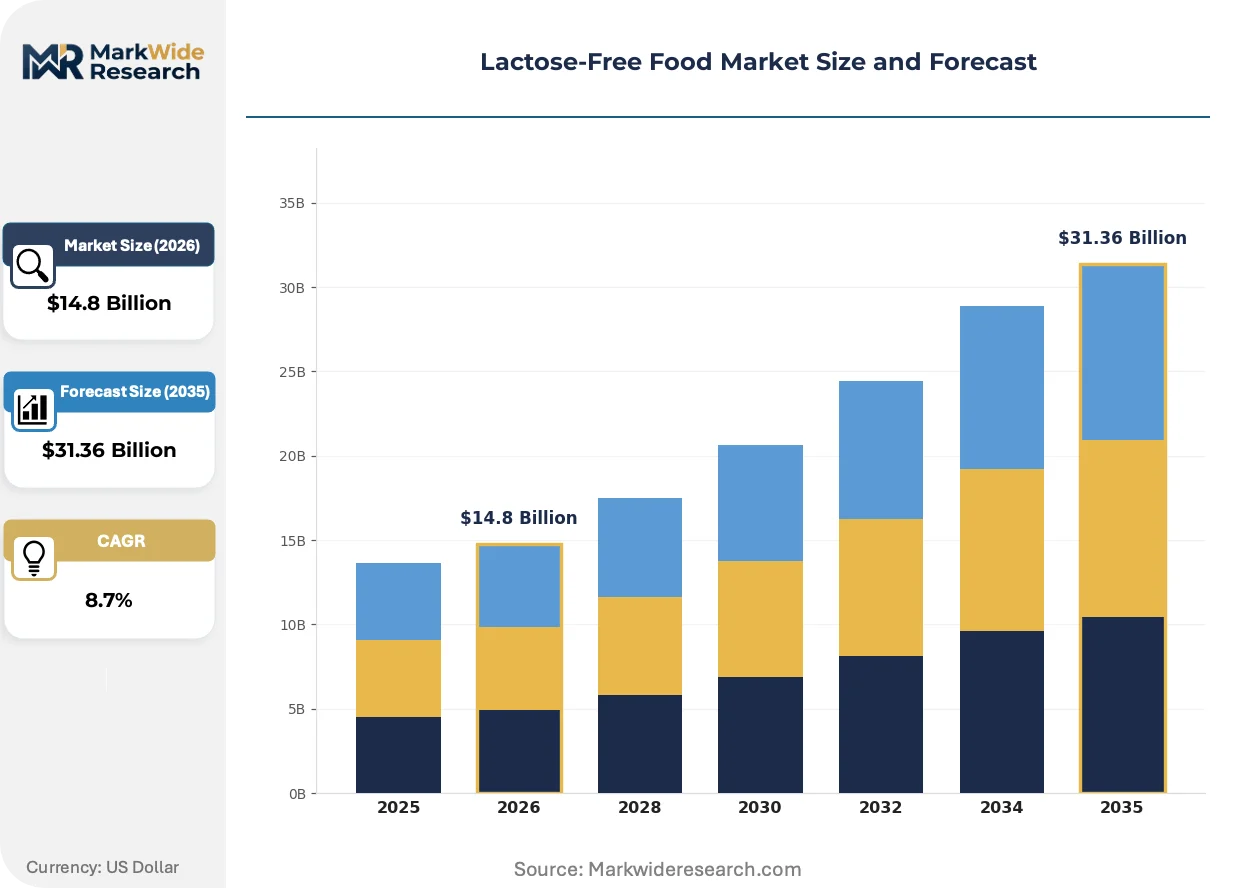
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Ice Cream End User: Retail Consumers, Food Service Industry, Restaurants, Bakeries Packaging Type: Bottles, Tetra Packs, Cartons, Pouches Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores |
| Companies Covered | Arla Foods, Danone SA, Nestlé SA, Valio Ltd, Fonterra Co-operative Group Limited, General Mills Inc., Galaxy Nutritional Foods Inc., Green Valley Creamery, Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose-Free Food Market Emerging Trajectories
Processing technology convergence with plant-based formulation science is dissolving the historical boundary between lactose-free dairy and dairy alternatives, creating hybrid product architectures that serve multiple dietary restriction profiles simultaneously.
Precision fermentation-derived lactase is unifying enzyme production with sustainable manufacturing credentials. Specialty chemical suppliers in the Netherlands and Denmark are deploying this cell-culture approach to reduce agricultural substrate dependency. The technology is unifying cost parity with traditional microbial fermentation while satisfying EFSA novel food approval pathways for clean-label positioning.
EFSA nutrition and health claims regulation revision is tightening permissible digestive benefit statements for yogurt and fermented products. Manufacturers must now submit clinical trial data for specific strain-probiotic-lactose interaction claims. German and French dairy cooperatives are responding by funding independent gastrointestinal transit studies to secure authorized health claim status.
Pediatric allergist recommendations are compressing parent purchase decision cycles for infant-grade lactose-free formulas. Hospital discharge protocols in United States metropolitan pediatric centers now include lactose-free feeding guidance for diagnosed infants. This behavioral shift concentrates initial brand loyalty formation in neonatal care settings rather than retail trial.
Lactose-Free Food Market Segmentation
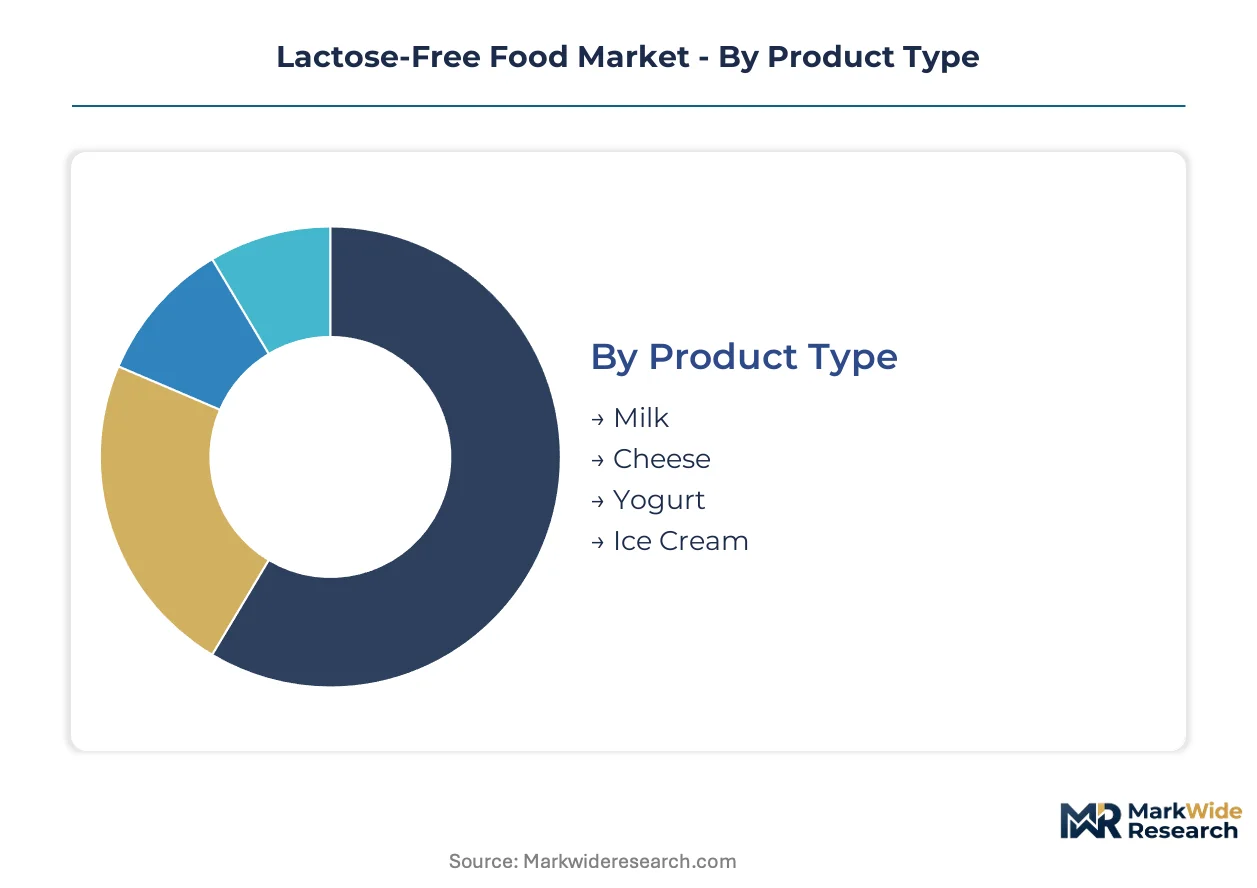
Segmentation in the lactose-free food market reveals how enzymatic processing costs and cold-chain requirements reshape competitive boundaries across product formats. Distinct margin structures emerge between daily-consumption staples and occasional-treat categories, while packaging innovation unlocks distribution reach beyond traditional refrigerated retail.
Product Type:
Milk commands absolute volume through infant nutrition substitution and daily household replenishment cycles, while yogurt captures accelerating premiumization through probiotic positioning.
- Milk:Standardized to less than 0.1 grams lactose per 100 grams via enzymatic hydrolysis or membrane filtration, this segment anchors production scale economics for hydrolysis-dependent processors. Daily consumption frequency in the United States and Germany sustains the highest absolute tonnage, though commodity milk input pricing directly compresses margins.
- Yogurt:Fermented base cultures intersect with lactose-free processing to create dual-digestive-benefit positioning that commands shelf-space premiums. Brazilian retail expansion and US natural-channel distribution concentrate demand growth as EFSA clinical trial requirements for strain-specific claims reshape competitive entry barriers.
- Cheese:Aging protocols complicate lactose reduction, limiting commercial scale to younger, fresh varieties where hydrolysis integrates more cleanly with manufacturing workflows.
- Ice Cream:Indulgence-oriented purchase cycles restrict volume relative to daily staples, though premium price tiers and clean-label positioning sustain attractive per-unit economics for specialized processors.
Today's leader: Milk. Tomorrow's challenger: Yogurt.
End User:
Retail purchase behavior splits between diagnosed medical necessity and discretionary wellness seeking, while foodservice adoption concentrates in high-margin preparation segments.
- Retail Consumers:Diagnosed lactose intolerance drives consistent repurchase loyalty, while broader digestive wellness trends expand the addressable base beyond clinical populations. Direct-to-consumer subscription models with last-mile cold-chain partners are penetrating United States metropolitan markets outside traditional supermarket dependency.
- Food Service Industry:Institutional procurement specifications for dietary accommodation create volume contracts with predictable offtake, though price sensitivity compresses margins relative to branded retail.
- Restaurants:Menu labeling requirements and allergen disclosure protocols in the United States and Germany are standardizing lactose-free ingredient sourcing for front-of-house transparency.
- Bakeries:Ingredient substitution in prepared goods demands functional performance from lactose-free dairy fats and proteins that hydrolysis processing must preserve.
Retail Consumers currently dominate absolute revenue. Food Service Industry procurement consolidation represents the steepest expansion trajectory.
Packaging Type:
Thermal stability requirements divide segments between cold-chain dependency and ambient distribution economics.
- Tetra Packs:Aseptic filling technology achieves extended shelf stability without refrigeration, collapsing distribution cost structures for Brazilian supermarket penetration and United States direct-to-consumer models. Tetra Pak's equipment licensing network concentrates margin pools for this format.
- Cartons:Gable-top refrigerated formats balance consumer familiarity with moderate shelf-life extension, dominating German and United States conventional retail dairy aisles.
- Bottles:PET and HDPE formats prioritize consumption convenience and resealability, capturing on-the-go usage occasions in convenience store channels.
- Pouches:Flexible packaging reduces material cost and shipping cube, though consumer perception challenges restrict penetration outside value-oriented private label positioning.
Tetra Packs are gaining share fastest through distribution cost advantages. Cartons defend incumbent shelf position through consumer habit formation.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with specialty positioning commanding premium multiples.
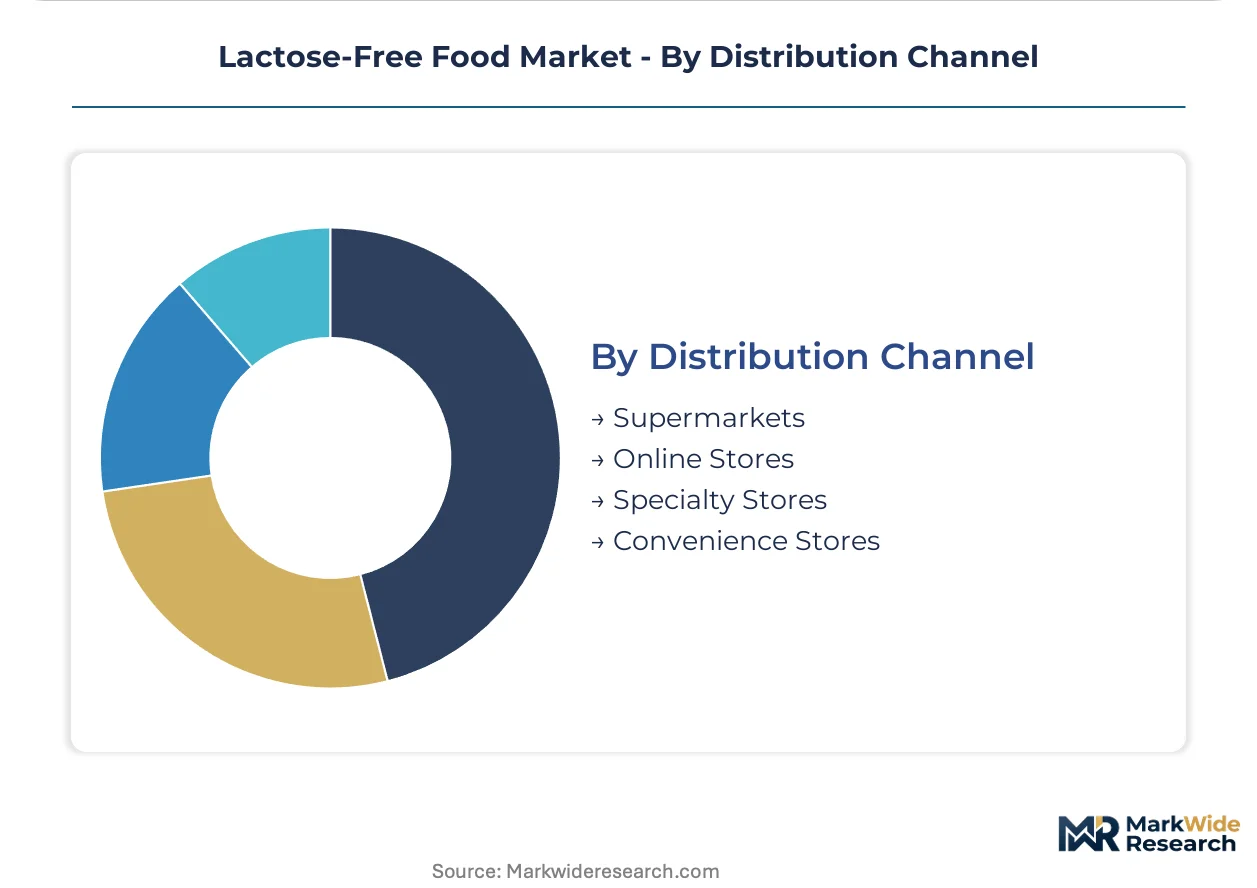
- Supermarkets:Shelf-space competition in São Paulo and Rio de Janeiro state clusters offers first-mover positioning before multinational dairy consolidation, while United States and German retailers standardize lactose-free planogram minimums.
- Specialty Stores:Natural channel distribution in the United States captures dual organic-lactose-free certification premiums, with USDA organic requirements shaping supplier qualification thresholds.
- Online Stores:Refrigerated logistics partnerships enable recurring delivery subscriptions that bypass retail slotting fees, though customer acquisition costs concentrate economics in metropolitan density clusters.
- Convenience Stores:Single-serve and on-the-go formats align with impulse purchase behavior, though SKU breadth limitations restrict category representation to highest-velocity milk and yogurt items.
Supermarkets anchor current volume. Online Stores are climbing the fastest through subscription model economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzymatic hydrolysis technology for lactose reduction first achieved commercial scale in Scandinavian dairy cooperatives during the 1980s, establishing Denmark and Finland as foundational markets before diffusion into Germany and the United States.
United States
FDA labeling standards for lactose content claims now govern permissible thresholds below 0.1 grams per 100 grams, reducing formulation uncertainty for domestic processors. Pediatric allergist recommendations from metropolitan hospital discharge protocols concentrate initial brand loyalty formation in neonatal care settings. California and New York metropolitan clusters anchor direct-to-consumer subscription model penetration with last-mile cold-chain partnerships.
Germany
EFSA nutrition and health claims regulation revisions now mandate clinical trial data for specific strain-probiotic-lactose interaction claims on yogurt packaging. Pediatric dietary guidelines explicitly recommend lactose-free alternatives for diagnosed malabsorption cases, expanding the addressable patient population. Bavarian dairy cooperatives fund independent gastrointestinal transit studies to secure authorized health claim status.
Brazil
ANVISA claim requirements for digestive benefit statements shape permissible packaging language for imported and domestic products alike. Hospital discharge protocols in São Paulo and Rio de Janeiro state clusters now include lactose-free feeding guidance. Underpenetrated supermarket shelf space in these metropolitan areas offers first-mover positioning before multinational dairy consolidation.
France
EFSA novel food approval pathways govern clean-label positioning for precision fermentation-derived lactase enzymes entering the market. French dairy cooperatives respond to tightening probiotic claim requirements by funding strain-specific clinical research. The Île-de-France region concentrates retail distribution infrastructure for refrigerated lactose-free yogurt and milk formats.
Netherlands
Specialty chemical suppliers deploy cell-culture lactase production approaches to reduce agricultural substrate dependency while satisfying EFSA approval requirements. Dutch enzymatic processing technology vendors consolidate patent positions around hydrolysis equipment licensing. The Randstad region anchors precision fermentation research clusters serving European dairy processors.
Lactose-Free Food Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and cold-chain capability dimensions, with dual organic-lactose-free certification commanding 40-60% retail price premiums in natural channel distribution. The vendor base stratifies into three archetypes: multinational dairy conglomerates with chilled logistics networks, regional cooperatives with farm-direct positioning, and specialized enzymatic processing technology licensors. Dominant competitive moves include M&A consolidation of mid-tier dairy processors and strategic partnerships with last-mile refrigerated logistics specialists.
Within the multinational conglomerate tier, Danone SA and Nestlé SA exemplify scale-driven portfolio diversification across refrigerated and ambient distribution formats. Arla Foods and Valio Ltd represent cooperative-structured competitors with farm-direct supply chain control. Green Valley Creamery occupies a position exemplifying small-batch, premium-tier specialization in North American natural channels. These named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Arla Foods |
| Danone SA |
| Nestlé SA |
| Valio Ltd |
| Fonterra Co-operative Group Limited |
| General Mills Inc. |
| Galaxy Nutritional Foods Inc. |
| Green Valley Creamery |
| Lactalis Group |
| Others |
Supply Flow & Price Mechanics
Retail consumer concentration in United States and German natural channels anchors premium capture through dual organic-lactose-free certification tiers, while commodity milk input dependency forces margin compression at the standard tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain capability. Dual organic-lactose-free certification commands substantial retail premiums in United States natural channel distribution, while private-label economy tiers compete on enzymatic processing efficiency. Pricing pressure stems from raw milk commodity volatility that compresses hydrolysis-dependent processor margins. Food service procurement exhibits highest price sensitivity; specialty store distribution shows lowest.
Supply Chain Analysis
Refrigerated logistics costs concentrate distribution economics around metropolitan density clusters in California, New York, and São Paulo state. Enzyme supply draws from Netherlands and Denmark precision fermentation facilities; ceramic membrane systems source from European equipment vendors. Single-source vulnerability in lactase enzyme production creates supply risk for hydrolysis-dependent processors. Distribution runs through supermarket retail with direct-to-consumer subscription models penetrating last-mile cold-chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lactose-free food market functions as a stable compounder, with enzymatic hydrolysis technology diffusion sustaining steady margin expansion across processing tiers.
For Market Incumbents: Anchor defensive positioning through backward integration into precision fermentation enzyme supply and exclusive cold-chain logistics partnerships. Patent consolidation around hydrolysis equipment licensing compresses equipment costs for mid-tier dairy processors, threatening margin pools. Certification investment in dual organic-lactose-free tiers protects premium capture against private-label encroachment. For New Entrants and Emerging Players: Direct-to-consumer refrigerated logistics partnerships offer white-space penetration in United States metropolitan clusters outside traditional retail slotting fee structures. Brazilian supermarket shelf space in São Paulo and Rio de Janeiro state clusters remains underpenetrated before multinational dairy consolidation. Strain-specific probiotic clinical trial investment unlocks EFSA authorized health claim positioning for yogurt entrants. For Investors and Strategic Acquirers: Multinational dairy conglomerates are the most active acquirer in this space, consolidating mid-tier enzymatic processing capabilities to secure volume scale. Long-term viability centers on hybrid product architectures dissolving boundaries between lactose-free dairy and plant-based alternatives. Precision fermentation-derived lactase cost parity with traditional microbial fermentation serves as inflection indicator for next-generation processing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Netherlands and Denmark suppliers reduce agricultural substrate dependency while satisfying EFSA novel food pathways. |
| Dual Certification Investment | USDA organic-lactose-free convergence commands premium positioning in United States natural channel distribution. |
| Direct-to-Consumer Launch | Refrigerated logistics partnerships with last-mile cold-chain specialists bypass retail slotting fee structures. |
| Clinical Trial Funding | German and French dairy cooperatives secure EFSA authorized health claim status for strain-specific probiotic positioning. |
| Membrane Filtration Adoption | Ceramic membrane systems from European equipment suppliers achieve sub-0.1% lactose retention without enzyme dependency. |
Methodological Framework
Multiple input streams — primary interviews with dairy processing executives, enzymatic technology licensors, and retail category buyers; secondary validation through FDA labeling guidance, EFSA nutrition claim registers, and ANVISA packaging requirements; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to model projections across the analysis window. Segmentation dimensions included product type, packaging thermal stability tier, distribution channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating enzymatic processing patent expiration schedules and pediatric dietary guideline adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw milk commodity volatility, enzyme supplier concentration risk, and EFSA claim regulation revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Global Gluten Free Prepared Foods Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Fermented Garlic and Onion Digestive Comfort Bases Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Lactose Free Products Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market