
 Canada Gluten-Free Foods and Beverages Market | 2026-2036
Canada Gluten-Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Gluten-Free Foods and Beverages Market Outlook
Single-serve and snack-size bundling is rebalancing consumer trial behavior in the Canada gluten-free aisle. General Mills leverages its manufacturing scale to anchor multi-pack offerings across mainstream supermarkets. Nature's Path Foods differentiates through organic-certified snack bundles that command shelf space in health food stores. PepsiCo competes with savory snack variety packs that lower the entry price for hesitant first-time buyers.
Canada gluten-free foods and beverages comprise formulated products containing less than 20 parts per million gluten, utilizing alternative grains such as rice, quinoa, and buckwheat to achieve comparable texture and shelf stability. These products serve both diagnosed celiac patients and the broader wellness-oriented consumer base seeking reduced-inflammatory diets. The breads segment dominates volume but faces margin compression from commodity grain costs, while beverages represent the fastest-expanding margin pool as functional hydration formats gain traction. Ecommerce platforms capture disproportionate growth among online shoppers in remote and suburban markets where specialty retail access remains limited.
Health Canada enforces gluten-free claims through the Food and Drug Regulations, while the Canadian Food Inspection Agency conducts facility audits and product testing to verify compliance. The Canadian Celiac Association's certification program adds a voluntary third-party layer that retailers increasingly require for shelf placement. Stakeholders must monitor whether Health Canada tightens the 20 ppm threshold to match emerging international standards, as such a shift would force reformulation investments across the supplier base.
Market Dynamics
Health Canada's tightening gluten-free labeling thresholds under the Food and Drug Regulations are forcing reformulation investments across Canadian manufacturers while creating compliance-driven competitive segmentation between certified and uncertified suppliers.
Growth Catalysts
- Celiac Diagnosis Rates:Rising clinical detection across Ontario and British Columbia expands the diagnosed patient pool requiring strict gluten-free diets, anchoring demand in restaurant and food service channels.
- Health Canada's Labeling Standards:Updated purity thresholds under the Food and Drug Regulations enhance consumer trust and reduce information asymmetry, accelerating retail adoption of verified products.
- Alternative Grain Processing:Advanced milling techniques for rice, quinoa, and buckwheat improve texture parity with wheat-based equivalents, reducing sensory trade-offs for mainstream consumers.
Market Restraints
- Commodity Grain Cost Volatility:Buckwheat and quinoa input prices fluctuate with harvest yields in Saskatchewan and Manitoba, compressing margins for bread and bakery segment producers.
- Supply Concentration Risk:Certified gluten-free oat processing concentrates in Prairie province facilities, creating single-point vulnerability for breakfast and snack categories.
- Cross-Contamination Technical Limits:Current manufacturing infrastructure cannot reliably achieve sub-10 ppm thresholds, constraining potential alignment with emerging international standards.
Strategic Opportunities
- Remote and Suburban Ecommerce Penetration:Online platforms capture underserved demand in Northern Ontario and Atlantic Canada communities lacking specialty retail infrastructure.
- Functional Beverage Formats:Fermented and probiotic-enhanced gluten-free drinks align with wellness-oriented consumption patterns in Vancouver and Calgary metropolitan corridors.
- Canadian Celiac Association Certification:Third-party verification programs unlock premium shelf placement in Loblaw, Sobeys, and Metro banner stores seeking liability reduction.
Industry Challenges
- Specialized Food Science Talent Scarcity:Formulation expertise in alternative grain rheology and shelf-stability engineering remains concentrated in Toronto and Montreal, constraining facility expansion timelines.
- Dual-Facility Capital Requirements:Dedicated gluten-free production lines demand redundant equipment investments to prevent cross-contamination, elevating break-even thresholds for mid-scale entrants.
- Health Canada Compliance Timelines:Product approval and facility audit queues under the Canadian Food Inspection Agency extend launch windows, delaying revenue realization for reformulated SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Gluten-Free Foods and Beverages Market |
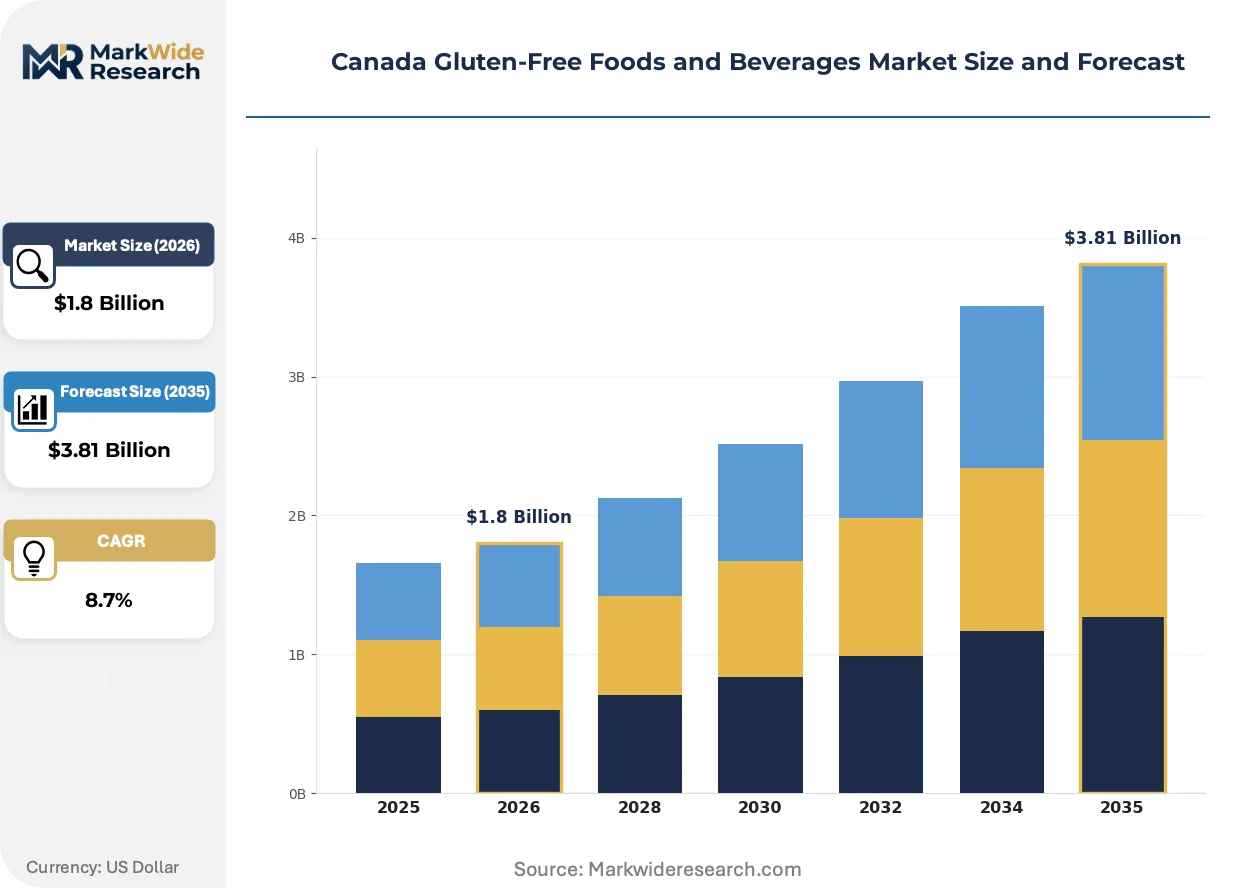
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Snacks, Pasta, Beverages End User: Retail Consumers, Restaurants, Food Services, Online Shoppers Distribution Channel: Supermarkets, Health Food Stores, Ecommerce Platforms, Specialty Stores Price Tier: Premium, Mid-range, Budget, Organic |
| Companies Covered | Kinnikinnick Foods Inc, The Hain Celestial Group, General Mills Inc, PepsiCo Inc, Conagra Brands Inc, Grupo Bimbo, Nature's Path Foods, Bob's Red Mill Natural Foods, Nestlé S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Gluten-Free Foods and Beverages Market Strategic Shifts
Canadian gluten-free manufacturing is pivoting from ingredient substitution toward functional equivalence and clean-label positioning, driven by diagnosed patient needs and wellness-consumer crossover demand.
Enzymatic gluten degradation technology is converging with traditional fermentation processes to expand the permissible ingredient base for gluten-adjacent products. Ontario-based craft breweries and bakeries are piloting these systems to reduce reliance on certified gluten-free supply chains. The structural consequence is converging with conventional production economics, narrowing the cost gap between dedicated and adapted facilities.
Health Canada's Food and Drug Regulations are tightening enforcement protocols for gluten-free claims through expanded Canadian Food Inspection Agency testing mandates. Manufacturers face accelerated recall exposure and labeling liability, compressing tolerance for supply chain opacity. The breads and baked goods segment is responding with blockchain-enabled ingredient traceability systems to preempt audit failures.
Subscription-based specialty grocery purchasing is displacing conventional retail stocking patterns among diagnosed celiac households. Toronto's metropolitan corridor shows the highest concentration of direct-to-consumer bundle services, replacing periodic supermarket trips with curated monthly shipments. This channel shift is most visible among dual-income professional households seeking time efficiency and contamination-risk reduction.
Canada Gluten-Free Foods and Beverages Market Segmentation
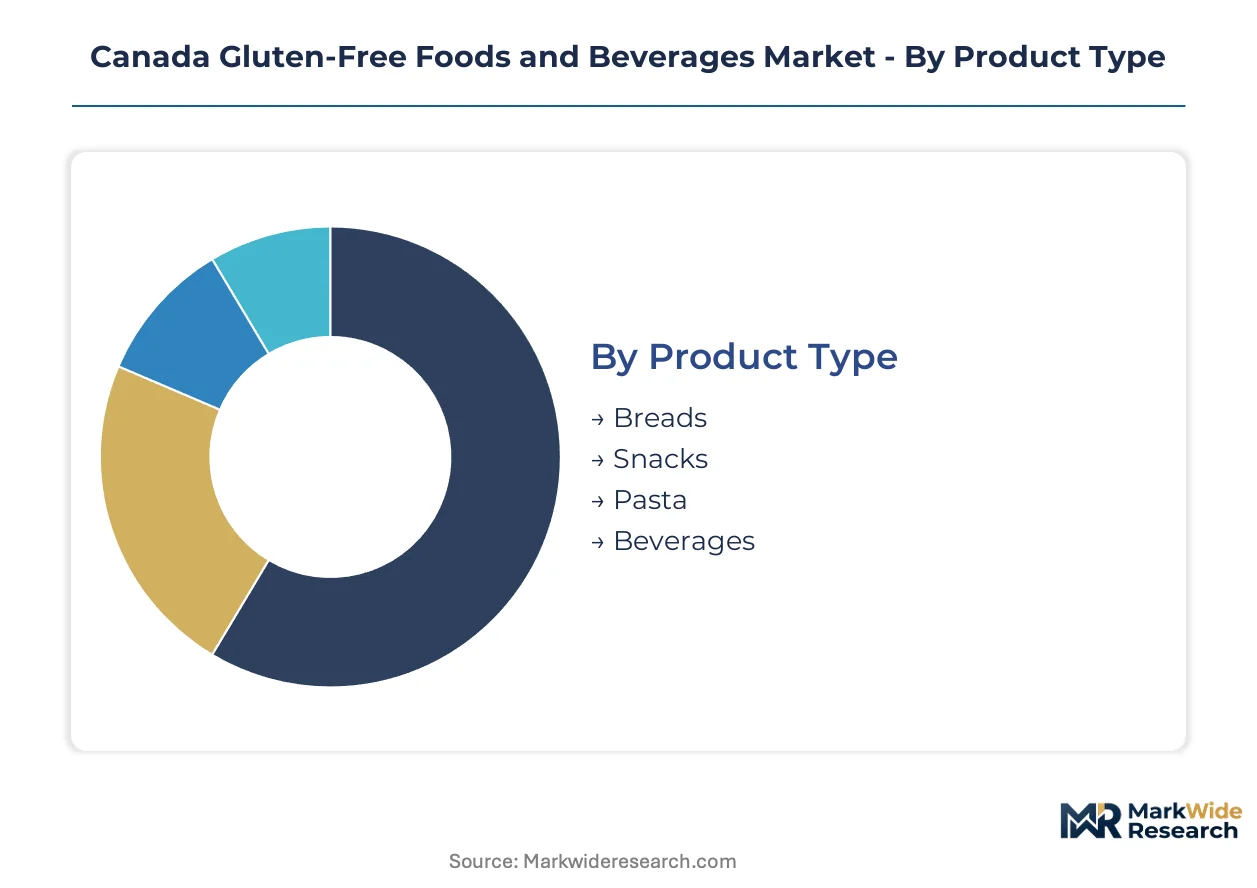
Product type and distribution channel configurations in Canada's gluten-free market reflect divergent capital requirements and margin structures. Health Canada's 20 ppm compliance threshold forces facility-level investments that segment producers by scale and certification depth.
Product Type:
Capital intensity varies sharply across product categories, with beverage manufacturing demanding specialized aseptic filling lines and breads requiring dedicated gluten-free baking infrastructure to prevent cross-contamination.
- Breads:Formulated loaves and rolls utilizing rice, quinoa, and buckwheat flours achieve texture parity through advanced hydrocolloid systems. Toronto's metropolitan retail corridor anchors volume, though Prairie province commodity grain cost volatility compresses producer margins.
- Beverages:Functional hydration formats including fermented and probiotic-enhanced drinks command the widest margin spreads. Vancouver and Calgary metropolitan corridors concentrate wellness-oriented demand as consumers seek reduced-inflammatory consumption patterns.
- Snacks:Single-serve and variety-pack configurations lower trial barriers for hesitant first-time buyers across mainstream supermarket channels.
- Pasta:Extruded and sheeted products from alternative grains serve both diagnosed celiac households and crossover wellness consumers seeking dietary rotation.
Breads absorb the bulk of installed capacity; beverages are expanding most quickly.
End User:
Customer archetypes stratify by contamination sensitivity, purchase frequency, and channel preference, with diagnosed patients exhibiting fundamentally different procurement patterns than wellness-oriented trialists.
- Retail Consumers:Diagnosed celiac households and wellness seekers purchase through recurring supermarket and health food store trips, with subscription services displacing conventional stocking patterns among Toronto dual-income professionals.
- Restaurants:Ontario and British Columbia food service operators expand gluten-free menu options as clinical detection rates climb, requiring supplier certification to reduce liability exposure.
- Food Services:Institutional and contract catering segments demand bulk formats with verified supply chain documentation for audit compliance.
- Online Shoppers:Remote and suburban households in Northern Ontario and Atlantic Canada leverage ecommerce platforms where specialty retail infrastructure remains limited.
Retail consumers command the deepest penetration; online shoppers are gaining share fastest.
Distribution Channel:
Channel selection determines compliance burden and shelf placement economics, with certified suppliers unlocking premium positioning in banner store networks.
- Supermarkets:Loblaw, Sobeys, and Metro banner stores require Canadian Celiac Association certification for gluten-free shelf placement, filtering supplier access by third-party verification investment.
- Ecommerce Platforms:Direct-to-consumer bundle services capture underserved demand in communities lacking specialty retail, with curated monthly shipments reducing contamination-risk anxiety.
- Health Food Stores:Organic-certified and clean-label products command disproportionate space in independent and chain natural retailers.
- Specialty Stores:Dedicated gluten-free boutiques concentrate in Toronto's metropolitan corridor, serving diagnosed patient households with comprehensive category depth.
Supermarkets absorb the bulk of volume throughput; ecommerce platforms are climbing the fastest.
Price Tier:
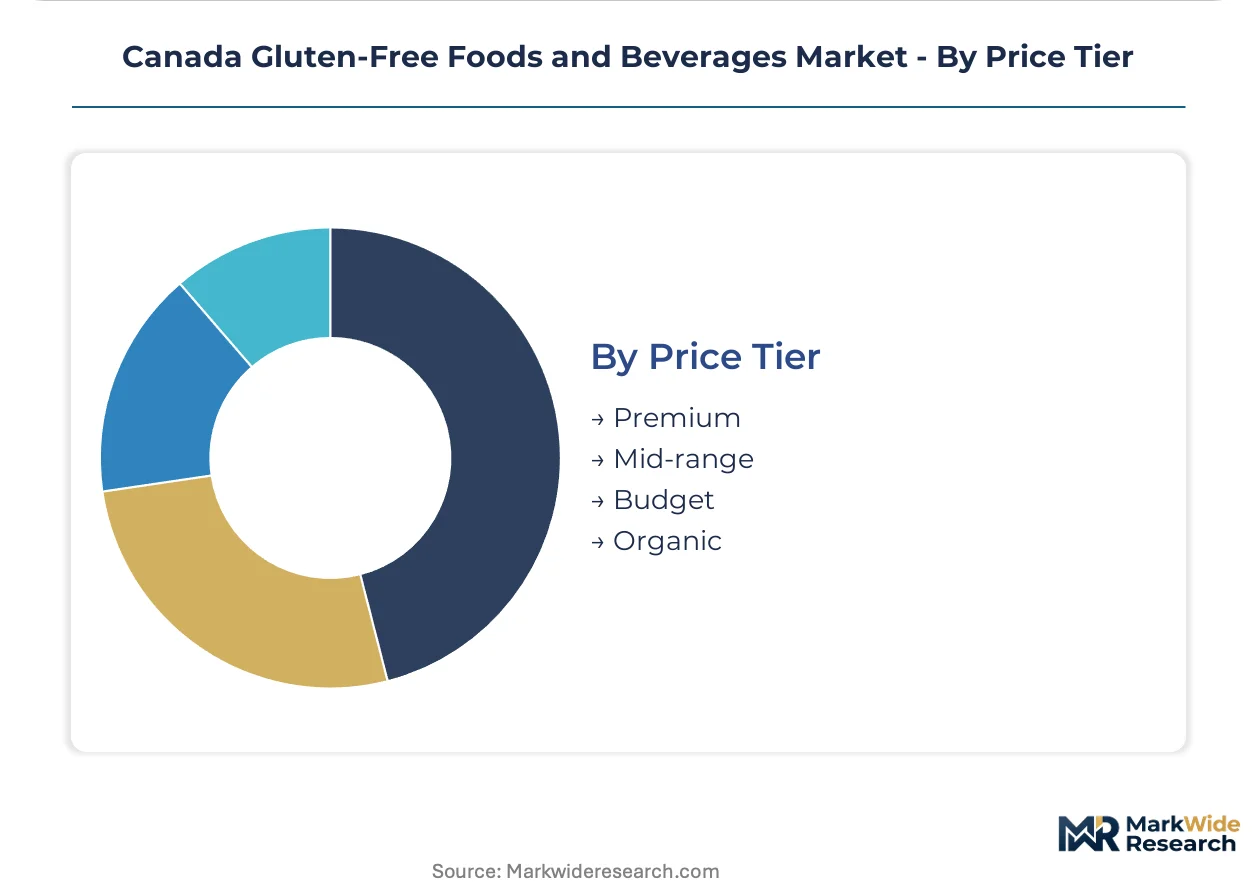
Premium positioning correlates with certification depth and ingredient sourcing transparency, while budget tiers compete on manufacturing scale and private label supply contracts.
- Premium:Canadian Celiac Association-certified products with blockchain-enabled ingredient traceability command shelf placement premiums in banner stores seeking liability reduction.
- Organic:Dual-certified gluten-free and organic products anchor health food store assortments, with Nature's Path Foods and comparable suppliers differentiating through sourcing transparency.
- Mid-range:Mainstream supermarket brands balance certification compliance with price accessibility for crossover wellness consumers.
- Budget:Private label and multi-pack offerings from scaled manufacturers lower entry price points for hesitant first-time buyers.
Premium tiers capture the widest margins; budget segments are expanding volume most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of gluten-free grains concentrates in the Prairie provinces while consumption gravity centers on Ontario and British Columbia metropolitan corridors. Health Canada's national labeling standards apply uniformly, yet provincial health systems and retail infrastructure create divergent adoption velocities across sub-regions.
Ontario
Toronto's metropolitan corridor anchors the deepest retail penetration, with specialty grocers and health food stores commanding premium shelf placement for certified products. Health Canada maintains its Ottawa headquarters where Food and Drug Regulations governing gluten-free claims are drafted and enforced. The Golden Horseshoe manufacturing cluster around Hamilton and Kitchener-Waterloo hosts dedicated gluten-free baking facilities serving Loblaw and Metro banner networks.
British Columbia
Vancouver and Calgary metropolitan corridors concentrate wellness-oriented demand for functional beverage formats and fermented gluten-free products. The province's Ministry of Health coordinates with Health Canada on celiac disease screening programs that expand the diagnosed patient pool. Lower Mainland food service operators lead menu expansion, requiring supplier certification to reduce liability exposure in high-traffic restaurant districts.
Quebec
Montreal's food manufacturing base supplies private-label gluten-free products to Provigo and IGA networks across the province. The Canadian Celiac Association's Quebec chapter operates certification programs that retailers increasingly require for shelf placement. Laval and Longueuil industrial zones host mid-scale alternative grain processing facilities serving Atlantic Canada distribution.
Alberta
Calgary's metropolitan corridor replicates Vancouver's wellness-consumption patterns while Edmonton anchors Prairie province distribution logistics. The province's agricultural extension services support buckwheat and quinoa cultivation that feeds into certified gluten-free supply chains. Red Deer and Lethbridge processing facilities face margin compression from commodity grain cost volatility.
Atlantic Canada
Remote and suburban households in Nova Scotia and New Brunswick leverage ecommerce platforms where specialty retail infrastructure remains limited. Health Canada's national labeling standards reduce information asymmetry for consumers lacking local health food store access. Halifax anchors regional distribution, with St. John's and Moncton showing rising subscription-service adoption among diagnosed celiac households.
Canada Gluten-Free Foods and Beverages Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price and certification segments. The market structure shows moderate consolidation, with scaled CPG manufacturers holding mainstream supermarket access while regional specialists dominate health food channels. Three archetypes predominate: multinational diversified food conglomerates with gluten-free portfolio extensions, mid-cap organic-certified specialists with third-party verification investments, and private-label suppliers serving banner store networks. Competitive moves center on Canadian Celiac Association certification acquisition and dedicated production line capacity expansion to prevent cross-contamination.
Among diversified conglomerates, General Mills Inc and PepsiCo Inc occupy positions exemplifying scale-driven multi-pack strategies that lower trial barriers across mainstream supermarkets. Nature's Path Foods represents the specialist archetype, anchoring organic-certified positioning within health food store channels. These three companies illustrate the competitive tension between manufacturing scale and certification depth that segments shelf placement economics.
| Leading Market Players |
|---|
| Kinnikinnick Foods Inc |
| The Hain Celestial Group |
| General Mills Inc |
| PepsiCo Inc |
| Conagra Brands Inc |
| Grupo Bimbo |
| Nature's Path Foods |
| Bob's Red Mill Natural Foods |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Canadian Celiac Association-verified and uncertified suppliers manifests in parallel pricing premiums and supply chain redundancy requirements. Health Canada's 20 ppm threshold forces dual-facility investments that concentrate certified production among scaled manufacturers, while uncertified suppliers compete on commodity grain spot markets with thinner margin buffers.
Pricing Analysis
Margin tightening in mid-range tiers reflects buckwheat and quinoa cost volatility from Prairie province harvest yields. Three-tier pricing structure across premium, standard, and economy levels anchors on certification depth and volume scale, with Canadian Celiac Association verification commanding shelf placement premiums in Loblaw and Sobeys networks. Price differentiation hinges on blockchain-enabled traceability investments that banner stores require for liability reduction. Budget-conscious first-time buyers exhibit highest price sensitivity, while diagnosed celiac households prioritize contamination-risk reduction over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with certified gluten-free oat processing concentrated in Saskatchewan and Manitoba facilities. Raw material dependencies center on Prairie province buckwheat cultivation, South American quinoa imports, and domestic rice milling from Ontario and Quebec. Supply chain risk traces to commodity grain price volatility compressing bakery segment margins. Distribution runs through Toronto metropolitan retail corridors for specialty grocers, with ecommerce platforms capturing remote Northern Ontario and Atlantic Canada demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance investments that filter out undercapitalized competitors. Health Canada's tightening audit protocols and facility certification requirements accelerate shakeout among uncertified regional suppliers.
For Market Incumbents: Deepen Canadian Celiac Association certification coverage across reformulated SKU portfolios to preempt Health Canada threshold revisions. Expand dedicated production line capacity in Golden Horseshoe manufacturing clusters to capture Metro and Loblaw banner network shelf resets. Anchor defensive positioning against enzymatic gluten degradation technology pilots that could erode certified supply chain premiums. For New Entrants and Emerging Players: Mid-range price-point gaps between premium certified products and private-label economy tiers offer white-space entry for scaled contract manufacturers. Target Atlantic Canada ecommerce penetration where subscription-based bundle services displace conventional retail stocking patterns. Pursue go-to-market angles through direct-to-consumer curated shipments that reduce contamination-risk anxiety for diagnosed households. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap organic-certified specialists given Health Canada enforcement protocol expansion accelerating retailer third-party verification requirements. Long-term viability favors targets with existing Prairie province grain sourcing relationships and dual-facility redundancy. Watch for Canadian Food Inspection Agency audit queue extensions as inflection signals for compliance-driven competitive segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Canadian Celiac Association Certification Expansion | Unlocks premium shelf placement in Loblaw, Sobeys, and Metro banner networks seeking liability reduction. |
| Dual-Facility Production Line Investment | Prevents cross-contamination while meeting Health Canada 20 ppm threshold compliance mandates. |
| Blockchain-Enabled Ingredient Traceability | Preempts Canadian Food Inspection Agency audit failures through transparent supply chain documentation. |
| Ecommerce Platform Penetration | Captures underserved demand in Northern Ontario and Atlantic Canada communities lacking specialty retail. |
| Functional Beverage Format Development | Aligns with wellness-oriented consumption patterns in Vancouver and Calgary metropolitan corridors. |
Study Parameters
Health Canada regulatory filings, Canadian Food Inspection Agency audit records, and Prairie province agricultural statistics formed the secondary backbone of this analysis. Primary interviews with gluten-free product development executives, category buyers at Loblaw and Sobeys, supply chain planners at alternative grain processors, and regulatory affairs specialists at certified manufacturers combined with bottom-up and top-down triangulation approaches. Secondary validation drew from Nielsen retail audit data, Canadian Celiac Association certification databases, and customs records tracking quinoa and buckwheat import flows.
Historical trendline analysis across alternative grain price indices, certified product shelf placement rates, and ecommerce penetration curves informed the analytical framework. Segmentation dimensions modeled include product type, distribution channel, price tier, and provincial health system adoption velocity. CAGRs were derived from volume and value trajectory fitting across the projection horizon. Industry-specific forecast inputs incorporated Health Canada labeling standard revision probabilities and Prairie province harvest yield variance patterns.
Underlying measurement precision varies by segment; beverages and ecommerce channels carry tighter precision than breads and conventional retail given data availability asymmetries. Forecasts reflect assumptions about Health Canada enforcement intensity and commodity grain price stabilization that regulatory or climatic shifts could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Gluten Free Malt Extracts Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Argentina Gluten-Free Food and Beverage Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market