
 Celiac Disease Market | 2026-2036
Celiac Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Celiac Disease Market Analysis
Specialty pharmacy distribution is fragmenting as direct-to-patient channels and digital health platforms capture prescription gluten-free therapeutics and adjuvant care. Takeda Pharmaceutical Company Limited leverages its gastrointestinal therapeutic portfolio to sustain clinical presence across hospital formularies. Amgen competes through biologic R&D intensity in autoimmune modulation, while Novartis AG anchors European market access with its established rare-disease commercial infrastructure.
Celiac disease constitutes a chronic autoimmune disorder triggered by gluten ingestion in genetically predisposed individuals, characterized by villous atrophy of the small intestinal mucosa and malabsorption of nutrients. The condition demands strict lifelong elimination of wheat, barley, and rye proteins, with serological screening (tissue transglutaminase IgA) and confirmatory duodenal biopsy serving as standard diagnostic protocols. Gluten-free bread and pasta occupy mature, high-volume positions with thin margins, whereas diagnostic testing services command premium pricing due to specialized laboratory infrastructure and clinician interpretation requirements. Online retail channels for gluten-free products are expanding fastest, diverting volume from traditional supermarkets as subscription models and telehealth-integrated nutrition counseling reshape patient purchasing behavior.
The FDA enforces its gluten-free labeling rule, mandating products contain fewer than 20 parts per million of gluten to bear the claim, while the EU's regulation on food information to consumers imposes parallel strictures across member states. Health Canada and the PMRA coordinate allergen labeling with gluten-specific provisions, creating a multi-jurisdictional compliance burden for manufacturers seeking cross-border distribution. Stakeholders must monitor evolving serological testing guidelines from national gastroenterology societies and the WHO's diagnostic standards, as earlier detection protocols promise to redefine addressable patient populations and shift care settings from hospitals toward home-based disease management platforms.
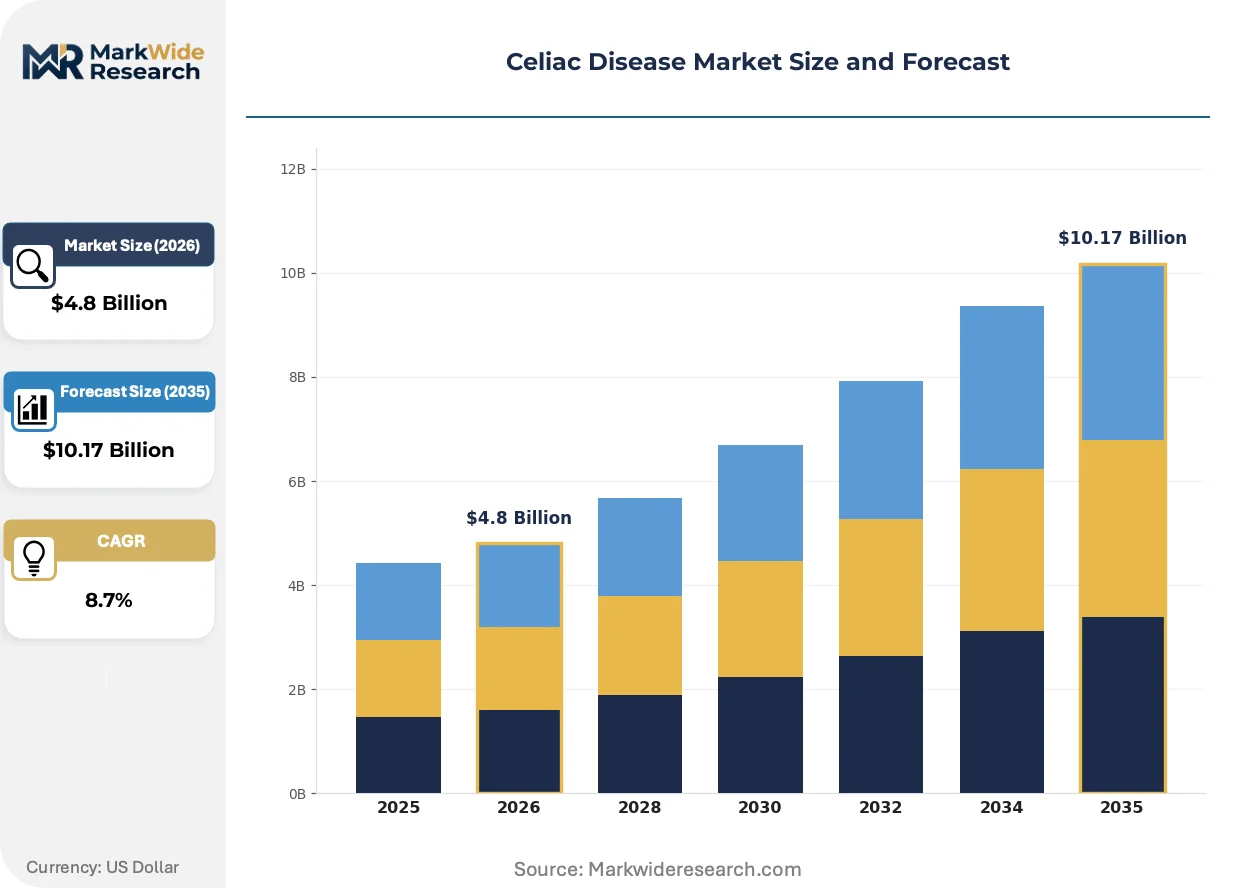
Market Dynamics
The celiac disease market is experiencing a fundamental restructuring as diagnostic protocol automation and serological test standardization compress the pathway from symptom presentation to confirmed diagnosis, expanding the addressable patient base while shifting care delivery toward ambulatory and home-based settings.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The regulation mandating fewer than 20 parts per million gluten for label claims has created enforceable product standards that reduce consumer uncertainty and accelerate retail shelf placement for certified manufacturers.
- Serological Testing Automation:Laboratory robotics and tissue transglutaminase IgA assay standardization are reducing diagnostic turnaround times from weeks to days in hospital and clinic workflows.
- Digital Health Integration:Telehealth platforms coupling nutrition counseling with subscription gluten-free product delivery are capturing patient adherence data and recurring revenue streams.
Market Restraints
- Input Cost Volatility:Specialty grain supply chains for sorghum, millet, and rice flour face climate-driven harvest variability that compresses gluten-free food manufacturing margins.
- Supply Concentration Risk:Diagnostic reagent production for celiac serology clusters among a limited set of European and North American laboratory suppliers, creating vulnerability to export restrictions.
- Substitution Threat:Non-celiac gluten sensitivity self-diagnosis drives demand for unregulated "gluten-reduced" products that bypass formal diagnostic channels and prescription frameworks.
Strategic Opportunities
- Underpenetrated Rural Diagnostics:Point-of-care serological testing deployment in underserved United States counties promises to capture undiagnosed patient populations outside metropolitan hospital networks.
- EU Regulation on Food Information:Mandatory allergen disclosure requirements are creating compliance service opportunities for cross-border gluten-free product certification and label verification.
- AI-Assisted Biopsy Analysis:Machine learning tools for duodenal histopathology interpretation are converging with digital pathology platforms to reduce specialist pathologist bottlenecks.
Industry Challenges
- Gastroenterologist Workforce Constraints:The specialized clinician pool for confirmatory endoscopy and biopsy interpretation faces training pipeline limitations that extend diagnostic waiting periods.
- Multi-Jurisdictional Certification Timelines:Manufacturers seeking simultaneous FDA, EFSA, and Health Canada approval encounter non-harmonized gluten threshold definitions and testing methodology requirements.
- Legacy Hospital Procurement Integration:Electronic health record systems in established medical centers require custom API development to incorporate digital gluten-free prescription and monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celiac Disease Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free Bread, Gluten-Free Pasta, Gluten-Free Snacks, Gluten-Free Beer End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Service Type: Diagnostic Testing, Nutritional Counseling, Support Services, Disease Management |
| Companies Covered | Takeda Pharmaceutical Company Limited, Amgen, Teva Pharmaceutical Industries Ltd, Sanofi, Novartis AG, ImmunogenX, Anokion SA, BioLineRx Ltd, Entero Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celiac Disease Market Emerging Trajectories
Diagnostic technology miniaturization and regulatory data harmonization are converging to reshape how celiac disease is detected, managed, and commercially addressed across patient journeys from suspicion to lifelong dietary adherence.
Point-of-care serological testing devices using capillary blood sampling are collapsing the geographic and economic barriers that previously concentrated diagnosis in specialized hospital gastroenterology departments. Rural clinics and primary care offices across the United States and Germany are deploying these instruments to capture patients who would otherwise remain undiagnosed due to referral friction. The structural consequence is a redistribution of diagnostic volume away from tertiary care centers toward distributed ambulatory settings that lack integrated biopsy capabilities.
The European Union's regulation on food information to consumers is mandating standardized allergen presentation across packaged goods, forcing reformulation disclosures that expose previously opaque supply chain practices. Gluten-free manufacturers must now document ingredient provenance and cross-contamination controls with audit-ready precision. Small and mid-sized producers in Italy and Spain face disproportionate compliance burdens as they retrofit legacy production lines to meet documentation requirements that larger competitors absorbed earlier.
Subscription-based gluten-free product procurement is displacing traditional supermarket purchasing among diagnosed patients who prioritize consistency and dietary safety over price comparison. Direct-to-patient channels integrated with telehealth follow-up are capturing adherence data that informs personalized nutrition recommendations. This behavioral shift is most visible in United States metropolitan areas where digital health platform penetration and celiac disease awareness campaigns have created concentrated populations of engaged, diagnosed consumers.
Celiac Disease Market Segmentation
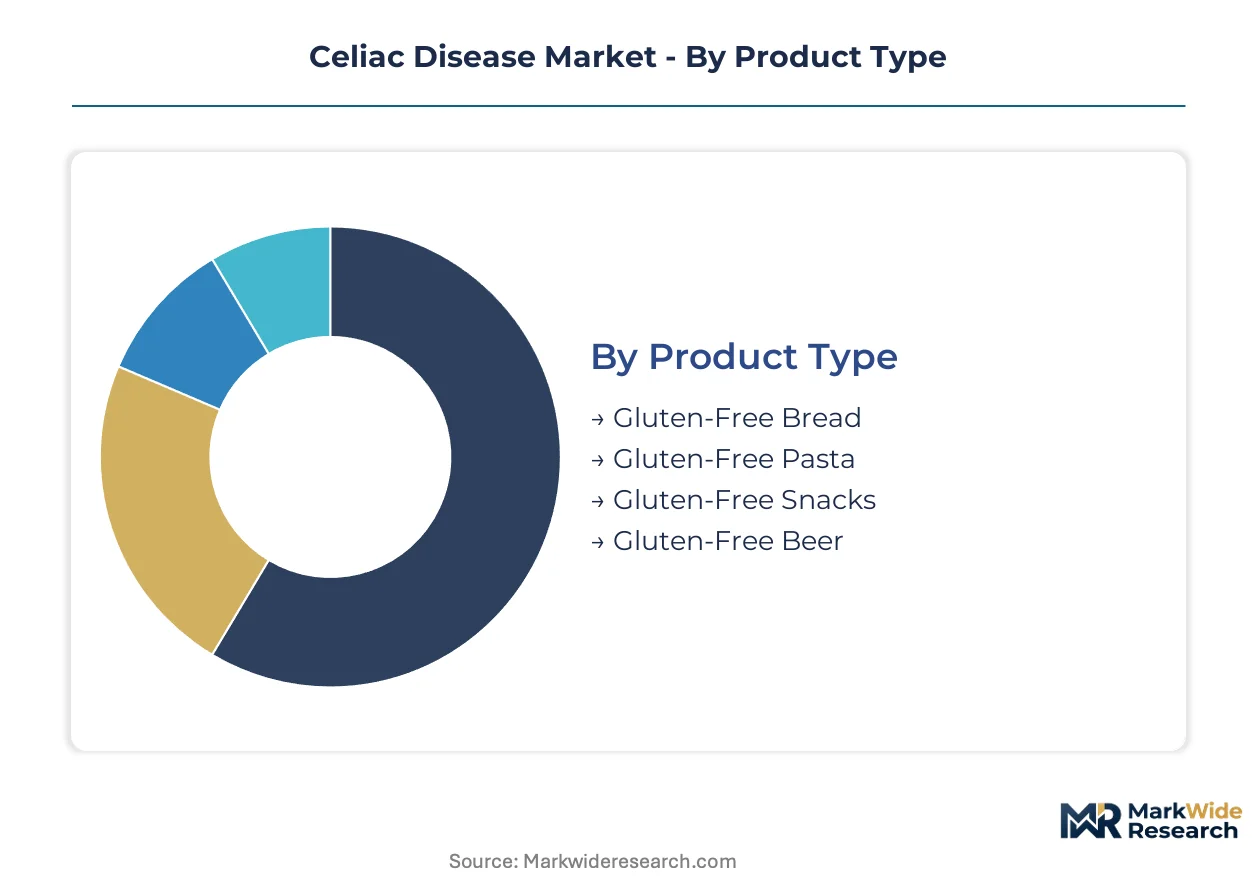
Celiac disease market segmentation reveals how patient journeys fragment across acute intervention, chronic management, and lifestyle maintenance phases. Product, service, and channel configurations must align with distinct clinical and consumer decision points.
Product Type:
Use-case spectrum spans daily dietary staples to occasional indulgence products, with compliance requirements and consumption frequency driving margin structures.
- Gluten-Free Bread:Formulated with rice flour, tapioca starch, and xanthan gum to replicate wheat-based texture and elasticity. Hospital cafeterias in the United States and Germany account for concentrated institutional procurement as patient meal programs expand allergen-safe options. Input cost volatility for specialty starches compresses manufacturer margins despite premium retail pricing.
- Gluten-Free Pasta:Manufactured from corn, quinoa, or legume flours with extrusion processes adapted to prevent cooking disintegration. Italian and Spanish producers dominate European supply through heritage processing infrastructure, while North American brands compete on pulse-based protein enrichment claims. Subscription direct-to-patient channels capture recurring household demand in metropolitan United States markets.
- Gluten-Free Snacks:Cracker and bar formats using nut flours and seed bases for portable consumption.
- Gluten-Free Beer:Sorghum, millet, or rice-based fermentation with enzyme-treated barley alternatives for flavor approximation.
Established volume favors gluten-free bread; emerging adoption favors gluten-free pasta.
End User:
Care setting determines reimbursement pathways and product formality, from clinical prescription to over-the-counter self-selection.
- Hospitals:Inpatient gastroenterology units and foodservice operations managing confirmed celiac diagnoses through controlled meal provision. Serological testing automation within hospital laboratories accelerates diagnostic confirmation and triggers immediate dietary intervention protocols.
- Clinics:Outpatient gastroenterology and primary care sites conducting initial screening and referral coordination.
- Home Care:Patient-managed environments where digital health platforms and subscription procurement replace institutional oversight.
- Pharmacies:Retail dispensaries handling prescription gluten-free products and adjuvant nutritional supplements.
Diagnostic concentration favors hospitals; longitudinal engagement favors home care.
Distribution Channel:
Channel selection reflects patient confidence levels, with newly diagnosed consumers prioritizing safety verification over price comparison.
- Online Retail:E-commerce platforms and subscription services with batch-level certification documentation and telehealth-integrated reordering. United States metropolitan areas show highest penetration as digital health platform adoption correlates with diagnosed patient density.
- Supermarkets:Mass-market retail with dedicated shelf sections and private-label gluten-free ranges.
- Health Food Stores:Specialty retailers with educated staff and curated premium product assortments.
- Specialty Stores:Dedicated gluten-free boutiques and pharmacy-adjacent nutrition shops.
Volume concentration favors supermarkets; loyalty and adherence data capture favors online retail.
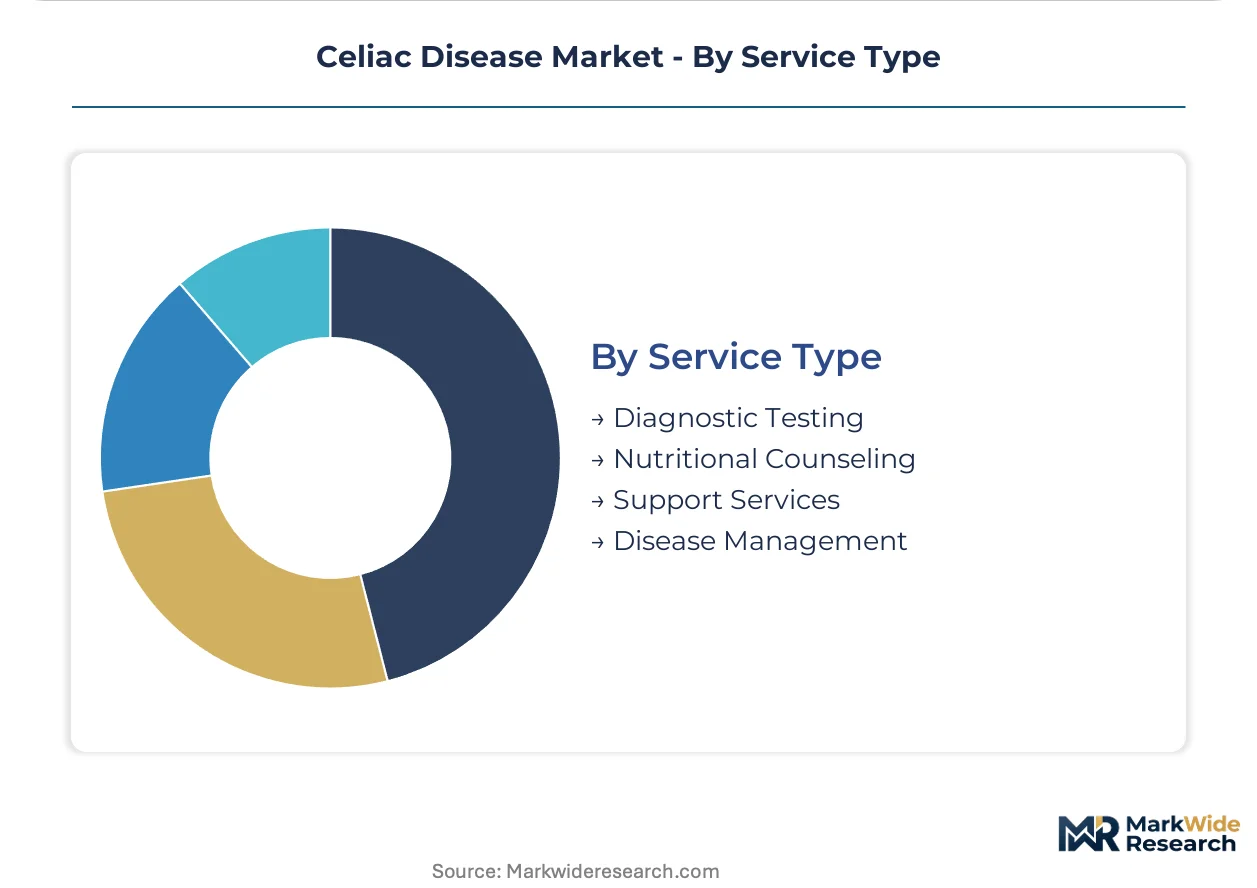
Service Type:
Service delivery spans detection, education, and ongoing management, with reimbursement status determining addressable patient pools.
- Diagnostic Testing:Serological assays for tissue transglutaminase IgA and confirmatory duodenal biopsy interpretation. Laboratory robotics standardization in the United States and Germany compresses turnaround times from weeks to days, expanding screening capacity beyond tertiary centers.
- Nutritional Counseling:Registered dietitian consultations for meal planning and cross-contamination avoidance education.
- Support Services:Patient advocacy group programs and peer community facilitation.
- Disease Management:Integrated digital platforms combining symptom tracking, dietary logging, and clinician communication.
Revenue concentration favors diagnostic testing; patient lifetime value expansion favors disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA anchors market development in the United States through its gluten-free labeling rule, while parallel regulatory frameworks in Europe and Canada shape cross-border product certification requirements and diagnostic protocol standardization.
United States
Hospital gastroenterology departments in Boston and Baltimore deploy automated tissue transglutaminase IgA assays that compress diagnostic turnaround to under 48 hours. The FDA's 20 parts per million gluten threshold mandates enforceable product standards that reduce consumer uncertainty. New York and Chicago metropolitan areas concentrate subscription-based gluten-free procurement through telehealth-integrated digital health platforms.
Germany
Duodenal biopsy interpretation bottlenecks in Munich and Heidelberg academic medical centers drive adoption of AI-assisted histopathology tools. The EU regulation on food information to consumers imposes standardized allergen disclosure across packaged goods. Bavarian and Baden-Württemberg diagnostic laboratories cluster serological testing automation infrastructure that serves cross-border patient flows from Austria and Switzerland.
Italy
Heritage pasta processing infrastructure in Emilia-Romagna and Lombardy sustains European supply dominance for corn and legume-based formulations. EFSA gluten threshold harmonization efforts create compliance service opportunities for cross-border label verification. Turin and Milan host concentrated gluten-free manufacturer networks retrofitting legacy production lines for audit-ready documentation requirements.
Canada
Health Canada coordinates allergen labeling with gluten-specific provisions that create multi-jurisdictional compliance burdens for US manufacturers seeking northern distribution. The PMRA oversees therapeutic approval pathways for adjuvant celiac treatments entering clinical trials. Toronto and Vancouver metropolitan areas concentrate diagnosed patient populations driving demand for specialty pharmacy gluten-free product distribution.
United Kingdom
National Institute for Health and Care Excellence serological testing guidelines expand screening eligibility in primary care settings across Greater London and the Midlands. Post-Brexit regulatory divergence from EU food information standards creates parallel certification requirements for cross-channel exporters. Manchester and Birmingham hospital networks pilot point-of-care capillary blood testing devices in underserved counties.
Celiac Disease Market Vendor Landscape
Pharmaceutical incumbents and biotech specialists split the market between established gastrointestinal therapeutic portfolios and novel autoimmune modulation approaches. The vendor base concentrates among multinational drug developers with rare-disease commercial infrastructure and emerging therapy developers targeting mucosal healing endpoints. Three archetypes dominate: large-cap pharmaceutical companies with hospital formulary relationships, mid-cap biotech firms with autoimmune R&D pipelines, and pre-commercial specialty developers with celiac-specific candidates. Competitive moves center on gastrointestinal therapeutic portfolio expansion and point-of-care diagnostic technology licensing.
Within the large-cap pharmaceutical tier, Takeda Pharmaceutical Company Limited and Novartis AG exemplify established hospital formulary presence leveraged across autoimmune and rare-disease indications. Amgen occupies a position representing biologic R&D intensity in immune-mediated disorder modulation. These three companies anchor the competitive structure through contrasting geographic strengths: Takeda leverages Japanese and North American gastrointestinal networks, Novartis anchors European market access through Swiss-based rare-disease infrastructure, and Amgen exemplifies US-centric biologics development capacity.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Amgen |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| Novartis AG |
| ImmunogenX |
| Anokion SA |
| BioLineRx Ltd |
| Entero Therapeutics |
| Others |
Supply Flow & Price Mechanics
Emilia-Romagna's heritage pasta processing infrastructure anchors European gluten-free manufacturing capacity, with its concentrated milling and extrusion assets translating into asymmetric pricing power over North American buyers facing freight-adjusted premiums. The region's legacy equipment base and skilled labor pool create entry barriers that sustain manufacturer margins despite input cost volatility in specialty grain markets.
Pricing Analysis
Transatlantic price spreads of 15-25% separate Italian gluten-free pasta exports from domestic US production, with certification grade and volume scale serving as primary differentiation drivers. Three-tier pricing structure across premium certified-organic, standard FDA-compliant, and economy private-label levels stratifies the market. Cost compression in the economy tier is intensifying because supermarket private-label programs are consolidating procurement volumes. Newly diagnosed patients in metropolitan United States markets show lowest price sensitivity, prioritizing batch-level safety documentation over per-unit cost comparison.
Supply Chain Analysis
EU dual-use export controls on advanced diagnostic reagent production technology limit flows to non-member state laboratories, constraining serological testing capacity expansion outside the bloc. Manufacturing concentration in Italy, Germany, and the United States draws from sorghum and millet cultivation in the Great Plains and Australian wheat belts, plus tapioca starch from Southeast Asian processing hubs. Single-source vulnerability clusters around European suppliers of tissue transglutaminase IgA assay components. Distribution runs through specialty pharmacy networks and direct-to-patient subscription platforms, bypassing traditional wholesale grocery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The celiac disease market rewards scarce capabilities in automated serology and certified gluten-free manufacturing, with trained pathologist availability and audit-ready production documentation emerging as binding constraints on expansion.
For Market Incumbents: Harden hospital formulary relationships through integrated diagnostic-to-dietary intervention protocols that lock in patient lifetime value. Invest in backward integration into specialty grain sourcing to defend margin position against climate-driven harvest variability. Prioritize certification investment for simultaneous FDA and EFSA compliance to preempt emerging entrant regulatory arbitrage. For New Entrants and Emerging Players: Underserved rural counties in the United States present diagnostic service white space where point-of-care serology deployment can capture undiagnosed populations outside metropolitan hospital networks. Telehealth-integrated nutrition counseling platforms offer the most penetrable segment for digital-native entrants. Pursue partnership with existing gastroenterology practices as the fastest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to divest non-core gastrointestinal therapeutic assets. Five-to-ten year viability hinges on mucosal healing endpoint achievement in late-stage pipelines. Monitor EFSA gluten threshold harmonization progress as the critical inflection signal for cross-border certification service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostic Deployment | Rural clinic expansion in underserved US counties captures previously undiagnosed patient populations. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA and EFSA compliance unlocks cross-Atlantic product distribution without reformulation costs. |
| Telehealth Platform Integration | Direct-to-patient subscription models capture adherence data and recurring revenue streams in metropolitan markets. |
| AI-Assisted Histopathology Development | Machine learning tools reduce specialist pathologist bottlenecks in duodenal biopsy interpretation workflows. |
| Specialty Grain Supply Agreements | Long-term offtake contracts with Australian and US Great Plains growers hedge climate-driven input cost volatility. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Forecast inputs span product type, end-user care setting, distribution channel, and service delivery mode across the projection horizon. CAGRs derive from segmented growth rate reconciliation against macroeconomic healthcare expenditure trends. Serological testing automation penetration and digital health platform adoption curves inform patient journey migration assumptions throughout the modeling period.
Practitioners should monitor regulatory threshold harmonization efforts and climate-driven specialty grain harvest variability for early signals of forecast revision needs. Material shifts in gastroenterologist workforce training pipeline output or point-of-care diagnostic accuracy improvements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Australia Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Low GI Food Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
France Gluten-Free Food and Beverage Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Australia Gluten Free Food Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market