
 Gluten Free Malt Extracts Market | 2026-2036
Gluten Free Malt Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Malt Extracts Market Outlook
Enzymatic modification of gluten-free grains is reshaping how malt extracts achieve comparable diastatic power and flavor profiles to traditional barley malts. Doehler leverages its integrated ingredient platforms to supply beverage producers with consistent liquid extract formulations. The Malt Company anchors its position through dedicated gluten-free malting facilities in Northern Europe. Imperial Malts Limited competes by specializing in sorghum and millet base malts for regional food manufacturers.
Gluten free malt extracts are concentrated sweet worts produced from cereals such as sorghum, rice, buckwheat, or millet that have undergone controlled germination and kiln-drying to develop amylolytic enzymes and Maillard-derived color compounds. These extracts typically achieve 75-80% soluble solids and serve primarily as fermentable substrates in brewing and as natural sweeteners and browning agents in baked goods. Liquid extract dominates volume due to its ease of incorporation into industrial brewing workflows, while powdered extract commands premium positioning among health food stores and dietary supplement formulators seeking extended shelf stability. The dietary supplements segment represents the fastest-growing application as protein-fortified and digestive-health positioned products gain shelf space.
The FDA enforces its gluten-free labeling rule at 20 ppm threshold, compelling malt extract producers to validate supply chains through third-party certification. The EU's FIC Regulation and EFSA gluten threshold guidance shape import requirements and intra-European trade compliance for non-barley malt ingredients. Codex Alimentarius standards provide the reference framework for harmonized gluten-free claims in cross-border markets. Stakeholders must monitor evolving allergen threshold science and certification scheme proliferation to maintain market access and premium positioning.
Market Dynamics
Enzymatic modification of gluten-free grains is compressing the performance gap with traditional barley malts, forcing producers to validate diastatic power parity through third-party certification while reformulating supply chains around dedicated gluten-free malting infrastructure.
Growth Catalysts
- EU Gluten Threshold Standards:The EU's updated gluten-free labeling requirements under FIC Regulation are compelling bakery chains across Germany and France to specify certified gluten-free malt extracts for clean-label bread formulations, tightening purity validation protocols.
- Craft Brewing Expansion:Independent brewers in the United States are sourcing sorghum and millet base malts to develop gluten-free beer portfolios, creating dedicated procurement channels that bypass commodity grain markets.
- Maillard Reaction Engineering:Controlled kiln-drying protocols for buckwheat and rice malts are enabling reproducible color compound development, allowing extract producers to supply consistent browning agents for industrial baked goods manufacturers.
Market Restraints
- Input Cost Volatility:Millet and sorghum prices fluctuate with sub-Saharan African harvest cycles, compressing margin stability for malt extract producers dependent on these non-commodity grain streams.
- Technical Performance Ceiling:Gluten-free malt extracts achieve 15-20% lower diastatic power than barley equivalents, limiting substitution rates in high-gravity brewing applications where enzymatic conversion efficiency is critical.
- Supply Concentration Risk:Dedicated gluten-free malting facilities cluster in Northern Europe, creating geographic single-point-of-failure exposure for North American and Asia-Pacific buyers seeking certified inputs.
Strategic Opportunities
- Dietary Supplements Channel:Protein-fortified and digestive-health positioned products are capturing shelf space in health food retail, with powdered gluten-free malt extracts commanding premium positioning for extended shelf stability formulations.
- India PLI Scheme Alignment:India's production-linked incentive scheme for food processing infrastructure offers capital cost offsets for gluten-free grain malting investments, opening access to domestic brewing and baking supply chains.
- ISO 17025 Convergence:Harmonized laboratory accreditation standards for gluten detection are reducing cross-border certification friction, enabling malt extract producers to serve multiple regulatory jurisdictions with unified testing protocols.
Industry Challenges
- Amylolytic Enzyme Expertise Gap:Gluten-free malting requires specialized knowledge of non-barley germination kinetics, and trained maltsters capable of optimizing diastatic enzyme development in sorghum and buckwheat remain scarce across commercial operations.
- Certification Timeline Compression:Third-party gluten-free validation from bodies accredited to FDA and EFSA standards requires 90-120 day batch testing cycles, constraining just-in-time supply responsiveness for craft brewers with seasonal formulation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Malt Extracts Market |
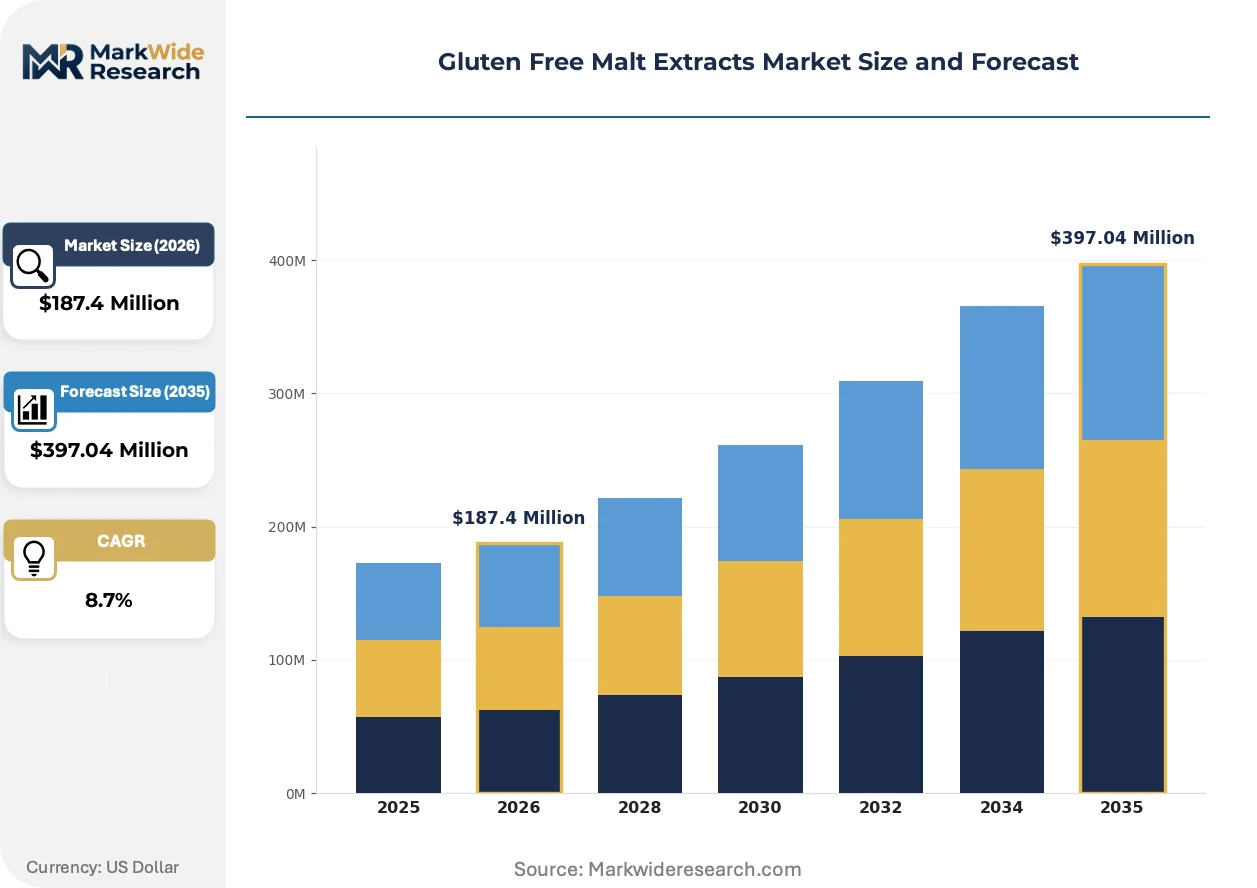
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powdered Extract, Syrup, Granulated Extract Application: Baking, Brewing, Confectionery, Dietary Supplements End User: Food Manufacturers, Beverage Producers, Health Food Stores, Home Bakers Packaging Type: Bottles, Bags, Tins, Custom Packaging |
| Companies Covered | Doehler, Diastatische Producten, The Malt Company, Pure Malt Products, Laihian Mallas, Imperial Malts Limited, Malt Products Corporation, EDME Limited, Senson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Malt Extracts Market Strategic Shifts
Controlled germination protocols and precision kiln-drying systems are converging to close the functional performance gap between gluten-free and traditional malt extracts, reshaping procurement criteria across brewing and baking value chains.
Spray-drying technology for liquid malt extract is migrating from pharmaceutical excipient applications into food-grade production, enabling extract producers to supply free-flowing powders with sub-5% moisture content. Health food retailers and dietary supplement formulators are adopting these stabilized formats for protein-fortified product lines. The shift is compressing cold-chain dependency and extending distribution radius for gluten-free malt ingredients into ambient-temperature retail channels.
EFSA's updated gluten threshold guidance under the FIC Regulation is tightening import requirements for non-barley malt ingredients entering European Union markets. Malt extract producers must now demonstrate supply chain segregation and dedicated facility protocols to maintain intra-European trade compliance. German and French bakery chains are responding by qualifying single-source suppliers with integrated gluten-free malting and extraction capabilities.
Buyer concentration among North American craft brewing collectives is consolidating procurement decisions into cooperative purchasing agreements. These pooled buying structures are displacing spot-market transactions with multi-year supply contracts that specify diastatic power minimums and lot-level gluten testing. The Pacific Northwest brewing corridor exhibits the most visible contract standardization, with specifications now referencing Codex Alimentarius thresholds alongside FDA requirements.
Gluten Free Malt Extracts Market Segmentation
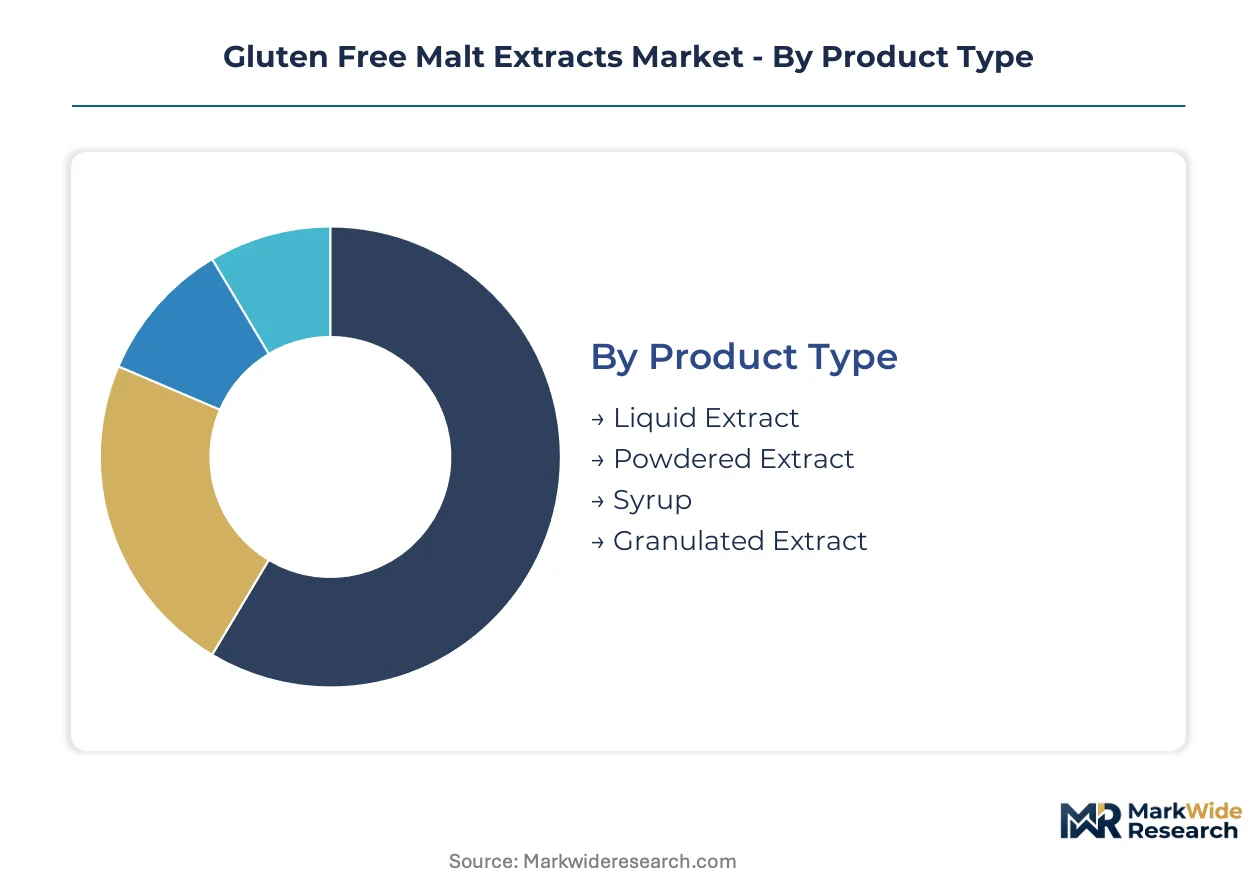
Segmentation in gluten-free malt extracts reflects divergent technical requirements across brewing, baking, and nutraceutical channels. Each segment demands distinct enzymatic specifications, packaging formats, and certification protocols that reshape supplier capabilities and margin structures.
Product Type:
After-sales service intensity varies sharply by product type, with liquid extracts requiring refrigerated logistics support and powdered formats demanding technical troubleshooting for reconstitution protocols.
- Liquid Extract:Concentrated sweet wort achieving 75-80% soluble solids through controlled germination of sorghum, rice, or millet. Industrial brewers in Germany and the United States specify liquid formats for seamless integration into automated brewing workflows where enzymatic consistency batch-to-batch is non-negotiable.
- Powdered Extract:Spray-dried malt solids with sub-5% moisture content enabling ambient distribution without cold-chain dependency. Health food stores and dietary supplement formulators in France source powdered extracts for protein-fortified formulations where extended shelf stability commands premium positioning.
- Syrup:Viscous liquid concentrate standardized for viscosity and color units. Confectionery manufacturers utilize syrup formats for controlled browning in caramel and toffee applications.
- Granulated Extract:Free-flowing agglomerated particles bridging liquid handling ease with powder stability. Craft brewers seeking intermediate moisture formats for seasonal production flexibility represent the primary demand concentration.
Liquid extract holds the largest share; momentum sits with powdered extract as health food retail expands.
Application:
Cost tier differentiation across applications separates commodity brewing inputs from premium nutraceutical positioning where certification overhead recovers through price premiums.
- Baking:Natural sweetener and Maillard browning agent in clean-label bread formulations. Bakery chains across Germany specify certified gluten-free malt extracts to comply with EU FIC Regulation labeling thresholds.
- Brewing:Fermentable substrate for gluten-free beer production where diastatic power parity with barley malts remains the critical performance metric. Independent brewers in the United States source sorghum and millet base malts through cooperative purchasing agreements specifying lot-level gluten testing.
- Confectionery:Color and flavor development in caramel, toffee, and chocolate applications where controlled kiln-drying protocols enable reproducible Maillard compound formation.
- Dietary Supplements:Protein-fortified and digestive-health positioned products gaining shelf space in health food retail channels. Powdered extracts with extended stability profiles are expanding most quickly as supplement formulators seek clean-label carbohydrate sources.
Brewing commands volume leadership; dietary supplements are climbing the fastest as functional positioning accelerates.
End User:
Customer type determines procurement sophistication, with beverage producers demanding technical specifications and home bakers prioritizing retail accessibility and recipe guidance.
- Food Manufacturers:Industrial bakers and confectioners requiring bulk liquid or syrup formats with consistent enzymatic activity and color specifications. German and French bakery chains qualify single-source suppliers with integrated gluten-free malting capabilities.
- Beverage Producers:Craft brewers and commercial breweries sourcing certified gluten-free inputs for portfolio diversification. The Pacific Northwest brewing corridor exhibits consolidated cooperative purchasing with multi-year contracts referencing Codex Alimentarius thresholds.
- Health Food Stores:Retail channels stocking powdered and granulated formats for consumer DIY brewing and baking. Staff technical training on gluten-free certification interpretation represents a service differentiator.
- Home Bakers:Individual consumers purchasing smaller-format packaged extracts through specialty retail and e-commerce. Recipe development support and substitution guidance drive brand loyalty in this segment.
Food manufacturers hold the largest share; momentum sits with beverage producers as craft gluten-free brewing accelerates.
Packaging Type:
Supply concentration in Northern European malting facilities shapes packaging format availability, with bulk formats dominating industrial channels and retail-ready packaging commanding logistics premiums.
- Bottles:Amber or opaque glass containers protecting liquid extracts from light degradation during ambient distribution. Beverage producers and home bakers favor bottles for precise volumetric measurement.
- Bags:Multi-layer laminate or kraft structures for powdered and granulated extracts. Food manufacturers specify bag formats for efficient bulk handling and storage density.
- Tins:Metal containers offering premium shelf presence and resealability. Health food stores stock tin-packaged extracts for gift-oriented and specialty positioning.
- Custom Packaging:Private-label and co-manufactured formats tailored to specific branding or functional requirements. Dietary supplement brands utilize custom packaging to differentiate protein-fortified product lines.
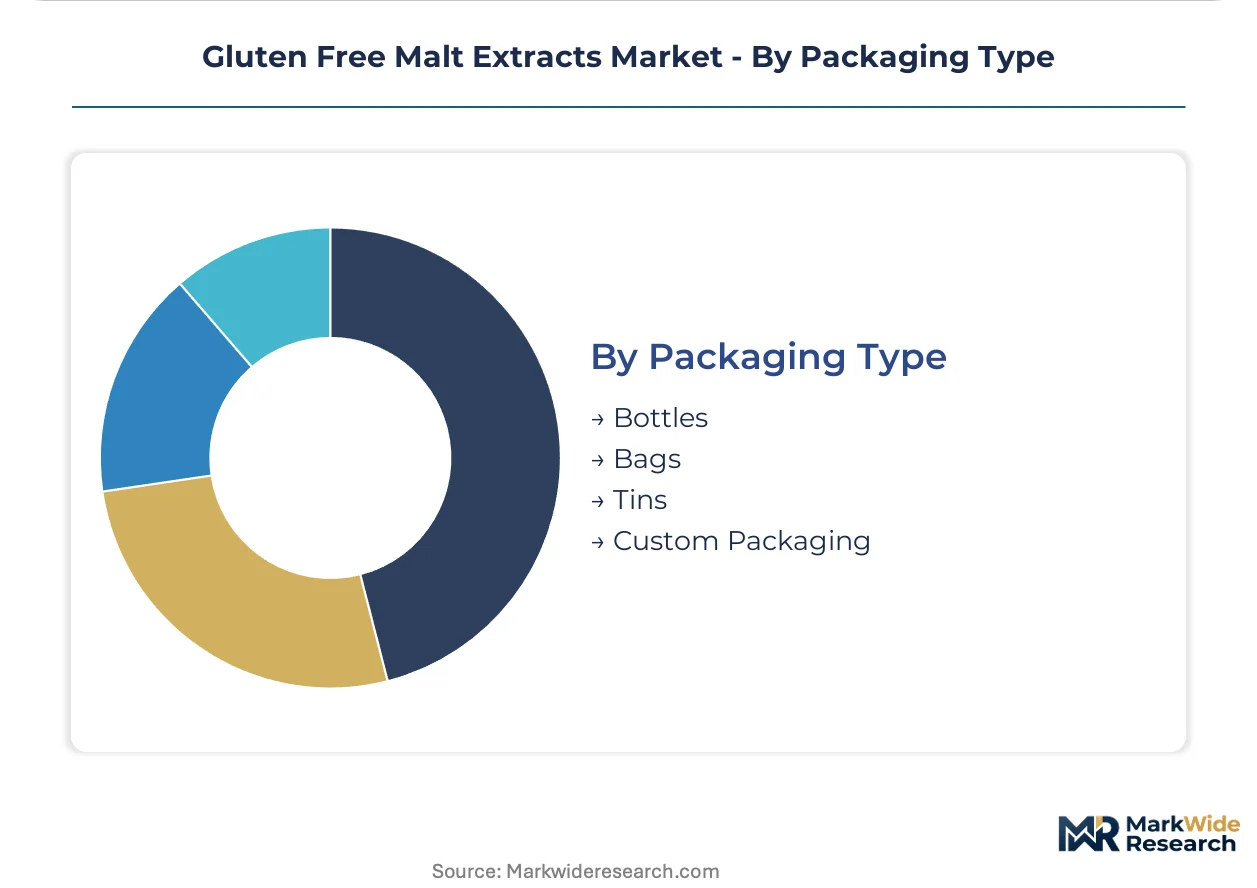
Bags hold the largest share; custom packaging is gaining share fastest as private-label proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German malt extract producers export certified gluten-free formulations to North American craft brewers and French bakery chains, establishing a transatlantic trade corridor anchored by EU FIC Regulation compliance.
United States
Independent brewers in the Pacific Northwest and Colorado source sorghum and millet base malts through cooperative purchasing agreements. FDA gluten-free labeling rules at 20 ppm compel lot-level testing documentation. Portland and Denver brewing clusters specify diastatic power minimums in multi-year supply contracts.
Germany
Bakery chains across Bavaria and North Rhine-Westphalia specify certified gluten-free malt extracts for clean-label bread formulations. EU FIC Regulation thresholds shape procurement qualification protocols. Munich and Hamburg anchor dedicated gluten-free malting infrastructure serving intra-European distribution.
France
Health food retailers in Île-de-France and Auvergne-Rhône-Alpes stock powdered malt extracts for protein-fortified supplement lines. EFSA gluten threshold guidance tightens import validation for non-barley ingredients. Lyon-based formulators demand extended shelf stability specifications.
India
Domestic brewers in Maharashtra and Karnataka seek localized gluten-free grain malting capacity to bypass import dependency. India's PLI scheme for food processing infrastructure offers capital cost offsets for malting investments. Mumbai and Bangalore beverage producers pilot sorghum-based formulations.
United Kingdom
Craft brewing collectives in London and Scotland consolidate procurement through pooled buying structures. Codex Alimentarius standards provide reference frameworks for harmonized gluten-free claims. Edinburgh malt extract users specify segregation protocols in supplier audits.
Gluten Free Malt Extracts Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply tiers. The vendor base clusters around integrated ingredient platforms and dedicated gluten-free malting facilities. Three archetypes dominate: diversified ingredient conglomerates, regional malting specialists, and contract manufacturing service providers. Competitive moves center on backward integration into captive grain supply and multi-jurisdiction certification acquisition.
Within the diversified ingredient tier, Doehler anchors integrated platform supply to beverage producers. Regional specialists include The Malt Company with Northern European facility concentration and Imperial Malts Limited representing Indian-origin sorghum and millet base malt supply. These three exemplify distinct geographic and capability positioning across the competitive map.
| Leading Market Players |
|---|
| Doehler |
| Diastatische Producten |
| The Malt Company |
| Pure Malt Products |
| Laihian Mallas |
| Imperial Malts Limited |
| Malt Products Corporation |
| EDME Limited |
| Senson |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Northern European malting facilities compresses margin stability while forcing buyers into premium contract tiers that bundle certification overhead with volume commitments. This geographic chokepoint simultaneously widens pricing spreads between certified and uncertified grades and accelerates investment in alternative sourcing regions.
Pricing Analysis
Enzyme-optimization technology gaps separate current-gen spray-dried powders from prior-gen liquid concentrates and next-gen granulated formats. Three-tier pricing structure across premium certified, standard commercial, and economy bulk grades dominates, with certification level and volume scale as primary differentiation drivers. Pricing pressure stems from millet and sorghum harvest volatility in sub-Saharan Africa. Craft brewers exhibit highest price sensitivity due to seasonal cash flow constraints; dietary supplement brands show lowest sensitivity given premium positioning recovery.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk calculations for transatlantic malt extract movements. Production gravity centers on Germany, France, and the Netherlands, with emerging capacity in India. Raw material flows draw from Nigerian sorghum, Indian millet, and Thai rice. Distribution runs through temperature-controlled bulk liquid tankers for industrial brewers and ambient parcel networks for health food retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EFSA and FDA certification entrenchment creates switching costs that protect incumbent positions. Network effects concentrate among buyers with cooperative purchasing agreements that consolidate volume leverage.
For Market Incumbents: Harden certification moats by accelerating ISO 17025 laboratory accreditation across multiple jurisdictions before EFSA threshold tightening finalizes. Deepen backward integration into captive sorghum and millet supply through offtake agreements with Nigerian and Indian grain aggregators. This counters emerging regional maltsters in India leveraging PLI scheme subsidies.
For New Entrants and Emerging Players: Establish a beachhead in India's domestic brewing corridor by aligning malting investments with PLI scheme capital offsets. Target Maharashtra and Karnataka beverage producers seeking localized gluten-free grain processing to bypass import dependency. Lead with sorghum-based formulations and technical service partnerships that compensate for brand recognition gaps.
For Investors and Strategic Acquirers: EU FIC Regulation threshold enforcement reshapes the acquisition landscape toward certified-facility assets with multi-jurisdiction testing protocols. Five-to-ten year viability favors integrated ingredient platforms over pure-play malters exposed to commodity grain volatility. Monitor EFSA batch-testing timeline compression as the signal indicating certification-bottleneck easing or intensification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Grain Supply | Nigerian sorghum and Indian millet offtakes reduce harvest-cycle margin compression for malt extract producers. |
| Multi-Jurisdiction Certification Acquisition | Simultaneous FDA and EFSA accreditation expands addressable market for German and Dutch malting facilities. |
| Spray-Drying Capacity Expansion | Sub-5% moisture powder formats capture health food retail shelf space from liquid-dependent competitors. |
| Cooperative Purchasing Agreement Formation | Pacific Northwest brewing collectives consolidate procurement leverage against spot-market price volatility. |
| Technical Service Partnership Development | Amylolytic enzyme expertise transfer closes the performance gap with barley malts for craft brewer retention. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with maltsters, brewery procurement directors, and health food retail category managers; and secondary validation through EFSA guidance documents, FDA gluten-free labeling rule filings, EU FIC Regulation compliance databases, and customs trade records. Bottom-up volume modeling triangulated against top-down ingredient demand estimates from brewing and baking sector outputs.
Forecast inputs span product type segmentation across liquid, powdered, syrup, and granulated formats; application channels including brewing, baking, confectionery, and dietary supplements; and end-user archetypes from industrial food manufacturers to home bakers. CAGRs were derived from regression analysis against historical volume trajectories and projected capacity additions. Industry-specific inputs incorporate PLI scheme implementation timelines in India and EFSA threshold guidance evolution.
Sensitivities concentrate around sub-Saharan harvest variability, certification timeline compression, and craft brewing demand cyclicality. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Sugar Free Food and Beverage Market
Food Intolerance Products
Reduced Salt Food Products Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
North America Free from Food Market
Food Intolerance Products
Food Intolerance Products Market
Food Intolerance Products
Global Lactose Intolerance Treatment Market
Food Intolerance Products
Gluten Free Tortillas Market
Food Intolerance Products
Italy Gluten-Free Foods and Beverages Market
Food Intolerance Products
Food Allergy and Intolerance Products Market
Food Intolerance Products
Canada Gluten-Free Foods and Beverages Market
Food Intolerance Products
Lactose-Free Food Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market