
 Egg Allergy Market | 2026-2036
Egg Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Allergy Market Analysis
Diagnostic testing revenue is reshaping margin pools away from pharmaceutical interventions toward laboratory services. Quest Diagnostics leverages its nationwide laboratory network to anchor clinical allergen testing volume. HYCOR Biomedical specializes in precision IgE assay platforms that differentiate its portfolio from commodity diagnostics. Sanofi sustains pharmaceutical R&D intensity while navigating the shift toward preventive and diagnostic care models.
Egg allergy encompasses immune-mediated hypersensitivity reactions to proteins found in hen's egg whites and yolks, primarily ovomucoid and ovalbumin, with clinical manifestations ranging from urticaria to anaphylaxis requiring strict dietary elimination and emergency epinephrine protocols. The condition's commercial purpose centers on enabling safe food consumption through allergen avoidance, diagnostic confirmation, and acute reaction management across pediatric and adult populations. Egg-free products occupy the largest revenue pool among product type segments as reformulated baked goods and sauces penetrate mainstream retail shelves. Alternative proteins represent the fastest-growing category as pea and mung bean isolates achieve functional parity in emulsification and foaming applications previously dependent on egg whites.
FDA enforces Food Allergen Labeling and Consumer Protection Act requirements that mandate clear egg disclosure on packaged goods, directly shaping manufacturer reformulation investments and product line architectures. EMA's pediatric investigation plans and the EU's broader allergen labeling framework under Regulation (EU) No 1169/2011 create parallel compliance obligations for multinational food and pharmaceutical companies operating across Atlantic markets. ISO 22000 food safety management standards further constrain facility-level cross-contamination risks. Stakeholders must monitor evolving threshold dose research that could redefine precautionary labeling practices and reshape liability exposure across the value chain.
Market Dynamics
The diagnostic-laboratory pivot is restructuring commercial flows, redirecting capital from pharmaceutical manufacturing toward precision IgE testing infrastructure and allergen detection platforms.
Growth Catalysts
- Precision diagnostics:Specific IgE blood assays and component-resolved diagnostics enable targeted dietary management, reducing unnecessary elimination diets and driving laboratory service volume.
- FDA Food Allergen Labeling mandates:Strict disclosure requirements for packaged foods force manufacturers to reformulate products, expanding the addressable market for egg-free alternatives and verification testing.
- Pediatric population concentration:Parents of young children with egg allergies exhibit high willingness-to-pay for safety-assured products, sustaining premium pricing across retail and foodservice channels.
Market Restraints
- Functional protein scarcity:Pea and mung bean isolates still fail to replicate egg white foaming in angel food cakes and meringues, limiting complete substitution in technical applications.
- Cross-contamination liability:Shared manufacturing equipment in conventional bakeries creates legal exposure that deters mainstream brands from entering allergen-free product lines.
- Diagnostic access inequality:Rural and underserved urban areas lack specialist allergist density, delaying confirmation testing and compressing addressable patient populations.
Strategic Opportunities
- Oral immunotherapy protocols:Desensitization treatment expansion in specialized clinics creates parallel pharmaceutical and monitoring service revenue streams beyond avoidance products.
- EU Green Deal protein transition:Sustainability-driven agricultural policy accelerates investment in alternative protein infrastructure that benefits egg-free formulation R&D.
- Direct-to-consumer testing:At-home IgE screening kits bypass traditional healthcare gatekeepers, capturing diagnostic margin and expanding market penetration.
Industry Challenges
- Threshold dose uncertainty:Lack of standardized minimum eliciting dose data complicates precautionary labeling decisions and exposes manufacturers to inconsistent liability rulings.
- Allergy specialist workforce gaps:Extended fellowship training timelines fail to match rising pediatric allergy prevalence, creating diagnostic bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Allergy Market |
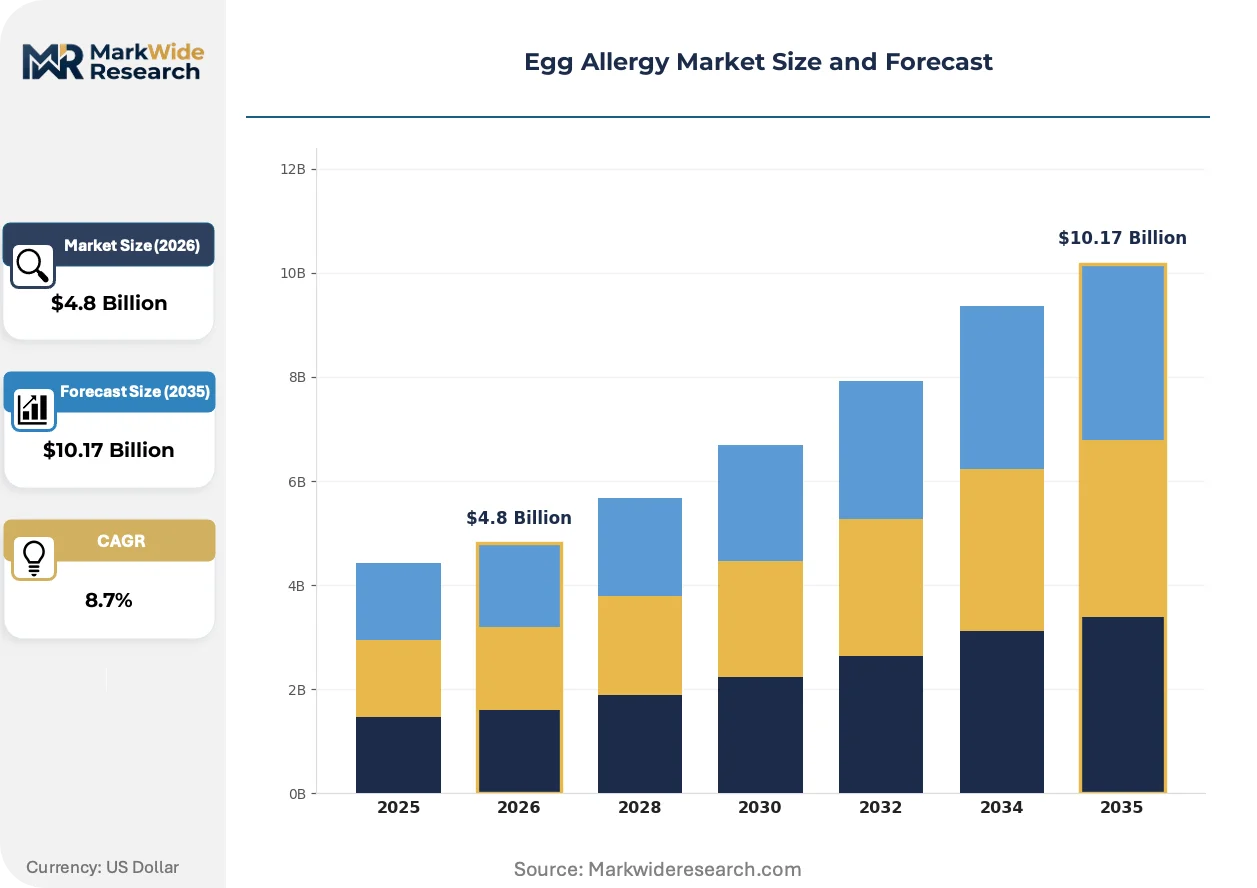
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Egg-free Products, Alternative Proteins, Plant-Based Substitutes, Allergy-Safe Foods End User: Hospitals, Food Manufacturers, Retailers, Parents Distribution Channel: Online Stores, Supermarkets, Health Food Shops, Specialty Stores Application: Baked Goods, Snacks, Dressings, Sauces |
| Companies Covered | Genentech, Sanofi, Aimmune Therapeutics, DBV Technologies, Quest Diagnostics, HYCOR Biomedical, ImmuneTech, Alletess Medical Laboratory, Kaleo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Allergy Market Emerging Trajectories
Component-resolved diagnostics and precision protein engineering are converging to transform how clinicians characterize sensitivities and how formulators replace egg functionality.
Next-generation sequencing-based IgE epitope mapping pinpoints specific protein reactivity profiles with single-amino-acid resolution. Academic medical centers and reference laboratories deploy these platforms to distinguish clinically relevant sensitivities from cross-reactive patterns. This granularity is rendering obsolete the crude whole-extract testing that previously drove unnecessary dietary restrictions.
EU Regulation (EU) No 1169/2011 mandates quantitative allergen disclosure alongside ingredient lists, pushing manufacturers toward standardized detection methodologies. Food producers now invest in in-house ELISA or PCR verification capabilities to ensure compliance across multi-country distribution networks. Germany and France lead enforcement intensity, with retail chains demanding batch-level certificates of analysis.
Parents increasingly demand third-party certification marks from organizations like the Asthma and Allergy Foundation of America before purchasing packaged foods. This preference shift elevates certified products to premium shelf positioning while squeezing uncertified competitors into price-driven segments. Retail buyers in the United States now treat certification as a non-negotiable listing criterion for pediatric-targeted categories.
Egg Allergy Market Segmentation
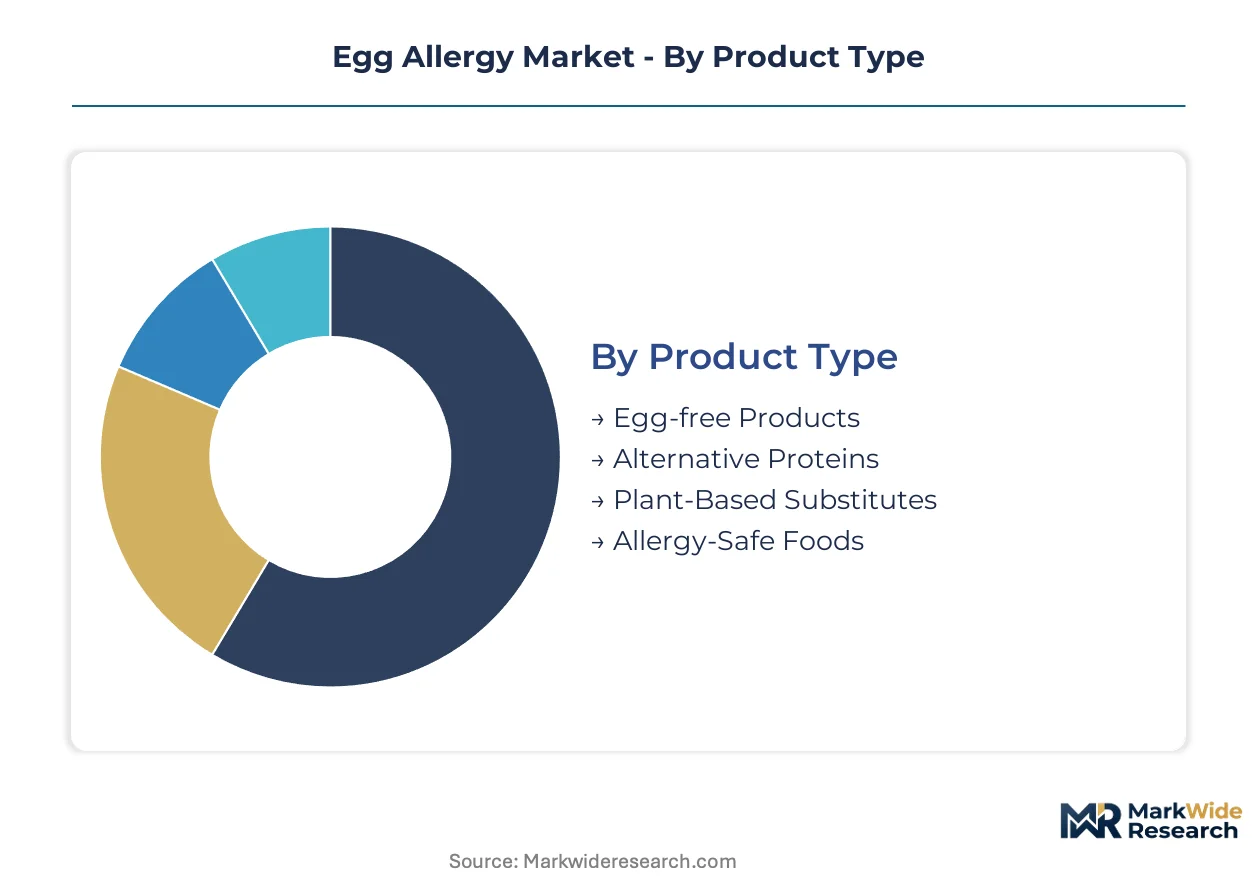
Egg allergy market segmentation reveals distinct commercial architectures across product formulation, procurement authority, channel access, and culinary application. Each dimension carries specific margin structures and regulatory exposure that shape stakeholder investment priorities.
Product Type:
Mature categories dominate current revenue pools while emerging formats capture reformulation-driven expansion.
- Egg-free Products:Reformulated baked goods, mayonnaise, and pasta formulations eliminate ovalbumin and ovomucoid through ingredient substitution. Parents of allergic children in the United States and Germany drive premium retail placement. FDA labeling mandates force mainstream manufacturers into this segment, expanding shelf space allocation.
- Alternative Proteins:Pea protein isolates and mung bean extracts replicate egg white emulsification and foaming properties in industrial food production. EU Green Deal agricultural policy accelerates European production capacity for these inputs. Technical gaps in angel food cake and meringue applications constrain complete substitution.
- Plant-Based Substitutes:Aquafaba and commercial starch-blend replacers target home baking and small-batch foodservice.
- Allergy-Safe Foods:Third-party certified packaged goods carrying Asthma and Allergy Foundation of America seals command pediatric category shelf positioning.
Egg-free Products retain volume leadership; Alternative Proteins hold the steepest expansion curve.
End User:
Procurement authority concentrates with institutional buyers and parental gatekeepers rather than individual patients.
- Parents:Primary decision-makers for pediatric dietary management exhibit high willingness-to-pay for certified safety-assured products. United States retail chains now require third-party certification for pediatric-targeted category listings. Emergency epinephrine protocols and strict elimination diets drive recurring purchase frequency.
- Food Manufacturers:Industrial formulators reformulate mainstream product lines to capture allergen-free market segments. Shared equipment liability concerns deter entry, favoring dedicated facility operators. EU Regulation (EU) No 1169/2011 mandates quantitative allergen disclosure across multi-country distribution networks.
- Hospitals:Clinical allergists prescribe diagnostic testing and emergency management protocols.
- Retailers:Grocery buyers control shelf placement and certification requirements for private-label expansion.
Parents command premium pricing power; Food Manufacturers are scaling reformulation fastest.
Distribution Channel:
Channel selection determines compliance burden and customer acquisition cost structures.
- Supermarkets:Mainstream retail chains in Germany and the United States dominate volume throughput. Buyers demand batch-level certificates of analysis and third-party certification marks. Precautionary labeling disputes create legal exposure that concentrates shelf space among established allergen-free specialists.
- Online Stores:Direct-to-consumer platforms bypass traditional healthcare gatekeepers for diagnostic kits and specialty foods. Subscription models capture recurring revenue from parental purchasers. Rural and underserved urban areas lacking specialist allergist density rely on this channel for product access.
- Health Food Shops:Independent retailers serve early-adopter consumers seeking novel alternative proteins.
- Specialty Stores:Dedicated allergen-free boutiques provide curated assortments with verified supply chain segregation.
Supermarkets anchor volume throughput; Online Stores are expanding geographic penetration most aggressively.
Application:
Technical functionality requirements segment formulation difficulty and substitution completeness.
- Baked Goods:Cakes, cookies, and bread formulations require egg replacers for moisture retention, leavening, and crumb structure. Industrial bakeries invest in dedicated allergen-free production lines to eliminate cross-contamination liability. Component-resolved diagnostics reduce unnecessary elimination diets, expanding addressable consumer base.
- Dressings:Mayonnaise and salad dressing emulsions depend on lecithin functionality from egg yolk. Pea protein isolates achieve commercial parity in this application, accelerating foodservice adoption. ISO 22000 standards constrain facility-level contamination risks in multi-product plants.
- Snacks:Extruded and coated products utilize egg wash alternatives for adhesion and sheen.
- Sauces:Hollandaise and béarnaise derivatives present complex emulsion stability challenges for plant-based replacers.
Baked Goods capture the largest reformulation investment; Dressings demonstrate the most complete functional substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratory networks and food manufacturing clusters concentrate activity in specific national markets. Regulatory frameworks in the United States and Germany enforce stringent allergen disclosure standards that reshape commercial investment patterns.
United States
FDA labeling mandates under the Food Allergen Labeling and Consumer Protection Act drive reformulation investments by mainstream food manufacturers. Quest Diagnostics anchors clinical testing volume through its nationwide laboratory infrastructure. Greater Boston and the San Francisco Bay Area host precision diagnostics development clusters.
Germany
EU Regulation (EU) No 1169/2011 enforces quantitative allergen disclosure that exceeds U.S. precautionary labeling requirements. Retail chains in Bavaria and North Rhine-Westphalia demand batch-level certificates of analysis for certified product placement. The country's food safety authority intensifies enforcement of ISO 22000 facility standards.
United Kingdom
NHS specialist allergist shortages create diagnostic access bottlenecks that compress addressable patient populations. The Food Standards Agency maintains parallel allergen labeling obligations post-Brexit. London's research hospitals advance component-resolved diagnostic platforms.
France
ANSM pediatric investigation requirements shape pharmaceutical development timelines for desensitization therapies. Retail concentration in Île-de-France accelerates certified product penetration. The country's agricultural policy under the EU Green Deal expands pea protein production capacity.
Japan
METI standards for food allergen labeling create compliance obligations distinct from Western frameworks. PMDA regulatory pathways influence oral immunotherapy protocol development. Tokyo's metropolitan hospitals concentrate specialist allergist density.
Egg Allergy Market Vendor Landscape
Pharmaceutical developers and diagnostic laboratories split the market into distinct value capture zones. Consolidation pressures concentrate around precision IgE testing platforms and biologic therapy pipelines. Three archetypes dominate: multinational pharmaceutical conglomerates, specialized diagnostic service providers, and emerging biotech therapy developers. Competitive moves center on laboratory network expansion and oral immunotherapy protocol commercialization.
Within the pharmaceutical tier, Sanofi and Genentech exemplify R&D-intensive archetypes navigating the shift toward preventive care models. Among diagnostic specialists, Quest Diagnostics anchors clinical testing volume. HYCOR Biomedical occupies a position within the precision assay segment. These entities represent divergent strategic postures across the therapeutic-diagnostic continuum.
| Leading Market Players |
|---|
| Genentech |
| Sanofi |
| Aimmune Therapeutics |
| DBV Technologies |
| Quest Diagnostics |
| HYCOR Biomedical |
| ImmuneTech |
| Alletess Medical Laboratory |
| Kaleo |
| Others |
Supply Flow & Price Mechanics
Cross-contamination liability exposure in shared manufacturing equipment determines both the premium spread for dedicated-facility products and the geographic clustering of allergen-free production capacity. FDA enforcement intensity and EU quantitative disclosure mandates compress margins for non-compliant operators while rewarding certified specialists with pricing power.
Pricing Analysis
FDA Food Allergen Labeling and Consumer Protection Act requirements dictate the pricing tier structure across the egg allergy market. Three-tier pricing separates third-party certified premium products from standard reformulated goods and economy private-label alternatives. Price differentiation rests on certification grade from the Asthma and Allergy Foundation of America and volume scale commitments from retail chains. Cost compression in the standard tier is intensifying because mainstream manufacturers absorb reformulation expenses to retain shelf placement. Parents of allergic children exhibit the lowest price sensitivity, while institutional foodservice buyers drive the hardest volume negotiations.
Supply Chain Analysis
Tariff exposure between the United States and Canada on processed food ingredients dominates supply chain risk calculations for North American operators. Production gravity centers on Germany, the United States, and France for finished allergen-free goods, while pea protein isolate supply draws from Canada and France under EU Green Deal agricultural subsidies. Raw material dependencies include mung bean extracts, aquafaba processing streams, and precision IgE assay reagents. Single-source vulnerability in specialist diagnostic reagent supply creates bottlenecks for laboratory service expansion. Distribution runs through supermarket retail chains in Germany and the United States, with online direct-to-consumer platforms capturing rural and underserved urban demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized allergist density shortages and precision assay manufacturing expertise gaps constrain market expansion more than capital availability. Stakeholders must prioritize capability acquisition over geographic expansion.
For Market Incumbents: Harden diagnostic laboratory network density in Bavaria and North Rhine-Westphalia to preempt emerging European competitors. Secure backward integration into pea protein isolate production through offtake agreements with Canadian processors, insulating against EU agricultural policy volatility. Certification investment in ISO 22000 facility standards defends shelf placement against private-label encroachment in U.S. pediatric categories. For New Entrants and Emerging Players: Pursue direct-to-consumer IgE testing kits as the most penetrable white-space opportunity, bypassing specialist allergist bottlenecks in the United Kingdom and rural United States. Target third-party certification services as a fragmented, high-margin adjacency with minimal incumbent concentration. A subscription-based go-to-market model captures recurring parental expenditure patterns more effectively than transactional retail placement. For Investors and Strategic Acquirers: EMA pediatric investigation plan requirements reshape the acquisition landscape toward desensitization therapy developers with active clinical pipelines. Long-term viability favors platforms combining diagnostic confirmation with therapeutic monitoring rather than single-modality avoidance products. Acquisition target archetypes include precision assay developers with component-resolved diagnostic capabilities. The signal to watch is threshold dose research standardization that would redefine precautionary labeling liability exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Oral immunotherapy protocol validation through FDA and EMA pediatric investigation plans accelerates therapeutic revenue diversification. |
| Regulatory Approval Pathway | CE marking for component-resolved diagnostic platforms unlocks quantitative allergen disclosure compliance across German retail chains. |
| Backward Integration | In-house pea protein isolate production secures supply continuity for alternative protein formulations under EU Green Deal incentives. |
| Long-term Supply Agreement | Batch-level certificate of analysis contracts with U.S. supermarket buyers lock in premium shelf positioning for certified product lines. |
| Strategic Partnership | Hospital system partnerships in Greater Boston and San Francisco anchor reference laboratory volume for precision IgE testing. |
Methodological Framework
The analysis maps diagnostic laboratory services, egg-free product manufacturing, alternative protein ingredient supply, and oral immunotherapy development, each validated through regulatory affairs specialists at multinational food manufacturers, clinical allergists at academic medical centers, retail category buyers, and precision assay R&D directors. Primary interviews with these stakeholders combined with secondary validation against FDA enforcement actions, EMA pediatric investigation plan filings, EU Regulation (EU) No 1169/2011 implementation guidance, and ISO 22000 facility audit records. Bottom-up patient population modeling and top-down retail scanner data triangulation anchored volume estimates.
Fixed assumptions included sustained FDA labeling mandate enforcement intensity, continued EU quantitative disclosure requirements, and stable pea protein isolate production capacity expansion under agricultural policy support. Variable assumptions encompassed oral immunotherapy protocol adoption rates, specialist allergist workforce growth, and threshold dose research standardization timing. Segmentation dimensions modeled comprised product type, procurement authority, distribution channel, and technical application difficulty. CAGRs were derived from patient prevalence trends cross-referenced with pricing elasticity estimates across the projection horizon. Forecast inputs included pediatric population concentration patterns and third-party certification penetration rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, agricultural commodity prices, or trade tariff regimes would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity changes or diagnostic technology disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Global Gluten-Free Ready Meals Market
Food Intolerance Products
United States Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Food Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Pasta Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Europe Gluten-Free Oats Market
Food Intolerance Products
Japan Lactose-Free Dairy Market
Food Intolerance Products
Allergen Free Food Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
United Kingdom Gluten Free Foods and Beverages Market
Food Intolerance Products
Gluten Free Products Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Europe Gluten Free Foods and Beverages Market
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
North America Free from Food Market